
 Atorvastatin API Market | 2026-2036
Atorvastatin API Market Size, Share, and Industry Trends Forecast 2026-2036
Atorvastatin API Market Analysis
Buyer concentration among generic pharmaceutical manufacturers is broadening as multinational formulators diversify API procurement beyond traditional European suppliers. Teva Pharmaceutical Industries leverages vertical integration into upstream synthesis to secure captive atorvastatin supply for its own tablet operations. Zhejiang Hisun Pharmaceutical anchors large-scale fermentation capacity in China, while Dr. Reddy's Laboratories competes through cost-optimized process chemistry and ANDA filing density in the United States.
Atorvastatin API is the active pharmaceutical ingredient of the synthetic statin atorvastatin calcium, typically manufactured through a multi-step organic synthesis involving a pyrrole ring formation and a chiral side-chain attachment, with purity specifications exceeding 99.5% and stringent control of diastereomeric impurities per pharmacopeial monographs. The ingredient serves primarily as the therapeutic basis for cholesterol-lowering formulations prescribed in cardiovascular risk management. Tablet formulations dominate volume consumption across the therapy area segmentation, reflecting patient adherence preferences and established reimbursement pathways, while the dyslipidemia indication captures the deepest margin pool due to chronic dosing requirements and sustained prescription renewal rates. Direct sales channels to large generic houses sustain the highest throughput, though online pharmacies represent the fastest-growing distribution vector as telehealth prescribing normalizes post-pandemic.
US FDA, EMA, and India's CDSCO collectively enforce ICH Q7 good manufacturing practice standards that dictate facility inspection frequency, impurity profiling depth, and documentation rigor for atorvastatin API export eligibility. These regulatory frameworks elevate capital requirements for new market entrants while privileging incumbent manufacturers with established regulatory filing histories and dedicated quality units. Stakeholders must monitor evolving nitrosamine impurity testing mandates and bioequivalence study design changes that could alter the competitive economics of generic atorvastatin sourcing decisions.
Market Dynamics
Regulatory scrutiny of overseas API facilities is compressing supplier qualification timelines while simultaneously extending audit backlogs, forcing formulators to pre-qualify multiple fermentation and synthesis sources before single-source dependencies crystallize.
Growth Catalysts
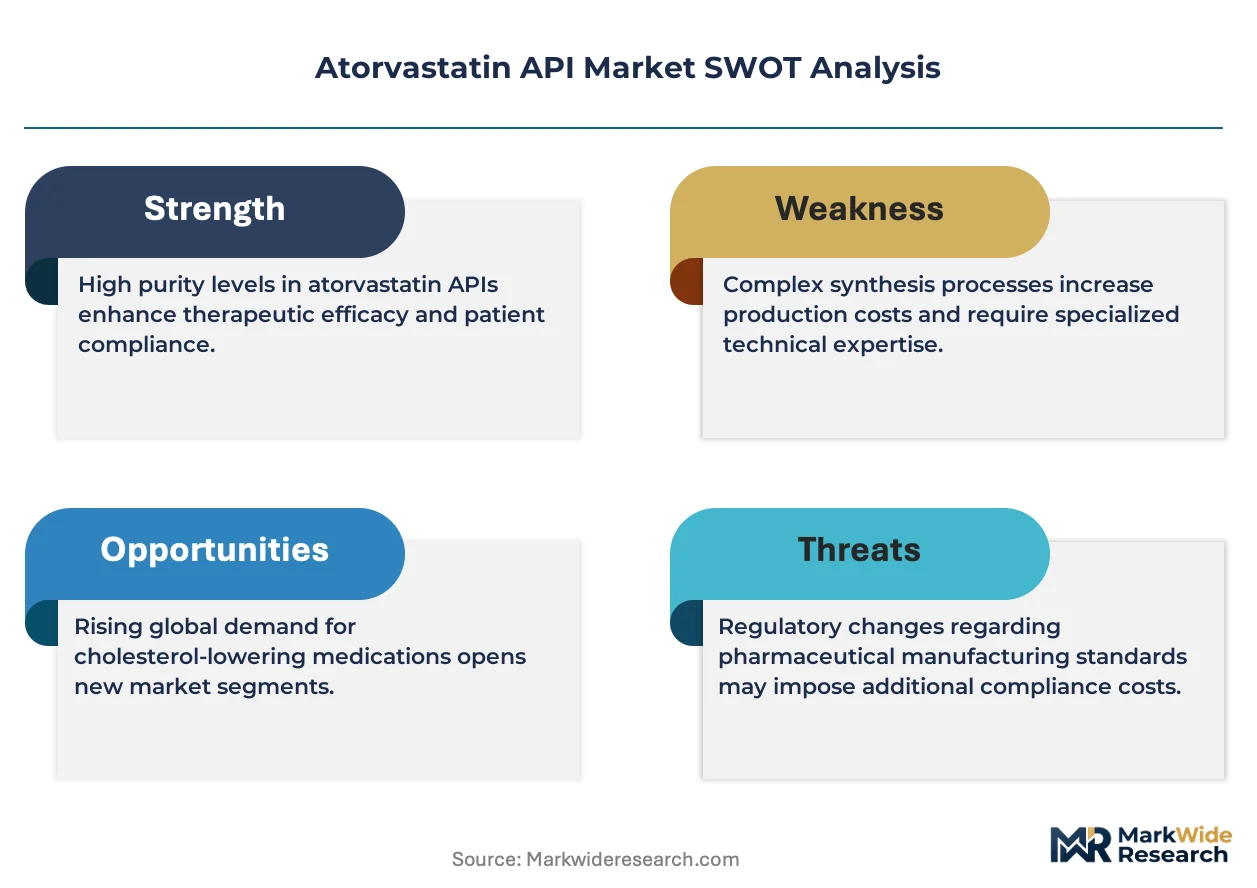
- India's PLI scheme for bulk drugs:The production-linked incentive program subsidizes capital expenditure for fermentation-based statin intermediates, attracting greenfield investments into Andhra Pradesh and Gujarat bulk drug parks.
- Cardiovascular combination therapies:Fixed-dose combinations pairing atorvastatin with amlodipine or ezetimibe are expanding prescription volumes across hypertension and dyslipidemia patient cohorts.
- ICH Q7 harmonization:Unified good manufacturing practice standards across US FDA, EMA, and CDSCO inspection protocols are reducing duplicative compliance costs for multi-destination exporters.
Market Restraints
- Acetonitrile and borane reagent cost volatility:Key inputs for chiral side-chain construction face petrochemical feedstock price swings that compress batch economics for non-integrated manufacturers.
- Supplier concentration in Zhejiang and Hyderabad:Fermentation capacity clusters within two state-level jurisdictions expose procurement continuity to localized environmental enforcement actions or power grid instability.
- Nitrosamine impurity testing mandates:Evolving FDA and EMA guidance on N-nitrosodimethylamine limits requires additional validation studies and extended stability protocols for ANDA submissions.
Strategic Opportunities
- Sub-Saharan Africa cardiovascular programs:WHO prequalification pathways for essential medicines list statins are opening tender opportunities for cost-optimized API supply into Kenya, Nigeria, and Ethiopia.
- Continuous flow chemistry adoption:Microreactor platforms for pyrrole ring cyclization are reducing solvent volumes and enabling distributed manufacturing footprints closer to formulation sites.
- Telehealth prescribing normalization:Post-pandemic virtual consultation platforms are expanding statin initiation rates among diagnosed-but-untreated dyslipidemia populations in Brazil and Mexico.
Industry Challenges
- Analytical method transfer complexity:Migrating diastereomeric impurity assays from HPLC to UPLC platforms across contract manufacturing organizations demands revalidation timelines that delay tech transfer completion.
- Cold-chain API logistics for biologics co-location:Multi-product facilities handling both synthetic statins and temperature-sensitive biologics face segregation and cross-contamination control investments that strain capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atorvastatin API Market |
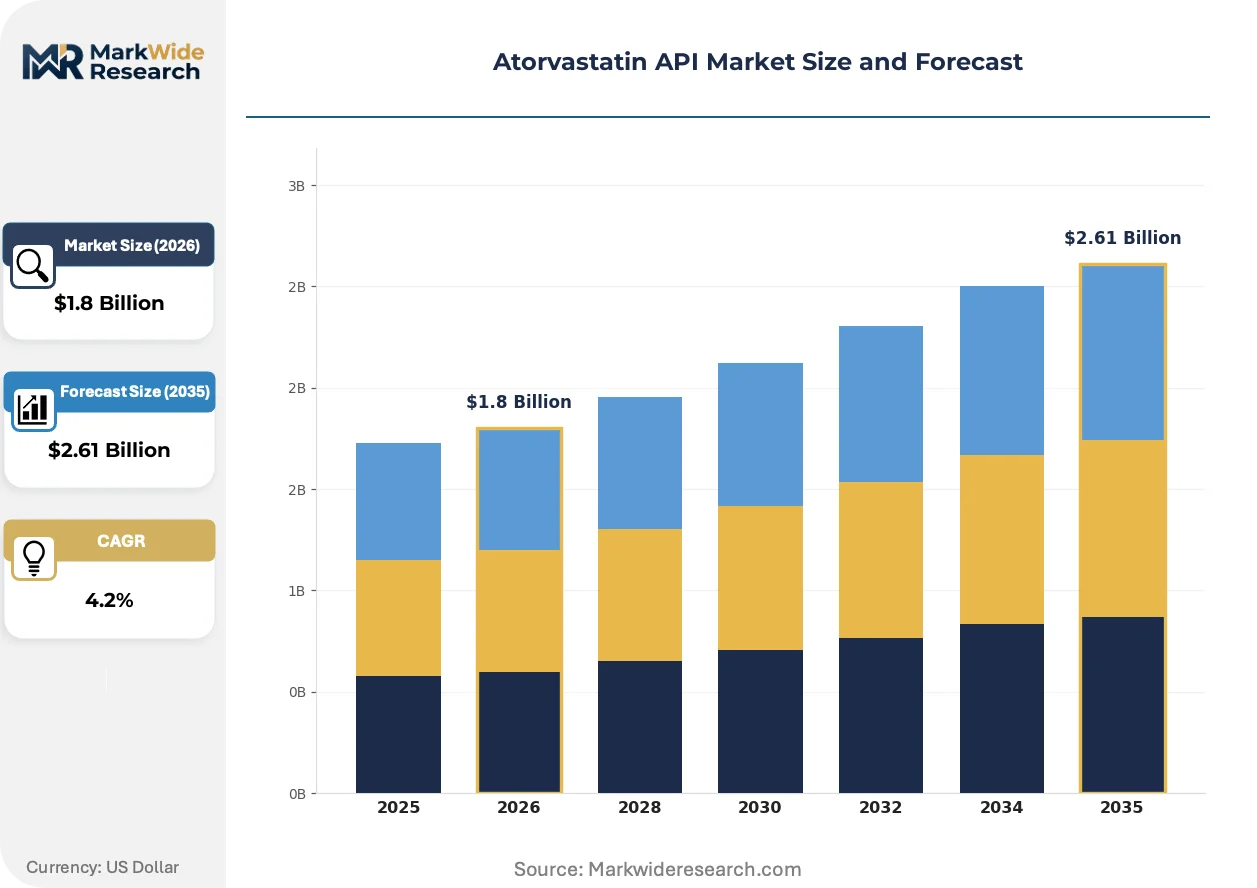
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Oral Solution, Other Forms End User: Hospitals, Clinics, Pharmacies, Research Institutions Therapy Area: Cardiovascular, Dyslipidemia, Hypertension, Metabolic Disorders Distribution Channel: Direct Sales, Wholesalers, Retail Pharmacies, Online Pharmacies |
| Companies Covered | Centrient Pharmaceuticals, Zhejiang Hisun Pharmaceutical Co Ltd, Teva Pharmaceutical Industries Ltd, Anuh Pharma Ltd, Cadila Pharmaceuticals, Sun Pharmaceutical Industries Ltd, Morepen Laboratories Ltd, Jubilant Life Sciences Ltd, Dr. Reddy’s Laboratories Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atorvastatin API Market Emerging Trajectories
Process intensification and regulatory data harmonization are converging to reshape how atorvastatin API is synthesized, tested, and distributed across fragmented national markets.
Continuous manufacturing platforms employing flow chemistry for the Paal-Knorr pyrrole synthesis are displacing traditional batch reactors in pilot-scale deployments. Mid-tier generic houses in India are adopting these skid-mounted systems to reduce solvent recovery burdens. The technology is modularizing capital deployment, allowing manufacturers to scale throughput through parallel reactor trains rather than single-train capacity expansion.
EMA's revised nitrosamine risk assessment guidelines now mandate comprehensive survey testing for all chemically synthesized APIs with secondary or tertiary amine structures. This regulatory tightening is extending analytical development timelines by four to six months for new supplier qualifications. European formulators are responding by consolidating procurement onto established vendors with validated impurity control strategies rather than qualifying emerging low-cost sources.
Hospital and health system procurement consortia are consolidating annual API volume commitments into multi-year framework agreements with pre-negotiated price corridors. These arrangements displace spot-market purchasing for standardized monograph-grade material. The shift is most visible in United States group purchasing organizations serving integrated delivery networks, where formulary standardization around specific generic suppliers reduces pharmacy inventory complexity.
Atorvastatin API Market Segmentation
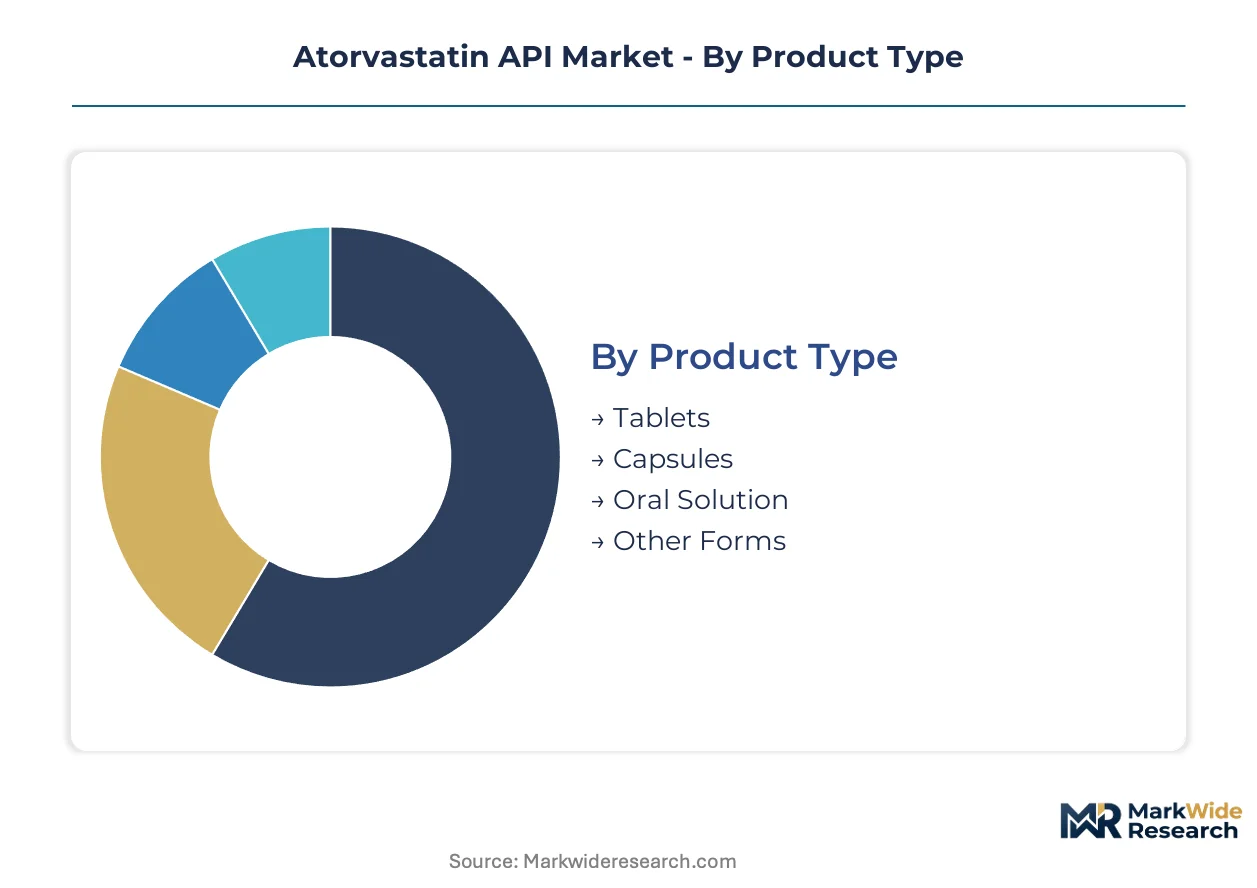
Atorvastatin API demand fragments across formulation types, clinical settings, and procurement channels that each impose distinct purity specifications, volume cadences, and regulatory documentation burdens. Understanding these segment boundaries reveals where margin pools concentrate and where supplier qualification investments yield the highest returns.
Product Type:
Supply concentration in tablet-grade material dominates fermentation and synthesis capacity allocation, with manufacturers prioritizing monograph-compliant output for high-volume solid dosage forms over niche liquid presentations.
- Tablets:Film-coated and immediate-release tablet grades constitute the bulk of API volume, with specifications demanding tight particle size distribution for direct compression and dissolution profiles meeting USP <711> requirements. Indian generic houses in Hyderabad and Ahmedabad consume the deepest share of tablet-grade output, driven by chronic dosing regimens for dyslipidemia management and the economics of 90-day prescription fills.
- Capsules:Hard gelatin and HPMC capsule formulations require micronized API with enhanced flow properties for encapsulation efficiency, serving patients with dysphagia or those requiring dose titration flexibility. Demand concentrates among specialty pharmacies in the United States and Germany, where individualized statin dosing protocols support cardiovascular risk stratification programs.
- Oral Solution:Pediatric and geriatric liquid formulations utilize solubilized atorvastatin calcium with stability-enhancing excipients, addressing swallowing difficulties in nursing home populations.
- Other Forms:Orally disintegrating tablets and fixed-dose combination granules serve specific adherence-enhancement programs and co-formulation with ezetimibe or amlodipine.
Today's leader: Tablets. Tomorrow's challenger: Capsules.
End User:
Hospital procurement consortia are consolidating annual API volume commitments into multi-year framework agreements, displacing fragmented clinic-level purchasing with pre-negotiated price corridors and single-source qualification.
- Hospitals:Integrated delivery networks and public hospital systems in Brazil, Mexico, and Thailand drive tender-based procurement of high-purity API for formulary standardization, with WHO prequalification status increasingly gating supplier eligibility. These institutions prioritize batch documentation and stability data packages that support centralized pharmacy compounding operations.
- Clinics:Outpatient cardiovascular and lipidology clinics in the United States and United Kingdom initiate statin therapy through sample-to-prescription pathways, creating demand for smaller API lot sizes with rapid analytical turnaround.
- Pharmacies:Community and chain pharmacies in India's tier-2 cities represent the steepest expansion trajectory for generic atorvastatin dispensing, supported by Jan Aushadhi program subsidies and pharmacist-led cardiovascular screening initiatives.
- Research Institutions:Academic medical centers and contract research organizations source GMP-grade API for bioequivalence studies and polymorph characterization, requiring comprehensive impurity profiles and certificate of analysis documentation.
Hospital procurement is consolidating fastest. Pharmacy volume is climbing the fastest.
Therapy Area:
Margin capture varies sharply across cardiovascular indications, with chronic dyslipidemia management sustaining the deepest renewal economics versus acute coronary syndrome protocols with shorter treatment horizons.
- Cardiovascular:Broad-spectrum prevention of myocardial infarction and stroke drives the largest absolute prescription volumes, with API specifications emphasizing endotoxin control for parenteral-adjacent manufacturing environments. Demand anchors in Medicare-aged populations across the United States and Japan's National Health Insurance system.
- Dyslipidemia:Primary hypercholesterolemia and mixed dyslipidemia indications command premium API pricing due to lifelong therapy requirements and the clinical emphasis on LDL-C target attainment. German and Dutch healthcare systems prioritize high-potency atorvastatin formulations for familial hypercholesterolemia registries.
- Hypertension:Fixed-dose combination therapies pairing atorvastatin with ACE inhibitors or calcium channel blockers are gaining share in Latin American markets where polypill strategies address medication adherence gaps.
- Metabolic Disorders:Diabetic dyslipidemia and non-alcoholic fatty liver disease protocols utilize atorvastatin as adjunct therapy, with endocrinology clinics in Saudi Arabia and the UAE driving specialized procurement for metabolic syndrome patient cohorts.
Dyslipidemia commands the deepest margins. Metabolic Disorders represent the fastest-growing trajectory.
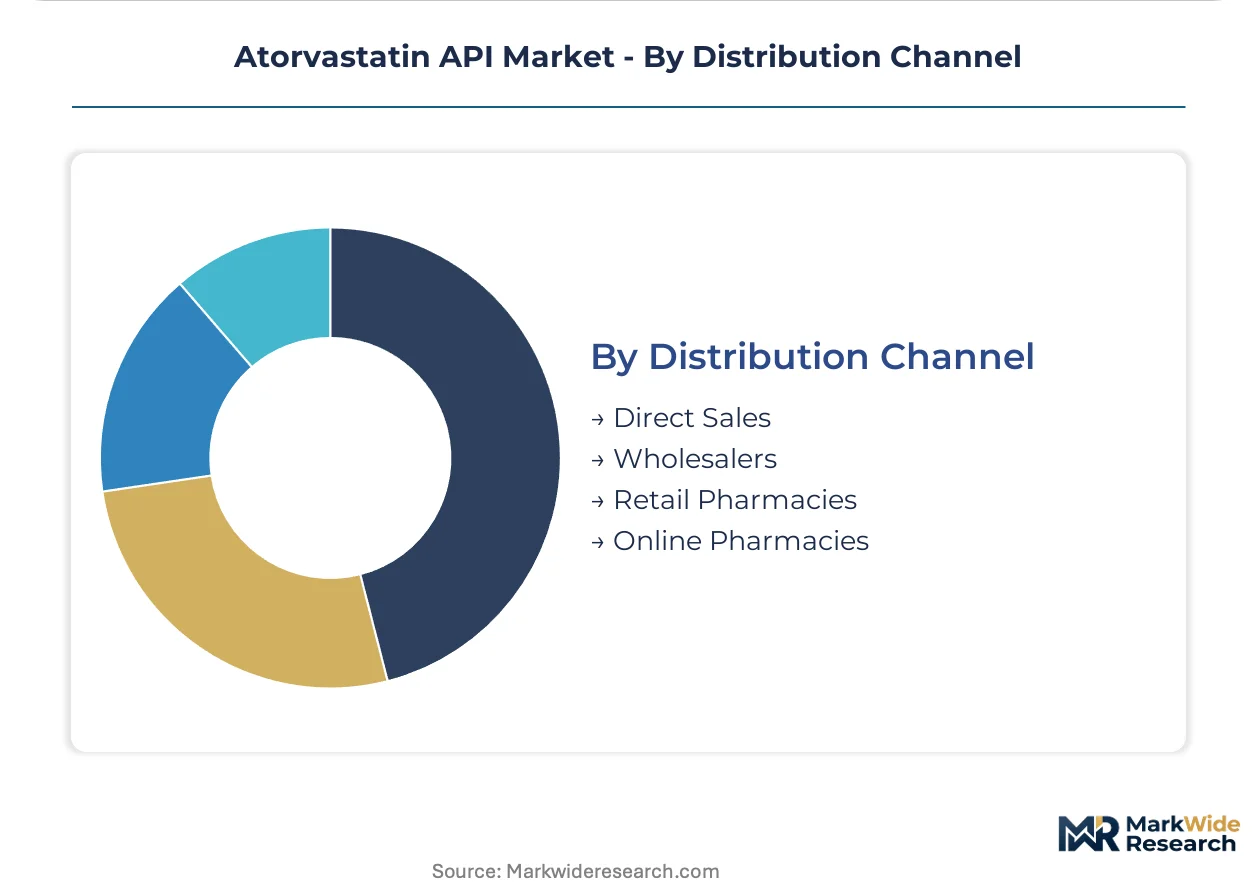
Distribution Channel:
Channel selection determines documentation burdens, with direct sales to large generic houses minimizing transactional overhead while online pharmacy growth is forcing API suppliers to adapt to serialized track-and-trace requirements.
- Direct Sales:Long-term supply agreements between API manufacturers and vertically integrated generic houses in India and China sustain the highest throughput volumes, with Teva Pharmaceutical Industries and Dr. Reddy's Laboratories qualifying captive and dual-source fermentation capacity. These arrangements emphasize annual volume commitments with price renegotiation clauses tied to acetonitrile feedstock indices.
- Wholesalers:Regional pharmaceutical distributors in Europe and Southeast Asia aggregate API demand from mid-tier formulators, requiring lot-specific CoA packages and temperature-controlled storage validation.
- Retail Pharmacies:Independent and chain pharmacy procurement of finished dosage forms ultimately traces back to API supply through abbreviated new drug application holders, with CVS Health and Walgreens Boots Alliance influencing supplier selection through formulary exclusion policies.
- Online Pharmacies:Telehealth-integrated dispensing platforms in Brazil, Mexico, and Nigeria are expanding statin access among diagnosed-but-untreated populations, creating demand for API packaged in smaller batch sizes with multilingual labeling support.
Direct Sales anchors current volume. Online Pharmacies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China command contrasting positions in atorvastatin API supply, with India consolidating fermentation capacity through government incentives while China dominates intermediate chemical synthesis. Germany and the United States anchor formulation demand through vertically integrated generic houses. Brazil represents the fastest-expanding consumption frontier as telehealth platforms normalize statin prescribing.
India
Domestic generic manufacturers in Hyderabad and Ahmedabad drive API consumption through 90-day prescription fills and chronic dyslipidemia protocols. CDSCO enforces ICH Q7 alignment with US FDA inspection protocols for export eligibility. Andhra Pradesh's bulk drug parks under the PLI scheme are attracting greenfield fermentation investments from mid-tier suppliers.
China
Zhejiang province anchors intermediate synthesis capacity for chiral side-chain construction and pyrrole ring formation. NMPA harmonizes GMP standards with ICH Q7 to streamline multi-destination exports. Taizhou and Shaoxing chemical parks face environmental enforcement actions that periodically constrain batch output for non-integrated manufacturers.
United States
Medicare-aged populations sustain prescription volumes through integrated delivery networks and group purchasing organization consolidation. FDA nitrosamine testing mandates are extending ANDA submission timelines and privileging established suppliers with validated impurity profiles. New Jersey and North Carolina host formulation sites that source API through long-term supply agreements with pre-negotiated price corridors.
Germany
Familial hypercholesterolemia registries prioritize high-potency atorvastatin formulations for LDL-C target attainment. EMA revised nitrosamine risk assessment guidelines now mandate comprehensive survey testing for all secondary amine APIs. Frankfurt and Hamburg distribution hubs aggregate demand from mid-tier European formulators requiring lot-specific CoA packages.
Brazil
Telehealth-integrated dispensing platforms expand statin access among diagnosed-but-untreated dyslipidemia populations in São Paulo and Rio de Janeiro. ANVISA streamlines WHO prequalification pathways for essential medicines list inclusion. Southeast regional procurement consortia are consolidating annual volume commitments into multi-year framework agreements.
Atorvastatin API Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across upstream synthesis and downstream formulation. Market structure tilts toward consolidated supply with four to six fermentation-scale manufacturers capturing the majority of tablet-grade volume. Strategic archetypes span vertically integrated generic houses, standalone API specialists, and diversified life sciences conglomerates. Dominant competitive moves include backward integration into captive intermediate supply and geographic diversification of dual-source qualification to mitigate regulatory audit backlogs.
Within the vertically integrated tier, Teva Pharmaceutical Industries and Dr. Reddy's Laboratories exemplify manufacturers controlling upstream synthesis for captive tablet operations. Zhejiang Hisun Pharmaceutical Co Ltd anchors the standalone fermentation specialist archetype with large-scale capacity in China's Zhejiang province. Among diversified conglomerates, Sun Pharmaceutical Industries Ltd and Jubilant Life Sciences Ltd occupy positions spanning multiple therapeutic APIs beyond statin intermediates.
| Leading Market Players |
|---|
| Centrient Pharmaceuticals |
| Zhejiang Hisun Pharmaceutical Co Ltd |
| Teva Pharmaceutical Industries Ltd |
| Anuh Pharma Ltd |
| Cadila Pharmaceuticals |
| Sun Pharmaceutical Industries Ltd |
| Morepen Laboratories Ltd |
| Jubilant Life Sciences Ltd |
| Dr. Reddy's Laboratories Ltd |
| Others |
Supply Flow & Price Mechanics
Captive fermentation capacity in Andhra Pradesh and Gujarat anchors supply positions for Indian generic houses while simultaneously insulating them from acetonitrile feedstock volatility that erodes margins for non-integrated competitors. This backward integration into upstream pyrrole ring synthesis creates pricing power through batch cost control and regulatory filing continuity.
Pricing Analysis
Capacity additions in Zhejiang and Hyderabad are reshaping price floors for tablet-grade material as fermentation scale economies compress per-kilogram costs. Three-tier pricing structure across US FDA-inspected, EMA-certified, and domestic-only grades separates premium API with validated nitrosamine profiles from standard monograph-compliant output. Cost compression in the economy tier is intensifying because environmental enforcement actions in Taizhou periodically constrain batch output from non-integrated manufacturers. Hospital procurement consortia exhibit the lowest price sensitivity due to formulary standardization requirements, while mid-tier generic houses in Southeast Asia face acute margin pressure from acetonitrile and borane reagent cost swings.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang province for chiral side-chain intermediates and with Hyderabad for fermentation-scale statin output. India, China, and the United States concentrate finished API supply, with intermediate synthesis drawing from petrochemical feedstocks in Zhejiang and Shaoxing chemical parks. Supply chain risk centers on localized environmental enforcement actions that constrain batch output without warning. Distribution runs through direct sales agreements to vertically integrated generic houses, with wholesaler aggregation serving mid-tier European and Southeast Asian formulators requiring temperature-controlled logistics validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atorvastatin API has entered a late-cycle quality phase where EMA nitrosamine mandates and FDA inspection intensity favor incumbents with validated impurity control strategies over cost-optimized challengers. Prescription volumes are tilting toward high-potency formulations for familial hypercholesterolemia registries that demand premium-grade material with comprehensive stability data packages.
For Market Incumbents: Deploy continuous flow chemistry platforms for pyrrole ring cyclization to reduce solvent recovery burdens and enable distributed manufacturing footprints closer to formulation sites. Consolidate procurement relationships through multi-year framework agreements with pre-negotiated price corridors tied to acetonitrile indices, insulating against emerging Chinese fermentation capacity that threatens spot-market pricing. CDSCO alignment with US FDA inspection protocols privileges established regulatory filing histories.
For New Entrants and Emerging Players: Launch via WHO prequalification pathways for essential medicines list statins targeting Sub-Saharan Africa cardiovascular programs in Kenya, Nigeria, and Ethiopia. Telehealth-integrated dispensing platforms in Brazil and Mexico represent the most penetrable demand frontier, with pharmacist-led cardiovascular screening initiatives creating prescription pull-through for cost-optimized API supply. Focus initial capacity on micronized capsule grades for specialty pharmacy distribution where dysphagia patient populations support dose titration flexibility.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier fermentation specialists with captive intermediate supply because regulatory audit backlogs are extending supplier qualification timelines and privileging incumbents with established quality units. Over the projection horizon, acquisition targets should demonstrate validated nitrosamine control strategies and dedicated CDSCO-FDA dual-filing capabilities. The signal to watch is EMA guidance evolution on secondary amine API testing mandates that could accelerate consolidation onto established vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Microreactor platforms reduce solvent volumes and enable distributed manufacturing closer to formulation sites. |
| Backward Integration into Intermediate Synthesis | Captive pyrrole ring construction insulates batch economics from acetonitrile feedstock price volatility. |
| WHO Prequalification Pathway Investment | Essential medicines list status opens tender opportunities for Sub-Saharan Africa cardiovascular programs. |
| Multi-Year Framework Agreement Structuring | Pre-negotiated price corridors with hospital procurement consortia displace spot-market purchasing volume. |
| Nitrosamine Control Strategy Validation | Comprehensive survey testing capabilities meet EMA revised guidelines for secondary amine APIs. |
Methodological Framework
Bottom-up tablet formulation modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at Indian and Chinese API manufacturers, formulary directors at United States group purchasing organizations, and hospital procurement managers in Brazil and Germany were cross-validated against secondary sources including FDA ANDA filings, EMA inspection databases, and CDSCO export registration records. Triangulation across supply-side capacity announcements and demand-side prescription data ensures segmentation integrity.
Input-output matrices map pyrrole ring synthesis throughput to finished API volume across tablet, capsule, and oral solution grades, with CAGRs derived from regression analysis of historical prescription trends and capacity utilization rates. Segmentation dimensions include formulation type, end-user institution class, therapy area indication, and distribution channel structure, with regional regulatory cluster effects modeled separately for US FDA, EMA, and CDSCO jurisdiction overlaps. Forecast inputs incorporate PLI scheme subsidy trajectories and telehealth prescribing normalization curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nitrosamine testing mandate acceleration or environmental enforcement actions in Zhejiang chemical parks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Global Autogenous Vaccines Market