
 Esters Market | 2026-2036
Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Esters Market Analysis
Polyol esters are repositioning mineral oil-based lubricants in automotive and industrial formulations. BASF SE leverages integrated acrylic acid-to-ester pathways to sustain margin control across European supply chains. Evonik Industries AG anchors its position through high-purity specialty esters for pharmaceutical and cosmetic APIs. Lanxess AG competes on backward integration into adipic acid, securing captive feedstock for nylon-intermediate esters.
Esters are organic compounds formed from the condensation reaction between an acid and an alcohol, characterized by the general formula RCOOR' and typically produced via Fischer esterification or transesterification processes; they serve as critical intermediates for solvents, plasticizers, lubricants, and fragrance carriers across industrial and consumer applications. Acetic esters dominate volume flows through paints and coatings applications where fast evaporation rates and solvent power prove essential. Ethyl esters are gaining share in food additive and flavoring applications as clean-label formulations displace synthetic alternatives. Propionic esters occupy a narrower but higher-margin niche in pharmaceutical excipient grades where USP certification commands price premiums.
EPA regulations on volatile organic compound emissions from coatings and adhesives are redirecting formulation chemistry toward low-VOC ester solvents. ECHA's REACH framework enforces registration and hazard communication standards that filter non-compliant imports from Asian suppliers. FDA food additive regulations under 21 CFR govern permissible ester concentrations in flavoring and direct food contact materials. Stakeholders must monitor evolving bio-based feedstock certifications as sustainability claims become a gating factor for procurement decisions by multinational formulators.
Market Dynamics
REACH compliance in Europe is tightening purity thresholds for cosmetic-grade esters, forcing reformulation investments across the personal care value chain while specialty chemical clusters in Germany consolidate high-value production capacity.
Growth Catalysts
- Personal care sector demand:Natural-derived emollients are expanding formulation opportunities as clean-label cosmetics displace petroleum-based alternatives in skincare and haircare products.
- REACH framework enforcement:ECHA registration requirements are filtering non-compliant imports from Asian suppliers, creating protected market space for certified European producers.
- Polyol ester technology:Advanced synthetic pathways are repositioning mineral oil-based lubricants in automotive and industrial formulations through superior thermal stability and biodegradability.
Market Restraints
- Feedstock volatility:Crude oil-linked acrylic acid and adipic acid prices expose margin compression risks for non-integrated ester manufacturers without captive feedstock supply.
- Asian supply concentration:Bulk acetic ester production concentrates in China, creating import dependency and tariff exposure for European coatings formulators.
- Propionic ester technical barriers:USP certification for pharmaceutical excipient grades requires multi-year stability testing that blocks rapid market entry.
Strategic Opportunities
- Bio-based feedstock certifications:Sustainability claims are becoming procurement gating factors for multinational formulators seeking ISO-compliant renewable carbon sourcing.
- Food additive applications:Ethyl esters in flavoring formulations are gaining share as clean-label displacements accelerate in North American and European packaged foods.
- Low-VOC solvent transition:EPA regulations on volatile organic compound emissions from coatings are redirecting formulation chemistry toward compliant ester solvents.
Industry Challenges
- Specialized synthesis expertise:Fischer esterification and transesterification process optimization requires scarce chemical engineering talent familiar with high-purity pharmaceutical-grade production.
- Multi-jurisdictional compliance:Simultaneous navigation of FDA 21 CFR food additive rules, EPA VOC standards, and ECHA REACH dossiers extends product launch timelines by 18-24 months.
- Legacy equipment retrofit costs:Stainless steel reactor upgrades for corrosive acid handling demand capital deployment that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esters Market |
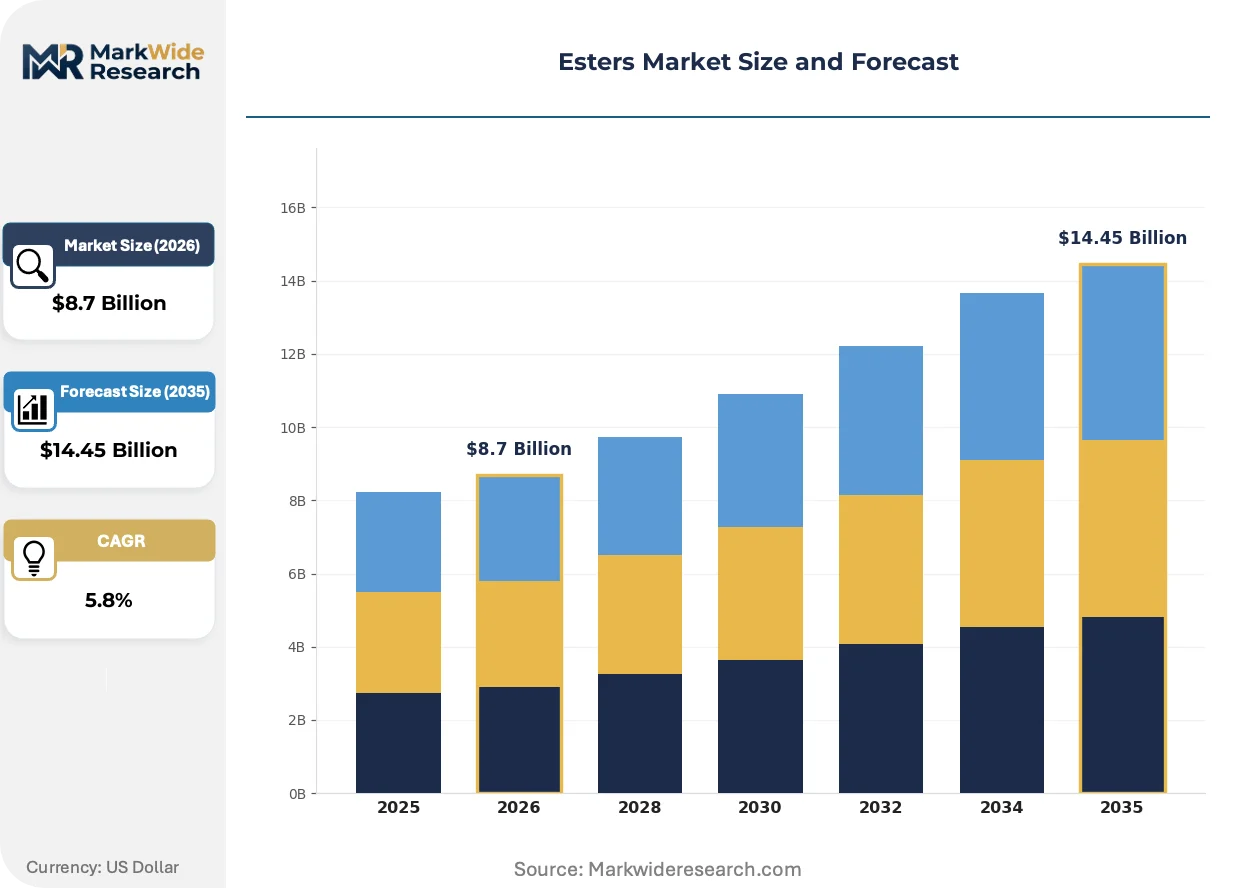
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Esters, Butyric Esters, Propionic Esters, Ethyl Esters Application: Food Additives, Cosmetics, Paints, Adhesives End User: Food Industry, Personal Care, Automotive, Pharmaceutical Distribution Channel: Direct Sales, E-commerce, Distributors, Retail Outlets |
| Companies Covered | Lanxess AG, Evonik Industries AG, BASF SE, Croda International Plc, Arkema SA, Exxon Mobil Corporation, Mitsubishi Chemical Corporation, Huntsman International LLC, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esters Market Emerging Trajectories
Process intensification and digital control systems are compressing batch cycle times while regulatory data automation is reducing compliance overhead across multi-jurisdictional markets.
Continuous flow reactor technology is automating temperature and pressure control in Fischer esterification processes. Specialty chemical manufacturers in Germany are adopting these systems to reduce solvent waste and improve yield consistency. The technology is automating quality assurance steps that previously required manual sampling and laboratory analysis.
ECHA's REACH framework is expanding substance evaluation lists to include previously grandfathered ester intermediates used in fragrance and solvent applications. Industrial consequence includes mandatory toxicological dossier updates for existing registrations. Cosmetic-grade ester suppliers in France and Germany are responding by consolidating purity testing capabilities in-house to accelerate compliance documentation.
Direct procurement relationships between ester producers and end-use formulators are displacing traditional distributor intermediaries in high-volume coatings and lubricant segments. Large automotive OEMs and personal care multinationals are negotiating multi-year supply agreements with certified producers. This pattern is most visible in the German specialty chemical corridor where backward-integrated suppliers offer integrated technical service alongside volume commitments.
Esters Market Segmentation
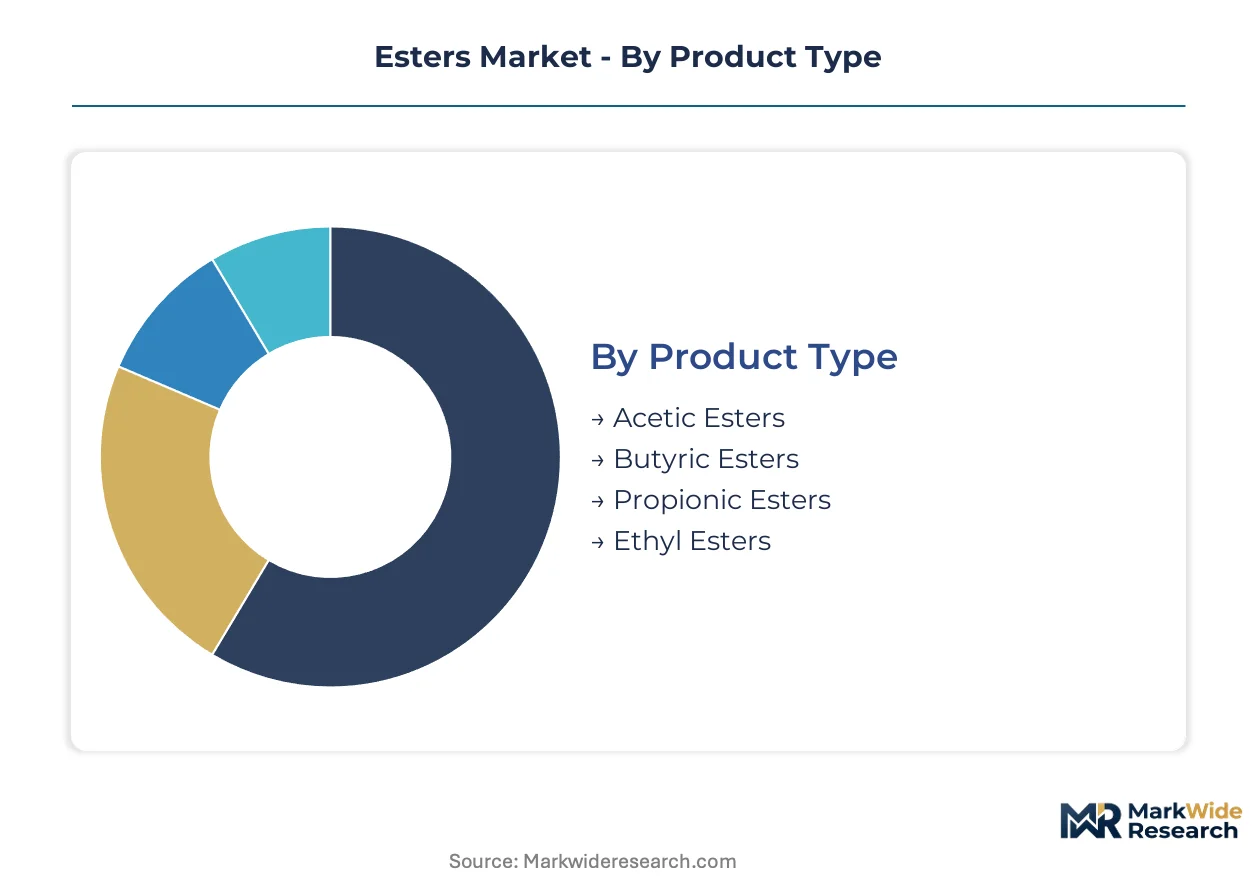
Segmentation in the esters market reveals how formulation chemistry, regulatory thresholds, and procurement patterns fragment demand across distinct value tiers. Buyers select ester types based on evaporation profiles, purity certifications, and feedstock origin claims that determine qualification for specific end-use applications.
Product Type:
Cost tier differentiation separates commodity solvents from specialty pharmaceutical grades, with purity specifications and certification overhead driving price spreads.
- Acetic Esters:Fast-evaporating solvents derived from acetic acid condensation, prized in coatings for their solvency power and flash point control. Demand concentrates in German automotive OEM paint shops where VOC compliance deadlines are compressing formulation windows. REACH registration costs and purity testing overhead protect established European producers from Asian commodity imports.
- Propionic Esters:Higher-molecular-weight esters with slower evaporation rates and enhanced stability profiles, qualifying for pharmaceutical excipient grades under USP certification. French and German API manufacturers specify these grades for controlled-release drug formulations where impurity thresholds are measured in parts per million. Multi-year stability testing requirements create technical barriers that sustain margin premiums.
- Butyric Esters:Fruit-flavored compounds serving food and fragrance applications with characteristic apple and pineapple notes.
- Ethyl Esters:Clean-label flavor carriers displacing synthetic additives in North American packaged foods.
Acetic esters lead on scale; propionic esters lead on momentum.
Application:
Application selection hinges on regulatory jurisdiction, with FDA food additive rules, EPA VOC limits, and ECHA REACH dossiers creating distinct compliance pathways.
- Cosmetics:Natural-derived emollients and emulsifiers where clean-label positioning commands formulation priority. German personal care multinationals are consolidating supplier qualifications around bio-based feedstock certifications and ISO-compliant carbon accounting. REACH purity thresholds are tightening faster than formulation cycles can adapt, favoring backward-integrated producers with in-house testing capabilities.
- Paints:Solvent systems where low-VOC ester alternatives are displacing mineral spirits under EPA enforcement pressure. Automotive refinish shops in the US and industrial maintenance coatings in Germany represent concentrated demand nodes. Evaporation rate tuning for specific humidity and temperature conditions requires technical service partnerships that direct procurement favors.
- Food Additives:Flavor carriers and texture modifiers governed by 21 CFR concentration limits and GRAS self-determination pathways.
- Adhesives:Tackifiers and plasticizers in pressure-sensitive tapes and construction bonding agents.
Cosmetics commands margin premiums; paints captures volume concentration.
End User:
Customer type determines procurement rhythm, with pharmaceutical and automotive sectors favoring multi-year supply agreements over spot purchasing.
- Personal Care:Skincare and haircare formulators sourcing emollients with renewable carbon claims and RSPO-certified palm derivatives. German specialty chemical clusters anchor supply relationships through integrated technical service and joint formulation development. Direct procurement patterns are displacing distributor intermediaries for high-volume accounts.
- Pharmaceutical:API manufacturers and excipient suppliers requiring USP, EP, and JP pharmacopeia compliance with documented supply chain transparency. Batch-level certificates of analysis and audit rights are standard contractual terms. French and German producers dominate this segment through decades of regulatory dossier accumulation.
- Food Industry:Flavor houses and packaged food manufacturers seeking clean-label positioning.
- Automotive:Lubricant blenders and paint formulators specifying thermal stability and corrosion resistance.
Personal care leads on contract value; pharmaceutical leads on qualification intensity.
Distribution Channel:
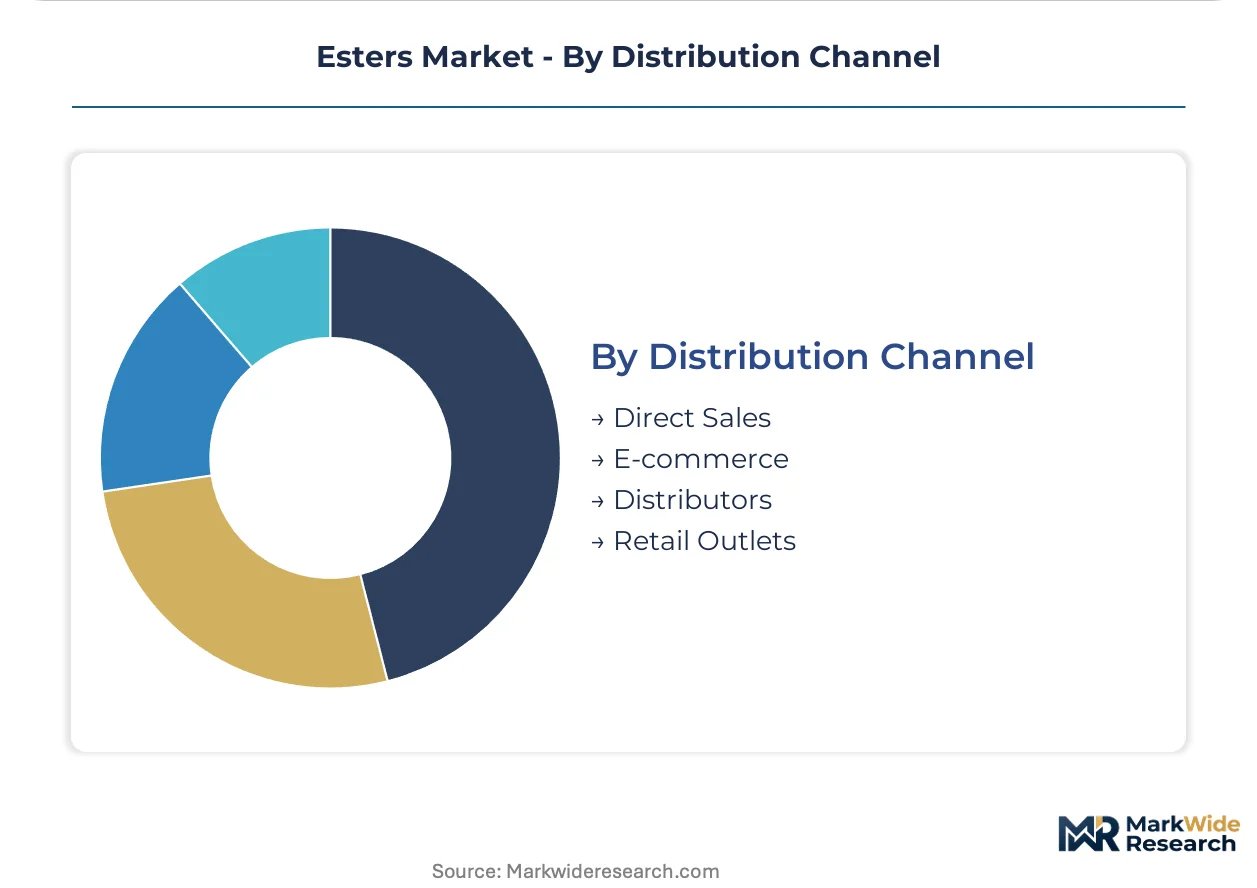
Channel selection reflects order scale and technical service requirements, with large accounts bypassing intermediaries.
- Direct Sales:Multi-year supply agreements between ester producers and automotive OEMs, personal care multinationals, and pharmaceutical API manufacturers. Technical service integration including formulation support and regulatory documentation is bundled with volume commitments. German specialty chemical corridor producers leverage this channel most intensively.
- Distributors:Regional stockholding intermediaries serving mid-scale coatings formulators and adhesive compounders with shorter lead time requirements.
- E-commerce:Sample ordering and small-batch procurement for R&D laboratories and startup formulators.
- Retail Outlets:Limited presence for consumer-facing specialty ester products in niche applications.
Direct sales leads on revenue concentration; e-commerce leads on expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German specialty chemical corridor anchors the highest-value ester production capacity in Europe, with backward-integrated producers leveraging captive adipic acid and acrylic acid feedstocks to sustain margin control across automotive lubricant and cosmetic emollient supply chains.
United States
Automotive OEM paint shops and personal care multinationals drive demand for low-VOC acetic ester solvents and natural-derived emollients. EPA regulations on volatile organic compound emissions from coatings compress formulation windows toward compliant ester alternatives. The Gulf Coast petrochemical complex sustains integrated acrylic acid-to-ester pathways for domestic coatings formulators.
Germany
Pharmaceutical API manufacturers and cosmetic formulators concentrate demand for USP-certified propionic esters and REACH-compliant cosmetic grades. ECHA's REACH framework tightens purity thresholds for fragrance and solvent intermediates previously grandfathered under earlier registration protocols. The Cologne-Leverkusen chemical cluster consolidates high-value specialty ester production through in-house toxicological dossier capabilities.
France
Flavor houses and fragrance compounders source ethyl esters and butyric esters for clean-label food additive and luxury perfume applications. ANSM enforces pharmaceutical-grade purity standards that parallel USP certification requirements for excipient suppliers. The Lyon chemical basin anchors production of high-stability ester intermediates for controlled-release drug formulations.
China
Bulk acetic ester production for coatings and adhesives concentrates in coastal petrochemical zones, creating export dependency for European formulators. The country's national chemical regulator enforces GB standards on solvent purity that increasingly align with REACH technical guidance. The Yangtze River Delta hosts integrated acid-to-ester facilities serving domestic automotive and construction coatings demand.
India
Personal care contract manufacturers and generic pharmaceutical producers expand procurement of cosmetic-grade and excipient-grade esters. CDSCO's tightening import inspection protocols for pharmaceutical raw materials filter non-compliant Asian suppliers. The Mumbai-Pune industrial corridor attracts specialty ester distributors serving mid-scale skincare and haircare formulators with technical service partnerships.
Esters Market Vendor Landscape
Backward integration into captive feedstock supply dominates the current landscape, with producers securing in-house adipic acid and acrylic acid production to buffer margin compression from crude oil-linked raw material volatility. The vendor base stratifies across three tiers: multinational diversified chemical conglomerates with integrated petrochemical assets, mid-cap specialty ester houses focused on pharmaceutical and cosmetic certifications, and regional bulk solvent distributors serving spot-market coatings demand. Two strategic archetypes define competitive positioning—REACH-registered European specialists leveraging regulatory compliance as a moat, and scale-driven Asian producers competing on acetic ester volume. Capacity expansion in bio-based feedstock pathways and M&A consolidation of regional distributors represent the dominant competitive moves.
Among German-based integrated producers, BASF SE, Evonik Industries AG, and Lanxess AG exemplify the backward-integrated archetype, each anchoring distinct feedstock positions that shape their respective ester portfolio economics. BASF SE represents the diversified conglomerate model with acrylic acid integration, Evonik Industries AG occupies the high-purity specialty tier, and Lanxess AG anchors adipic acid-captive supply for nylon-intermediate esters. These three producers collectively illustrate how feedstock control, regulatory dossier depth, and pharmaceutical-grade certification capabilities stratify competitive position in European specialty ester markets.
| Leading Market Players |
|---|
| Lanxess AG |
| Evonik Industries AG |
| BASF SE |
| Croda International Plc |
| Arkema SA |
| Exxon Mobil Corporation |
| Mitsubishi Chemical Corporation |
| Huntsman International LLC |
| Cargill Incorporated |
| Others |
Supply Flow & Price Mechanics
Continuous flow reactor technology is compressing batch cycle times in Fischer esterification processes while simultaneously redrawing cost curves and supplier concentration maps across European specialty chemical corridors. German producers deploying these automated systems capture yield efficiencies that commodity-scale Asian acetic ester manufacturers cannot replicate, creating tiered margin structures that reward technical sophistication over volume scale.
Pricing Analysis
Acrylic acid and adipic acid feedstock volatility passes through directly to ester pricing, with non-integrated manufacturers absorbing margin compression that backward-integrated German producers avoid. Pricing stratifies across USP-certified pharmaceutical grades, REACH-registered cosmetic tiers, and bulk solvent commodities, with certification overhead and purity testing driving spreads. Pricing pressure stems from crude oil-linked raw material swings and Asian import competition in coatings solvents. Commodity acetic ester buyers in industrial coatings exhibit highest price sensitivity; pharmaceutical API manufacturers accept premium pricing for documented supply chain transparency.
Supply Chain Analysis
REACH registration and USP certification requirements gate supply participation, filtering non-compliant Asian suppliers from European pharmaceutical and cosmetic value chains. Production concentrates in Germany, China, and the United States, with German specialty clusters anchoring high-purity grades and Chinese coastal zones dominating bulk acetic ester output. Supply chains draw from crude oil-derived acrylic acid, bio-based fatty alcohols, and adipic acid from cyclohexane oxidation. Tariff exposure on Chinese acetic ester imports creates structural risk for European coatings formulators. Distribution runs through direct technical-service partnerships for large accounts, with regional distributors serving mid-scale spot buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in specialty grades where certification barriers protect pricing power, with bio-based feedstock transitions offering cost-down pathways through renewable carbon sourcing incentives.
For Market Incumbents: Acquire captive adipic acid or acrylic acid production assets to buffer feedstock volatility and sustain margin control against Asian commodity competition. Consolidate in-house toxicological dossier capabilities to accelerate REACH compliance documentation and defend market position against emerging bio-based entrants. Expand technical service partnerships with automotive OEMs and personal care multinationals to lock in multi-year direct procurement agreements. For New Entrants and Emerging Players: Contract manufacturers serving mid-scale personal care formulators represent the most accessible channel entry point for certified specialty ester suppliers. Target clean-label food additive applications in North America where ethyl ester displacement of synthetic flavor carriers accelerates procurement switching. Pursue bio-based feedstock certification as a differentiation wedge against incumbent petroleum-based supply. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialty ester houses lacking backward integration but holding pharmaceutical-grade certification assets. Long-term viability favors producers with documented supply chain transparency and multi-jurisdictional regulatory dossiers. Watch bio-based feedstock cost parity against petroleum-derived inputs as the inflection signal for portfolio rebalancing toward renewable carbon pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstock | BASF SE and Lanxess AG anchor margin control through in-house acrylic acid and adipic acid production. |
| REACH Compliance Certification Investment | Evonik Industries AG consolidates high-purity specialty ester supply through toxicological dossier depth. |
| Bio-Based Feedstock Transition | Cargill Incorporated leverages renewable carbon sourcing to meet ISO-compliant procurement gating by multinational formulators. |
| Direct Technical Service Partnerships | German specialty chemical corridor producers displace distributor intermediaries through integrated formulation support. |
| Continuous Flow Reactor Deployment | Specialty manufacturers automate Fischer esterification quality assurance to reduce solvent waste and improve yield consistency. |
Methodological Framework
Bottom-up personal care and pharmaceutical demand modeling reconciled against top-down acrylic acid and adipic acid supply tracking forms the analytical core of this study. Primary interviews with plant managers at German specialty chemical clusters, procurement leads at automotive OEM paint shops, regulatory affairs directors at cosmetic multinationals, and distribution channel partners in coatings supply chains combined with secondary validation from ECHA registration databases, FDA 21 CFR filings, Cefic industry reports, and customs trade data. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapping feedstock conversion yields to end-use application demand drove the forecast framework across the projection horizon. Segmentation dimensions modeled include ester product type, purity certification tier, end-use industry, and regional production hub. CAGRs derived from regression analysis of historical capacity utilization and forward-looking demand elasticity by application. Forecast inputs incorporated REACH enforcement timelines, EPA VOC regulatory phase-ins, and bio-based feedstock cost trajectory assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude oil price volatility, bio-based feedstock scale-up rates, and REACH substance evaluation list expansions. Deviation in Chinese acetic ester export policy or European tariff posture would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Aminoethylethanolamine Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Squalane Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
Global Specialty Oleochemicals Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Fatty Acid Amides Market