
 Allyl Caproate Market | 2026-2036
Allyl Caproate Market Size, Share, and Industry Trends Forecast 2026-2036
Allyl Caproate Market Outlook
Food-grade specification upgrades are redrawing procurement standards across the Allyl Caproate value chain. Givaudan leverages backward integration into raw material sourcing to secure consistent ester supply for its flavor compounding operations. Symrise AG anchors its position through specialized manufacturing scale in high-purity allyl caproate for European fragrance houses. Robertet Group differentiates via technology leadership in natural-identical ester production methods.
Allyl caproate is an unsaturated aliphatic ester synthesized through esterification of caproic acid with allyl alcohol, typically achieving purity grades between 98% and 99.5% depending on intended application. The compound imparts a pineapple-like odor profile and functions primarily as a flavoring agent and fragrance ingredient across food, beverage, and personal care formulations. The Flavors segment leads in volume terms as food manufacturers standardize on ester-based tropical profiles for beverage and confectionery applications. Fragrances represents the fastest-growing application area as niche perfumers adopt allyl caproate for its diffusion characteristics in fine fragrance compositions. Industrial Chemicals occupies a mature position with stable demand from agrochemical intermediate producers seeking cost-effective ester building blocks.
REACH registration requirements under ECHA govern substance identity and purity thresholds for allyl caproate circulating within the European Economic Area. FDA food additive regulations under 21 CFR establish safety parameters for flavor use in the United States, while FSSAI standards in India set maximum permissible limits for ester-based flavorants in processed foods. Stakeholders must monitor evolving purity specifications across these regulatory frameworks to align product grades with jurisdiction-specific compliance thresholds.
Market Dynamics
REACH compliance under ECHA is tightening purity specifications for flavor and fragrance intermediates, forcing formulators to upgrade procurement standards and consolidate supplier relationships around certified ester producers.
Growth Catalysts
- Fine fragrance diffusion demand:Niche perfumers are expanding allyl caproate use for its volatility characteristics in high-end compositions. This pulls volume from specialty chemical distributors into direct fragrance house procurement.
- Captive esterification buildout:Domestic flavor houses in China are constructing in-house production capacity to secure supply chain control. This reduces import dependency and compresses lead times for tropical profile formulations.
- FSSAI standardization:India's food safety regulator is formalizing maximum permissible limits for ester-based flavorants. Compliance-driven procurement is displacing ungraded material in processed food manufacturing.
Market Restraints
- Caproic acid feedstock volatility:Palm kernel and coconut oil price swings transmit directly to allyl caproate production economics. Formulators face margin compression during oleochemical supply disruptions.
- Specialized reactor concentration:High-purity allyl caproate synthesis requires corrosion-resistant esterification equipment concentrated among German and Swiss chemical engineering firms. Equipment scarcity extends project timelines.
- Natural-identical substitution pressure:Fermentation-derived pineapple flavor molecules are capturing share in premium beverage applications. Ester producers must defend position on cost-performance metrics.
Strategic Opportunities
- Indian flavorant formalization:FSSAI's evolving standards create first-mover advantage for REACH-registered suppliers. Early compliance investments position entrants ahead of domestic capacity buildout.
- Biocatalytic esterification convergence:Lipase enzyme immobilization with continuous flow reactor design is opening lower-temperature synthesis pathways. This technology pairing reduces energy intensity and byproduct formation.
- Direct-to-compounder distribution:Digital procurement platforms are disintermediating traditional chemical distributors. Fragrance houses in France and flavor formulators in the United States are piloting blockchain-verified batch tracking.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry expertise for trace impurity quantification is concentrated among retiring specialists. Recruitment gaps delay batch release timelines.
- Dual certification complexity:Simultaneous REACH registration and FDA food additive petitioning requires parallel toxicological dossier preparation. Documentation burden extends market entry timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allyl Caproate Market |
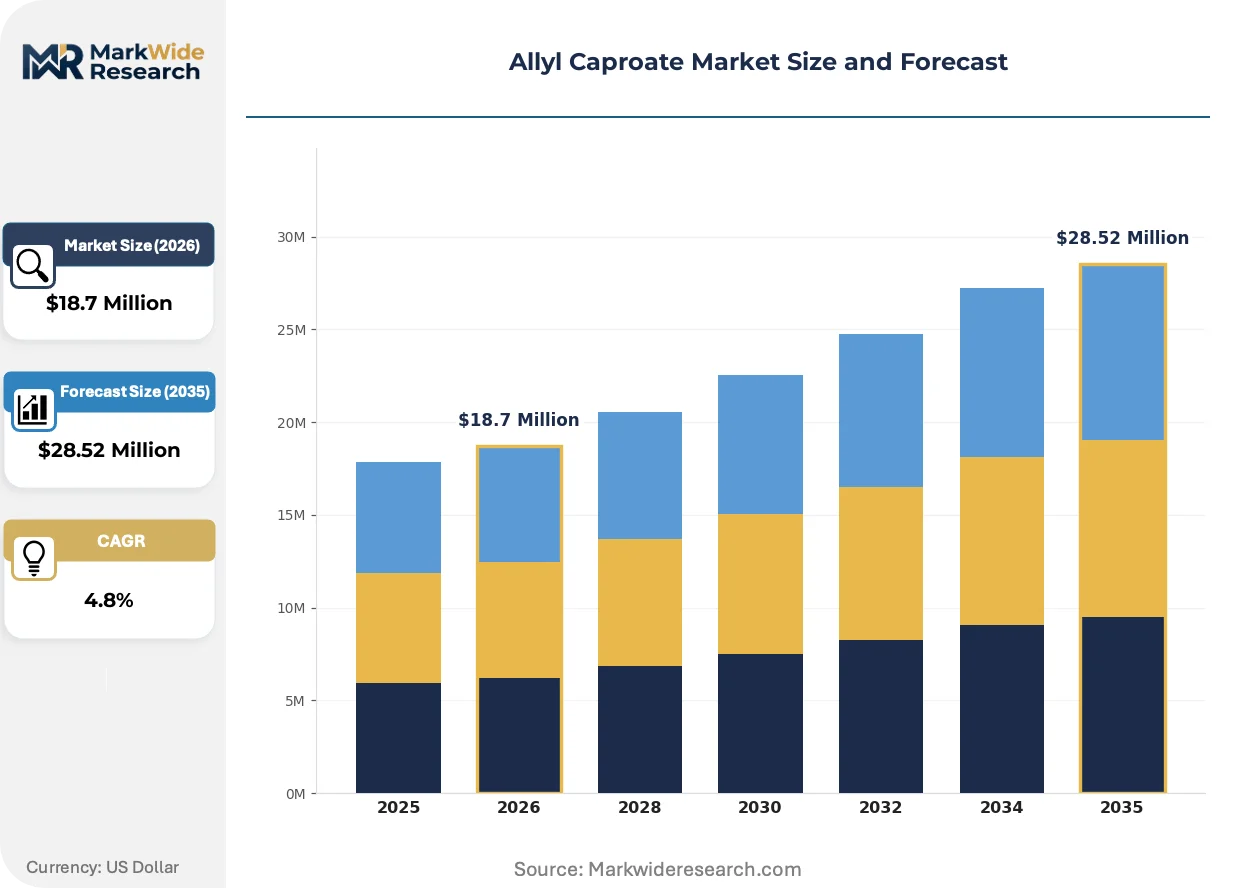
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.52 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavors, Fragrances, Industrial Chemicals, Food Additives Application: Food & Beverage, Personal Care, Pharmaceuticals, Agrochemicals End User: Food Manufacturers, Cosmetic Producers, Pharmaceutical Companies, Agricultural Sector Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Vigon International, Inc., Penta Manufacturing Company, Merck KGaA, Givaudan, Ernesto Ventós, S.A., Berjé Inc., Symrise AG, Robertet Group, Treatt Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allyl Caproate Market Strategic Shifts
Process intensification and regulatory digitization are compressing batch cycle times while expanding traceability requirements across the allyl caproate value chain.
Continuous flow reactor technology is miniaturizing traditional batch esterification infrastructure. Mid-sized fragrance compounders in Germany and the Netherlands are adopting skid-mounted systems that halve solvent usage and enable real-time purity monitoring. This equipment shift is compressing capital requirements for high-purity production entry.
REACH registration dossiers under ECHA now mandate full substance identity profiling including impurity specifications down to 0.1% w/w. European fragrance houses are demanding enhanced analytical certificates that exceed baseline compliance. Suppliers without in-house GC-MS capability are losing preferred vendor status.
Flavor houses are consolidating purchase orders around fewer ester suppliers with multi-jurisdiction certification. Procurement teams in beverage and confectionery verticals now require simultaneous FDA, FSSAI, and EFSA documentation. This behavior concentrates volume with integrated producers and marginalizes regional specialists lacking regulatory breadth.
Allyl Caproate Market Segmentation
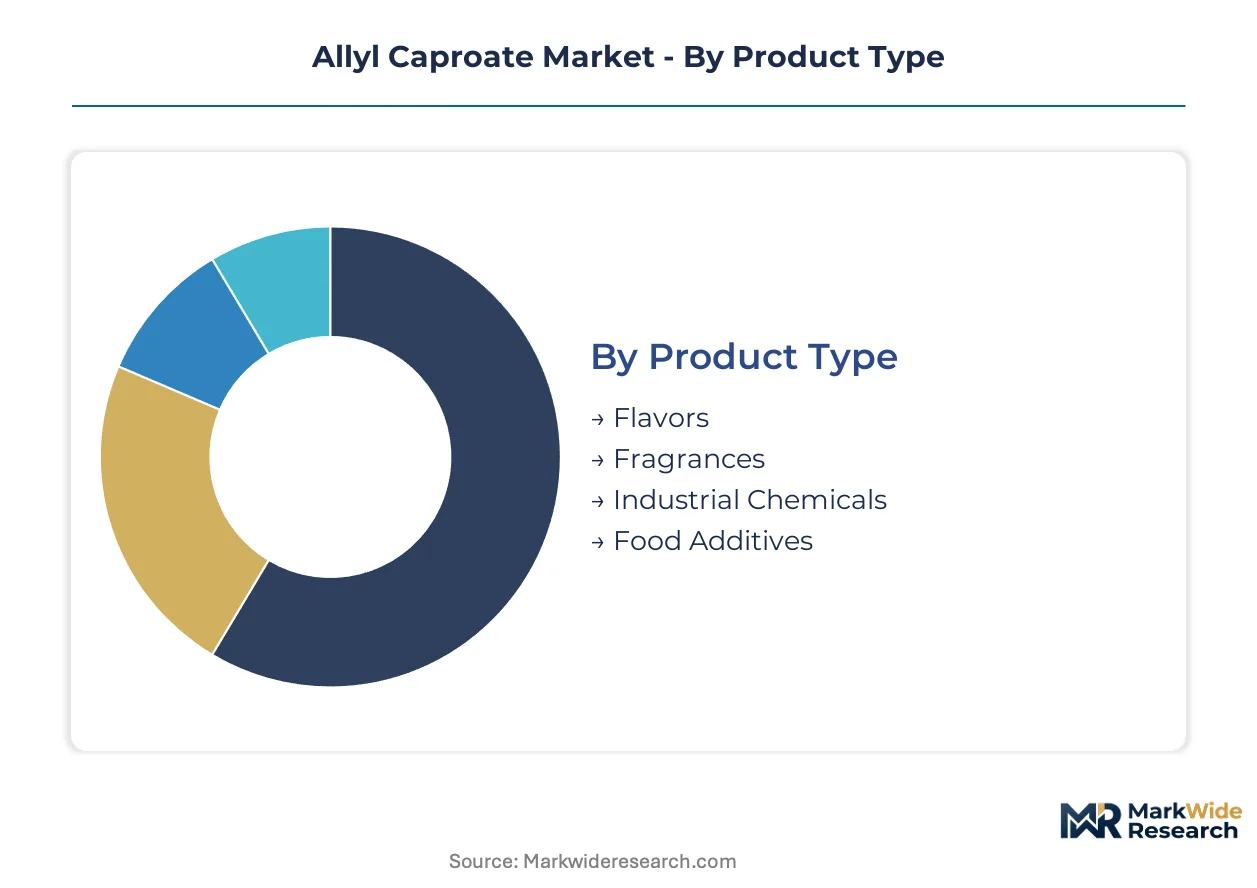
Segmentation in the allyl caproate market reflects divergent purity specifications and regulatory pathways across end-use verticals. Each category channels procurement behavior toward specialized suppliers with jurisdiction-specific certification portfolios.
Product Type:
REACH registration thresholds under ECHA and FDA food additive petitions create divergent compliance burdens across product grades, fragmenting supplier qualification requirements.
- Flavors:Food-grade allyl caproate achieves 99.0-99.5% purity with stringent residual acid limits. Beverage manufacturers in the United States and confectionery formulators in India concentrate procurement around FSSAI-registered and FDA-compliant producers.
- Fragrances:Fine perfumery applications demand 98.5-99.0% purity with optimized volatility characteristics. European fragrance houses in France and Germany direct volume toward REACH-registered specialists with enhanced analytical documentation.
- Industrial Chemicals:Technical-grade material serves agrochemical intermediate synthesis with lower purity tolerances.
- Food Additives:Direct food contact applications require additional toxicological dossier preparation beyond standard flavor-grade specifications.
Established volume favors Flavors; emerging adoption favors Fragrances.
Application:
Cost tier differentiation separates commodity ester consumption from specialty-grade procurement with multi-certification requirements.
- Food & Beverage:Tropical profile standardization in carbonated drinks and confectionery drives bulk ester consumption. Major beverage compounders in the United States negotiate annual contracts with specified purity bands.
- Personal Care:Fine fragrance diffusion properties command premium pricing in niche perfumery. French and Italian cosmetic houses source directly from specialized ester producers.
- Pharmaceuticals:Excipient-grade allyl caproate requires GMP-compliant manufacturing with enhanced impurity profiling.
- Agrochemicals:Cost-sensitive intermediate applications tolerate technical-grade specifications with minimal regulatory documentation.
Food & Beverage dominates procurement scale; Personal Care commands the steepest expansion trajectory.
End User:
Customer type determines contract structure, with multinational formulators demanding multi-jurisdiction certification and regional players accepting single-market compliance.
- Food Manufacturers:Global beverage and confectionery conglomerates consolidate purchase orders around integrated producers with simultaneous FDA, FSSAI, and EFSA documentation. Procurement teams specify batch-level traceability through blockchain verification.
- Cosmetic Producers:Fragrance compounders in France and personal care formulators in Germany require REACH-registered supply with enhanced GC-MS certificates. Direct supplier relationships displace distributor intermediation.
- Pharmaceutical Companies:GMP-compliant ester sourcing for excipient applications demands audit-ready manufacturing facilities with validated analytical methods.
- Agricultural Sector:Agrochemical intermediate producers prioritize cost performance over certification breadth, sourcing technical-grade material through regional distributors.
Food Manufacturers anchor procurement volume; Cosmetic Producers are gaining share fastest.
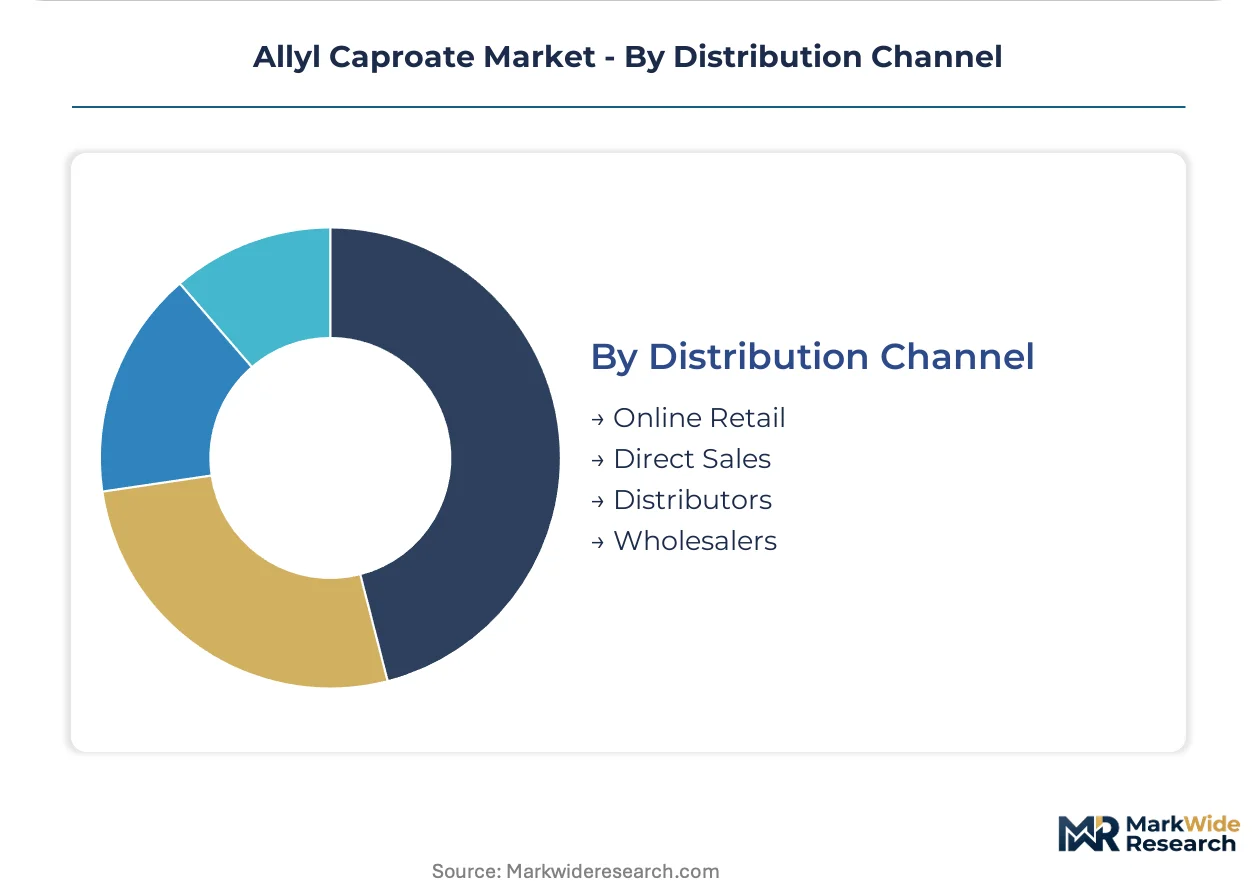
Distribution Channel:
Supply concentration among German and Swiss chemical engineering firms shapes channel selection for high-purity grades versus commodity procurement.
- Direct Sales:Fragrance houses and flavor compounders with volume scale negotiate direct contracts with ester producers. Blockchain-verified batch tracking pilots in France and the United States compress lead times and documentation exchange.
- Distributors:Mid-sized formulators without procurement scale rely on specialty chemical distributors for regulatory documentation and technical support. REACH-registered distributors in Germany and the Netherlands consolidate regional demand.
- Online Retail:Small-scale researchers and specialty compounders access catalog-grade material through B2B platforms with instant certificate download.
- Wholesalers:Technical-grade industrial applications source through bulk chemical wholesalers with minimal value-added services.
Direct Sales concentrates premium-grade volume; Distributors retain commodity-tier dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. European fragrance houses absorb premium pricing for REACH-registered material, while Asian food manufacturers prioritize cost efficiency in bulk tropical flavor formulations.
China
Domestic flavor houses are constructing captive esterification plants to reduce import dependency. SAMR's evolving food additive standards are tightening purity documentation for tropical profile imports. Guangdong and Zhejiang provinces concentrate new capacity buildout for beverage and confectionery supply chains.
United States
Beverage compounders negotiate annual contracts with specified purity bands for pineapple-flavored carbonated drinks. FDA regulations under 21 CFR govern safety parameters for ester-based flavorants. New Jersey and California host the largest fragrance house procurement operations demanding blockchain-verified batch tracking.
Germany
Fine fragrance diffusion properties command premium pricing from niche perfumers in Cologne and Hamburg. ECHA REACH registration mandates full substance identity profiling with 0.1% w/w impurity thresholds. Bavaria and North Rhine-Westphalia cluster specialized esterification equipment engineering expertise.
India
Confectionery formulators are displacing ungraded material as FSSAI formalizes maximum permissible limits for ester-based flavorants. The food safety regulator's evolving standards create compliance-driven procurement windows. Maharashtra and Gujarat concentrate processed food manufacturing demand.
France
Cosmetic houses source directly from specialized ester producers for fine fragrance compositions. ANSM oversees cosmetic ingredient safety alongside REACH obligations. Grasse and Paris anchor personal care formulation demand with steep requirements for volatility characteristics documentation.
Allyl Caproate Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, producing a tiered market structure. Integrated fragrance houses with backward integration into raw material sourcing secure supply chain control. Specialized ester manufacturers concentrate high-purity production capacity. Regional distributors retain commodity-tier positioning. Dominant competitive moves include captive production buildout and multi-jurisdiction certification investments.
Within the integrated fragrance house tier, Givaudan and Symrise AG exemplify archetypes combining formulation expertise with captive ester supply. Among specialized manufacturers, Robertet Group occupies a position representing technology leadership in natural-identical production methods. Ernesto Ventós, S.A. anchors the regional specialist archetype with concentration in European fragrance distribution.
| Leading Market Players |
|---|
| Vigon International, Inc. |
| Penta Manufacturing Company |
| Merck KGaA |
| Givaudan |
| Ernesto Ventós, S.A. |
| Berjé Inc. |
| Symrise AG |
| Robertet Group |
| Treatt Plc |
| Others |
Value Chain & Pricing Dynamics
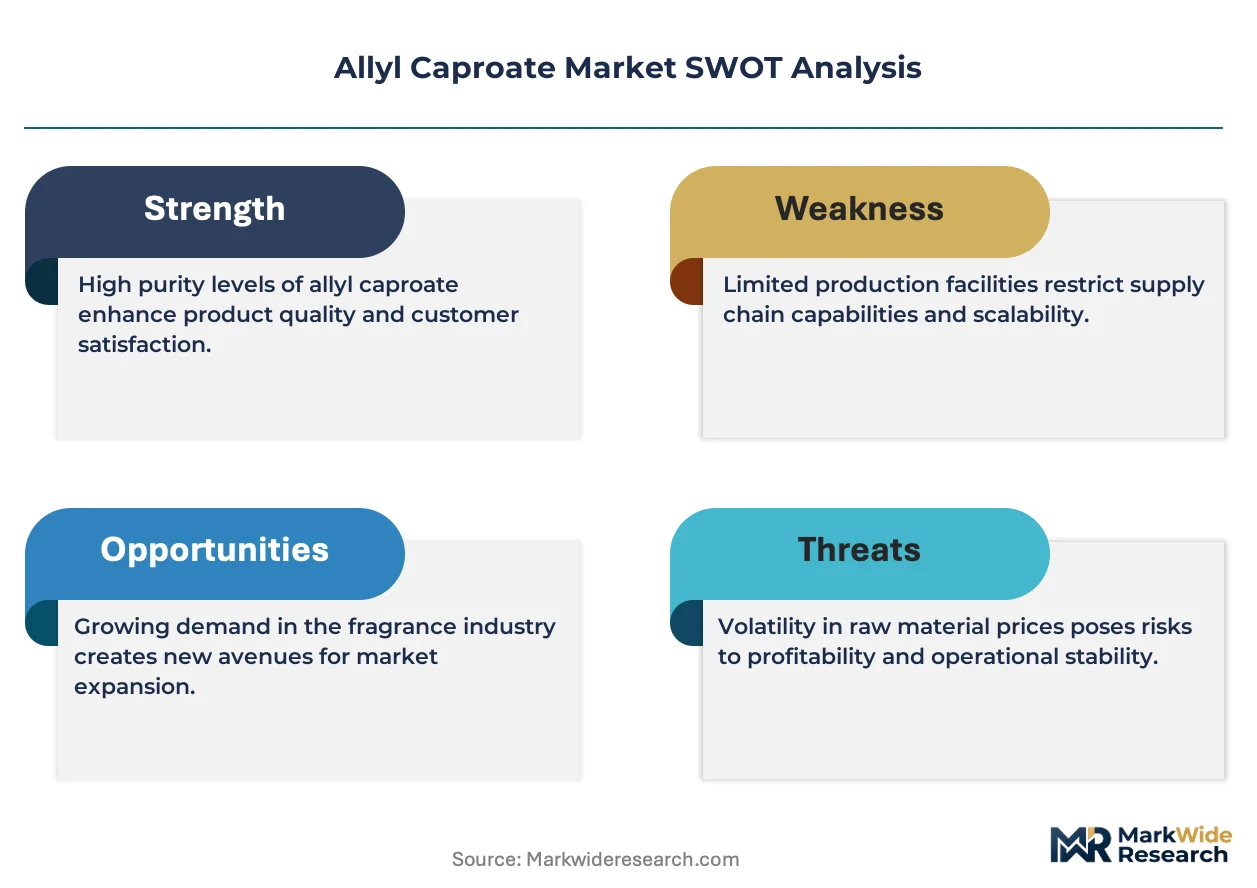
Long-term offtake contracts between German fragrance houses and Swiss specialty ester producers lock in multi-year supply access while fixing price bands indexed to caproic acid feedstock movements. This structure insulates formulators from spot market volatility but embeds cost pass-through clauses that transmit palm kernel oil price swings directly to procurement budgets.
Pricing Analysis
REACH registration dictates the pricing tier structure across the European Economic Area, separating REACH-registered producers commanding premium positioning from unregistered suppliers competing on cost. Three-tier pricing structure across premium, standard, and economy levels reflects certification breadth, with FDA-FSSAI dual-registered material capturing the top tier. Cost compression in standard grades is intensifying because Chinese captive capacity buildout is displacing import volumes. Agrochemical intermediate buyers exhibit highest price sensitivity, while fine fragrance compounders absorb premiums for volatility-optimized grades.
Supply Chain Analysis
Germany and Switzerland anchor high-purity esterification equipment manufacturing, with Bavaria and North Rhine-Westphalia clustering corrosion-resistant reactor engineering expertise. Allyl caproate production draws from caproic acid derived from palm kernel and coconut oil oleochemical streams, with allyl alcohol sourced from petrochemical and bio-based routes. Single-source vulnerability concentrates in specialized reactor procurement, where German and Swiss engineering firms maintain order backlogs extending project timelines. Distribution runs through direct sales channels for premium grades, while commodity-tier material flows via specialty chemical distributors in the Netherlands and regional wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification requirements and purity specifications is creating defendable niches for specialized producers. REACH-FDA-FSSAI triple registration is splintering the supplier base, opening entry points for compliance-focused entrants.
For Market Incumbents: Fortify market position by deepening backward integration into caproic acid sourcing to buffer feedstock volatility, and accelerate multi-jurisdiction certification investments ahead of FSSAI formalization. Fermentation-derived pineapple flavor molecules represent a substitution threat requiring cost-performance defense in beverage applications. For New Entrants and Emerging Players: Lead with biocatalytic esterification technology targeting Indian confectionery formulators displaced by FSSAI compliance deadlines. The most penetrable white space sits in REACH-registered supply for mid-sized European fragrance houses seeking alternatives to integrated producers. A direct-to-compounder digital procurement platform with blockchain-verified batch documentation offers differentiation against traditional distributor intermediation. For Investors and Strategic Acquirers: Capital is best deployed toward specialized ester manufacturers with existing REACH registration and scalable continuous flow reactor technology. Over the projection horizon, integrated fragrance houses will likely consolidate captive supply positions, making independent REACH-registered producers with analytical capabilities attractive acquisition targets. The signal to watch is FSSAI's publication of final maximum permissible limits, which will trigger compliance-driven procurement displacement and volume consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caproic Acid Sourcing | Secures feedstock cost visibility against palm kernel oil volatility for German producers. |
| Multi-Jurisdiction Certification Investment | Positions suppliers ahead of FSSAI formalization in Indian processed food manufacturing. |
| Biocatalytic Esterification Scale-Up | Reduces energy intensity and byproduct formation for lipase-immobilized continuous flow systems. |
| Direct-to-Compounder Digital Platform | Disintermediates Dutch and German specialty chemical distributors through blockchain-verified tracking. |
| Continuous Flow Reactor Adoption | Halves solvent usage for mid-sized fragrance compounders in the Netherlands seeking capital efficiency. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fragrance house procurement directors, flavor compounder technical managers, ester plant operations heads, and specialty chemical distribution channel partners. Secondary validation drew from ECHA REACH registration dossiers, FDA 21 CFR food additive regulations, FSSAI draft standards, SEC filings of listed fragrance houses, and customs trade data for allyl caproate import flows. Bottom-up volume modeling from end-use consumption patterns was triangulated against top-down production capacity assessments across identified manufacturing clusters.
Across the analysis window, forecasts were constructed through segmentation by product grade, application vertical, end-user type, and distribution channel, with regional production hub clustering as an additional dimension. CAGRs were derived from elasticity-adjusted volume projections incorporating purity specification upgrade trajectories and regulatory compliance timeline assumptions. Key inputs included oleochemical feedstock price correlation models and fragrance house captive capacity buildout announcements.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity, FSSAI formalization pace, or fermentation-derived flavor substitution rates would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and feedstock price transmission mechanisms. Recalibration cycles align with material shifts in ECHA guidance publication, FSSAI final rule issuance, and major fragrance house vertical integration announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Global Creosote Oil Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
Petrolatum Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Global Decant Oil Market