
 Healthcare IT Consulting Services Market | 2026-2036
Healthcare IT Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare IT Consulting Services Market Insights
North American health systems is recalibrating procurement priorities after CMS reimbursement rules tied to interoperability metrics took effect. Accenture leverages its federal contracting footprint to anchor large-scale EHR modernization programs for integrated delivery networks. Deloitte competes through specialized regulatory compliance practices that navigate FDA 21st Century Cures Act certification requirements.
Healthcare IT consulting services encompass advisory, implementation, and managed support engagements that align clinical workflows with digital infrastructure, typically delivered through hybrid cloud architectures integrating on-premises legacy systems with SaaS platforms. The primary commercial purpose centers on reducing operational friction in care delivery while ensuring audit-ready documentation for reimbursement and compliance. Implementation Services commands the largest revenue share as hospitals prioritize phased EHR deployments over greenfield builds. Cloud-Based delivery is expanding fastest as Microsoft Azure and AWS health data lakes gain traction among pharmacy chains seeking elastic analytics capacity.
FDA interoperability mandates, HIPAA security rule enforcement, and CMS quality payment program criteria collectively elevate demand for compliance-specialized consulting engagements that bridge technical implementation with legal risk mitigation. The EU AI Act and GDPR health data provisions are extending regulatory complexity for multinational hospital operators with European footprints. Stakeholders must monitor how ONC information blocking penalties reshape vendor selection criteria and consulting scope definitions.
Market Dynamics
Hospital procurement committees now prioritize interoperability certification over feature breadth when selecting EHR consulting partners, compressing vendor qualification timelines and elevating specialized regulatory practices above generalist IT advisors.
Growth Catalysts
- FDA 21st Century Cures Act:Information blocking penalties compel health systems to engage compliance-specialized consultants for API gateway architecture and patient data exchange protocols.
- Cloud-native analytics platforms:Pharmacy chains and specialty clinics deploy Microsoft Azure and AWS health data lakes, requiring elastic capacity planning advisory that legacy on-premises specialists cannot deliver.
- India:The PLI scheme for medical device manufacturing and digital health infrastructure investments create demand for EHR localization and telemedicine workflow consulting.
Market Restraints
- Specialized talent scarcity:Health informaticists with dual clinical-technical credentials command premium rates, inflating project delivery costs and extending timelines.
- EU AI Act and GDPR health data provisions:Multinational hospital operators face conflicting compliance obligations across European subsidiaries, fragmenting consulting scope and increasing legal review overhead.
- Legacy system entrenchment:Decades-old on-premises EHR architectures resist cloud migration, trapping consulting spend in maintenance rather than transformation engagements.
Strategic Opportunities
- Rural US health systems:Critical access hospitals under CMS quality payment program pressure seek fractional CIO services and remote cybersecurity monitoring previously unavailable at their scale.
- Generative AI and clinical decision support convergence:Consulting practices that bridge LLM implementation with FDA software-as-medical-device pathways capture premium advisory retainers.
- Germany:The Hospital Future Act (KHZG) funding deadlines accelerate EHR replacement cycles, creating implementation capacity shortages that external consultants fill.
Industry Challenges
- ONC information blocking rule interpretation:Evolving enforcement guidance forces consultants to revise project scopes mid-engagement, eroding margin predictability.
- Multi-cloud integration complexity:Health systems deploying hybrid architectures across Azure, AWS, and Google Cloud require specialized orchestration expertise that remains scarce.
- HIPAA security rule audit preparation:OCR enforcement actions intensify demand for documentation-heavy risk assessments, commoditizing baseline compliance work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare IT Consulting Services Market |
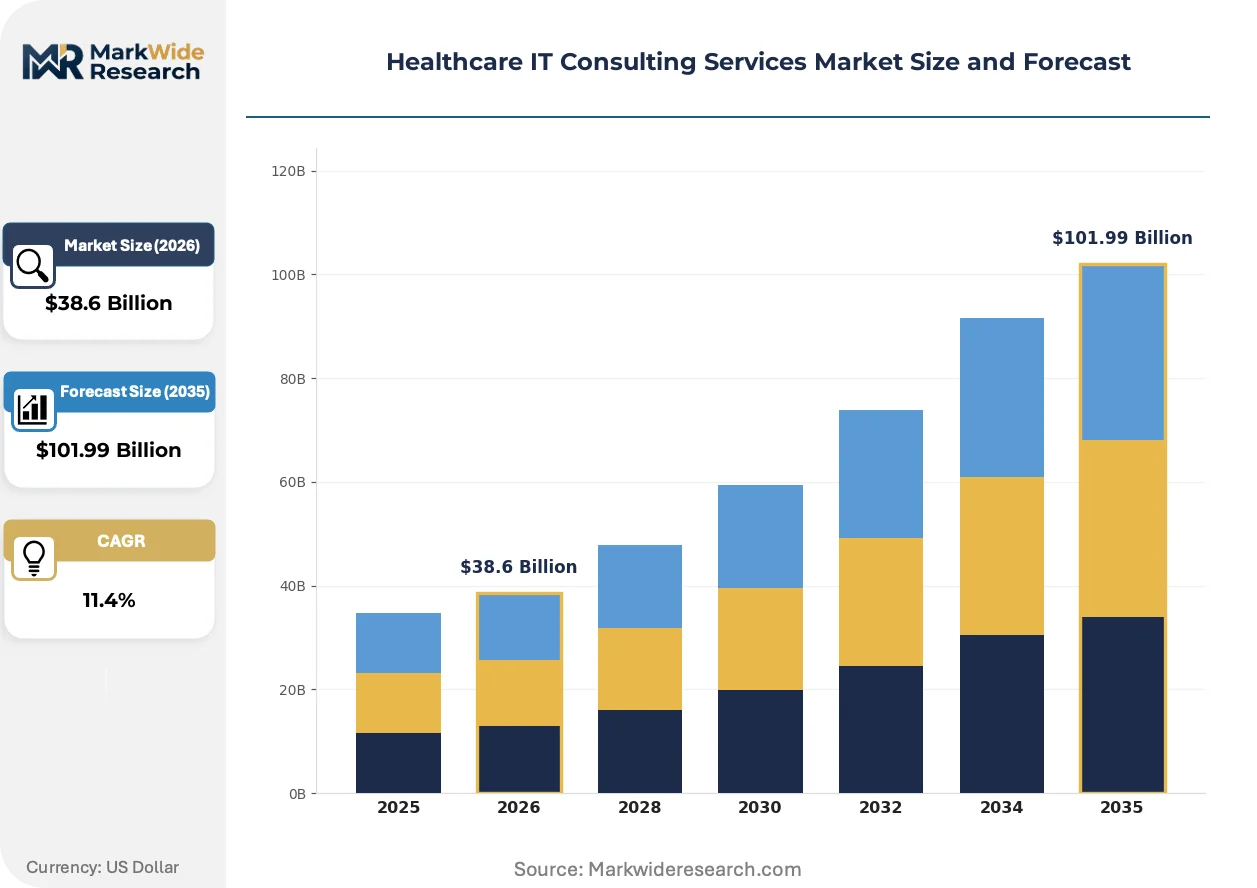
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Implementation Services, Support & Maintenance, Regulatory Compliance End User: Hospitals, Clinics, Laboratories, Pharmacy Chains Technology: EHR Solutions, Telemedicine Platforms, Health Analytics, Interoperability Solutions Delivery Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | IBM Consulting, DXC Technology, Accenture, Optum, Infosys, Deloitte, PwC, GE Healthcare, Cognizant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare IT Consulting Services Market Trends and Innovations
Healthcare IT consulting is pivoting from system installation toward continuous compliance monitoring and AI governance advisory. This reconfiguration rewards practices with embedded regulatory expertise and penalizes pure technical implementers.
FHIR-based interoperability middleware is absorbing consulting investment that previously flowed to custom HL7v2 interface development. Integrated delivery networks in the United States deploy SMART on FHIR app galleries, requiring consultants to architect standardized authentication and data consent frameworks. This standardization is compressing the market for bespoke integration engineering.
The EU AI Act risk classification system for clinical decision support software is restructuring vendor qualification requirements across European hospital procurement. High-risk AI deployments now mandate conformity assessment procedures that consulting firms must embed within implementation methodologies. German and French health systems are advancing procurement language that excludes uncertified algorithmic tools.
Subscription-based advisory retainers are displacing project-based statements of work among mid-size hospital systems. These arrangements bundle ongoing regulatory monitoring with fractional technical architecture support, replacing episodic EHR upgrade contracts. The model is most visible in United States metropolitan markets where health system consolidation has centralized IT governance.
Healthcare IT Consulting Services Market Segmentation
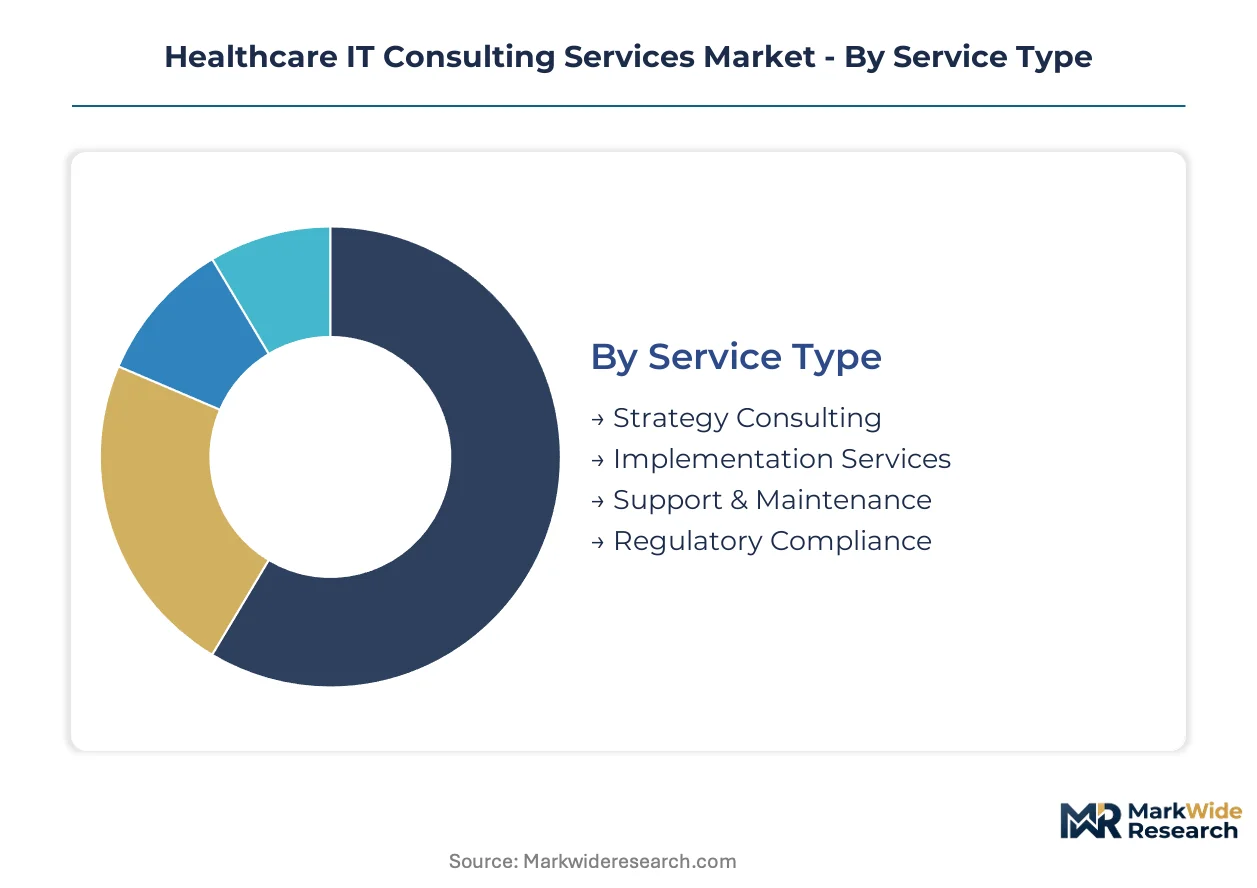
Healthcare IT consulting engagements fragment across four structural dimensions that determine pricing, delivery complexity, and vendor qualification. Procurement committees weight service maturity against technology risk when allocating consulting budgets across these categories.
Service Type:
Hospital procurement committees prioritize implementation track records over advisory breadth when qualifying vendors for multi-year EHR deployments.
- Strategy Consulting:C-suite advisory engagements align digital transformation roadmaps with CMS reimbursement timelines and FDA interoperability mandates. Academic medical centers in the United States commission these services to rationalize vendor portfolios across acquired hospital networks.
- Implementation Services:Phased EHR deployment project management consumes the largest share of consulting expenditure as health systems avoid greenfield builds. Germany's Hospital Future Act funding deadlines accelerate demand for Cerner and Epic migration expertise.
- Support & Maintenance:Post-go-live optimization retains incumbent consultants through multi-year application management contracts.
- Regulatory Compliance:HIPAA security rule documentation and ONC information blocking remediation engagements expand with OCR enforcement intensity.
Volume sits with Implementation Services; growth tilts toward Regulatory Compliance.
End User:
Scale of IT governance infrastructure determines consulting engagement structure and pricing tier.
- Hospitals:Integrated delivery networks deploy enterprise EHR modernization programs requiring hundreds of consultant FTEs. United States health systems under CMS quality payment program pressure anchor demand for fractional CIO services.
- Clinics:Specialty ambulatory practices purchase modular workflow optimization rather than enterprise transformation.
- Laboratories:LIS-EHR integration and FDA 21st Century Cures Act API compliance drive niche consulting demand.
- Pharmacy Chains:CVS and Walgreens-scale operators commission Azure and AWS health data lake architecture for population analytics.
Procurement concentration favors Hospitals; Pharmacy Chains expand most quickly.
Technology:
Interoperability certification requirements reshape which technology specializations command premium consulting rates.
- EHR Solutions:Epic, Cerner, and MEDITECH deployment expertise remains the core revenue pillar as hospitals replace legacy systems.
- Telemedicine Platforms:Virtual care workflow integration surged post-pandemic and now sustains steady demand for patient portal and remote monitoring configuration.
- Health Analytics:Cloud-native data lake implementations for pharmacy chains and payers require specialized capacity planning advisory.
- Interoperability Solutions:FHIR-based middleware and SMART on FHIR app gallery architecture absorbs investment previously directed to custom HL7v2 interfaces.
Revenue weight rests with EHR Solutions; Interoperability Solutions climbs the fastest.
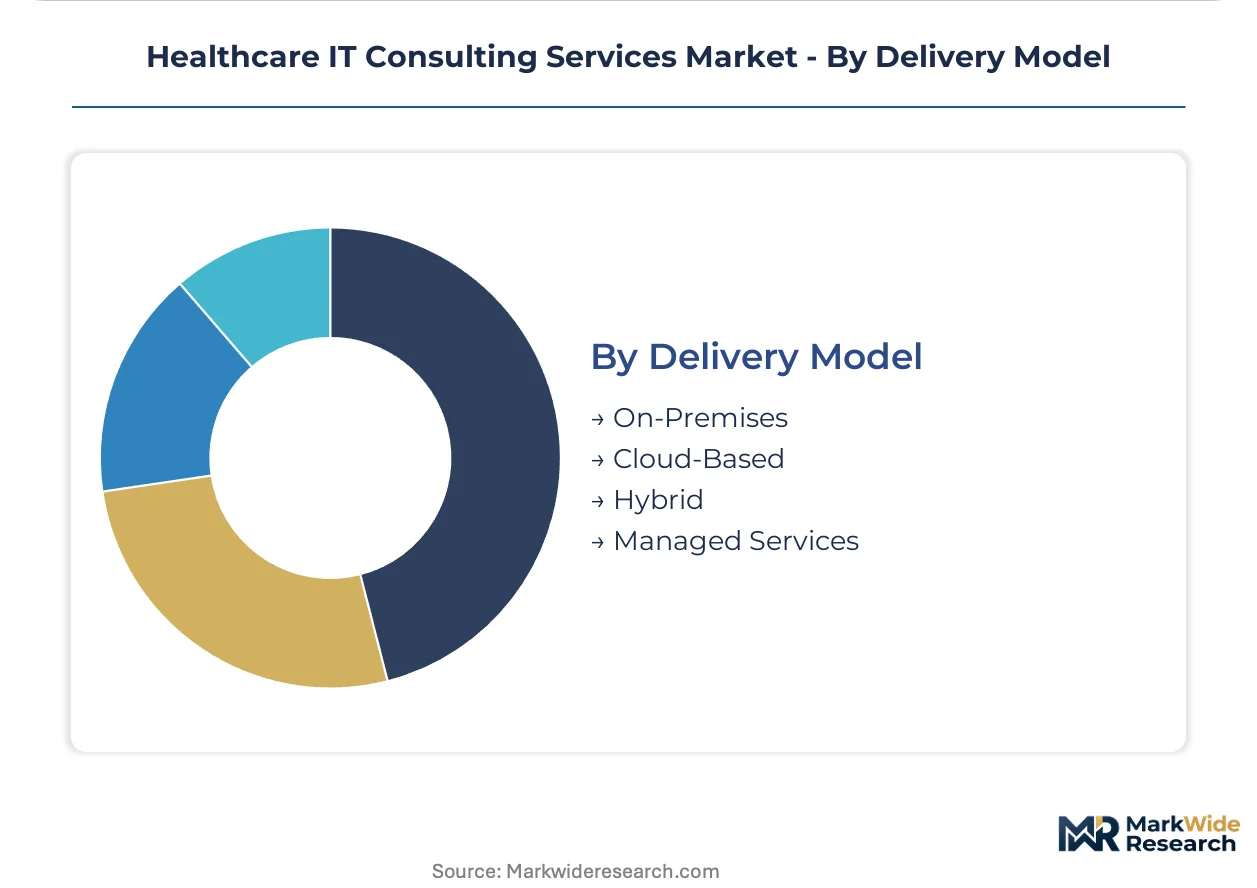
Delivery Model:
Cloud migration maturity divides consulting practices between legacy maintenance and elastic architecture advisory.
- On-Premises:Decades-old data center EHR architectures trap consulting spend in maintenance rather than transformation.
- Cloud-Based:Microsoft Azure and AWS health data lakes gain traction among pharmacy chains seeking elastic analytics capacity without capital infrastructure.
- Hybrid:Mixed on-premises and SaaS architectures dominate hospital deployments requiring phased legacy retirement.
- Managed Services:Subscription-based advisory retainers displace project-based statements of work among mid-size health systems.
Engagement volume clusters in Hybrid; Cloud-Based shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's health data infrastructure anchors North American consulting demand, while Germany's industrial software heritage shapes European procurement patterns. Hospital digitalization mandates across three continents concentrate advisory spend in specific regulatory environments.
United States
Integrated delivery networks in Texas and Florida commission Epic migration projects exceeding five hundred consultant FTEs. CMS quality payment program penalties and FDA 21st Century Cures Act information blocking rules compress vendor qualification timelines. The Boston-Cambridge corridor anchors specialized regulatory compliance practices serving academic medical centers.
Germany
Hospital Future Act funding deadlines through 2024 accelerate Cerner replacement cycles in Bavaria and North Rhine-Westphalia. KHZG reimbursement rules mandate interoperable EHR architectures, elevating demand for FHIR middleware specialists. Berlin-based consulting practices capture federal digital hospital program implementation contracts.
India
PLI scheme incentives for medical device manufacturing drive EHR localization projects in Maharashtra and Karnataka. CDSCO digital health guidelines and Ayushman Bharat telemedicine expansion create workflow consulting demand. Hyderabad's health tech cluster attracts implementation partnerships with US-based advisory firms.
United Kingdom
NHS England's federated data platform procurement concentrates advisory spend in London and the Greater Manchester health innovation zone. NHSX interoperability standards and GDPR health data enforcement elevate compliance-specialized engagements. Cambridge's biomedical cluster generates clinical decision support algorithm governance demand.
Japan
METI's Society 5.0 health data integration roadmap drives cloud migration advisory in Tokyo and Osaka metropolitan hospitals. PMDA software-as-medical-device pathways for AI diagnostic tools restructure vendor qualification requirements. Nagoya's medical device manufacturing corridor demands ERP-EHR integration expertise.
Healthcare IT Consulting Services Market Competitive Landscape
Global majors compete with regional champions across regulatory specialization depth, creating a tiered structure where scale and expertise trade off. The vendor base clusters around three strategic archetypes: federal contracting specialists capturing large-scale EHR modernization, regulatory compliance boutiques navigating FDA and EU AI Act certification, and cloud-native practices delivering elastic analytics architecture. Dominant competitive moves include strategic partnerships with Microsoft Azure and AWS health cloud divisions, plus geographic expansion through India-based delivery centers.
Among federal contracting specialists, Accenture anchors large-scale integrated delivery network transformations. Deloitte occupies a position within the regulatory compliance tier, exemplifying practices that bridge technical implementation with FDA 21st Century Cures Act requirements. IBM Consulting represents the hybrid cloud architecture archetype, sitting within the segment delivering Azure and AWS health data lake implementations for pharmacy chain operators.
| Leading Market Players |
|---|
| IBM Consulting |
| DXC Technology |
| Accenture |
| Optum |
| Infosys |
| Deloitte |
| PwC |
| GE Healthcare |
| Cognizant |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery networks in the United States concentrate procurement authority for multi-year EHR modernization programs, anchoring project-based consulting fees that bundle implementation labor with ongoing regulatory compliance retainers. This buyer concentration elevates pricing power for practices with FDA 21st Century Cures Act certification expertise while compressing margins for generalist IT advisors competing on technical implementation alone.
Pricing Analysis
Regulatory compliance bundling separates premium-tier advisory from unbundled technical implementation quotes across the Healthcare IT Consulting Services Market. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA-specialized practices commanding retainers that unbundle post-go-live support from initial deployment fees. Price differentiation hinges on dual clinical-technical credential density and geographic delivery cost for on-site workflow redesign. Cost compression in standard-tier implementation is intensifying because health informaticist scarcity inflates project delivery timelines. Critical access hospitals exhibit highest price sensitivity, while academic medical centers prioritize regulatory risk mitigation over fee minimization.
Supply Chain Analysis
India's PLI scheme for medical device manufacturing and digital health infrastructure is reshaping sourcing patterns for EHR localization and telemedicine workflow talent. Consulting delivery draws from the United States for regulatory specialization, India for implementation scale, and Germany for FHIR middleware engineering. Raw material dependencies include cloud compute capacity from Microsoft Azure and AWS, specialized health informaticist labor pools, and certification training infrastructure. Single-source vulnerability concentrates in dual clinical-technical credential pipelines that resist rapid expansion. Distribution runs through direct enterprise sales to hospital procurement committees and federal contracting vehicles for large-scale integrated delivery network transformations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare IT Consulting Services Market operates under acute supply constraint as dual clinical-technical credential scarcity props pricing power for certified practices. This capacity bottleneck sustains premium retainers for regulatory-specialized advisors while limiting expansion velocity for pure technical implementers.
For Market Incumbents: Deepen vertical integration into health informaticist training pipelines and certification programs to defend against boutique regulatory practices eroding implementation margins. Accenture and Deloitte should anchor cloud-native analytics partnerships with Microsoft Azure and AWS to preempt pure-play cloud consultancies. Incumbents must lock multi-year application management contracts before subscription-based advisory retainers displace project-based statements of work among mid-size hospital systems.
For New Entrants and Emerging Players: Capture fractional CIO services demand from rural US critical access hospitals previously unserved at their scale, where CMS quality payment program pressure creates urgent procurement appetite. India's PLI scheme incentives and CDSCO digital health guidelines present the most penetrable geography for EHR localization consulting. New entrants should pursue partnership-based go-to-market models with US-based advisory firms seeking Hyderabad delivery center expansion rather than competing directly for enterprise procurement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regulatory compliance boutiques in Germany facing KHZG funding deadline compression, where Hospital Future Act implementation capacity shortages create acquisition targets with embedded FHIR middleware expertise. Long-term viability centers on practices bridging LLM implementation with FDA software-as-medical-device pathways as generative AI converges with clinical decision support. Investors should monitor ONC information blocking enforcement guidance revisions as the inflection signal that reshapes vendor qualification criteria and consulting scope definitions.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21st Century Cures Act Certification Investment | Positions practices for information blocking penalty-driven demand from US integrated delivery networks. |
| Cloud-Native Analytics Partnership | Captures pharmacy chain demand for Azure and AWS health data lake elastic capacity planning. |
| Health Informaticist Training Pipeline Development | Addresses specialized talent scarcity inflating project delivery costs across implementation services. |
| SMART on FHIR App Gallery Architecture | Absorbs consulting investment shifting from custom HL7v2 interfaces to standardized middleware. |
| EU AI Act Conformity Assessment Capability | Qualifies practices for high-risk clinical decision support software procurement across German and French hospital systems. |
Research Methodology
Document review covered FDA 21st Century Cures Act guidance documents, CMS reimbursement rule filings, and hospital procurement databases, complemented by interviews with health system CIOs, EHR vendor implementation directors, GPO contracts managers, and regulatory compliance officers. Secondary validation drew from SEC filings of publicly traded consulting firms, hyperscaler health cloud division disclosures, and European Hospital Future Act funding reports. Bottom-up engagement sizing across service type and delivery model segments was triangulated against top-down market aggregation from national health IT expenditure surveys.
Cross-referencing historical EHR deployment timelines against panel input from procurement committees and consulting practice leaders shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end user scale, technology specialization, and delivery model maturity, with additional weighting for regulatory complexity tier. CAGRs were derived from elasticity-adjusted adoption curves and capacity-constrained supply expansion limits, incorporating cloud migration velocity and interoperability mandate enforcement intensity as healthcare-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ONC information blocking rule interpretation shifts, EU AI Act enforcement calibration, and health informaticist pipeline expansion rates. Forecasts reflect documented assumptions regarding CMS reimbursement timeline stability and cloud provider health data lake investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
Secure Messaging in Healthcare Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Cancer Patient Registry Software Market