
 Polymerase Chain Reaction Technologies Market | 2026-2036
Polymerase Chain Reaction Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Polymerase Chain Reaction Technologies Market Analysis
High-sensitivity digital PCR specification tiers is rotating toward the center of vendor strategy as laboratories demand absolute quantification for liquid biopsy and cell-free DNA applications. Thermo Fisher Scientific leverages its integrated reagent-instrument workflow to dominate clinical installed bases. Bio-Rad Laboratories sustains technology leadership in droplet digital PCR through specialized microfluidics engineering. QIAGEN anchors molecular sample preparation connectivity to PCR platforms, controlling upstream workflow capture.
Polymerase chain reaction technologies constitute enzymatic DNA amplification systems operating through thermal cycling between denaturation, annealing, and extension temperatures, typically employing Taq polymerase at 72°C extension optima to generate millions of target sequence copies for downstream detection. Real-time PCR systems command the largest installed base across clinical diagnostics due to established reimbursement pathways and regulatory familiarity. Digital PCR represents the fastest-expanding segment category, with margin pools concentrating in oncology research applications where absolute quantification commands premium pricing.
The FDA quality system regulation and Clinical Laboratory Improvement Amendments govern instrument validation and laboratory-developed test protocols, respectively, creating compliance barriers that favor established manufacturers with regulatory affairs infrastructure. ISO 15189 medical laboratory accreditation and the EU In Vitro Diagnostic Regulation shape product standards and market access requirements across European territories. Stakeholders must monitor evolving FDA guidance on next-generation sequencing companion diagnostics, as convergence between PCR and sequencing platforms will reshape platform procurement decisions and reagent consumable attach rates.
Market Dynamics
The transition from qualitative endpoint detection to absolute quantification is fragmenting installed base loyalty as laboratories revalidate workflows around digital PCR specifications.
Growth Catalysts
- Liquid Biopsy Expansion:Oncology laboratories in the United States are validating cell-free DNA protocols that demand digital PCR sensitivity thresholds, pulling instrument refresh cycles forward.
- Pharmacogenomic Panel Reimbursement:Expanded CPT code coverage for CYP450 and warfarin sensitivity testing is driving clinical laboratory menu expansion across hospital systems.
- ISO 15189 Accreditation:European medical laboratories pursuing harmonized quality standards are standardizing on integrated reagent-instrument workflows to reduce analytical variability.
Market Restraints
- Thermocycler Component Concentration:Precision Peltier element manufacturing concentrates in East Asian suppliers, exposing instrument OEMs to thermal cycling chip allocation constraints.
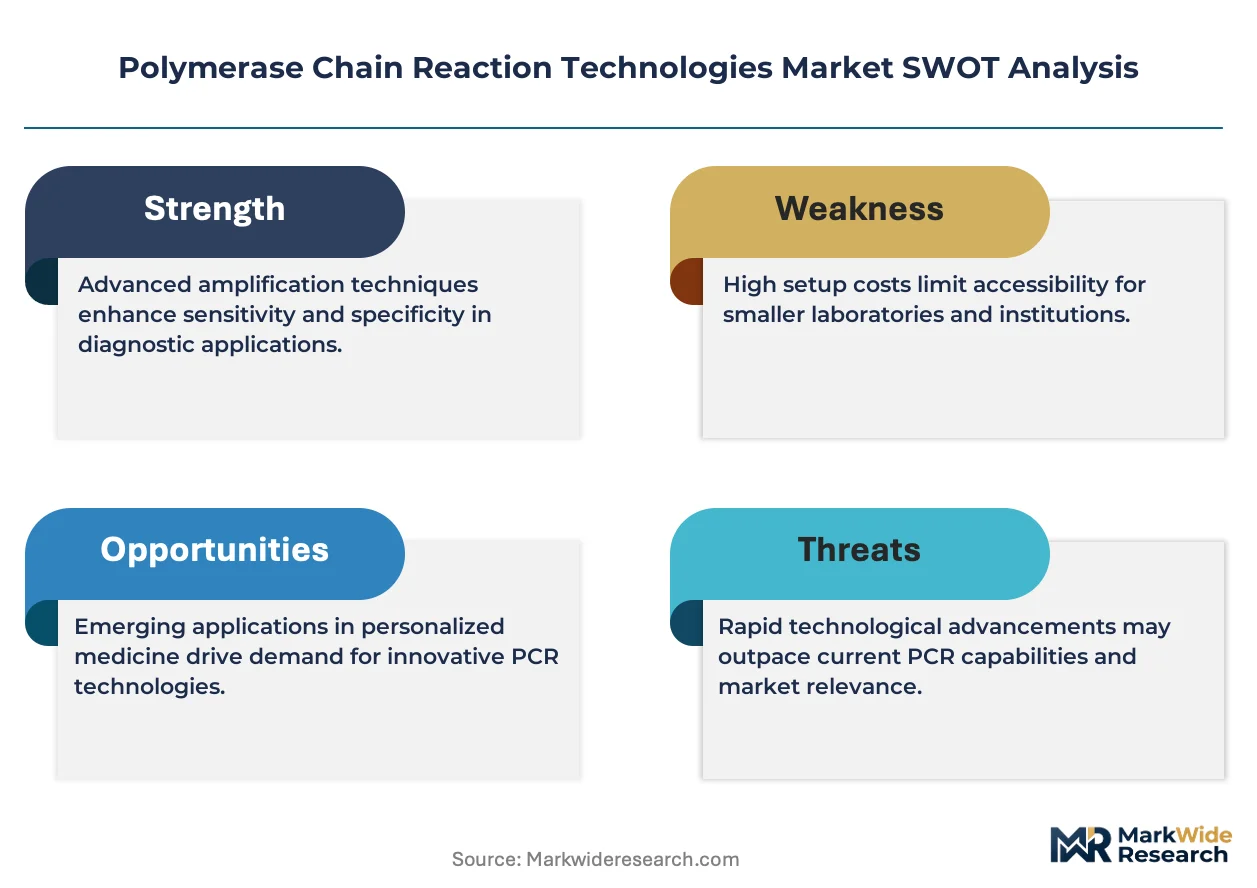
- Fluorophore Patent Thickets:Locked probe chemistry intellectual property held by incumbent reagent vendors limits third-party assay development and commoditizes detection channel differentiation.
- CLIA Complexity:The Clinical Laboratory Improvement Amendments' high-complexity test classification creates compliance overhead that slows laboratory-developed test commercialization timelines.
Strategic Opportunities
- Point-of-Care Decentralization:CLIA-waived molecular testing regulations are opening pharmacy clinic and urgent care channels for cartridge-based PCR platforms.
- CRISPR-PCR Convergence:SHERLOCK and DETECTR diagnostic architectures combining CRISPR collateral cleavage with amplification are creating new intellectual property white space in infectious disease detection.
- Saudi Arabia Healthcare Privatization:SFDA regulatory harmonization with IMDRF standards is accelerating private laboratory infrastructure buildout for hereditary disorder screening programs.
Industry Challenges
- Bioinformatics Pipeline Integration:Clinical laboratories struggle to validate cloud-based analysis workflows against FDA cybersecurity guidance for in vitro diagnostic data systems.
- Reagent Cold Chain Integrity:Enzyme and probe stability requirements create last-mile distribution complexity for reference laboratory networks expanding into ambient-temperature climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymerase Chain Reaction Technologies Market |
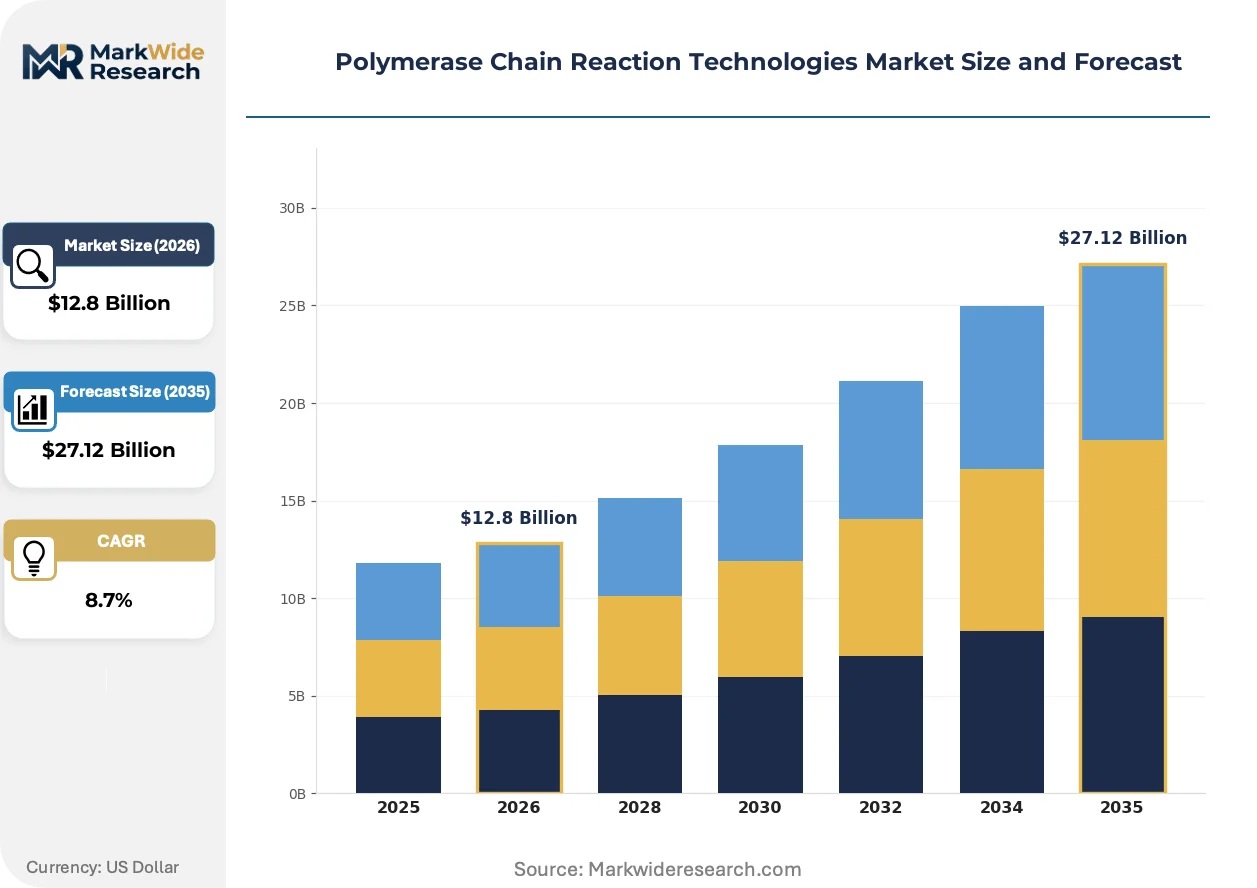
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard PCR, Real-Time PCR, Digital PCR, Multiplex PCR End User: Academic Research, Clinical Diagnostics, Forensic Laboratories, Biotechnology Firms Technology: Isothermal Amplification, Quantitative PCR, High-Throughput PCR, Next-Generation Sequencing Application: Genetic Testing, Infectious Disease Diagnosis, Oncology Research, Environmental Analysis |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., QIAGEN, F. Hoffmann-La Roche Ltd., Agilent Technologies Inc., Abbott, Danaher, Standard BioTools, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymerase Chain Reaction Technologies Market Emerging Trajectories
Workflow automation and microfluidic integration are compressing manual handling steps while regulatory convergence between PCR and sequencing platforms is reshaping capital procurement criteria.
Microfluidic droplet generation is fragmenting the digital PCR hardware landscape as specialized chip foundries enable modular instrument architectures. Academic research cores and contract research organizations are adopting open-platform droplet systems at twice the rate of closed-box clinical installations. This modularity is fragmenting vendor lock-in patterns and compressing service contract attach rates for legacy thermal cycler incumbents.
The EU In Vitro Diagnostic Regulation's Common Specifications for companion diagnostics are forcing reagent manufacturers to maintain parallel technical documentation for PCR and next-generation sequencing assay formats. Instrument OEMs must now validate software pipelines for both detection modalities under a single quality management system. Oncology reference laboratories in Germany and France are consolidating procurement committees to evaluate combined PCR-sequencing platform bids.
Hospital laboratory consolidation is compressing vendor negotiation cycles as integrated delivery networks centralize high-throughput instrument purchasing. Group purchasing organizations are unbundling reagent contracts from instrument placement agreements, forcing suppliers to compete on per-test economics rather than capital lease structures. This pattern is most visible in United States multi-hospital systems exceeding 50 laboratories under unified supply chain management.
Polymerase Chain Reaction Technologies Market Segmentation
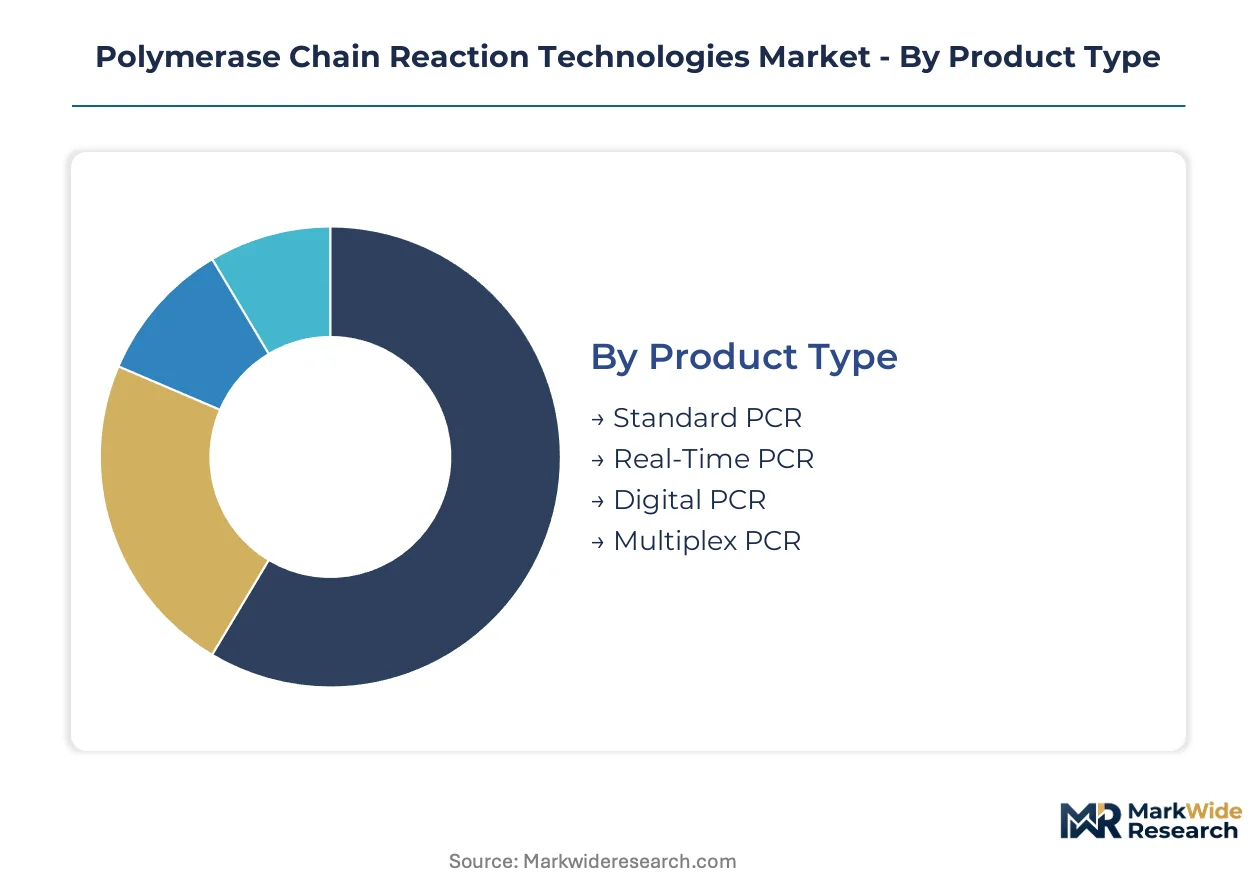
PCR technology segmentation reveals how laboratories prioritize detection sensitivity, throughput economics, and regulatory compliance when allocating capital across amplification platforms. Substitution pressures from sequencing and isothermal methods are fragmenting traditional category boundaries.
Product Type:
Real-Time PCR faces the strongest substitution threat from digital PCR in oncology quantification workflows, while standard endpoint PCR retains cost advantages in resource-limited settings.
- Standard PCR:Endpoint detection systems employing gel electrophoresis or colorimetric readouts for presence-absence screening. Demand concentrates in veterinary diagnostics and food safety laboratories across India and Brazil where capital constraints limit fluorogenic instrument adoption. Thermal cycler hardware commoditization is compressing margins for incumbent manufacturers.
- Real-Time PCR:Fluorogenic signal acquisition during thermal cycling enables relative quantification through SYBR Green or hydrolysis probe chemistries. Clinical diagnostics laboratories in the United States deploy these systems for infectious disease panels under established CPT reimbursement codes. FDA 510(k) pathway familiarity sustains installed base loyalty despite digital PCR sensitivity advantages.
- Digital PCR:Absolute quantification through microfluidic droplet or chip-based partitioning eliminates standard curve dependencies. Oncology reference laboratories validate cell-free DNA protocols requiring single-molecule sensitivity thresholds.
- Multiplex PCR:Simultaneous amplification of multiple targets reduces reagent consumption per sample in respiratory pathogen surveillance panels.
Real-Time PCR retains volume leadership; Digital PCR holds the steepest expansion curve.
End User:
Customer type segmentation tracks procurement authority migration from principal investigators to supply chain committees in consolidated health systems.
- Academic Research:Core facilities and individual laboratories purchasing through institutional grants with emphasis on publication-grade sensitivity specifications. European Research Council funding cycles in Germany and France are prioritizing open-platform droplet digital PCR systems over closed-box clinical instruments.
- Clinical Diagnostics:Hospital laboratories and commercial reference operations subject to CLIA high-complexity test classification and FDA quality system regulation compliance. Group purchasing organizations in United States multi-hospital systems are unbundling reagent contracts from instrument lease agreements.
- Forensic Laboratories:Government crime laboratories validating STR amplification protocols under FBI Quality Assurance Standards.
- Biotechnology Firms:Contract manufacturing organizations integrating PCR into cell line authentication and mycoplasma detection workflows.
Clinical Diagnostics commands procurement volume concentration; Biotechnology Firms are expanding capacity fastest.
Technology:
Technology architecture determines thermal cycling requirements, reagent enzyme specifications, and downstream bioinformatics pipeline complexity.
- Isothermal Amplification:Loop-mediated amplification and recombinase polymerase amplification operating at constant temperature eliminate thermocycler hardware requirements. Point-of-care diagnostic developers in Kenya and Nigeria are deploying battery-powered devices for malaria and tuberculosis detection in ambient-temperature field conditions.
- Quantitative PCR:Real-time fluorescence monitoring enabling relative gene expression analysis through delta-delta Ct normalization methods. Pharmaceutical toxicology laboratories employ these workflows for biomarker validation under Good Laboratory Practice standards.
- High-Throughput PCR:384-well and 1536-well format thermal cyclers with robotic integration for genome-wide association studies.
- Next-Generation Sequencing:Library quantification and target enrichment workflows bridging amplification and sequencing platforms.
Quantitative PCR maintains installed base dominance; Isothermal Amplification is penetrating point-of-care channels fastest.
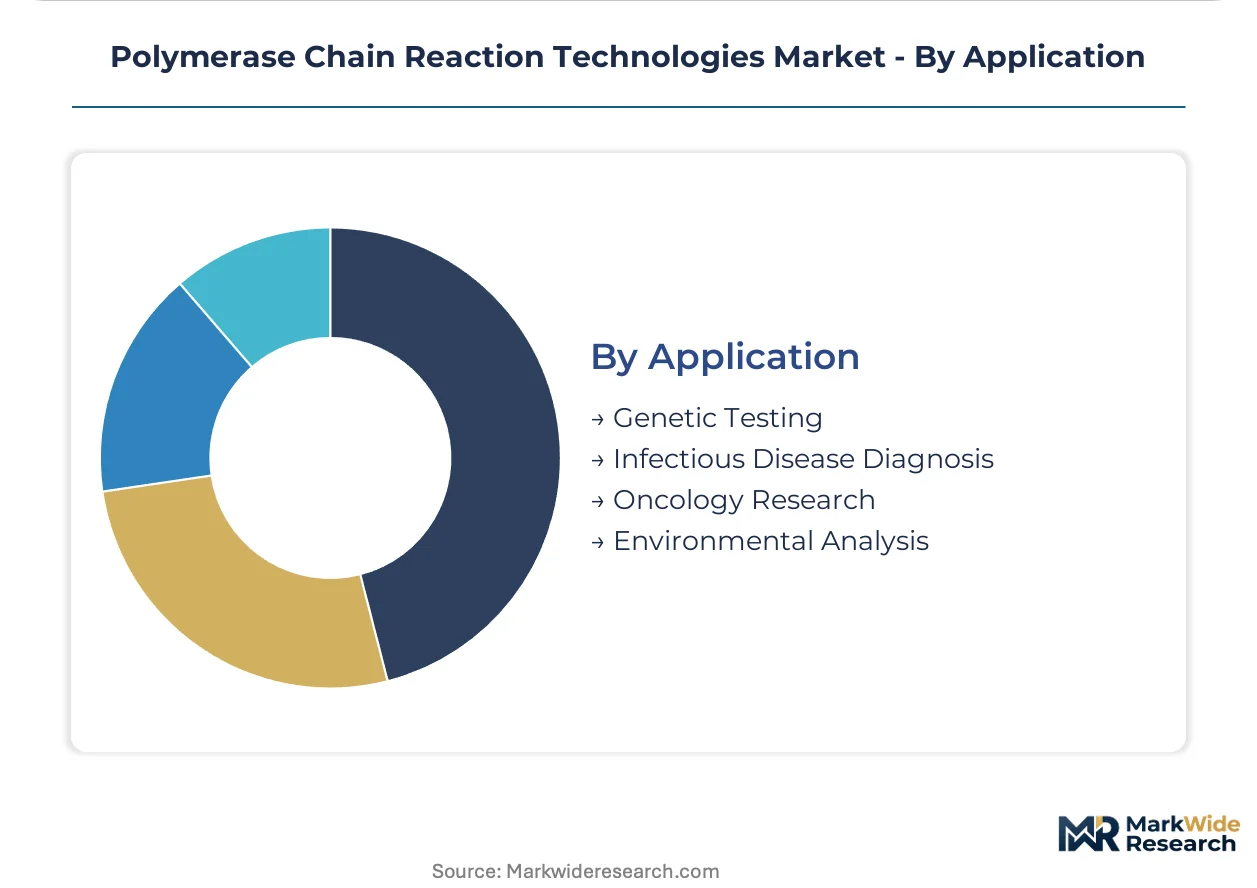
Application:
Application segmentation reflects reimbursement pathway maturity and companion diagnostic regulatory convergence between PCR and sequencing platforms.
- Genetic Testing:Carrier screening, newborn screening, and pharmacogenomic panel analysis requiring CLIA laboratory certification and state laboratory licensure. United States hospital laboratories are expanding CYP450 and warfarin sensitivity testing menus following expanded CPT code coverage.
- Infectious Disease Diagnosis:Respiratory pathogen panels, sexually transmitted infection screening, and antimicrobial resistance marker detection. Centralized reference laboratories in the United Kingdom are consolidating SARS-CoV-2 surveillance contracts onto high-throughput real-time PCR platforms.
- Oncology Research:Liquid biopsy validation for circulating tumor DNA monitoring in clinical trial enrollment.
- Environmental Analysis:Microbial source tracking and pathogen detection in water quality monitoring programs.
Infectious Disease Diagnosis anchors commercial volume; Oncology Research is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PCR instrument trade flows tilt toward net-importing clinical economies, while reagent manufacturing concentrates in jurisdictions with bioprocessing infrastructure. Regulatory harmonization is accelerating cross-border procurement standardization.
United States
Hospital laboratory consolidation is driving centralized procurement of high-throughput PCR platforms across multi-hospital systems. The FDA's quality system regulation for in vitro diagnostic devices shapes instrument validation requirements for CLIA high-complexity test classification. The Boston-Cambridge biotech corridor anchors oncology reference laboratory expansion for liquid biopsy validation.
Germany
ISO 15189 medical laboratory accreditation is standardizing integrated reagent-instrument workflows to reduce analytical variability. The EU In Vitro Diagnostic Regulation's Common Specifications for companion diagnostics force parallel technical documentation for PCR and sequencing assay formats. The Rhine-Ruhr industrial region concentrates pathology laboratory networks consolidating procurement committees for combined platform bids.
China
Domestic instrument manufacturers are capturing share in veterinary diagnostics and food safety applications where capital constraints limit fluorogenic system adoption. The National Medical Products Administration governs in vitro diagnostic device registration and quality management system certification. The Yangtze River Delta biopharma cluster is expanding contract manufacturing organization capacity for cell line authentication PCR workflows.
Japan
Pharmaceutical toxicology laboratories employ quantitative PCR workflows for biomarker validation under Ministry of Health, Labour and Welfare Good Laboratory Practice standards. The Pharmaceuticals and Medical Devices Agency oversees companion diagnostic regulatory convergence with sequencing platforms. The Kansai region's Osaka-Kobe pharmaceutical corridor is integrating PCR into antimicrobial resistance marker detection surveillance.
Saudi Arabia
Healthcare privatization is accelerating private laboratory infrastructure buildout for hereditary disorder screening programs. The Saudi Food and Drug Authority is harmonizing regulatory standards with International Medical Device Regulators Forum guidelines. Riyadh's medical city complex is centralizing molecular diagnostics procurement for pharmacogenomic panel expansion.
Polymerase Chain Reaction Technologies Market Vendor Landscape
Listed leaders compete with private specialists across reagent-instrument integration depth, creating a tiered structure where scale-driven conglomerates face modular challengers. The vendor base separates into three strategic archetypes: integrated workflow providers controlling upstream sample preparation, microfluidics specialists dominating droplet digital PCR specifications, and point-of-care platform developers exploiting CLIA-waived regulatory channels. Competitive moves concentrate on unbundling reagent contracts from instrument lease agreements and backward integration into precision thermal cycling component manufacturing.
Within the integrated workflow tier, Thermo Fisher Scientific Inc. and QIAGEN occupy positions anchoring clinical installed bases through reagent-instrument connectivity. Bio-Rad Laboratories Inc. exemplifies the microfluidics specialist archetype, with droplet digital PCR engineering sustaining technology leadership in absolute quantification applications. These three entities represent the dominant competitive anchors shaping procurement committee evaluations across consolidated health systems.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| QIAGEN |
| F. Hoffmann-La Roche Ltd. |
| Agilent Technologies Inc. |
| Abbott |
| Danaher |
| Standard BioTools |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Long-term reagent-instrument bundle contracts lock in supply access and price visibility for clinical diagnostics laboratories across United States hospital systems, insulating incumbent vendors from spot-market volatility while compressing third-party assay developer margins.
Pricing Analysis
Industrial OEM buyers anchor per-test economics as group purchasing organizations unbundle reagent contracts from instrument lease agreements. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification grade, throughput capacity, and after-sales service bundling. Cost compression in economy-tier thermal cyclers is intensifying because East Asian Peltier element manufacturers are expanding production capacity. Academic research cores exhibit highest price sensitivity due to grant-funded procurement constraints; oncology reference laboratories show lowest sensitivity given reimbursement-backed absolute quantification requirements.
Supply Chain Analysis
Strategic stockpiling of precision thermal cycling components dominates inventory strategy as laboratories buffer against East Asian supplier allocation constraints. Precision Peltier element manufacturing concentrates in China, South Korea, and Japan; fluorophore chemistries draw from German and Swiss specialty chemical producers. Single-source vulnerability in microfluidic droplet chip foundries threatens digital PCR instrument OEMs. Distribution runs through authorized distributor networks serving CLIA-certified laboratories, with cold chain logistics for enzyme reagents creating last-mile complexity in ambient-temperature climates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital PCR sensitivity thresholds are disrupting installed base loyalty as oncology laboratories revalidate workflows around absolute quantification specifications, with FDA guidance on next-generation sequencing companion diagnostics accelerating platform convergence decisions.
For Market Incumbents: Fortify reagent-instrument connectivity through backward integration into precision thermal cycling component manufacturing. Deepen regulatory affairs infrastructure to navigate EU In Vitro Diagnostic Regulation Common Specifications and FDA quality system regulation harmonization pressures. Incumbent thermal cycler vendors face substitution threat from modular droplet digital PCR systems; defend through exclusive assay menu expansion and service contract renewal incentives. For New Entrants and Emerging Players: Cloud-based bioinformatics pipeline validation services represent a service-layer gap where incumbents under-serve clinical laboratories struggling with FDA cybersecurity guidance compliance. Penetrate Saudi Arabia and Kenya point-of-care channels where CLIA-waived molecular testing regulations are opening pharmacy clinic access. Deploy cartridge-based PCR platforms through urgent care distribution partnerships rather than hospital laboratory direct sales. For Investors and Strategic Acquirers: Capital is best deployed toward microfluidics specialists with droplet digital PCR engineering capabilities and open-platform architectures. Long-term viability centers on absolute quantification applications in liquid biopsy and cell-free DNA monitoring. Watch FDA guidance convergence between PCR and next-generation sequencing companion diagnostics as inflection indicator for platform procurement committee decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Contract Unbundling | GPOs in United States multi-hospital systems are separating consumable pricing from instrument lease structures. |
| Microfluidic Chip Foundry Partnership | Modular droplet digital PCR architectures fragment vendor lock-in patterns and compress legacy service attach rates. |
| CLIA-Waived Platform Development | Pharmacy clinic and urgent care channel access accelerates point-of-care decentralization for infectious disease panels. |
| Companion Diagnostic Regulatory Convergence | EU In Vitro Diagnostic Regulation Common Specifications force parallel technical documentation for PCR and sequencing formats. |
| Precision Thermal Cycling Backward Integration | In-house Peltier element production insulates instrument OEMs from East Asian supplier allocation constraints. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across clinical diagnostics laboratories, academic research cores, and instrument OEMs. Primary interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists were validated against secondary sources including FDA 510(k) filings, EU In Vitro Diagnostic Regulation technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up instrument installation counts and top-down reagent consumable market estimates were triangulated to resolve segmentation discrepancies.
Across the analysis window, value projections were derived from pricing stratification across real-time PCR, digital PCR, and isothermal amplification tiers, with volume estimates segmented by end user type, application area, and technology architecture. CAGRs were calculated from modeled annual growth trajectories incorporating reimbursement pathway maturity, regulatory approval timelines, and laboratory consolidation patterns. Industry-specific forecast inputs included CLIA high-complexity test classification expansion rates and pharmacogenomic panel CPT code coverage adoption curves.
Forecasts assume regulatory continuity in FDA quality system regulation and EU In Vitro Diagnostic Amendment implementation; material policy shifts would require re-modeling. Specific risk factors include thermocycler component supply disruptions, fluorophore patent litigation outcomes, and cybersecurity guidance changes affecting cloud-based bioinformatics validation. Revision becomes warranted when digital PCR sensitivity threshold adoption crosses critical mass in oncology reference laboratory procurement committees.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Cell Disrupters Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Live Cell RNA Detection Market