
 Organic Dry Yeast Market | 2026-2036
Organic Dry Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Dry Yeast Market Analysis
Subscription-based technical support and formulation advisory services is restructuring how yeast suppliers monetize relationships beyond bulk ingredient sales. Lesaffre leverages its global fermentation expertise to anchor long-term supply contracts with industrial bakeries. Lallemand sustains competitive positioning through specialized strain development for organic brewing applications. Angel Yeast dominates Asia-Pacific production capacity with backward integration into molasses substrate refining.
Organic dry yeast consists of deactivated or active Saccharomyces cerevisiae cells cultivated on certified organic substrates, then dried to moisture levels below 8 percent to preserve viability and extend shelf stability; it functions as a biological leavening agent, flavor modulator, and nutritional fortificant across food and feed systems. Instant dry yeast leads product type demand due to its direct-dispersibility advantage in high-throughput bakery operations, while nutritional yeast captures premium margin pools from plant-based food fortification trends. Bakeries anchor end-user volume, though breweries represent the fastest-growing application segment as craft producers convert to organic certification.
USDA National Organic Program substrate traceability requirements and EU Organic Regulation propagation standards constrain which raw materials qualify for certified yeast production, directly shaping supplier sourcing geography and cost structures. The FDA GRAS self-affirmation pathway and EFSA novel food assessments create divergent market access timelines for innovative yeast-derived ingredients across Atlantic markets. Stakeholders must monitor evolving substrate scarcity risks and certification harmonization negotiations to secure supply continuity.
Market Dynamics
Certified organic substrate scarcity is compressing supplier margins while concentrating production among vertically integrated molasses refiners capable of meeting USDA National Organic Program traceability mandates.
Growth Catalysts
- EU Organic Regulation substrate standardization:Harmonized propagation rules across member states reduce cross-border certification friction for industrial bakeries sourcing certified yeast strains.
- Craft brewery certification conversion:Small-batch organic beer producers in Germany and France are expanding procurement of specialized Saccharomyces cerevisiae strains for fermentation consistency.
- Instant dry yeast direct-dispersibility:Elimination of rehydration steps accelerates throughput in high-volume automated bakery lines, reducing labor and water consumption.
Market Restraints
- Molasses supply concentration:Organic sugarcane and beet cultivation clusters in India and Brazil create geographic vulnerability to climate-induced harvest volatility.
- EFSA novel food assessment timelines:Extended safety evaluation periods delay market entry for innovative yeast-derived nutritional ingredients in European markets.
- Active dry yeast substitution:Lower-cost conventional yeast retains share in price-sensitive industrial baking segments where organic certification lacks consumer visibility.
Strategic Opportunities
- Plant-based food fortification:Nutritional yeast applications in vegan cheese analogs and protein powders command premium positioning in North American natural retail channels.
- Subscription formulation advisory:Technical service contracts lock in multi-year supply relationships beyond commodity ingredient transactions.
- Backward substrate integration:Captive organic molasses refining secures propagation material traceability while insulating against third-party price spikes.
Industry Challenges
- Certification audit complexity:USDA National Organic Program and EU Organic Regulation require parallel documentation systems, doubling compliance overhead for cross-Atlantic suppliers.
- Fermentation specialist scarcity:Qualified technicians for organic strain propagation command wage premiums that strain mid-cap facility economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Dry Yeast Market |
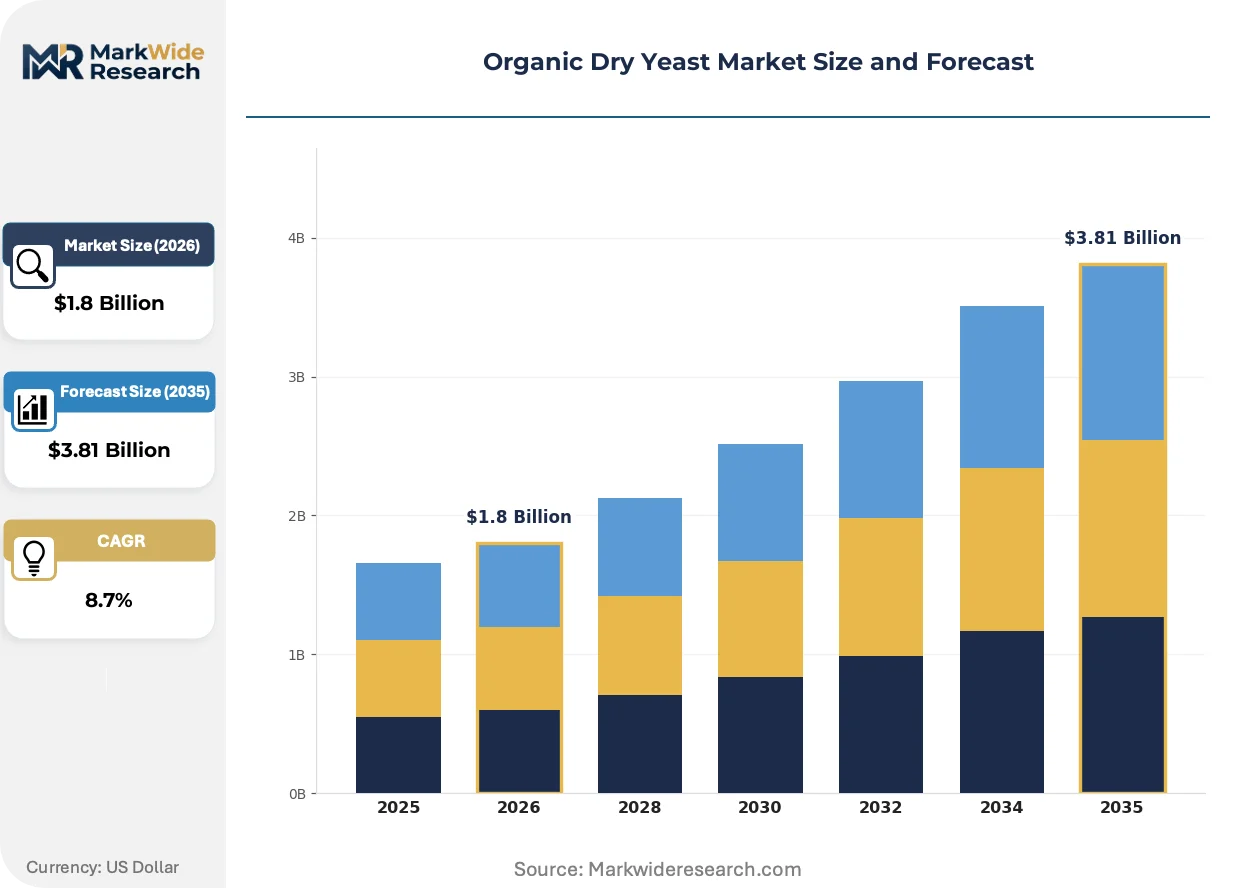
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Dry Yeast, Instant Dry Yeast, Nutritional Yeast, Baker's Yeast Application: Baking, Brewing, Fermentation, Animal Feed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Bakeries, Home Bakers, Breweries, Food Manufacturers |
| Companies Covered | Lesaffre, Lallemand, Angel Yeast, Biospringer, Ohly, Leiber GmbH, Red Star Yeast Company, AB Mauri, Koninklijke DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Dry Yeast Market Emerging Trajectories
Bioprocess automation and regulatory data digitization are compressing batch-to-batch variability while extending supply chain visibility from substrate field to finished dry yeast package.
Spray-drying optimization with fluidized bed technology is overtaking conventional drum-drying for instant dry yeast production. German industrial bakeries are retrofitting lines to accommodate the finer particle size and faster rehydration kinetics this method delivers. The shift is compressing equipment amortization timelines as throughput gains justify capital replacement cycles.
EU Green Deal Farm-to-Fork traceability requirements now mandate blockchain-verified substrate origin documentation for organic yeast certification. This industrial consequence forces propagation facilities to integrate farm-level data capture or risk delisting by major bakery purchasing consortia. French and Italian suppliers are responding fastest, leveraging existing cooperative relationships with organic beet growers.
Clean-label preference is rotating procurement authority from commodity buyers to technical formulation teams within artisan bakery chains. These specialists now specify strain performance metrics and substrate provenance rather than accepting standard catalog offerings. The pattern is most visible in German Landesbrot certification programs where ingredient transparency carries brand equity weight.
Organic Dry Yeast Market Segmentation
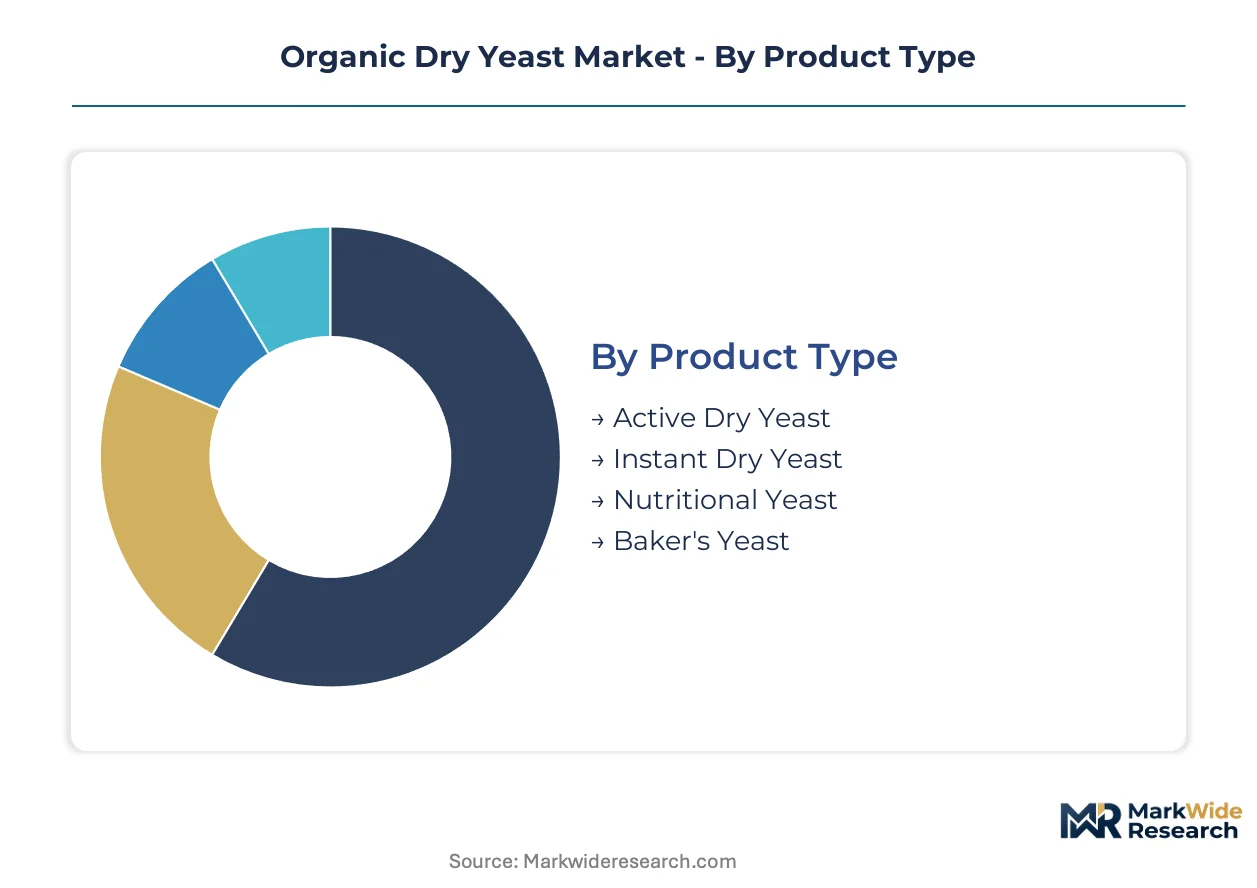
Procurement patterns across the organic dry yeast market diverge sharply between industrial scale and artisan volume. Certification requirements and formulation precision reshape how buyers evaluate product categories and channel relationships.
Product Type:
Formulation teams prioritize rehydration kinetics and strain viability over unit cost in high-throughput environments.
- Instant Dry Yeast:Finely milled particles disperse directly into flour without temperature-controlled rehydration. German industrial bakeries specify this grade for automated mixing lines where water conservation and labor reduction compound savings.
- Nutritional Yeast:Deactivated whole-cell preparations deliver B-vitamin fortification and umami depth to plant-based formulations. North American natural retail channels absorb premium positioning for vegan cheese analogs and protein powders.
- Active Dry Yeast:Larger granules require controlled rehydration before incorporation, constraining deployment to smaller-scale operations with flexible batch timing.
- Baker's Yeast:Compressed fresh preparations command localized distribution due to refrigerated shelf-life limitations, concentrating demand near production facilities.
Instant dry yeast leads on scale; nutritional yeast leads on momentum.
Application:
End-use specifications determine strain selection, substrate documentation depth, and certification audit frequency.
- Baking:Leavening performance consistency under variable humidity conditions drives strain specification. Artisan chains in France and Italy now mandate blockchain-verified substrate origin as a procurement gate.
- Brewing:Specialized Saccharomyces cerevisiae strains for ale and lager fermentation require organic certification conversion. Craft producers in Germany expand procurement fastest as EU organic beer labeling tightens.
- Fermentation:Bioactive metabolite production for flavor modulation and preservation applications concentrates among mid-cap food manufacturers seeking clean-label alternatives.
- Animal Feed:Nutritional fortification for organic livestock operations faces substrate scarcity constraints as molasses supply concentrates in India and Brazil.
Baking anchors absolute volume; brewing climbs the fastest.
Distribution Channel:
Channel selection locks in margin structure and technical service access for buyers at different scale tiers.
- Direct Sales:Long-term supply contracts bundle formulation advisory with volume commitments. Industrial bakeries leverage this channel to secure strain customization and priority allocation during substrate shortages.
- Specialty Stores:Curated strain portfolios and technical consultation attract artisan producers seeking performance differentiation. French cooperative suppliers dominate this channel through embedded relationships with organic beet growers.
- Supermarkets:Packaged instant dry yeast for home bakers competes on shelf placement and price positioning, compressing margins for branded suppliers.
- Online Retail:Direct-to-consumer nutritional yeast sales bypass traditional wholesale markups, capturing margin in plant-based specialty segments.
Direct sales command the highest contract values; specialty stores gain share fastest among artisan segments.
End User:
User scale determines whether procurement optimizes for per-unit cost or total formulation performance.
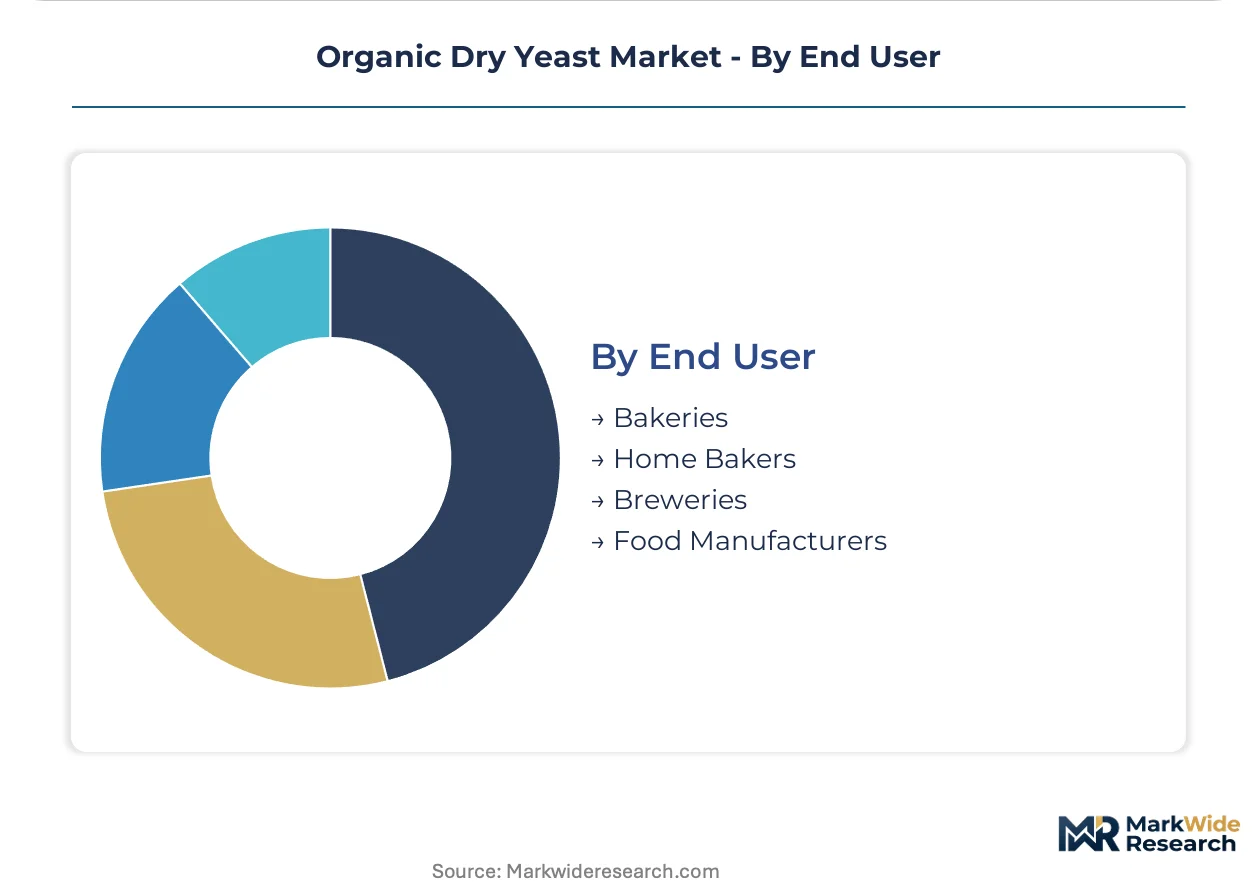
- Bakeries:Industrial operations specify instant dry yeast for throughput; artisan chains prioritize substrate traceability for brand equity. German Landesbrot certification programs now require ingredient transparency disclosure.
- Breweries:Craft organic conversion drives specialized strain demand. Small-batch producers in France and Germany absorb technical advisory costs to secure fermentation consistency.
- Food Manufacturers:Nutritional yeast integration for vegan product lines requires formulation support that commodity channels cannot provide.
- Home Bakers:Price sensitivity and convenience positioning dominate, with supermarket and online channels capturing this fragmented demand pool.
Bakeries dominate absolute procurement volume; breweries show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest per-capita organic yeast consumption in Europe, while India emerges as the fastest-growing production hub for certified organic substrates. Brazil's molasses supply chains face mounting climate pressure, reshaping sourcing geography for multinational suppliers.
Germany
Artisan bakery chains in Bavaria and Baden-Württemberg now mandate blockchain-verified substrate documentation under Landesbrot certification protocols. The EU Organic Regulation's harmonized propagation standards reduce cross-border friction for industrial bakers sourcing from French suppliers. Munich and Stuttgart industrial clusters retrofit automated mixing lines to accommodate instant dry yeast's finer particle specifications.
France
Cooperative supplier networks in Île-de-France leverage embedded relationships with organic beet growers to meet EU Green Deal Farm-to-Fork traceability mandates. ANSM oversight of novel food applications intersects with EFSA assessments for innovative yeast-derived ingredients. Lyon and Lille fermentation facilities integrate farm-level data capture to secure contracts with major purchasing consortia.
Italy
Specialized strain demand from organic craft breweries in Piedmont and Lombardy accelerates faster than any other European application segment. EU Organic Regulation substrate standardization simplifies certification for yeast strains crossing from Austrian suppliers. Milan-area industrial bakers specify instant dry yeast grades to maximize throughput on retrofitted production lines.
United States
North American natural retail channels absorb premium-priced nutritional yeast for vegan cheese analogs and protein fortification applications. USDA National Organic Program traceability requirements constrain which raw materials qualify for certified production, favoring vertically integrated molasses refiners. California and Pacific Northwest plant-based food manufacturers drive formulation advisory service contracts beyond commodity transactions.
India
Organic sugarcane cultivation clusters in Maharashtra and Uttar Pradesh supply propagation material to Asia-Pacific fermentation facilities. FSSAI alignment with international organic standards facilitates export certification for substrate shipments to European yeast producers. Mumbai and Gujarat refining complexes expand captive organic molasses capacity to insulate against third-party price volatility.
Organic Dry Yeast Market Vendor Landscape
Top-tier vendors anchor long-term supply contracting with industrial bakeries, while mid-cap specialists concentrate on strain customization for craft brewing applications. The vendor base stratifies across three functional tiers: fermentation-integrated multinationals, substrate-refining regional champions, and technical service specialists. Two dominant competitive moves define current positioning: backward integration into organic molasses refining and subscription-based formulation advisory bundling.
Within the fermentation-integrated tier, Lesaffre and Lallemand occupy positions that exemplify divergent specialization strategies. Lesaffre leverages global propagation expertise to anchor multi-year industrial bakery contracts. Lallemand sustains competitive positioning through dedicated strain development protocols for organic brewing applications. Angel Yeast represents the substrate-refining archetype, with backward integration into molasses processing securing supply continuity for Asia-Pacific production networks.
| Leading Market Players |
|---|
| Lesaffre |
| Lallemand |
| Angel Yeast |
| Biospringer |
| Ohly |
| Leiber GmbH |
| Red Star Yeast Company |
| AB Mauri |
| Koninklijke DSM |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between USDA National Organic Program and EU Organic Regulation tiers manifests in both pricing premiums and captive sourcing configurations. Industrial bakeries absorb technical advisory costs within long-term contracts while artisan chains pay traceability premiums for blockchain-verified substrate documentation.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for certified organic molasses substrates. Three-tier pricing structure across premium, standard, and economy levels separates instant dry yeast for industrial throughput from nutritional yeast for plant-based fortification and active dry yeast for price-sensitive conventional baking. Cost compression in economy tiers intensifies because conventional yeast substitution retains share where organic certification lacks consumer visibility. Artisan bakery chains show least price sensitivity due to brand equity requirements under German Landesbrot protocols.
Supply Chain Analysis
Single-source vulnerability sits with organic sugarcane cultivation clusters in Maharashtra and Uttar Pradesh. Raw material dependencies draw from certified organic molasses, specialized fermentation nutrients, and pharmaceutical-grade drying agents. Geographic supply concentration centers on India, Brazil, and Thailand for substrate refining. Tariff exposure on cross-Atlantic substrate shipments threatens margin stability for European propagation facilities. Distribution runs through direct sales contracts with industrial bakeries, specialty stores for artisan segments, and online retail for nutritional yeast consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic dry yeast has entered late-cycle quality phase as craft brewery certification conversion and blockchain-verified substrate mandates rotate procurement authority toward technical specification teams.
For Market Incumbents: To counter fermentation specialist wage premiums that strain mid-cap facility economics, anchor multi-year supply contracts bundling formulation advisory with volume commitments. Prioritize backward integration into captive organic molasses refining in Maharashtra or São Paulo to insulate against third-party price spikes and secure USDA traceability compliance. For New Entrants and Emerging Players: Capture white-space in specialized Saccharomyces cerevisiae strain development for organic craft brewing applications in Germany and France. Target nutritional yeast fortification for North American vegan cheese analogs where premium positioning exceeds commodity margin pools. Deploy subscription-based technical service contracts to bypass entrenched bulk ingredient relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with substrate-refining regional champions possessing captive organic molasses capacity. Five-to-ten year viability hinges on certification harmonization between USDA National Organic Program and EU Organic Regulation reducing parallel compliance overhead. Monitor EU Green Deal Farm-to-Fork blockchain mandate adoption velocity as inflection indicator for traceability premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Molasses Refining | Captive substrate supply secures USDA traceability compliance while insulating margin from India-Brazil price volatility. |
| Subscription Formulation Advisory Launch | Technical service contracts lock in multi-year bakery relationships beyond commodity ingredient transactions. |
| Specialized Strain Development for Craft Brewing | Dedicated Saccharomyces cerevisiae protocols capture fastest-growing application segment in Germany and France. |
| Blockchain-Verified Substrate Documentation | Farm-to-Fork data capture meets EU Green Deal mandates and Landesbrot procurement gates for artisan chains. |
| Spray-Drying Equipment Retrofit | Fluidized bed technology adoption accelerates throughput on German industrial bakery automated mixing lines. |
Methodological Framework
Bottom-up bakery and brewery procurement modeling reconciled against top-down molasses substrate tracking forms the analytical core. Primary interviews with fermentation facility managers, organic certification auditors, industrial bakery procurement leads, and craft brewery technical directors combined with secondary validation from USDA National Organic Program filings, EU Organic Regulation implementation guidance, FSSAI export certification records, and customs trade data. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices map instant dry yeast throughput volumes, nutritional yeast premium positioning, and active dry yeast substitution elasticity across product type, application, and end-user dimensions. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate EU Green Deal Farm-to-Fork traceability mandate adoption curves and craft brewery organic certification conversion rates across the analysis window.
Substrate scarcity shocks, certification harmonization delays, and climate-induced harvest volatility in Maharashtra and São Paulo are the dominant revision risks. Forecasts reflect documented assumptions about regulatory enforcement intensity and buyer specification migration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
Organic Food and Beverages Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Organic Fruit Powder Market