
 Global Oil and Gas Analytics Market | 2026-2036
Global Oil and Gas Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oil and Gas Analytics Market Foresight
Upstream operators is collapsing the traditional buyer mix that once favored downstream refineries for analytics procurement. IBM leverages its Watson platform to anchor enterprise-grade AI deployments across supermajor portfolios. Oracle competes through integrated cloud infrastructure that sustains real-time field data processing at scale. SAS Institute differentiates via specialized risk analytics modules purpose-built for reservoir uncertainty modeling.
Oil and gas analytics encompasses the systematic application of statistical algorithms, machine learning models, and distributed computing architectures to subsurface data, production telemetry, and supply chain flows—typically processing terabyte-scale time-series data from downhole sensors, SCADA networks, and seismic surveys to optimize recovery rates and minimize non-productive time. The technology segment shows Big Data Analytics and Machine Learning occupying the deepest margin pools due to proprietary algorithm development and subscription renewal dynamics, while Edge Computing represents the fastest-expanding layer as operators push inference closer to wellheads and pipelines to reduce latency in automated shutdown decisions. Predictive Analytics within solution offerings leads current deployment intensity because it directly correlates with reduced equipment failure costs and extended asset life.
The US EPA enforces methane monitoring mandates under revised Clean Air Act provisions, compelling operators to deploy continuous emissions analytics or face escalating penalties. The EU Green Deal's carbon border adjustment mechanism and the F-Gas Regulation jointly reshape market access by requiring granular emissions reporting across imported LNG and refined product streams. Stakeholders must monitor how divergent regulatory timelines between North American and European enforcement regimes influence platform standardization decisions and cross-border data governance architectures.
Market Dynamics
Predictive maintenance platforms are compressing operational decision cycles across upstream portfolios, forcing analytics vendors to re-architect delivery models around real-time inference at the wellhead rather than centralized cloud batch processing.
Growth Catalysts
- EPA Methane Monitoring Mandates:US operators must deploy continuous emissions analytics under revised Clean Air Act provisions, creating immediate procurement pull for compliance-integrated platforms.
- Permian Basin Data Density:Sensor proliferation across West Texas and New Mexico well pads generates terabyte-scale telemetry streams that demand automated pattern recognition.
- Digital Twin Convergence:Reservoir simulation models are fusing with production telemetry to enable physics-informed machine learning that extends asset life.
Market Restraints
- Specialized Talent Scarcity:Geoscientists with simultaneous subsurface domain expertise and machine learning engineering capabilities command premium compensation that inflates platform deployment costs.
- Legacy SCADA Integration Friction:Brownfield installations require expensive protocol translation layers to connect 1990s-era control systems with modern analytics architectures.
- Cybersecurity Insurance Burden:Underwriters are imposing stringent data governance requirements on operational technology networks that slow cloud migration timelines.
Strategic Opportunities
- Brazil Pre-Salt Digitalization:Petrobras and international partners are greenlighting analytics-heavy development programs across the Santos Basin that favor vendors with Portuguese-language support infrastructure.
- EU Carbon Border Adjustment:LNG exporters to European terminals must demonstrate granular emissions accountability, opening subscription revenue for supply-chain traceability modules.
- Edge-AI Hardware Maturation:NVIDIA Jetson and Qualcomm robotics platforms are enabling inference directly on offshore platforms without satellite bandwidth dependency.
Industry Challenges
- Subsurface Data Harmonization:Seismic, well log, and production datasets arrive in incompatible formats that consume 40-60% of project timelines before model training begins.
- Model Drift in Depleting Reservoirs:Production optimization algorithms trained on early-stage field behavior degrade in accuracy as reservoir pressure and fluid composition evolve.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oil and Gas Analytics Market |
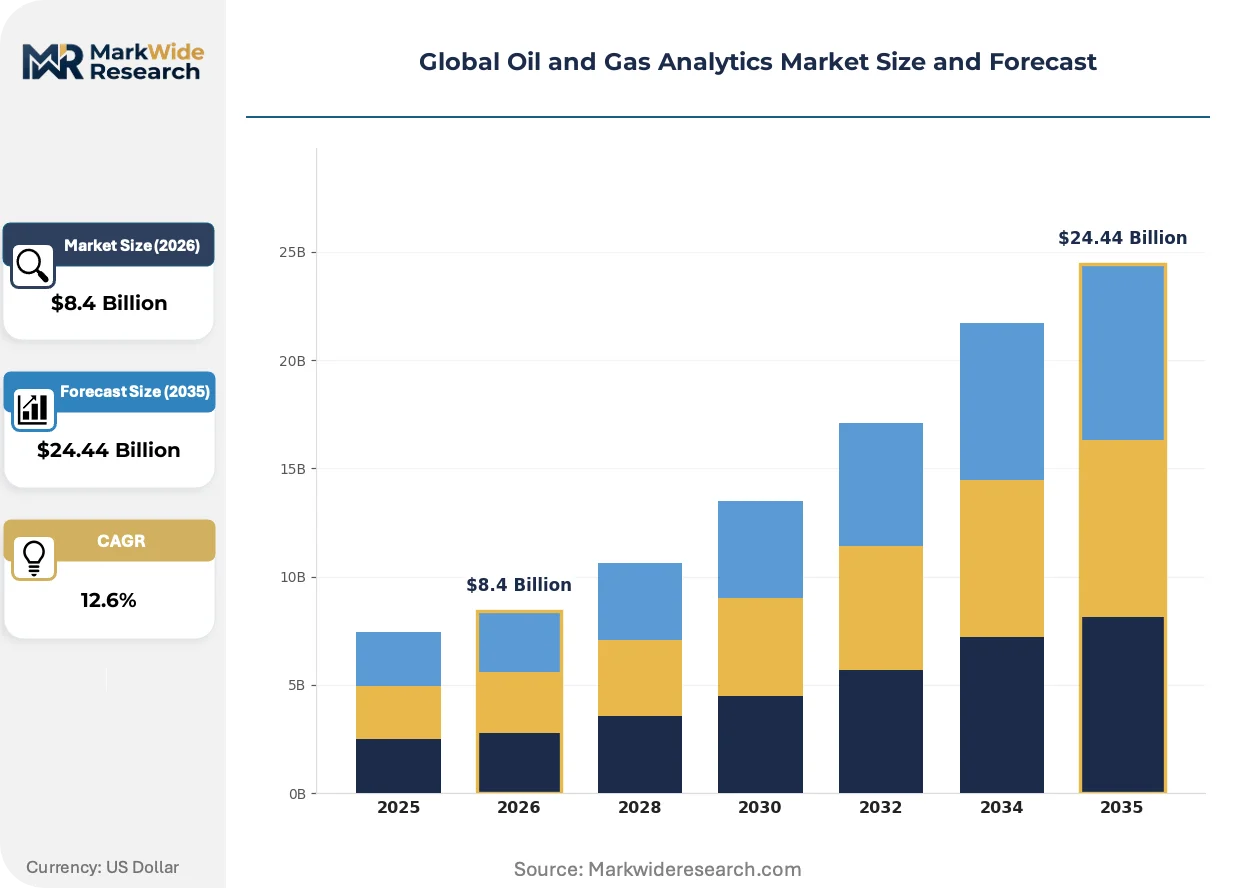
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $24.44 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Predictive Analytics, Real-Time Monitoring, Risk Management, Operational Optimization, Compliance Reporting, Asset Performance Technology: Big Data Analytics, Machine Learning, Cloud Computing, Artificial Intelligence, Data Visualization, Edge Computing Application: Exploration & Production, Reservoir Characterization, Drilling Optimization, Supply Chain Management, Health & Safety, Environmental Impact Assessment End User: Upstream Operators, Midstream Enterprises, Downstream Refineries, Equipment Suppliers, Engineering Firms, Research Organizations |
| Companies Covered | Tableau Software, Tibco Software, Hewlett Packard Enterprise, IBM, Cognizant, Hitachi, Teradata, SAS Institute, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oil and Gas Analytics Market Shifts & Advancements
Real-time inference architectures are migrating computation from hyperscale cloud regions to harsh-environment edge nodes, rewriting competitive advantage around latency tolerance and ruggedized hardware rather than raw algorithmic sophistication.
Edge-native analytics stacks are supplanting centralized cloud processing for automated shutdown decisions and leak detection scenarios. Supermajors operating North Sea platforms and Gulf of Mexico assets are deploying these systems at commercial scale. The shift compresses response latency from minutes to milliseconds while reducing satellite bandwidth costs that previously constrained offshore digitalization.
The EU F-Gas Regulation and carbon border adjustment mechanism are mandating emissions intensity documentation across imported LNG cargoes. European terminals now reject supply without certified methane leakage rates. This forces analytics vendors to embed blockchain-verified measurement trails into custody transfer documentation, with the Mediterranean and Baltic import markets driving specification urgency.
Subscription pricing for reservoir uncertainty modules is displacing perpetual license models that dominated 2010s procurement. Exploration teams at independent operators prefer operational expenditure treatment that aligns vendor compensation with discovery success. The model concentrates in US shale plays where drilling programs reset annually and capital allocation flexibility outweighs long-term asset ownership.
Global Oil and Gas Analytics Market Segmentation
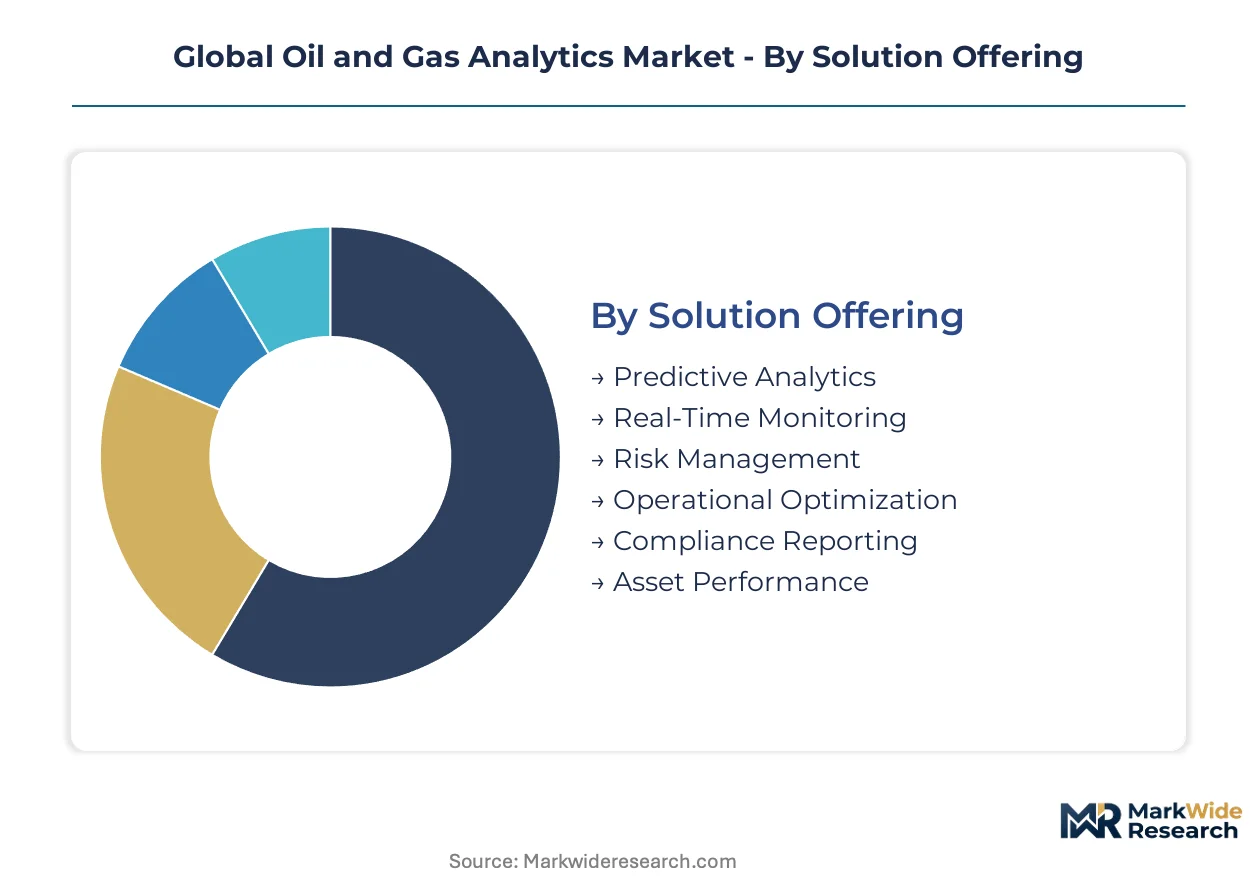
Analytics procurement in oil and gas fragments across solution maturity, infrastructure dependency, and operational risk tolerance. Vendors must architect modular platforms that span legacy SCADA environments through greenfield edge deployments without forcing rip-and-replace commitments.
Solution Offering:
Predictive Analytics faces displacement pressure from integrated asset performance suites that bundle forecasting with automated work order generation.
- Predictive Analytics:Algorithms process vibration spectra, thermal imaging, and fluid analysis to forecast equipment degradation windows. Demand concentrates among Permian Basin operators seeking to compress maintenance cycles on high-frequency pumping units. EPA methane monitoring mandates accelerate procurement for emissions anomaly prediction.
- Real-Time Monitoring:Dashboards aggregate SCADA telemetry, satellite imagery, and drone inspection feeds into unified operational views. North Sea platform operators deploy these systems to satisfy UK Health and Safety Executive requirements for simultaneous operations oversight.
- Risk Management:Quantifies reservoir uncertainty, commodity price exposure, and regulatory liability through Monte Carlo simulation frameworks.
- Operational Optimization:Production scheduling algorithms balance lift gas allocation, artificial lift efficiency, and export capacity constraints.
- Compliance Reporting:Automates emissions inventory compilation, incident documentation, and permit renewal submissions for EPA and EU Green Deal obligations.
- Asset Performance:Digital twin platforms fuse physics-based models with operational data to extend field life and optimize abandonment timing.
Predictive Analytics retains volume leadership; Asset Performance holds the steepest expansion curve.
Technology:
Margin concentration follows proprietary algorithm development, with Big Data Analytics and Machine Learning commanding premium pricing against commoditized visualization layers.
- Big Data Analytics:Distributed computing architectures process terabyte-scale seismic repositories and production time-series across multi-decade field histories. Brazilian pre-salt developments generate data volumes that demand Hadoop-scale infrastructure investments.
- Machine Learning:Deep learning models identify drilling dysfunctions, optimize completion designs, and predict production decline trajectories from sparse well control data. US shale operators deploy these tools to standardize best practices across dispersed asset portfolios.
- Cloud Computing:Hyperscale infrastructure delivers elastic compute for reservoir simulation and supply chain optimization workloads.
- Artificial Intelligence:Natural language processing extracts operational insights from unstructured maintenance logs and regulatory filings.
- Data Visualization:Geospatial rendering and immersive 3D environments translate complex subsurface models into decision-ready formats.
- Edge Computing:Ruggedized inference hardware executes automated shutdown decisions at wellhead latency without satellite bandwidth dependency.
Big Data Analytics commands the deepest margin pools; Edge Computing climbs the fastest as offshore latency requirements harden.
Application:
Exploration budgets fluctuate with commodity cycles, forcing vendors to diversify into production optimization and emissions compliance applications.
- Exploration & Production:Seismic interpretation, prospect ranking, and drilling target selection workflows integrate geophysical, geological, and petrophysical datasets. Norway's Johan Sverdrup field exemplifies full-field digitalization spanning exploration through late-life production.
- Reservoir Characterization:Stochastic modeling quantifies subsurface uncertainty to optimize infill drilling spacing and enhanced recovery sequencing. Middle East carbonate reservoirs demand specialized algorithms for fracture network characterization.
- Drilling Optimization:Real-time vibration analysis and rate-of-penetration modeling reduce non-productive time.
- Supply Chain Management:Logistics platforms coordinate rig movements, tubular deliveries, and product lift schedules across dispersed producing regions.
- Health & Safety:Computer vision monitors PPE compliance, confined space entry, and simultaneous operations conflicts.
- Environmental Impact Assessment:Spill trajectory modeling, habitat sensitivity mapping, and remediation planning tools satisfy project approval requirements.
Exploration & Production retains volume leadership; Environmental Impact Assessment gains share fastest under tightening EU and US regulatory timelines.
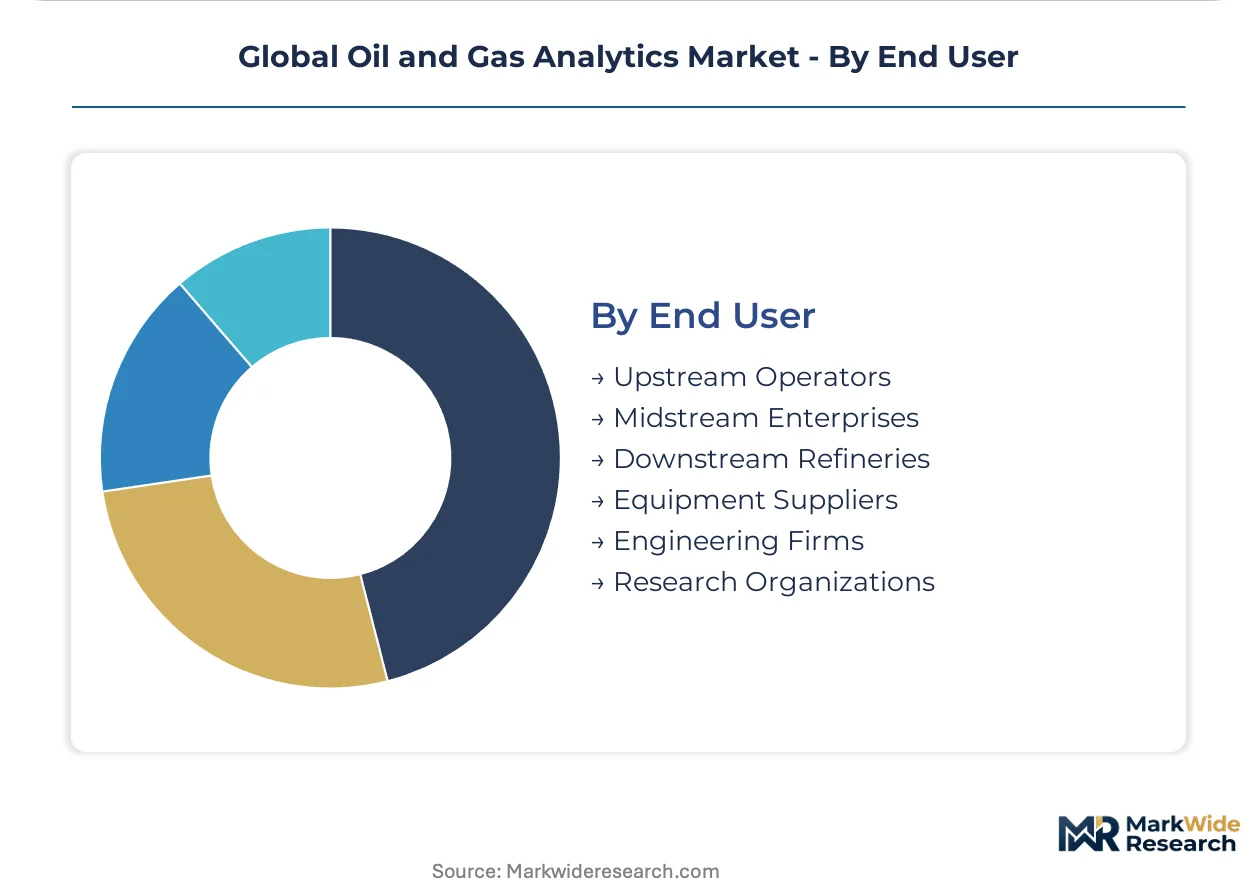
End User:
Upstream operators consolidate procurement authority, collapsing the distributed buying centers that once separated reservoir engineering from facilities maintenance.
- Upstream Operators:Supermajors and independents deploy enterprise analytics platforms across global asset portfolios, prioritizing predictive maintenance and emissions compliance. ExxonMobil's Permian digitalization program exemplifies integrated deployment at scale.
- Midstream Enterprises:Pipeline operators and terminal owners optimize throughput scheduling, integrity management, and custody transfer accuracy. US Gulf Coast LNG export terminals drive demand for supply-chain traceability modules.
- Downstream Refineries:Process optimization and yield analytics maximize conversion efficiency across complex fractionation trains.
- Equipment Suppliers:OEMs embed predictive diagnostics into rotating equipment and artificial lift systems to differentiate service offerings.
- Engineering Firms:EPC contractors leverage analytics to de-risk project execution and validate performance guarantees.
- Research Organizations:National laboratories and university consortia advance fundamental algorithms for subsurface imaging and multiphase flow prediction.
Upstream Operators retain volume leadership; Midstream Enterprises show the steepest procurement acceleration as LNG trade complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US LNG exporters to European terminals now face mandatory emissions documentation under the EU carbon border adjustment, reshaping analytics procurement on both sides of the Atlantic corridor. This trade-flow pressure cascades through production basins and import terminals alike.
United States
Permian Basin operators deploy predictive maintenance at scale across West Texas and New Mexico well pads, driven by EPA methane monitoring mandates under revised Clean Air Act provisions. The EPA enforces continuous emissions analytics requirements that carry escalating penalties for non-compliance. Houston anchors the vendor ecosystem, with supermajors integrating enterprise platforms across dispersed shale portfolios.
Brazil
Petrobras and international partners greenlight analytics-heavy development programs across the Santos Basin pre-salt fields, favoring vendors with Portuguese-language support infrastructure. The country's national petroleum regulator imposes stringent production optimization reporting for deepwater concessions. Rio de Janeiro concentrates the engineering procurement authority for these offshore digitalization investments.
Norway
Johan Sverdrup field operators deploy full-field digitalization spanning exploration through late-life production, integrating reservoir simulation with real-time telemetry. The Norwegian Petroleum Directorate mandates systematic emissions reporting and digital field documentation for all offshore licenses. Stavanger hosts the vendor engineering centers serving North Sea platform operators.
United Kingdom
North Sea platform operators satisfy UK Health and Safety Executive requirements through real-time monitoring dashboards aggregating SCADA telemetry and drone inspection feeds. The North Sea Transition Authority tightens emissions accountability timelines for aging basin infrastructure. Aberdeen concentrates the service provider ecosystem supporting simultaneous operations oversight.
Saudi Arabia
Aramco accelerates digital twin deployment across onshore and offshore assets, embedding physics-informed machine learning into reservoir management workflows. The Ministry of Energy imposes localization requirements that favor vendors with Riyadh-based implementation teams. The Eastern Province clusters the data science talent supporting these enterprise-scale deployments.
Global Oil and Gas Analytics Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and proprietary algorithm development. The vendor base organizes around three tiers: hyperscale cloud providers, specialized analytics boutiques, and integrated industrial automation houses. Strategic differentiation hinges on edge-native architecture versus centralized processing, and on subscription renewal rates versus perpetual license conversion. Competitive moves concentrate on M&A for subsurface domain expertise and strategic partnerships with national oil companies.
Within the enterprise software tier, IBM, Oracle, and SAS Institute exemplify divergent positioning strategies. IBM anchors enterprise-grade AI deployments through its Watson platform across supermajor portfolios. Oracle competes through integrated cloud infrastructure sustaining real-time field data processing at scale. SAS Institute occupies a specialized position via risk analytics modules purpose-built for reservoir uncertainty modeling.
| Leading Market Players |
|---|
| Tableau Software |
| Tibco Software |
| Hewlett Packard Enterprise |
| IBM |
| Cognizant |
| Hitachi |
| Teradata |
| SAS Institute |
| Oracle |
| Others |
Supply & Pricing Matrix
EPA methane monitoring mandates under revised Clean Air Act provisions gate both vendor qualification and price differentiation in upstream analytics procurement. Operators must deploy continuous emissions analytics to avoid escalating penalties, compressing the qualified vendor pool while segmenting pricing tiers by certification depth and real-time inference capability.
Pricing Analysis
Next-generation edge-native platforms command 40-60% subscription premiums over centralized cloud deployments due to ruggedized hardware requirements and sub-millisecond latency guarantees. Pricing stratifies across premium, standard, and economy tiers based on algorithm sophistication and after-sales implementation support. Cost compression in the standard tier is intensifying as hyperscale cloud providers bundle analytics modules with infrastructure contracts. Independent shale operators exhibit the highest price sensitivity, while supermajors prioritize performance guarantees over procurement cost.
Supply Chain Analysis
Satellite bandwidth constraints through trans-Atlantic and South Atlantic corridors tether offshore platform digitalization timelines to ground station capacity expansion in Brazil, Norway, and the US Gulf Coast. Hardware supply draws from Taiwan for edge-AI semiconductors, Germany for industrial sensors, and the US for ruggedized computing enclosures. Single-source vulnerability concentrates in NVIDIA Jetson module allocation for harsh-environment inference nodes. Distribution runs through Houston, Stavanger, and Rio de Janeiro engineering procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. EPA and EU Green Deal compliance requirements create switching costs that lock operators into certified platforms and resist vendor displacement.
For Market Incumbents: Consolidate subsurface domain expertise through targeted capability acquisition in reservoir uncertainty modeling and Portuguese-language support infrastructure for Brazil pre-salt expansion. Edge-AI hardware partnerships with NVIDIA and Qualcomm anchor switching cost architecture against cloud-native challengers. Certification maintenance for EPA and EU Green Deal emissions modules defends renewal rates. For New Entrants and Emerging Players: Anchor in midstream LNG supply-chain traceability modules where EU carbon border adjustment documentation creates immediate procurement pull with lower technical barriers than upstream reservoir analytics. Environmental Impact Assessment applications for European terminals represent the most penetrable segment. Go-to-market leverage rests on blockchain-verified measurement trail integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across edge-native hardware deployment as inference moves to wellhead processors and satellite bandwidth dependency diminishes. Target acquisition archetypes include specialized risk analytics boutiques with reservoir uncertainty modules and Portuguese-language implementation teams. The signal to watch is Petrobras procurement authorization velocity for Santos Basin digitalization programs.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Hardware Partnership | NVIDIA Jetson integration enables sub-millisecond automated shutdown decisions offshore Brazil. |
| Portuguese-Language Support Buildout | Localization capability unlocks Petrobras procurement authorization for Santos Basin programs. |
| Blockchain Emissions Verification | EU carbon border adjustment compliance secures LNG terminal subscription revenue in Mediterranean markets. |
| Reservoir Uncertainty Module Acquisition | Monte Carlo simulation expertise defends margin position against integrated asset performance suites. |
| Legacy SCADA Protocol Translation | Brownfield integration capability captures Permian Basin operator procurement for 1990s-era control systems. |
Research Methodology
Operator-level perspectives from upstream digitalization officers, reservoir engineering directors, SCADA integration specialists, and emissions compliance managers anchored the qualitative base. Primary interview findings triangulated against secondary validation from EPA enforcement databases, EU ETS transaction registries, Petrobras procurement disclosures, and Norwegian Petroleum Directorate field development approvals. Bottom-up segment sizing crossed with top-down macroeconomic anchoring across the analysis window.
Sensitivity analysis tested forecast robustness across commodity price scenarios, regulatory enforcement intensity variations, and technology substitution curves. Segmentation dimensions modeled include solution maturity tier, infrastructure dependency level, deployment latency requirement, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates, with cross-checks against vendor subscription renewal disclosures and national oil company capex allocation patterns.
Decision-makers should treat outputs as directional under sustained EPA enforcement and EU Green Deal implementation timelines; material deviation in regulatory stringency or commodity price recovery would warrant model refresh. Practitioners should keep alternative scenarios live as Brazil pre-salt authorization velocity and edge-AI hardware cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Pumpjack Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Underreamers Market
Oil & Gas
Egypt Oil and Gas Midstream Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Digital Drilling Rigs Market