
 Global Nosql Database Market | 2026-2036
Global Nosql Database Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nosql Database Market Foresight
ISO/IEC 27001 certification for information security management is bifurcating the competitive landscape into qualified and non-qualified vendors. MongoDB, Inc. leverages its document store architecture to anchor enterprise developer mindshare across cloud-native deployments. Amazon Web Services competes through integrated managed database services that extend its infrastructure dominance. Microsoft Corporation differentiates by embedding NoSQL capabilities within its broader enterprise software ecosystem.
NoSQL databases are non-relational data management systems engineered to handle unstructured, semi-structured, and high-velocity data across distributed architectures, typically employing horizontal scaling, flexible schema design, and eventual consistency models to support petabyte-scale workloads. Their primary commercial purpose centers on enabling real-time applications, big data analytics, and operational intelligence where rigid relational schemas impose latency or scalability constraints. Document store deployments capture the largest revenue pool as enterprises migrate legacy content management systems, while graph database adoption accelerates fastest within fraud detection and recommendation engine use cases where relationship traversal performance determines system value. Cloud-based deployment continues displacing on-premises installations as multi-cloud strategies mature.
The EU AI Act imposes algorithmic transparency mandates that reshape how graph databases process personal data for automated decision-making, while GDPR data localization rules restrict cross-border replication of key-value stores holding European citizen records. In the United States, NIST cybersecurity frameworks and SEC disclosure requirements for material cyber incidents tighten operational standards for database vendors serving regulated industries. China’s GB standards for data security and MIIT cloud service certifications create parallel compliance tracks for vendors operating in that jurisdiction. Stakeholders must monitor diverging sovereignty requirements as jurisdictions harden data residency rules without harmonized interoperability standards.
Market Dynamics
ISO/IEC 27001 certification requirements are bifurcating the competitive landscape into qualified and non-qualified vendors, forcing database providers to restructure compliance investments or exit regulated verticals entirely.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Financial services firms in Germany and France accelerate graph database deployments for explainable fraud detection systems that satisfy automated decision-making audit requirements.
- Cloud-native application architectures:Developer teams across enterprise software and fintech sectors demand document stores that integrate with Kubernetes orchestration and serverless compute frameworks.
- GDPR data localization enforcement:Key-value store providers establish sovereign cloud instances within EU member states to retain European enterprise contracts facing cross-border replication restrictions.
Market Restraints
- Distributed systems engineering talent scarcity:Implementation of eventually consistent architectures requires specialized site reliability engineers commanding premium compensation in competitive labor markets.
- Multi-cloud data egress cost volatility:Enterprises face unpredictable bandwidth charges when replicating document stores across AWS, Azure, and Google Cloud Platform regions.
- Relational database substitution inertia:Legacy Oracle and Microsoft SQL Server installations persist in transactional workloads where ACID guarantees remain non-negotiable.
Strategic Opportunities
- Edge computing database nodes:Industrial IoT deployments in manufacturing facilities require time-series capable NoSQL engines that synchronize with central analytics platforms.
- Quantum-resistant encryption standards:NIST post-quantum cryptography guidelines create replacement demand for database encryption modules in government and defense sectors.
- Healthcare FHIR data interoperability:HIPAA-compliant document stores capture patient record modernization budgets as US health systems retire proprietary EHR data models.
Industry Challenges
- Schema migration complexity:Enterprises struggle to refactor semi-structured data pipelines when upgrading from deprecated database versions without application downtime.
- ISO/IEC 27001 certification timelines:Mid-sized vendors face 12-18 month audit cycles that delay entry into financial services and government procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nosql Database Market |
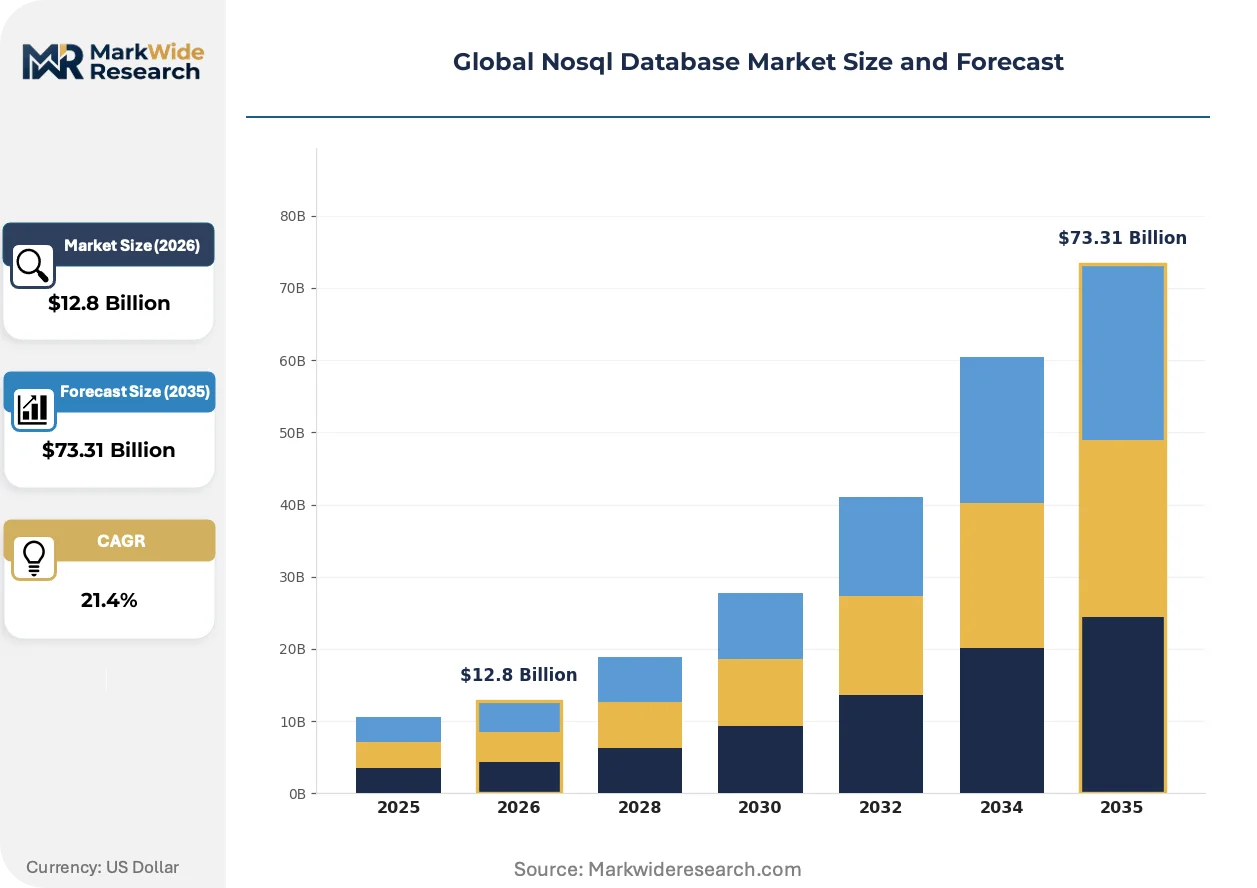
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $73.31 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Cloud Database Type: Document Store, Key-Value Store, Graph Database, Column Store Industry Vertical: Telecommunications, Media & Entertainment, Government, Education Use Case: Real-Time Analytics, Content Management, Fraud Detection, IoT Data Management |
| Companies Covered | MongoDB, Inc., Amazon Web Services, Microsoft Corporation, Google LLC, Couchbase, Inc., DataStax, Oracle Corporation, Aerospike, Inc., Redis Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nosql Database Market Shifts & Advancements
Vector database architectures are attracting venture funding and engineering talent as generative AI applications demand low-latency similarity search capabilities at billion-scale embedding dimensions.
Native vector indexing is bifurcating the document store category. Purpose-built vector databases such as Pinecone and Weaviate target AI-first startups requiring sub-100ms retrieval latency for recommendation engines. Established document stores respond by embedding approximate nearest neighbor search into existing JSON storage engines. Financial services firms in Singapore and London pilot hybrid architectures that route transactional queries to document stores while isolating embedding workloads to specialized vector substrates.
REACH chemical substance restrictions indirectly reshape database hardware procurement. EU-based cloud providers face compliance costs when sourcing rare earth elements for solid-state storage arrays deployed in Amsterdam and Frankfurt data centers. Database vendors serving European enterprises increasingly specify hardware supply chain documentation to satisfy downstream customer ESG reporting obligations under CSRD corporate sustainability rules.
Consumption-based pricing models disrupt traditional perpetual licensing. Enterprise procurement teams negotiate committed use contracts that blend reserved capacity with burst pricing for unpredictable analytics workloads. This shift compresses vendor cash conversion cycles while transferring infrastructure risk to database providers. SaaS-native vendors in the United States and Israel capture market share from incumbents clinging to term-based subscription structures.
Global Nosql Database Market Segmentation
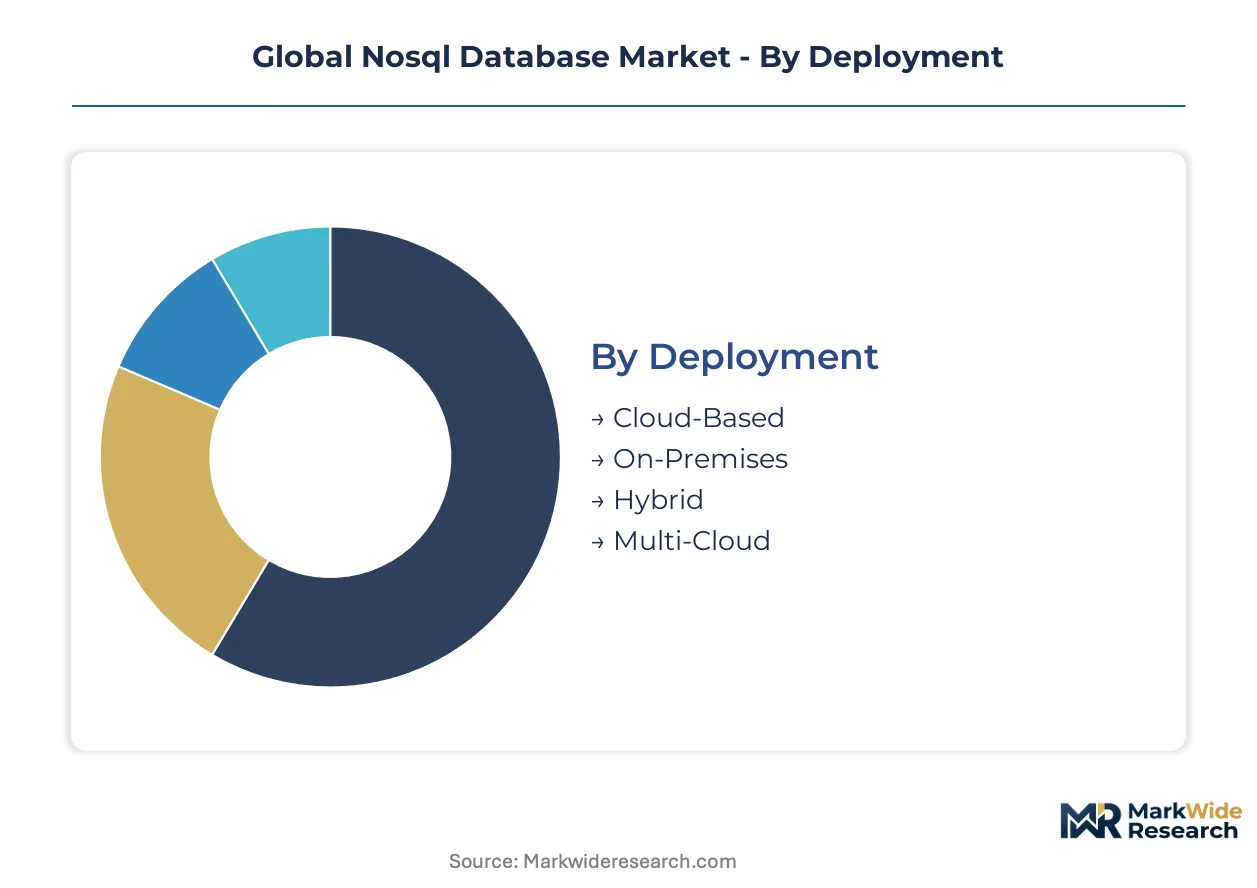
NoSQL database purchasing decisions hinge on deployment sovereignty requirements and workload-specific performance characteristics. Buyers evaluate schema flexibility, consistency guarantees, and regulatory alignment before committing to specific architectural patterns.
Deployment:
GDPR data localization mandates and NIST cybersecurity frameworks drive divergence between qualified and non-qualified infrastructure configurations.
- Cloud-Based:Managed services eliminate operational overhead for Kubernetes-orchestrated applications. Financial services firms in Singapore and Germany favor sovereign cloud instances to satisfy MiFID II and GDPR audit trails without maintaining physical data centers.
- On-Premises:Air-gapped installations serve defense contractors and classified government workloads where internet connectivity remains prohibited. China's GB standards for data security reinforce domestic procurement preferences for hardware-controlled environments.
- Hybrid:Split architectures route sensitive transactions to private infrastructure while bursting analytics workloads to public cloud. Manufacturing conglomerates in Japan deploy hybrid configurations to balance METI data governance with elastic compute requirements.
- Multi-Cloud:Replication across AWS, Azure, and Google Cloud Platform mitigates vendor lock-in for enterprise software vendors serving multinational clients. Egress cost unpredictability constrains adoption despite architectural flexibility.
Cloud-Based deployments handle the majority of throughput; Multi-Cloud is expanding most quickly on share as procurement teams negotiate cross-provider resilience.
Database Type:
Query pattern economics separate high-velocity transactional engines from relationship-intensive analytical substrates.
- Document Store:JSON-native storage with flexible schema evolution supports content management system migrations. Healthcare systems in the United States deploy HIPAA-compliant document stores for FHIR-formatted patient records.
- Key-Value Store:Sub-millisecond latency retrieval powers session management and caching tiers. E-commerce platforms in India leverage key-value architectures during festive shopping surges under RBI digital payment infrastructure guidelines.
- Graph Database:Native relationship traversal accelerates fraud detection and recommendation engines. EU AI Act transparency requirements push French and German banks toward explainable graph-based risk scoring.
- Column Store:Compressed columnar formats optimize analytical aggregation across petabyte-scale time-series. Industrial IoT deployments in South Korea feed sensor streams into column stores for MFDS-regulated pharmaceutical manufacturing monitoring.
Document Store captures the dominant revenue position; Graph Database is climbing the fastest as algorithmic accountability mandates proliferate.
Industry Vertical:
Data sovereignty sensitivity varies sharply across sectors with diverging regulatory exposure profiles.
- Telecommunications:Subscriber data retention laws in Brazil and Saudi Arabia compel localized NoSQL deployments for call detail record analytics. TRAI and CITC frameworks impose divergent encryption standards.
- Media & Entertainment:Content personalization engines require low-latency document stores for real-time recommendation serving. Streaming platforms in the United Kingdom navigate Ofcom content moderation alongside GDPR subscriber privacy.
- Government:Classified and unclassified network separation drives hybrid procurement patterns. FedRAMP authorization gates access to federal cloud contracts in the United States.
- Education:Student information systems migrate from legacy relational schemas to flexible document models. FERPA compliance requirements shape encryption and access control specifications for US institutions.
Telecommunications carries the heaviest infrastructure investment; Government verticals are gaining share fastest as classified workload modernization accelerates.
Use Case:
Latency tolerance and consistency requirements dictate database selection across operational and analytical workloads.
- Real-Time Analytics:Stream processing architectures demand in-memory capable NoSQL engines with sub-second ingestion-to-query pipelines. Capital markets firms in London deploy real-time analytics for MiFID II best execution reporting.
- Content Management:Versioned document storage with full-text indexing supports enterprise knowledge bases. Media organizations in Canada migrate from proprietary ECM platforms under PIPEDA data handling constraints.
- Fraud Detection:Graph traversal and pattern matching identify anomalous transaction networks. Australian banks integrate AUSTRAC reporting requirements with real-time graph-based suspicious activity monitoring.
- IoT Data Management:Time-series optimized storage ingests high-velocity sensor streams from distributed device fleets. Manufacturing facilities in Germany align Industry 4.0 data architectures with TISAX information security certification.
Real-Time Analytics processes the largest query volumes; Fraud Detection is expanding most rapidly as regulatory scrutiny of automated decision-making intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in financial services, telecommunications, and cloud infrastructure sectors drive geographic demand concentration across sovereign cloud deployments and regulated data center expansions.
United States
Capital markets firms in New York and Chicago deploy graph databases for SEC-mandated transaction surveillance and best execution reporting. FedRAMP authorization gates access to federal cloud contracts for database vendors serving classified workloads. Seattle and Northern Virginia data center clusters anchor multi-cloud replication strategies for SaaS providers managing cross-border enterprise clients.
China
Domestic cloud operators expand managed NoSQL services under MIIT certification requirements for financial technology and industrial IoT applications. GB standards for data security enforce hardware-controlled environments for state-owned enterprise deployments. Beijing and Shenzhen technology corridors concentrate engineering talent for distributed database development serving domestic e-commerce platforms.
Germany
Automotive manufacturers in Stuttgart and Munich adopt time-series NoSQL engines for Industry 4.0 sensor analytics under TISAX information security certification. EU AI Act transparency mandates push Frankfurt banking consortia toward explainable graph-based risk scoring systems. Sovereign cloud instances in Frankfurt and Berlin retain European enterprise contracts facing GDPR cross-border replication restrictions.
Singapore
Wealth management firms deploy hybrid architectures routing transactional queries to document stores while isolating AI embedding workloads to specialized vector substrates. Monetary Authority of Singapore technology risk management guidelines shape database encryption specifications for private banking clients. Marina Bay and Jurong data center clusters serve as regional hubs for multi-cloud strategies targeting Southeast Asian expansion.
United Kingdom
London capital markets firms pilot real-time analytics pipelines for MiFID II regulatory reporting using stream-processing NoSQL architectures. Ofcom content moderation requirements alongside GDPR subscriber privacy shape streaming platform database procurement. The City and Canary Wharf financial districts concentrate demand for low-latency fraud detection graph deployments.
Global Nosql Database Market Competitive Landscape
Player mix skews toward hyperscale cloud providers with infrastructure-integrated managed services, document store specialists with developer ecosystem anchoring, and legacy relational vendors with hybrid portfolio extensions. Strategic archetypes separate infrastructure-dominant platforms, schema-flexibility champions, and compliance-forward sovereign specialists. Competitive moves center on multi-cloud federation partnerships and ISO/IEC 27001 certification acceleration to capture regulated vertical procurement channels.
Within the infrastructure-integrated tier, Amazon Web Services and Microsoft Corporation exemplify platform economics that bundle database services with compute and storage primitives. MongoDB, Inc. occupies a position as the document store archetype, anchoring developer mindshare through cloud-native deployment patterns. These three entities collectively represent the competitive fault lines between infrastructure dominance, architectural specialization, and ecosystem embedding that structure procurement decisions across enterprise segments.
| Leading Market Players |
|---|
| MongoDB, Inc. |
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| Couchbase, Inc. |
| DataStax |
| Oracle Corporation |
| Aerospike, Inc. |
| Redis Labs |
| Others |
Supply & Pricing Matrix
Hyperscale cloud infrastructure utilization rates above eighty percent compress marginal compute costs for managed database services, concentrating pricing power among AWS, Azure, and Google Cloud while forcing independent software vendors toward specialized value-added tiers or sovereign cloud partnerships to defend margin structures.
Pricing Analysis
Consumption-based contracts indexed to committed use thresholds dominate enterprise procurement, with reserved capacity blending into burst pricing for unpredictable analytics workloads. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized sovereign instances from multi-tenant managed services and self-hosted community editions. Pricing pressure stems from hyperscale providers bundling database services below standalone cost, compressing vendor cash conversion cycles. Financial services and government verticals show lowest price sensitivity due to compliance mandates, while mid-market SaaS vendors face acute cost compression.
Supply Chain Analysis
United States and China anchor semiconductor fabrication for database acceleration hardware, with Taiwan producing advanced GPUs for vector indexing workloads. Rare earth element supply for solid-state storage arrays draws from Chinese processing facilities and Australian mining operations, creating tariff exposure under REACH chemical substance restrictions. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams, with channel partners serving regulated verticals requiring ISO/IEC 27001 certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global NoSQL Database Market sits in early-cycle expansion as EU AI Act transparency mandates and GDPR data localization rules force replacement demand across European financial services infrastructure, opening penetration opportunities before saturation economics take hold.
For Market Incumbents: Secure FedRAMP and ISO/IEC 27001 certification acceleration to capture classified government procurement channels, while embedding native vector indexing capabilities to defend against purpose-built AI database entrants. Backward integration into sovereign cloud hardware partnerships mitigates supply chain exposure from Chinese rare earth processing concentration.
For New Entrants and Emerging Players: Anchor in healthcare FHIR interoperability modernization as US health systems retire proprietary EHR schemas, targeting mid-sized hospital networks underserved by incumbent document store pricing. Edge computing database nodes for German automotive Industry 4.0 deployments offer a second white-space entry point through TISAX-certified channel partnerships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-forward sovereign specialists with established EU data residency infrastructure over undifferentiated multi-tenant SaaS vendors. Watch for inflection signals in quantum-resistant encryption module replacement demand as NIST post-quantum cryptography guidelines propagate through government and defense procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | FedRAMP authorization gates federal contracts while GDPR instances retain European enterprise relationships. |
| Native Vector Indexing Embedding | Document stores integrate approximate nearest neighbor search to counter purpose-built AI database competition. |
| Multi-Cloud Federation Partnership | Cross-provider replication mitigates vendor lock-in for SaaS vendors serving multinational clients. |
| Quantum-Resistant Encryption Module | NIST post-quantum cryptography guidelines drive replacement demand in government and defense sectors. |
| Healthcare FHIR Data Interoperability | HIPAA-compliant document stores capture patient record modernization budgets from retiring proprietary EHR systems. |
Research Methodology
Desk research of hyperscaler capex disclosures, SEC database vendor filings, and EU regulatory frameworks preceded structured interviews with CTOs at financial services firms, platform engineers at cloud-native enterprises, and procurement officers at healthcare systems. Primary fieldwork combined with secondary validation from ISO certification databases and sovereign cloud infrastructure announcements. Bottom-up deployment modeling and top-down vertical spending analysis provided triangulation across the analysis window.
Variance decomposition across deployment models, database types, and regulatory jurisdiction clusters shaped the analytical framework throughout the forecast period. CAGRs derived from elasticity-adjusted adoption curves incorporating GDPR enforcement intensity and AI Act implementation timelines. Industry-specific inputs included Kubernetes orchestration penetration rates and graph database fraud detection deployment velocity in EU banking consortia.
Material uncertainties — sovereign cloud hardware sourcing restrictions, quantum cryptography standard finalization, and distributed systems engineering labor availability — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory harmonization failure and multi-cloud egress cost stabilization. Recalibration cycles align with material shifts in EU AI Act audit requirement enforcement and NIST cybersecurity framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America IT Services Market
Software & Services
Background Removal Software Market
Software & Services
Home Design Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Business Email Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Global Survey Software Market
Software & Services
Photobooth Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Commercial Drone Software Market
Software & Services
Lab Automation Software Market
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Batch Management Software Market