
 Batch Management Software Market | 2026-2036
Batch Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Batch Management Software Market Analysis
FDA 21 CFR Part 11 is consolidating the cost-of-entry calculus for batch management software vendors serving regulated industries. Siemens sustains technology leadership through its SIMATIC BATCH platform and deep automation integration. Rockwell Automation leverages its FactoryTalk Batch suite to anchor position in North American pharmaceutical and food processing installations. AVEVA competes through unified engineering and operations software that extends lifecycle data management across batch-centric facilities.
Batch management software governs the sequencing, execution, and documentation of discrete production runs in process manufacturing, typically interfacing with distributed control systems through ISA-88 batch control standards to enforce recipe compliance and material genealogy. Its primary commercial purpose centers on eliminating paper batch records, reducing cycle times, and enabling real-time release decisions in FDA-regulated environments. Cloud-based deployment models are capturing the fastest expansion as chemical and cosmetics producers prioritize remote accessibility and reduced infrastructure overhead, while on-premise installations retain dominance in pharmaceutical settings where data residency requirements and validated system constraints preserve margin pools for specialized integrators.
FDA enforces electronic records and signatures through 21 CFR Part 11, directly shaping software validation requirements and vendor qualification protocols for U.S. pharmaceutical and food facilities. EMA's GMP Annex 11 and the EU AI Act collectively tighten data integrity and algorithmic transparency standards for batch systems deployed across European manufacturing networks. Stakeholders must monitor how converging FDA, EMA, and emerging Saudi SFDA digitalization mandates reshape platform architecture roadmaps and regional compliance module development priorities.
Market Dynamics
Cloud-native batch management architectures are compressing deployment cycles and eroding the validated-system moat that historically protected on-premise incumbents in pharmaceutical manufacturing.
Growth Catalysts
- EMA GMP Annex 11:European pharmaceutical facilities are accelerating electronic batch record adoption to satisfy data integrity requirements. German chemical manufacturers are standardizing platforms across multi-site operations.
- Continuous processing:Biologics manufacturers are retrofitting batch software to support hybrid batch-continuous workflows. This creates pull for advanced process control modules.
- Saudi SFDA digitalization:The kingdom's pharmaceutical regulator is mandating electronic submission of batch records. Domestic manufacturers are procuring compliant systems ahead of enforcement deadlines.
Market Restraints
- Validation cost structure:FDA 21 CFR Part 11 compliance requires extensive IQ/OQ/PQ documentation. Small and mid-sized pharmaceutical contract manufacturers face disproportionate qualification burdens.
- Specialized integrator concentration:Validated system deployment depends on a narrow pool of GAMP 5-certified implementation partners. North American and European integrators command premium rates.
- Legacy DCS lock-in:Proprietary communication protocols in existing distributed control systems constrain batch software substitution. Migration projects require hardware refresh cycles.
Strategic Opportunities
- India pharmaceutical corridor:CDSCO is aligning with ICH Q9 quality guidelines. Domestic formulation exporters are investing in FDA-inspection-ready batch documentation systems.
- AI-enabled release decisions:Machine learning algorithms for real-time batch release are converging with traditional recipe management. Early adopters are compressing quality control cycle times.
- EU AI Act transparency requirements:Algorithmic decision-making in batch release will require explainability documentation. Vendors developing audit-ready AI modules will capture first-mover advantage.
Industry Challenges
- GAMP 5 validation expertise:Pharmaceutical manufacturers report acute shortages of computer system validation engineers. Training pipelines have not kept pace with software refresh cycles.
- Multi-site harmonization:Global chemical producers struggle to standardize batch recipes across facilities with varying DCS vintages. Corporate IT organizations are absorbing unplanned integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Batch Management Software Market |
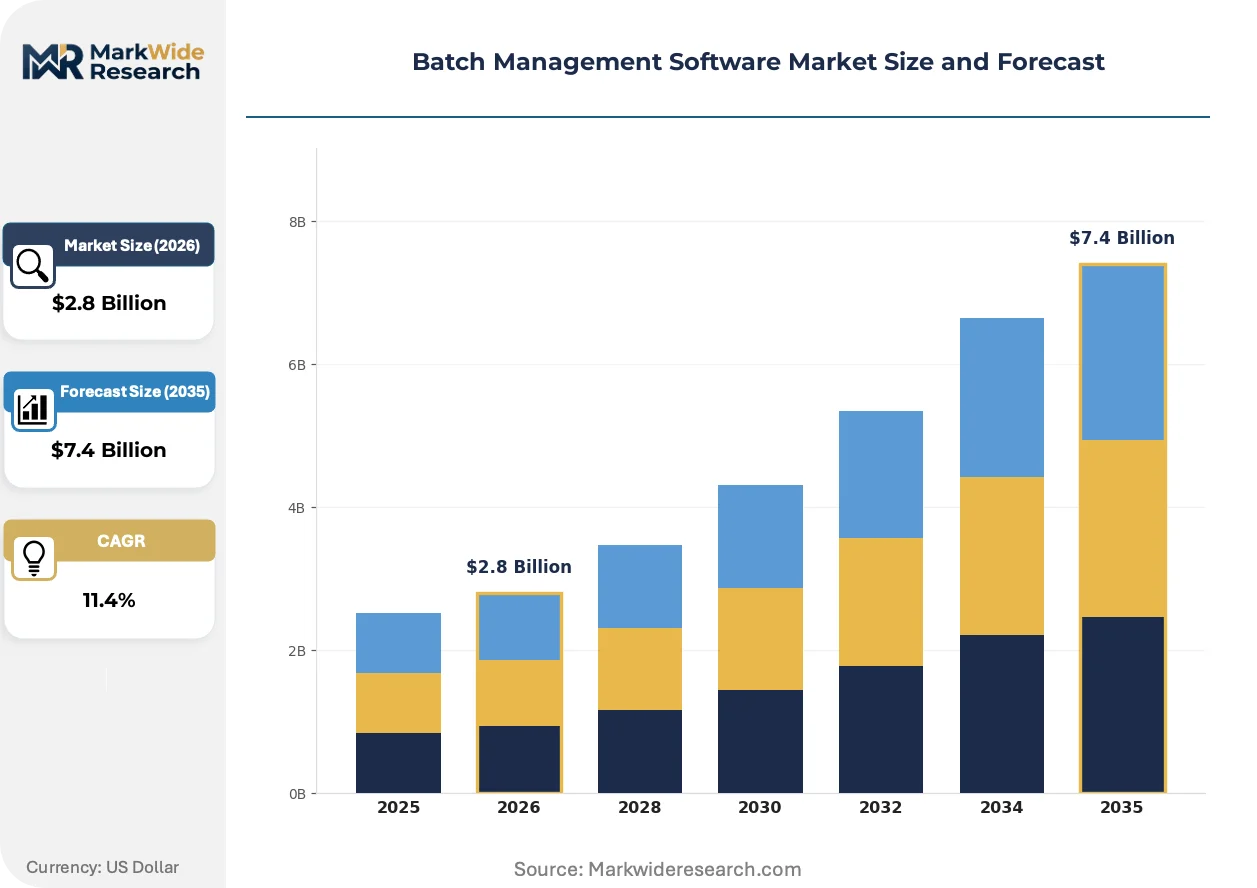
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Mobile End User: Food & Beverage, Pharmaceuticals, Chemicals, Cosmetics Deployment Model: Private Cloud, Public Cloud, Multi-Tenant, Single-Tenant Feature: Inventory Management, Quality Control, Compliance Tracking, Reporting |
| Companies Covered | Rockwell Automation, Siemens, ABB, Emerson Electric, Honeywell, SAP, Schneider Electric, General Electric, AVEVA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Batch Management Software Market Emerging Trajectories
Digital twin technology is migrating from asset management into batch execution, enabling virtual commissioning of recipe modifications before physical deployment.
Containerized microservices architectures are expanding into regulated manufacturing environments. Pharmaceutical quality assurance teams are piloting modular batch applications that isolate recipe steps into independently validated containers. This architecture is compressing change control timelines from months to weeks.
FDA's draft guidance on computer software assurance is reshaping validation economics for pharmaceutical batch systems. The regulator is explicitly permitting unscripted testing for lower-risk software functions. Mid-sized generic drug manufacturers are reallocating validation resources toward critical process parameters.
Subscription-based licensing is displacing perpetual purchase models in mid-market chemical processing. Plant engineering managers are prioritizing operational expenditure treatment over capital approval cycles. This preference shift is most visible in specialty chemical clusters across Germany and the Netherlands.
Batch Management Software Market Segmentation
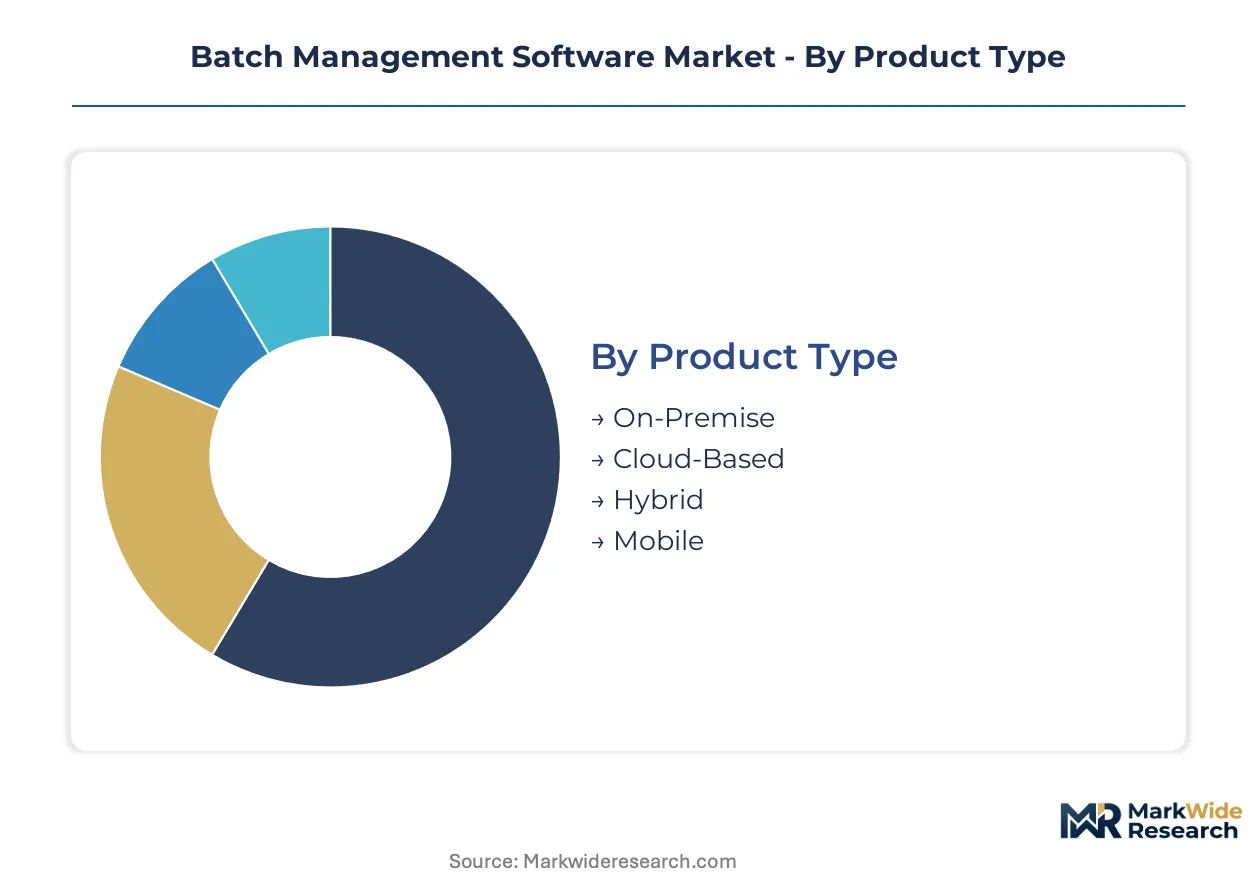
Batch management software segmentation reveals how deployment architecture, regulatory intensity, and operational scale reshape vendor product roadmaps. Pharmaceutical manufacturers demand validated on-premise systems while chemical producers prioritize cloud elasticity for multi-site coordination.
Product Type:
Deployment architecture determines validation burden, infrastructure ownership, and upgrade cadence across regulated manufacturing environments.
- On-Premise:Installed within facility data centers with full hardware control. FDA-regulated pharmaceutical plants in the United States and Germany retain this model to satisfy 21 CFR Part 11 data residency requirements and audit trail sovereignty.
- Cloud-Based:Delivered through vendor-managed infrastructure with subscription economics. Specialty chemical manufacturers in the Netherlands and cosmetics producers in France are migrating here to eliminate capital expenditure cycles and enable remote engineering access.
- Hybrid:Combines local execution engines with cloud-based analytics and reporting layers. Mid-sized contract manufacturers use this to keep batch records on-site while pushing performance dashboards to corporate headquarters.
- Mobile:Native applications for tablet and smartphone interfaces enabling floor-level recipe adjustments and exception handling. Food processing facilities with distributed production lines are piloting these for real-time operator alerts.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
End User:
Industry verticals impose distinct compliance regimes, batch complexity, and integration depth requirements that fragment vendor specialization.
- Pharmaceuticals:Governed by FDA 21 CFR Part 11 and EMA GMP Annex 11 with mandatory electronic batch records and signature workflows. German and Swiss facilities drive platform standardization across multi-site operations.
- Chemicals:ISA-88 batch control standards dominate with emphasis on recipe flexibility and material genealogy for hazardous substance tracking. BASF and Bayer operations in Germany's chemical corridor anchor demand for unified engineering environments.
- Food & Beverage:USDA and FDA Food Safety Modernization Act requirements shape traceability needs. Large-scale dairy and beverage processors in the United States prioritize lot tracking and allergen management modules.
- Cosmetics:EU Cosmetics Regulation and emerging Saudi SFDA mandates drive documentation investments. French and Italian personal care manufacturers are retrofitting legacy systems for electronic record compliance ahead of enforcement deadlines.
Validation complexity peaks in Pharmaceuticals. Fastest feature adoption is occurring in Cosmetics.
Deployment Model:
Tenancy structure and cloud ownership models segment infrastructure risk allocation and customization latitude.
- Private Cloud:Dedicated infrastructure hosted on-premises or through single-tenant colocation. Pharmaceutical manufacturers with validated system requirements favor this for environmental control and change management autonomy.
- Public Cloud:Shared infrastructure with vendor-managed security and availability. German mid-market chemical processors are expanding here to compress deployment timelines and shift operational expenditure treatment.
- Multi-Tenant:Shared software instances with logical data separation between customers. Cosmetics and smaller food producers accept this trade-off for lower per-seat pricing and automatic feature updates.
- Single-Tenant:Isolated software instances per customer with dedicated database and compute resources. Biologics manufacturers requiring GAMP 5 validation documentation prefer this for audit scope clarity.
Enterprise pharmaceutical demand anchors Single-Tenant. Public Cloud is climbing the fastest among cost-conscious chemical processors.
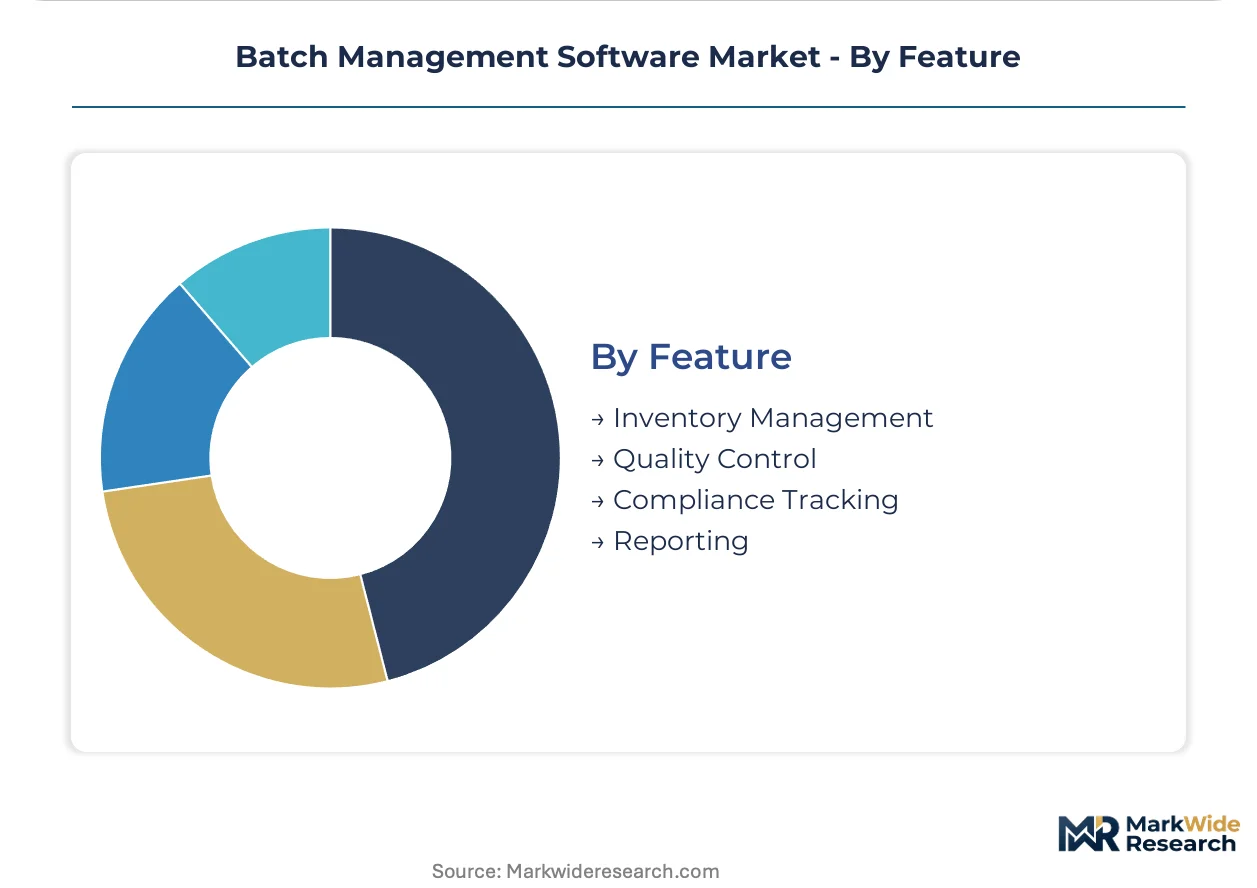
Feature:
Functional modules align with specific operational pain points across quality assurance, supply chain, and regulatory submission workflows.
- Compliance Tracking:Automated audit trails, electronic signatures, and deviation management for FDA, EMA, and Saudi SFDA submissions. Pharmaceutical quality assurance teams treat this as non-negotiable infrastructure.
- Quality Control:In-process testing integration, specification enforcement, and out-of-specification handling. Biologics manufacturers leverage this for real-time release decisions and reduced quarantine inventory.
- Inventory Management:Material genealogy, lot traceability, and warehouse integration for just-in-time production. Food and beverage processors use this to manage perishable ingredient flows and allergen segregation.
- Reporting:Customizable dashboards, regulatory submission templates, and performance analytics. Chemical operations managers deploy this for OEE tracking and energy consumption optimization across German multi-site networks.
Compliance Tracking dominates pharmaceutical procurement. Quality Control is gaining share fastest as AI-enabled release decisions mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's chemical corridor and India's pharmaceutical clusters concentrate batch management software procurement through tax-advantaged manufacturing hubs. These zones attract validated system deployments by bundling infrastructure incentives with regulatory fast-tracking.
United States
FDA 21 CFR Part 11 enforcement drives pharmaceutical facility upgrades across New Jersey and North Carolina clusters. The regulator's computer software assurance draft guidance reduces validation burdens for lower-risk functions. Boston's biologics corridor accelerates hybrid cloud deployments for real-time release decisions.
Germany
BASF and Bayer operations anchor demand for unified engineering platforms across Ludwigshafen and Leverkusen sites. EMA GMP Annex 11 data integrity requirements push mid-sized chemical processors toward standardized multi-site architectures. The country's chemical corridor leads European adoption of ISA-88 compliant batch control systems.
India
CDSCO alignment with ICH Q9 guidelines pressures Hyderabad and Ahmedabad formulation exporters toward FDA-inspection-ready documentation. The country's pharmaceutical special economic zones offer accelerated depreciation for electronic batch record investments. Domestic contract manufacturers face compressed timelines to satisfy Saudi SFDA digitalization mandates for export markets.
Saudi Arabia
SFDA electronic submission mandates for batch records trigger procurement waves among domestic pharmaceutical manufacturers. The kingdom's Vision 2030 industrial clusters attract validated system integrators to Riyadh and Jeddah production zones. Government procurement preferences favor platforms with pre-configured Arabic-language compliance modules.
China
NMPA data integrity guidelines reshape batch documentation requirements for Shanghai and Suzhou pharmaceutical exporters. The Yangtze River Delta biopharma cluster pilots AI-enabled release decision systems under regulatory sandbox programs. Domestic chemical producers in Shandong Province retrofit legacy DCS installations with modular batch execution layers.
Batch Management Software Market Vendor Landscape
German automation conglomerates anchor one tier through deep DCS integration and validated system legacies; North American software specialists hold another through cloud-native architectures and rapid deployment cycles. The market structures around three to five dominant platform ecosystems with long-tail specialists serving niche compliance requirements. Two strategic archetypes predominate: vertically integrated automation vendors bundling batch modules with control hardware, and pure-play software vendors emphasizing interoperability across heterogeneous plant floors. Competitive moves center on strategic partnerships with GAMP 5-certified integrators and geographic expansion through localized validation documentation.
Within the automation-integrated tier, Siemens AG and Rockwell Automation occupy positions exemplifying divergent geographic strengths. Siemens anchors European pharmaceutical and chemical demand through its SIMATIC BATCH platform and deep presence in Germany's chemical corridor. Rockwell Automation represents North American pharmaceutical specialization through FactoryTalk Batch deployments across FDA-regulated facilities. AVEVA sits within the engineering-software convergence space, unifying lifecycle data management across batch-centric operations. These three companies illustrate how vendor positioning maps to regional regulatory intensity and customer integration depth preferences.
| Leading Market Players |
|---|
| Rockwell Automation |
| Siemens |
| ABB |
| Emerson Electric |
| Honeywell |
| SAP |
| Schneider Electric |
| General Electric |
| AVEVA |
| Others |
Supply Flow & Price Mechanics
Industrial software licensing indices and cloud infrastructure cost benchmarks cascade through batch management software supply chains into pricing tiers differentiated by validation depth and deployment velocity. Pharmaceutical manufacturers absorb premium pricing for GAMP 5-validated systems while chemical processors exploit subscription elasticity to compress capital cycles.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with validated system deployments commanding premiums for accelerated implementation timelines against standard delivery schedules. Three-tier pricing structure across premium, standard, and economy levels segments by validation documentation depth and integration complexity. Cost compression in mid-market chemical tiers is intensifying because subscription models displace perpetual licenses. Contract manufacturers exhibit highest price sensitivity; biologics manufacturers with real-time release requirements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with specialized GAMP 5-certified integrators concentrated in Germany and the United States, constraining deployment capacity for validated pharmaceutical installations. Software development draws from engineering talent pools in India, Germany, and the United States, with cloud infrastructure sourcing from hyperscaler regions. Tariff exposure on cross-border data services threatens multi-tenant SaaS margins. Distribution runs through direct vendor sales organizations and certified system integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native microservices architectures are displacing monolithic validated systems, creating transition-phase investment requirements for incumbent vendors and opening white-space entry points for container-native specialists.
For Market Incumbents: Hedge against erosion of on-premise validation moats by acquiring container orchestration capabilities and embedding AI explainability modules ahead of EU AI Act enforcement. Prioritize backward integration into GAMP 5-certified implementation capacity to capture margin pools eroding to integrators. For New Entrants and Emerging Players: Enter via cosmetics and mid-market food processing segments where regulatory deadlines compress procurement cycles and incumbent validation overhead creates pricing vulnerability. Target Saudi SFDA-mandated upgrade waves through pre-configured Arabic-language compliance templates and rapid-deployment SaaS economics. For Investors and Strategic Acquirers: Distressed-cycle entries favor container-native batch software specialists with FDA 21 CFR Part 11 pre-validation in Germany and the United States, where pharmaceutical facility consolidation accelerates platform replacement decisions. Watch for inflection signals in Saudi SFDA enforcement timelines and FDA computer software assurance finalization.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Containerized architectures compress change control timelines from months to weeks for pharmaceutical quality teams. |
| AI-Enabled Release Module Development | Machine learning integration satisfies EU AI Act transparency requirements while reducing quarantine inventory. |
| GAMP 5 Integrator Acquisition | Validated system deployment capacity captures margin pools eroding from software licensing to implementation services. |
| Arabic-Language Compliance Localization | Saudi SFDA mandates create first-mover advantage in Vision 2030 pharmaceutical clusters. |
| Hybrid Deployment Architecture Launch | Local batch execution with cloud analytics serves mid-sized contract manufacturers seeking capital expenditure relief. |
Methodological Framework
Regulatory filing databases, trade association technical publications, and hyperscaler infrastructure disclosure reports formed the secondary backbone, cross-referenced with primary interviews involving batch control engineers, pharmaceutical quality assurance directors, chemical plant automation managers, and GAMP 5-certified system integrators. Bottom-up segment sizing triangulated against top-down industry expenditure estimates derived from capital project announcements and software vendor revenue disclosures.
Historical trendline analysis across deployment model transitions and vertical adoption patterns anchored the analytical framework, with growth trajectories modeled across on-premise, cloud-based, hybrid, and mobile architectures through the projection horizon. Segmentation dimensions included organization size, integration complexity with legacy DCS installations, regional regulatory cluster intensity, and vertical-specific compliance requirements. CAGRs were derived from slope analysis of validated system procurement cycles and cloud subscription conversion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA computer software assurance finalization or delayed Saudi SFDA enforcement. Forecasts reflect documented assumptions regarding regulatory timeline adherence and integrator capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Electronic Dictionary Market
Software & Services
Global Diagram Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
DevOps Market
Software & Services
Android Emulator Market
Software & Services
Event Management Software Market
Software & Services
Stock Footage Software Market
Software & Services
Global Recipe Apps Market
Software & Services
Global Text to Speech (TTS) Software Market
Software & Services
Warranty Management Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Construction Project Management Software Market
Software & Services
Fitness App Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Global Mobile Application Testing Solution Market
Software & Services
Global Bill of Material Management Software Market