
 Photobooth Software Market | 2026-2036
Photobooth Software Market Size, Share, and Industry Trends Forecast 2026-2036
Photobooth Software Market Insights
Independent wedding coordinators and boutique event planners is collapsing the legacy dominance of carnival operators and mall-based retail chains as the primary buyer archetype. dslrBooth leverages its offline-first architecture to anchor high-volume wedding deployments across North America. Foto Master competes through hardware-software bundling that controls the premium event-marketing segment. Simple Booth specializes in cloud-native workflows that extend brand reach for social-media-centric corporate activations.
Photobooth software constitutes programmable image-capture, processing, and distribution platforms that integrate DSLR or mirrorless camera APIs, real-time green-screen compositing, and instant print-queue management to automate branded photo experiences at commercial and social gatherings. Cloud-based solutions now lead deployment preference where SaaS subscription models reduce upfront capital barriers for seasonal event operators, while mobile applications represent the fastest-growing product type as smartphone-native workflows displace dedicated kiosk hardware at smaller gatherings. Desktop applications retain margin concentration among legacy operators running high-throughput print farms at stadiums and convention centers.
The EU AI Act and GDPR impose strict biometric-data handling standards on vendors serving European event markets, while the FCC's equipment authorization rules govern wireless transmission modules embedded in U.S. photobooth hardware. These frameworks shape product roadmaps by mandating consent-logging features and encrypted cloud pipelines that add compliance cost but create barrier-to-entry advantages for established platforms. Stakeholders must monitor whether emerging municipal privacy ordinances in California and New York force patchwork compliance that fragments SaaS delivery models.
Market Dynamics
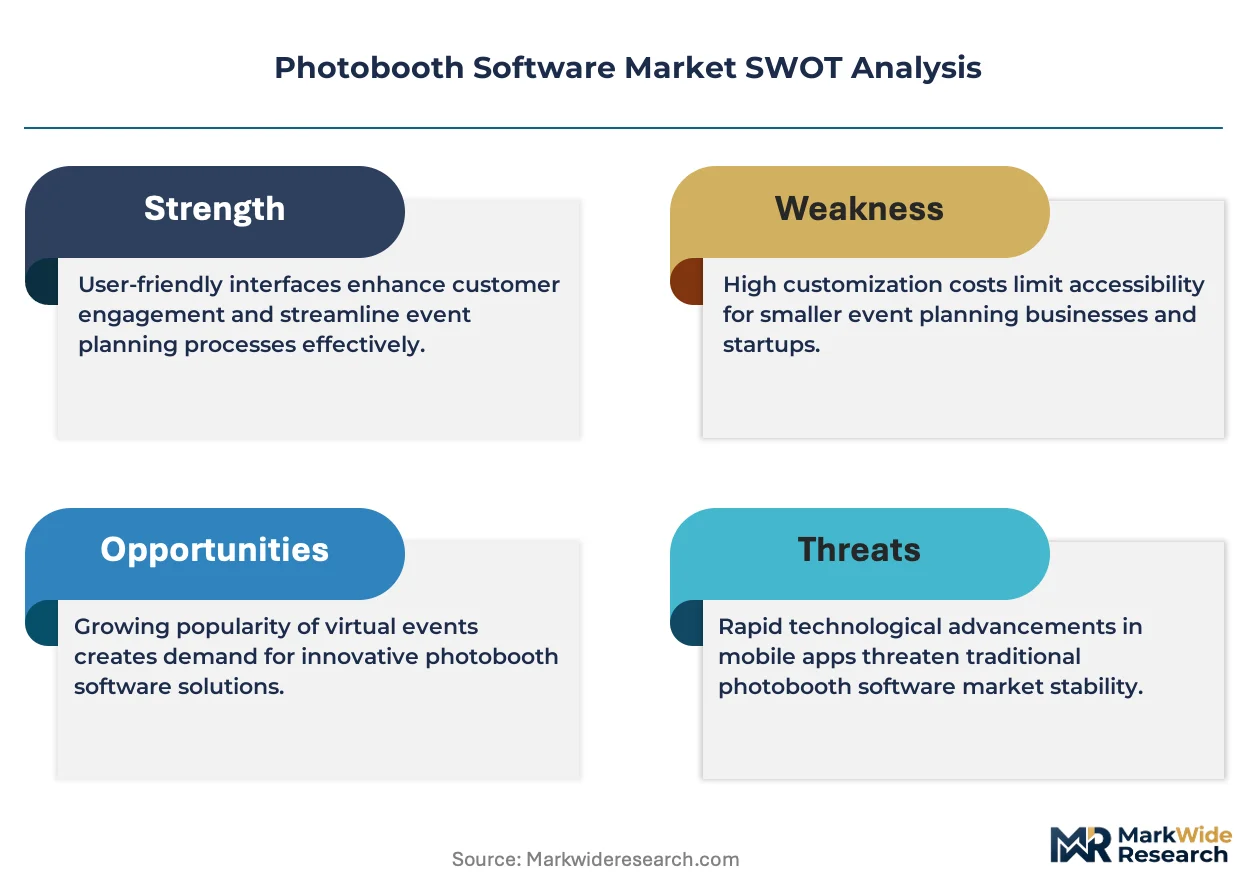
Cloud-native deployment architectures are collapsing the capital barrier that once protected legacy desktop incumbents, enabling seasonal wedding operators to launch photobooth services without hardware lock-in. This shift redistributes margin from perpetual-license vendors toward subscription-native platforms and forces established players to rearchitect their delivery models.
Growth Catalysts
- GDPR-aligned consent frameworks:European event markets now mandate auditable biometric-data handling pipelines, creating compliance-driven upgrade cycles among legacy operators who must replace offline storage with encrypted cloud workflows.
- DSLR-to-mirrorless camera transitions:Canon and Sony's API ecosystems now support real-time tethering protocols that slash capture-to-print latency, accelerating hardware refresh among high-volume wedding coordinators.
- Australia's event-service digitization:Sydney and Melbourne wedding markets exhibit the deepest SaaS penetration outside North America, with boutique planners standardizing on tablet-native booth configurations for outdoor vineyard ceremonies.
Market Restraints
- Mirrorless camera supply concentration:Sony and Canon control over 80% of professional-grade sensor supply, exposing booth operators to allocation risk during semiconductor fab capacity crunches.
- FCC equipment authorization timelines:Wireless transmission modules embedded in portable booth hardware face 90-120 day certification queues that delay product launches and compress selling seasons.
- Smartphone-native capture substitution:iOS and Android camera APIs now deliver computational photography quality that satisfies casual corporate activations, eroding demand for dedicated kiosk hardware at sub-50-attendee events.
Strategic Opportunities
- India's underpenetrated wedding market:Tier-1 Indian cities lack established photobooth rental infrastructure despite hosting multi-day celebrations with 500+ guests, creating first-mover terrain for cloud-native entrants.
- EU AI Act compliance tooling:Vendors who bundle automated consent-logging and facial-recognition audit trails can capture premium positioning among European corporate clients facing biometric-data liability exposure.
- Social-media platform API convergence:Instagram Reels and TikTok native posting integrations now enable real-time branded content workflows that extend corporate activation reach beyond physical event boundaries.
Industry Challenges
- Real-time compositing engineer scarcity:Green-screen chroma-key optimization and GPU-accelerated rendering pipelines require specialized talent that concentrates in gaming and VFX hubs, forcing photobooth vendors to compete for remote contractor pools.
- Legacy Windows-embedded hardware retrofit costs:Stadium and convention-center operators running decade-old print-farm controllers face six-figure migration expenses to achieve modern cloud connectivity and security patch compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photobooth Software Market |
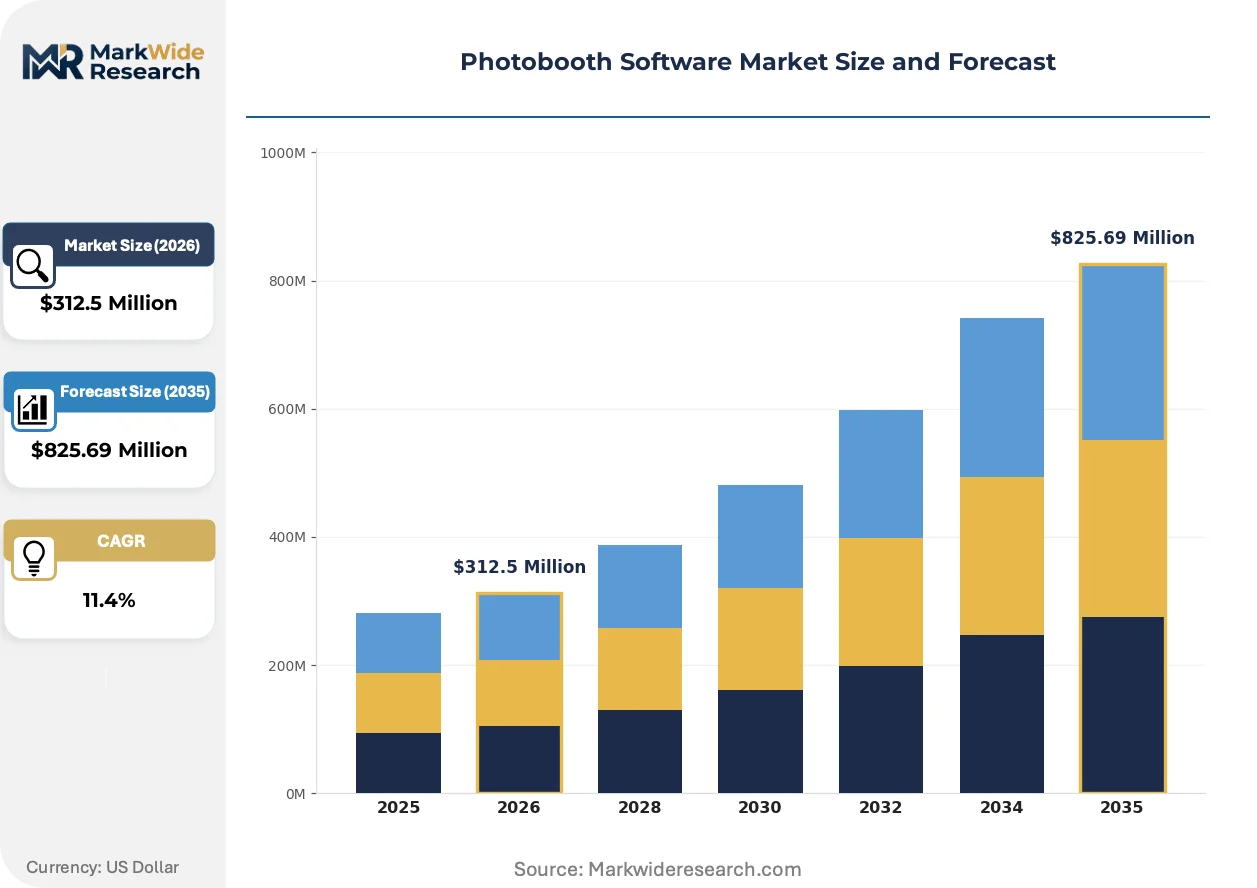
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Cloud-based Solutions, Mobile Applications, Desktop Applications Use Case: Event Marketing, Social Media Sharing, Guest Engagement, Corporate Events Customer Type: Event Planners, Wedding Coordinators, Corporate Clients, Individuals Deployment: On-premises, SaaS, Hybrid, Subscription-based |
| Companies Covered | dslrBooth, Foto Master, Simple Booth, Social Booth, LumaBooth, Snappic, Touchpix, SparkBooth, Darkroom Booth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photobooth Software Market Trends and Innovations
Tablet-native capture workflows are compressing hardware footprints and enabling roaming booth configurations that follow guests through venue spaces rather than anchoring fixed positions. This mobility shift redefines operator labor models and venue power requirements.
Mobile-first software stacks is supplanting dedicated DSLR-tethered kiosks at corporate activations and intimate gatherings. These tablet-native platforms leverage computational photography APIs to deliver acceptable output quality without proprietary camera hardware. Boutique event planners in Germany and Australia have accelerated adoption, compressing equipment shipping costs and setup labor to sub-15-minute deployments. The structural consequence is margin compression for hardware-bundled vendors who must unbundle software or cede the sub-500-attendee segment entirely.
The EU AI Act's biometric-data classification rules now designate real-time facial analysis and emotion detection as high-risk AI systems. This designation imposes conformity assessment obligations and third-party audit requirements on photobooth platforms offering automated beauty filters or demographic analytics. Wedding and corporate segments serving European clients must reengineer feature sets or disable functionality, while vendors who architect privacy-by-design pipelines gain competitive separation in compliance-heavy procurement cycles.
Outcome-based rental contracts are displacing flat-day-rate pricing among corporate marketing departments. Procurement teams now demand engagement metrics—social shares, email capture rates, dwell time—as contract performance clauses. This shift concentrates vendor selection among platforms with native analytics dashboards rather than offline desktop applications. The model is most visible in United States technology and consumer-brand verticals where marketing operations teams centralize event-technology procurement.
Photobooth Software Market Segmentation
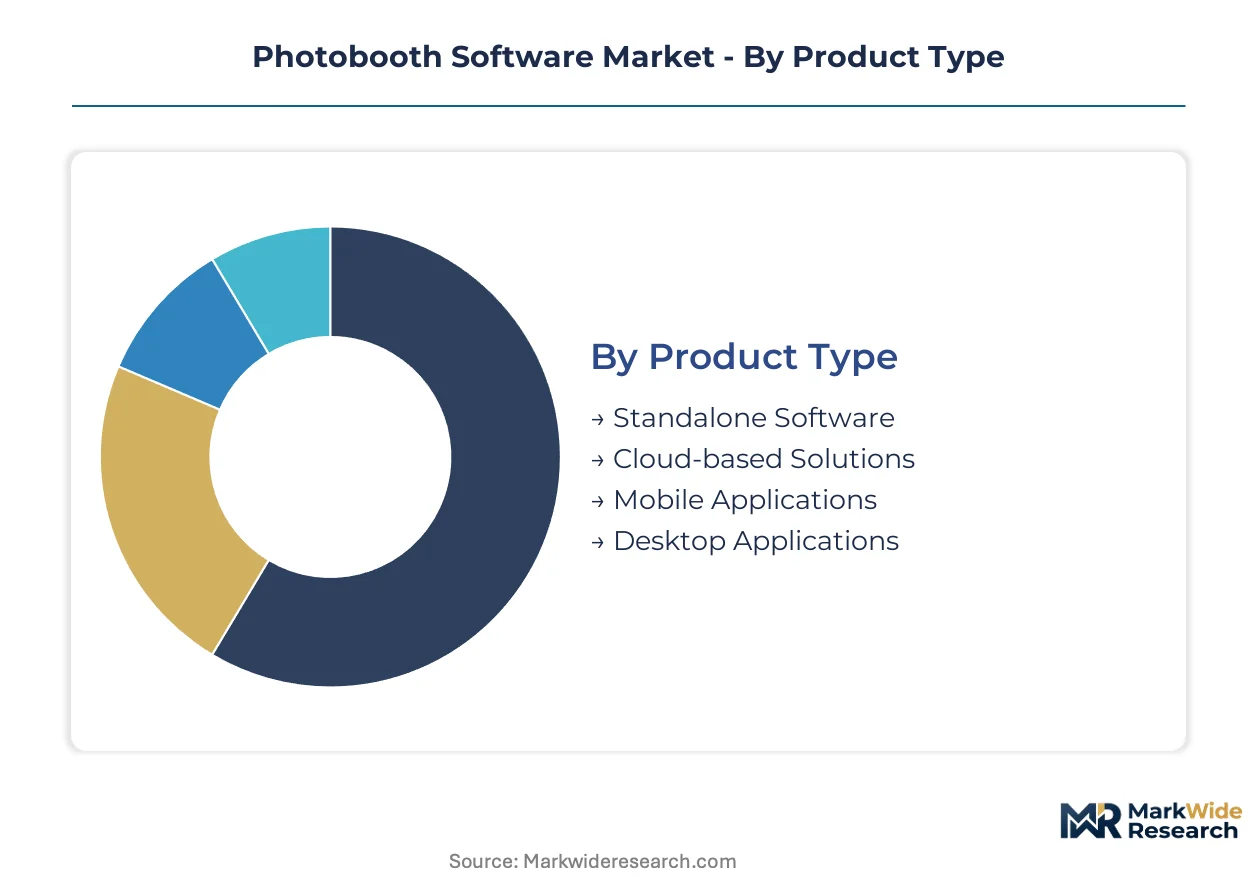
Segmentation in photobooth software reveals how margin migrates from perpetual-license hardware bundles toward recurring SaaS revenue. Understanding these splits exposes where vendor roadmaps must pivot to capture shifting buyer budgets across wedding, corporate, and retail channels.
Product Type:
Margin pools concentrate in cloud-native delivery models that convert upfront capital expenditure into recurring subscription streams, while legacy desktop incumbents defend high-throughput print-farm installations.
- Standalone Software:Perpetual-license packages installed on local Windows or macOS machines, tethered to DSLR hardware via USB or Wi-Fi protocols. Wedding coordinators in Australia favor these for vineyard ceremonies where internet connectivity remains unreliable, though the model faces margin compression as SaaS alternatives reduce upgrade revenue.
- Cloud-based Solutions:Browser-hosted platforms with real-time image processing, automatic backup pipelines, and GDPR-aligned consent logging. Corporate clients in Germany demand these for multi-city activation campaigns requiring centralized asset management and cross-border data compliance.
- Mobile Applications:iOS and Android-native capture workflows leveraging computational photography APIs. Boutique event planners deploy these for sub-50-attendee gatherings where hardware shipping costs erode profitability.
- Desktop Applications:Legacy Windows-embedded controllers running decade-old print-queue architectures. Stadium operators in the United States maintain these for high-volume throughput, though retrofit costs for cloud connectivity reach six figures.
Cloud-based Solutions holds installed capacity. Mobile Applications is rotating up the share rankings.
Use Case:
Application-driven segmentation tracks how procurement authority shifts from operations teams toward marketing departments demanding engagement metrics as contract clauses.
- Event Marketing:Branded photo experiences at product launches, trade shows, and sponsorship activations with real-time social amplification. Technology verticals in the United States now mandate dwell-time and email-capture KPIs in vendor contracts.
- Social Media Sharing:Instant posting workflows to Instagram Reels and TikTok with automated hashtag insertion. Corporate marketing teams prize these for extending physical event reach beyond venue boundaries.
- Guest Engagement:Interactive features including GIF creation, boomerang loops, and digital props at weddings and private celebrations. Wedding coordinators prioritize ease-of-use over advanced analytics here.
- Corporate Events:Multi-booth deployments with centralized dashboard monitoring and lead-capture integration. GDPR compliance tooling separates premium vendors in European procurement cycles.
Event Marketing captures the largest contract values. Social Media Sharing is climbing the fastest as platform API convergence accelerates.
Customer Type:
Buyer archetype segmentation exposes the collapse of carnival operators and mall-based retail chains as independent wedding coordinators and boutique planners seize procurement influence.
- Event Planners:Boutique agencies managing corporate activations and brand experiences across multiple cities. These buyers standardize on tablet-native configurations that compress setup labor to under fifteen minutes.
- Wedding Coordinators:Independent operators running seasonal high-volume deployments at multi-day celebrations. Australia's Sydney and Melbourne markets exhibit the deepest SaaS penetration among this cohort globally.
- Corporate Clients:Marketing operations teams centralizing event-technology procurement with outcome-based rental contracts. Engagement metrics now determine vendor selection over feature checklists alone.
- Individuals:Consumers purchasing one-time licenses for private parties and family gatherings. This segment concentrates in mobile applications with minimal hardware requirements.
Wedding Coordinators hold the deepest SaaS adoption. Corporate Clients is gaining share fastest as procurement centralization advances.
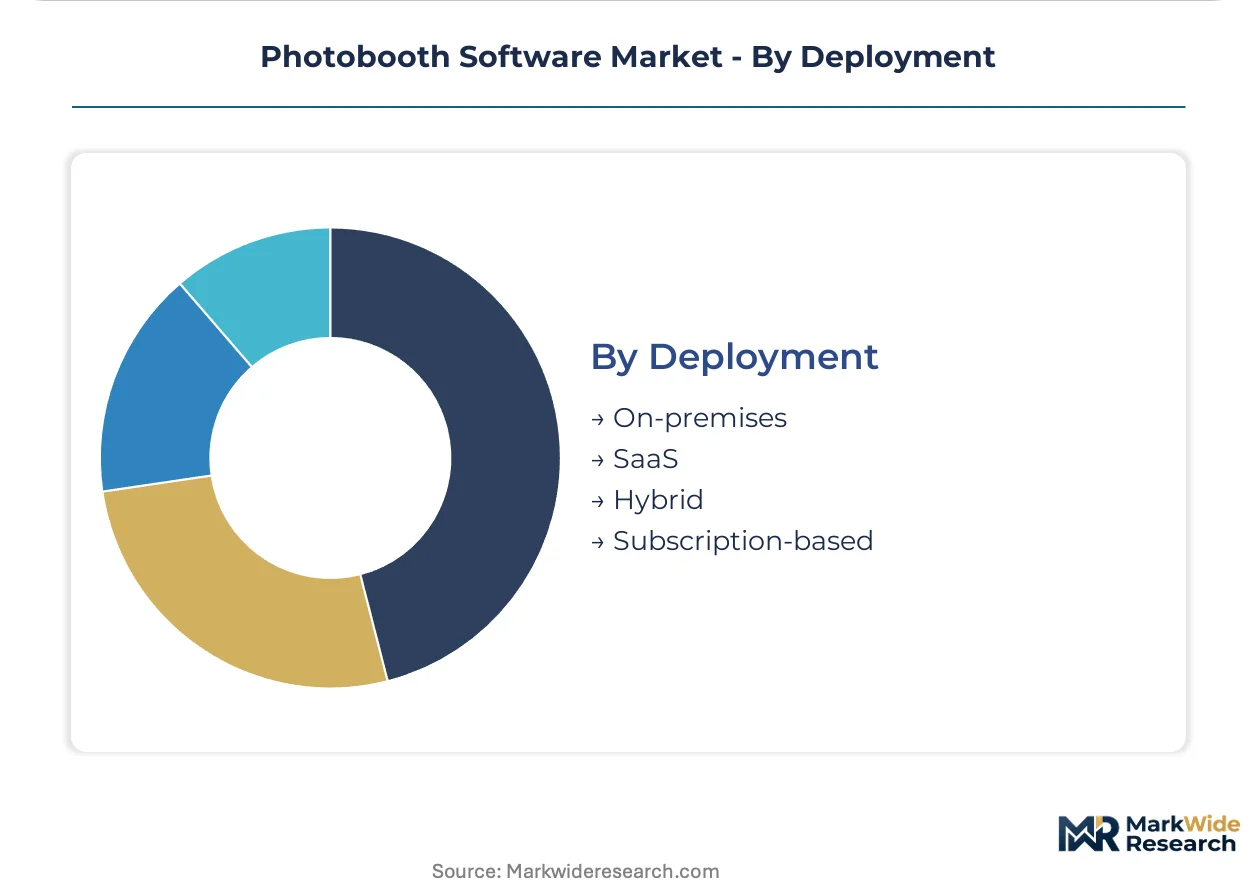
Deployment:
Delivery model segmentation tracks the architectural shift from on-premises hardware lock-in toward subscription-native platforms that reduce capital barriers for seasonal operators.
- On-premises:Local server installations with offline storage and manual backup protocols. Legacy stadium operators maintain these for air-gapped security, though GDPR-aligned European markets force migration toward encrypted cloud pipelines.
- SaaS:Fully managed browser platforms with automatic updates, elastic storage scaling, and API integrations. Seasonal wedding operators launch services without hardware procurement, redistributing vendor margin toward recurring revenue.
- Hybrid:Split architectures processing capture locally while syncing to cloud storage for backup and analytics. Germany's corporate market favors these for latency-sensitive real-time compositing with centralized compliance logging.
- Subscription-based:Tiered monthly or annual licensing with feature gates tied to event volume or output resolution. This model dominates among emerging operators in India's underpenetrated Tier-1 cities.
SaaS holds the largest subscriber base. Subscription-based is rotating up the share rankings as pricing experimentation expands in developing markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German photobooth software vendors export GDPR-compliant cloud platforms to wedding planners across France and the Netherlands, establishing a compliance-driven trade corridor that shapes procurement standards throughout Western Europe.
United States
Wedding coordinators in Texas and Florida drive SaaS adoption for seasonal high-volume deployments. FCC equipment authorization rules govern wireless transmission modules in portable booth hardware, creating 90-120 day certification queues. The Pacific Northwest corridor hosts tablet-native configuration specialists serving corporate technology activations.
Germany
Corporate marketing teams in Berlin and Munich mandate encrypted cloud pipelines for multi-city activation campaigns. The EU AI Act designates real-time facial analysis as high-risk, forcing vendors to reengineer beauty-filter features. Bavaria's boutique event planners standardize on hybrid deployment architectures for vineyard ceremonies.
Australia
Sydney and Melbourne wedding markets exhibit the deepest SaaS penetration outside North America, with boutique planners favoring tablet-native booth configurations for outdoor vineyard events. The country's national privacy regulator aligns state-level frameworks with GDPR-equivalent consent logging. Queensland's Gold Coast corridor concentrates roaming booth operators serving destination wedding venues.
India
Tier-1 cities including Mumbai and Bangalore lack established photobooth rental infrastructure despite hosting multi-day celebrations with 500-plus guests. The country's central bank monitors cross-border data flows for SaaS platforms processing payment-integrated activations. Maharashtra's wedding-service clusters present first-mover terrain for cloud-native entrants offering subscription-based pricing.
United Kingdom
London-based corporate marketing departments centralize event-technology procurement with outcome-based rental contracts demanding engagement metrics. The Information Commissioner's Office enforces biometric-data handling standards that mirror GDPR requirements. The Southeast corridor hosts specialists in social-media-integrated activations for technology and consumer-brand verticals.
Photobooth Software Market Competitive Landscape
Player mix skews toward specialized software vendors with hardware-agnostic architectures rather than integrated equipment manufacturers. The competitive structure remains fragmented across deployment models, with no single vendor commanding dominant share. Two strategic archetypes define positioning: offline-first desktop incumbents defending high-throughput print-farm installations, and cloud-native challengers capturing seasonal wedding operators through subscription economics. Dominant competitive moves include portfolio diversification into mobile-first workflows and strategic partnerships with mirrorless camera manufacturers for API-integrated tethering protocols.
Within the offline-first tier, dslrBooth anchors North American wedding deployments with perpetual-license architectures. Foto Master occupies the hardware-software bundling position controlling premium event-marketing segments. Simple Booth exemplifies the cloud-native archetype, representing subscription-native platforms that reduce capital barriers for social-media-centric corporate activations.
| Leading Market Players |
|---|
| dslrBooth |
| Foto Master |
| Simple Booth |
| Social Booth |
| LumaBooth |
| Snappic |
| Touchpix |
| SparkBooth |
| Darkroom Booth |
| Others |
Pricing and Supply Chain Analysis
Ninety-to-one-hundred-twenty-day FCC equipment authorization queues for wireless transmission modules compress selling seasons and redistribute pricing power toward vendors with pre-certified hardware inventories. This lead-time constraint concentrates margin in SaaS-native platforms that amortize certification costs across recurring subscriber bases while forcing seasonal operators toward rental models that transfer capital risk upstream.
Pricing Analysis
Next-generation cloud-native subscription tiers command premium positioning against legacy perpetual-license desktop packages and nascent mobile-application freemium tiers. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-compliant enterprise deployments from basic wedding-operator packages and individual consumer licenses. Cost compression in the mobile tier is intensifying because computational photography APIs erode dedicated hardware value. Wedding coordinators exhibit highest price sensitivity due to seasonal cash-flow volatility, while corporate marketing departments prioritize outcome-based contracts with engagement-metric clauses over per-unit pricing.
Supply Chain Analysis
Japan and South Korea anchor professional-grade mirrorless sensor fabrication and computational imaging chipset supply for tethered capture systems. Taiwan sources from specialty PCB manufacturers and precision mechanical housing fabricators concentrated in Taoyuan and Tainan science parks. Single-source vulnerability concentrates in Sony and Canon API ecosystem dependencies that expose booth operators to allocation risk during semiconductor fab capacity crunches. Distribution runs through direct vendor-to-operator digital channels for SaaS platforms, while hardware-bundled vendors maintain regional distributor networks for equipment logistics and on-site technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR-aligned biometric-data handling mandates and the EU AI Act's high-risk AI system classification create regulatory inflection that favors compliance-architected platforms over legacy offline incumbents. This disruption accelerates margin migration toward subscription-native vendors with encrypted cloud pipelines and automated consent-logging capabilities.
For Market Incumbents: Fortify high-throughput print-farm installations serving stadium and convention-center operators by embedding hybrid cloud-connectivity modules that satisfy modern security patch requirements without six-figure retrofit costs. Deepen API integration partnerships with Canon and Sony to lock in real-time tethering protocol access before mirrorless camera supply concentration worsens. Channel control through certified technician networks defends against tablet-native challengers eroding the sub-500-attendee segment. For New Entrants and Emerging Players: Boutique wedding-service digitization in India's Tier-1 cities represents the most penetrable white-space target, where multi-day celebrations with 500-plus guests lack established photobooth rental infrastructure. Tablet-native configurations with sub-15-minute deployment protocols unlock outdoor vineyard and destination wedding formats where hardware shipping costs erode legacy operator profitability. A subscription-based go-to-market angle with localized payment-integrated activations bypasses upfront capital barriers that constrain seasonal operator adoption. For Investors and Strategic Acquirers: Carve-out targets emerge from event-technology divisions of integrated marketing services holding companies seeking to divest non-core software assets. Long-term viability over the projection horizon rests on compliance tooling differentiation rather than feature breadth alone, positioning GDPR-architected platforms for sustained premium procurement. Monitor municipal privacy ordinance proliferation in California and New York as the signal to watch for patchwork compliance fragmentation that favors multi-jurisdiction-capable vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Converts perpetual-license revenue to recurring SaaS streams while reducing seasonal operator capital barriers. |
| GDPR Compliance Tooling Bundle | Captures premium positioning among European corporate clients facing biometric-data liability exposure under EU AI Act. |
| Mirrorless Camera API Integration | Secures real-time tethering protocol access that slashes capture-to-print latency for high-volume wedding deployments. |
| Social Media Platform Convergence | Enables Instagram Reels and TikTok native posting that extends corporate activation reach beyond physical venue boundaries. |
| India Market Entry Localization | Addresses underpenetrated Tier-1 cities with subscription-based pricing adapted to multi-day celebration formats. |
Research Methodology
Initial hypotheses were tested against primary input from wedding coordinators, event planners, corporate marketing operations leads, and photobooth software vendors and refined through secondary validation across SEC filings, hyperscaler capex disclosures, App Annie mobile application analytics, and FCC equipment authorization databases. Bottom-up triangulation of operator deployment counts and top-down reconciliation against aggregate event-services expenditure produced convergent market sizing estimates.
Variance decomposition across deployment model, customer type, use case, and regional adoption pattern shaped the analytical framework. CAGRs were derived from segmented growth rate reconciliation against macroeconomic event-services expenditure indicators. Forecast inputs incorporated DSLR-to-mirrorless camera transition velocity, SaaS penetration curves in Australia's Sydney and Melbourne markets, and GDPR compliance upgrade cycle timing.
Forecasts assume regulatory continuity in GDPR-aligned European regimes and FCC equipment authorization timelines; material policy shifts would require re-modeling. Specific risks include municipal privacy ordinance fragmentation in United States coastal states and mirrorless camera supply allocation shocks from semiconductor fab capacity constraints. Recalibration cycles align with material shifts in camera hardware refresh velocity and social-media platform API access policy changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Servicenow Tech Services Market
Software & Services
Personal Budgeting Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Identity Resolution Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Global Automotive Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Test Automation Market
Software & Services
Multiexperience Development Platforms Market
Software & Services
Software As a Service (Saas) Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Email Marketing Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Photo Editor App Market
Software & Services
Team Collaboration Tools Market