
 Business Email Market | 2026-2036
Business Email Market Size, Share, and Industry Trends Forecast 2026-2036
Business Email Market Outlook
The gap between premium integrated suites and standalone commodity email is realigning around API depth, compliance automation, and cross-platform workflow orchestration. Microsoft Outlook leverages its enterprise distribution channel and Entra identity fabric to sustain dominance in regulated industries. Google Workspace anchors the mid-market with native AI-assisted drafting and real-time collaboration tools. Zoho Mail competes aggressively on price while extending vertical CRM connectivity for emerging-market small businesses.
Business email denotes enterprise-grade messaging infrastructure with guaranteed uptime SLAs, encryption in transit and at rest, administrative audit logging, and directory service integration for identity governance. Hosted email and public cloud deployment together occupy the largest revenue pools, though hybrid configurations are gaining traction among enterprises with data residency requirements. Small businesses and startups represent the fastest-expanding customer type as self-service onboarding and per-seat billing lower adoption barriers. API support and third-party integrations concentrate margin in the integration level segment, where vendors charge premium rates for CRM, ERP, and marketing automation connectors.
GDPR mandates from EU regulators, ISO 27001 certification requirements, and SEC recordkeeping rules for US financial firms collectively shape product roadmaps and procurement vetting processes. The EU AI Act introduces additional scrutiny for automated email sorting and generative composition features, forcing vendors to document training data provenance and human oversight mechanisms. Stakeholders must monitor how jurisdictional fragmentation in data localization laws affects multi-tenant architecture decisions and customer migration costs.
Market Dynamics
API-first architecture and zero-trust security mandates are compressing procurement cycles as enterprises abandon monolithic suites for composable messaging stacks with embedded compliance automation.
Growth Catalysts
- GDPR Article 32 encryption mandates:EU enterprises must deploy end-to-end encryption for personal data processing, forcing upgrades from basic TLS to quantum-resistant protocols. Financial services firms in Frankfurt and Paris are accelerating procurement timelines.
- AI-assisted composition tools:Generative drafting capabilities embedded in enterprise inboxes reduce response latency for customer service teams. Mid-market professional services firms report measurable productivity gains.
- India:The country's digital infrastructure push and PLI scheme for IT hardware create captive demand for locally hosted email infrastructure among domestic conglomerates and government contractors.
Market Restraints
- Certificate authority concentration:Three vendors control over 90% of S/MIME and TLS certificate issuance, creating single-point-of-failure risk for encrypted email verification chains.
- Legacy directory service lock-in:Active Directory dependency in regulated industries imposes switching costs measured in 18-24 month migration timelines and seven-figure integration spend.
- EU AI Act documentation burden:Automated sorting and sentiment analysis features require algorithmic impact assessments and training data provenance records, slowing feature rollouts.
Strategic Opportunities
- Southeast Asian financial hubs:Singapore and Jakarta-based banks seek sovereign cloud email with local data residency, creating whitespace for regional hosting providers with MAS certification.
- ISO 27701 privacy certification:Vendors achieving this extension to 27001 capture procurement preference from EU healthcare and legal sectors where controller-processor agreements require documented privacy management.
- Voice-to-email transcription convergence:Integration of ambient computing interfaces with messaging workflows targets field service technicians and logistics coordinators in German manufacturing clusters.
Industry Challenges
- Zero-trust architecture talent scarcity:Enterprise IT departments lack engineers fluent in continuous authentication and microsegmentation, delaying secure email gateway deployments.
- Cross-border e-discovery friction:Conflicting data localization requirements between EU, China, and US jurisdictions complicate litigation hold procedures for multinational corporations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Email Market |
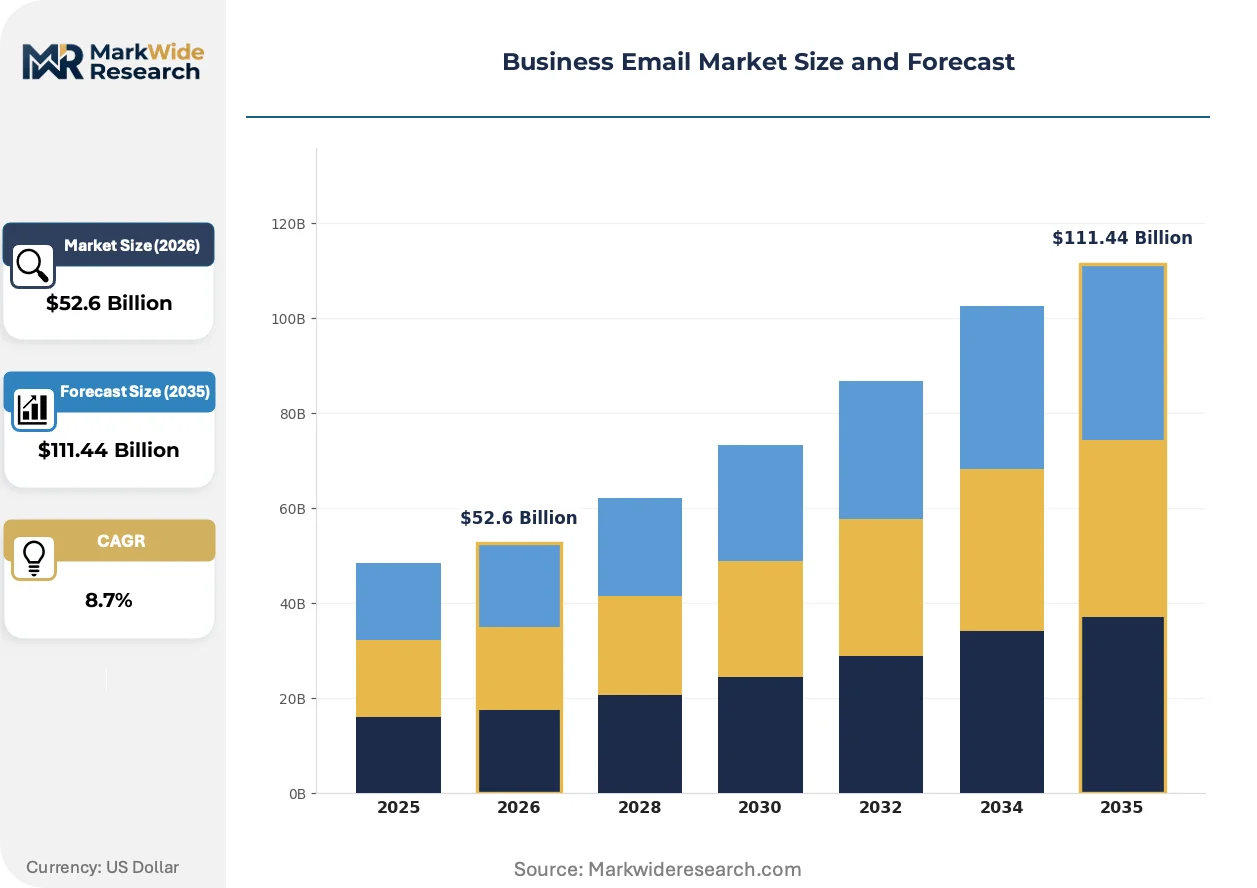
| Market Size in 2026 | $52.6 Billion |
| Market Size in 2035 | $111.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hosted Email, On-Premises Email, Hybrid Email, Email Archiving Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Customer Type: Small Businesses, Enterprises, Startups, Freelancers Integration Level: Third-Party Integrations, In-House Solutions, API Support, Custom Platforms |
| Companies Covered | Google Workspace, Microsoft Outlook, Zoho Mail, Brevo, Mailchimp, HubSpot, ActiveCampaign, Klaviyo, GetResponse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Email Market Strategic Shifts
Generative AI integration and sovereign cloud mandates are fragmenting vendor consolidation patterns as buyers prioritize composable security over bundled convenience.
Post-quantum cryptography migration is overtaking traditional RSA and elliptic curve implementations in enterprise procurement specifications. Financial services firms in London and Zurich are mandating CRYSTALS-Kyber and CRYSTALS-Dilithium support in RFPs. This transition compresses refresh cycles for hardware security modules and accelerates obsolescence of five-year-old encryption appliances.
The EU AI Act's risk classification framework imposes documentation and human oversight requirements on automated email triage and response generation systems. Vendors must maintain algorithmic decision logs and designate responsible AI officers. German automotive suppliers and French pharmaceutical distributors are delaying AI feature deployments pending legal clarity on high-risk system definitions.
Consumption-based billing for API calls and storage tiers displaces flat per-seat licensing in mid-market procurement negotiations. Managed service providers in Manchester and Amsterdam are unbundling email security from core messaging to capture margin from usage-variable threat detection. This shift pressures pure-play vendors lacking consumption metering infrastructure.
Business Email Market Segmentation
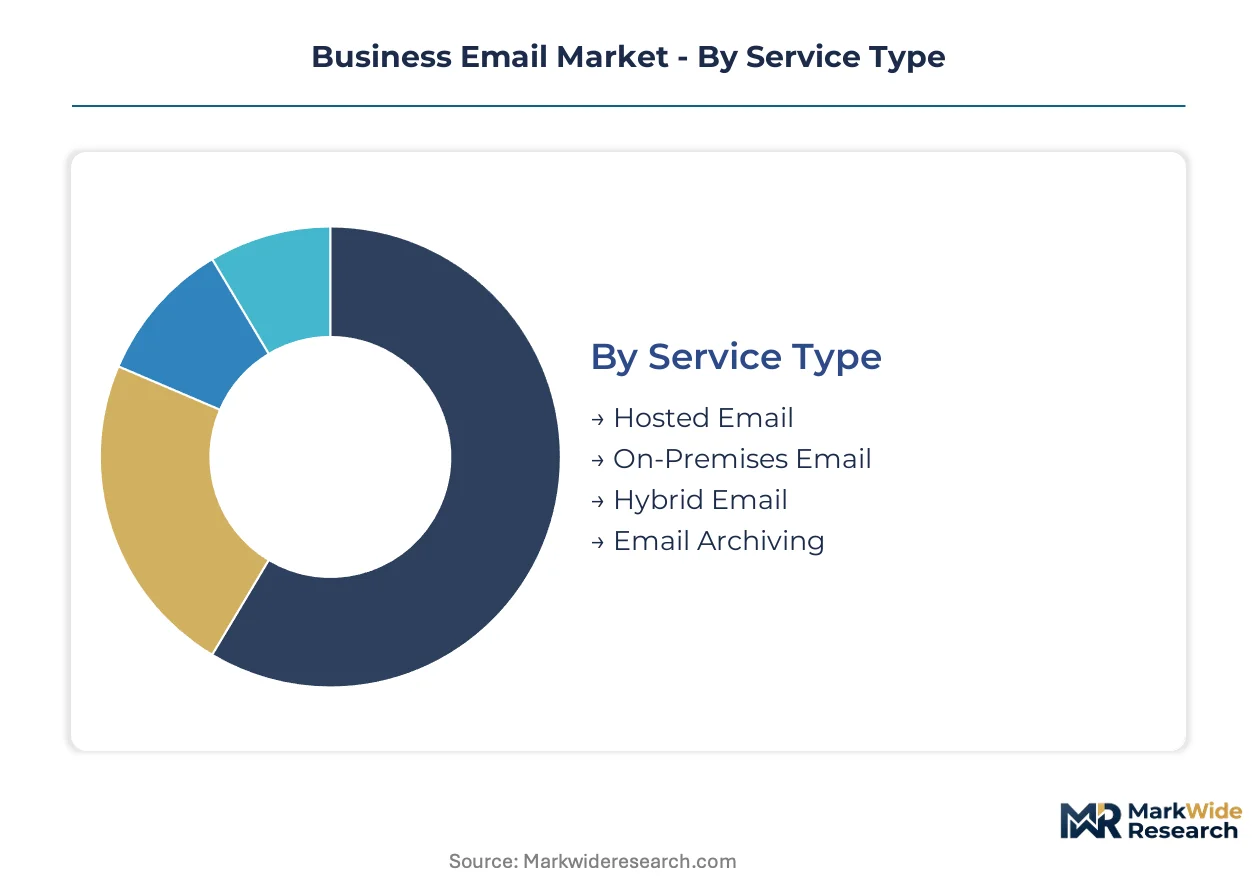
Segmentation in business email reveals how infrastructure investment, compliance burden, and workflow complexity split procurement budgets across fundamentally different operational models. Buyers sort themselves by data sovereignty tolerance, legacy system entanglement, and integration sophistication.
Service Type:
Capital intensity peaks with on-premises infrastructure, where hardware depreciation and facilities costs dominate TCO calculations.
- Hosted Email:Multi-tenant cloud delivery with vendor-managed uptime SLAs and automatic security patching. Demand concentrates among UK professional services firms seeking GDPR-compliant data residency without capital expenditure.
- On-Premises Email:Dedicated hardware and software licenses deployed within customer data centers. German automotive suppliers and French defense contractors favor this model for air-gapped environments with classified data handling requirements.
- Hybrid Email:Split workloads between cloud and local infrastructure. Swiss private banks use this architecture to keep core transaction records on-site while routing marketing communications through hosted tiers.
- Email Archiving:Long-term retention systems with legal hold capabilities and e-discovery indexing. US financial firms under SEC recordkeeping mandates drive procurement volume for tamper-proof storage with 7-year retention guarantees.
Most installed capacity flows through Hosted Email. Expansion is steepest in Hybrid Email.
Deployment Model:
Operational complexity and control granularity separate buyers, with sovereignty requirements pushing some toward isolated infrastructure.
- Public Cloud:Shared infrastructure with elastic scaling and pay-per-seat economics. Mid-market Dutch logistics firms and Danish SaaS startups gravitate here for rapid provisioning without procurement delays.
- Private Cloud:Single-tenant environments with dedicated compute and storage resources. Italian pharmaceutical manufacturers deploy this for EMA audit trails requiring isolated GxP-compliant systems.
- Hybrid Cloud:Orchestrated workload placement across public and private substrates. Australian mining conglomerates use this to process sensitive exploration data privately while collaborating via public channels.
- Community Cloud:Shared infrastructure restricted to specific industry verticals or regulatory frameworks. Canadian healthcare networks under PIPEDA and provincial privacy laws cluster here for peer-validated compliance.
Public Cloud carries the heaviest transaction volume. Private Cloud is climbing the fastest among regulated sectors.
Customer Type:
Procurement authority and integration sophistication create four distinct buying motions with different sales cycle lengths.
- Small Businesses:Self-service onboarding with credit-card billing and minimal IT staff. Indian retail chains and Brazilian professional services firms in São Paulo and Mumbai metro areas drive volume through simplified admin consoles.
- Enterprises:RFP-driven procurement with security questionnaires and legal review. German chemical conglomerates and Japanese automotive keiretsu mandate ISO 27001 certification and dedicated customer success managers.
- Startups:Growth-stage companies prioritizing API extensibility and per-seat flexibility. Israeli fintech ventures and Singaporean proptech firms favor consumption-based models that scale with headcount fluctuations.
- Freelancers:Individual professionals requiring basic custom domains and mobile synchronization. Creative contractors in Barcelona and Lisbon metro areas represent high-volume, low-ACV accounts with minimal support expectations.
Enterprises command the largest deal sizes. Startups are expanding most quickly as venture-backed firms proliferate.
Integration Level:
Technical maturity and ecosystem connectivity determine whether buyers seek plug-and-play connectors or bespoke development.
- Third-Party Integrations:Pre-built connectors to CRM, ERP, and productivity suites. US healthcare providers under HIPAA link email to Epic and Cerner systems for automated patient communication workflows.
- In-House Solutions:Custom-developed connectors maintained by internal engineering teams. Nordic industrial equipment manufacturers build proprietary links to SAP environments with specialized document routing logic.
- API Support:REST and GraphQL endpoints enabling customer-built automations. French insurtech firms and UK neobanks leverage these for real-time policy notifications and transaction alerts.
- Custom Platforms:Fully proprietary email stacks with no external dependencies. Russian and Chinese state-affiliated entities deploy these for complete supply chain autonomy and domestic cryptography mandates.
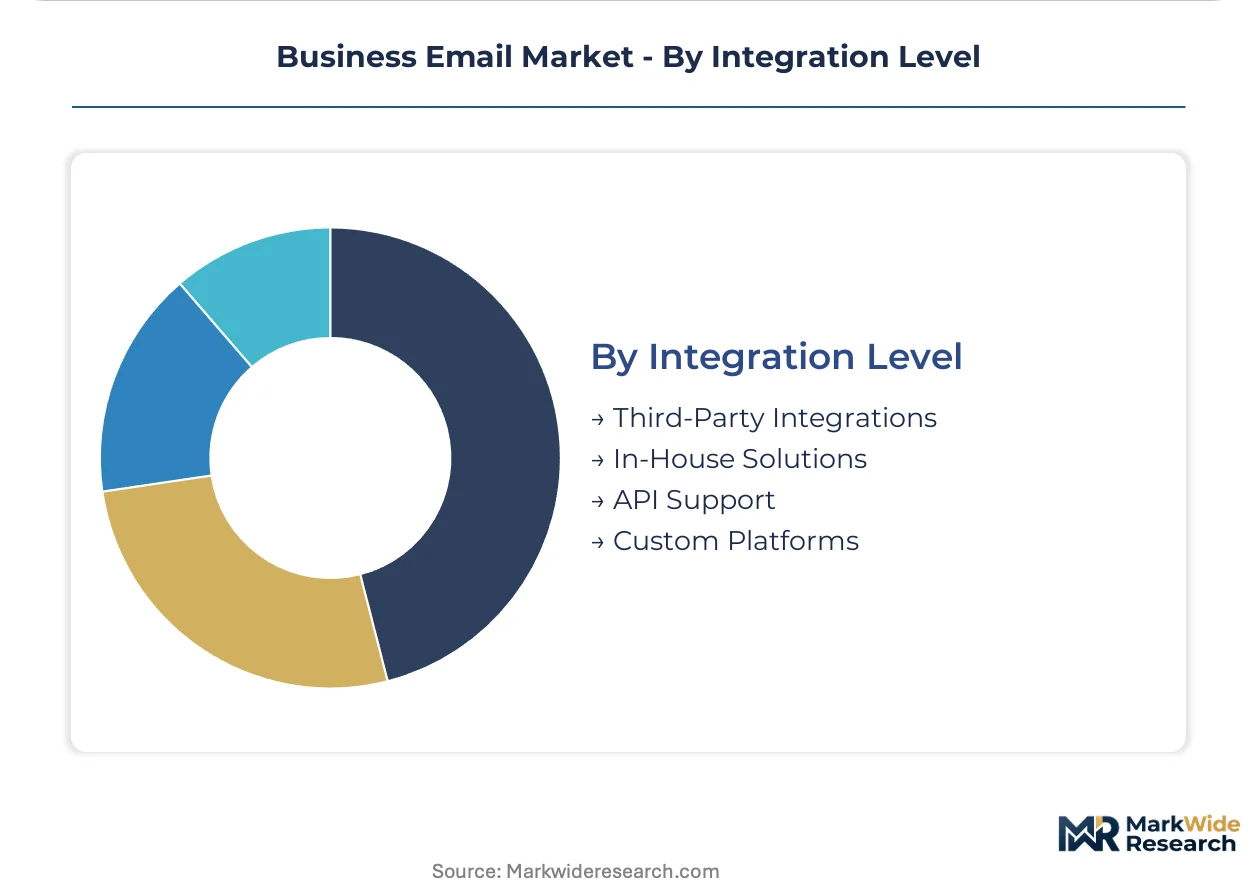
Third-Party Integrations absorb the majority of commercial activity. API Support is gaining share fastest among developer-centric buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud architects and cybersecurity specialists concentrate in London, Frankfurt, and Singapore, anchoring regional demand patterns for enterprise-grade messaging infrastructure across three continents.
United States
SEC recordkeeping mandates drive procurement from financial services firms in New York and Chicago. HIPAA compliance requirements shape healthcare provider decisions in the Boston-Cambridge corridor. Silicon Valley technology enterprises prioritize API extensibility and consumption-based billing models.
Germany
Automotive suppliers in Stuttgart and Munich demand air-gapped on-premises solutions for classified engineering data. BSI federal security guidelines enforce strict encryption standards for government contractors. Frankfurt financial institutions accelerate quantum-resistant protocol adoption ahead of EU regulatory deadlines.
United Kingdom
Professional services firms in London seek GDPR-compliant hosted tiers without capital expenditure burden. The Information Commissioner's Office enforcement actions tighten data residency requirements. Manchester managed service providers pioneer unbundled security pricing for mid-market clients.
India
Domestic conglomerates and government contractors require locally hosted infrastructure under PLI scheme incentives. Mumbai retail chains and Bangalore SaaS startups drive volume through self-service onboarding portals. TRAI data localization consultations influence multi-tenant architecture decisions.
Singapore
MAS-certified sovereign cloud email attracts banking headquarters relocating from Hong Kong. Jakarta-based financial institutions extend procurement to Singaporean hosting providers for regional data residency compliance. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria.
Business Email Market Competitive Environment
Top-tier vendors anchor enterprise procurement through identity fabric integration and compliance automation, while mid-market specialists compete on API depth and vertical connectivity. The vendor base stratifies across three tiers: hyperscale platforms with distribution channel dominance, regional hosting providers with sovereign cloud certification, and price-focused challengers extending CRM-native workflows. Strategic moves concentrate on M&A for zero-trust security capabilities and geographic expansion into Southeast Asian financial hubs.
Within the hyperscale tier, Microsoft Corporation and Google LLC exemplify platform consolidation through enterprise identity and AI-assisted productivity integration. Zoho Corporation occupies a distinct position among emerging-market specialists, leveraging vertical CRM connectivity for price-sensitive small business segments. Brevo S.A. represents the marketing-automation-native archetype, bridging transactional email with campaign orchestration for digital commerce operators.
| Leading Market Players |
|---|
| Google Workspace |
| Microsoft Outlook |
| Zoho Mail |
| Brevo |
| Mailchimp |
| HubSpot |
| ActiveCampaign |
| Klaviyo |
| GetResponse |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up hosting specialists in Manchester and Amsterdam enforce pricing discipline through consolidated infrastructure footprints while passing through data center energy costs and certificate authority fees as line-item surcharges. This ownership pattern concentrates supply-side leverage among vendors with captive data center assets, compressing margins for pure-play resellers lacking direct compute control.
Pricing Analysis
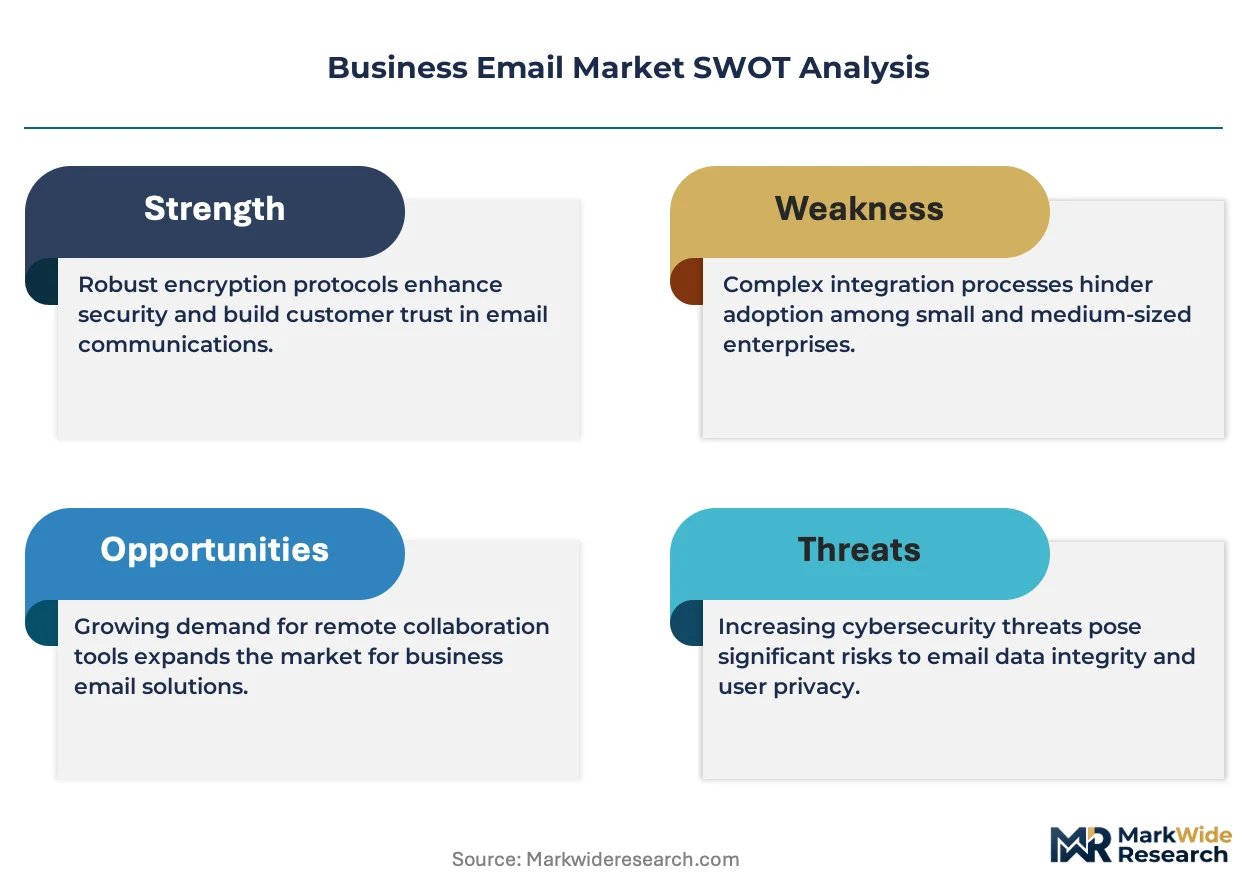
The bundled-vs-unbundled service split distinguishes enterprise procurement patterns across the market. Three-tier pricing structure across premium, standard, and economy levels anchors SaaS subscription models, with ISO 27001 certification tier and API call volume serving as primary price differentiation drivers. Cost compression in the economy tier is intensifying because hyperscale platforms absorb infrastructure overhead at scale. Small businesses exhibit highest price sensitivity, while regulated financial services firms demonstrate lowest elasticity due to compliance mandates.
Supply Chain Analysis
Certification and qualification gating restricts viable infrastructure providers to vendors with ISO 27001, SOC 2 Type II, and regional data residency attestations. Geographic supply concentrates in Germany, Ireland, and Singapore for primary hosting capacity, with secondary nodes emerging in India under PLI scheme incentives. Raw material dependencies center on TLS certificate issuance from concentrated authorities, encryption hardware security modules, and fiber interconnect capacity. Single-source vulnerability in certificate infrastructure poses structural supply chain risk. Distribution runs through direct enterprise sales teams, managed service provider channels, and self-service onboarding portals for volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where GDPR Article 32 encryption mandates and EU AI Act documentation requirements continuously refresh procurement cycles among compliance-sensitive buyers.
For Market Incumbents: Lock in enterprise relationships through Entra identity fabric integration and automated compliance reporting dashboards that reduce customer audit preparation burden. Deepen backward integration into quantum-resistant cryptography modules before CRYSTALS-Kyber mandates harden in Frankfurt and Zurich procurement specifications. Channel control through certified managed service provider networks defends against price-focused challengers. For New Entrants and Emerging Players: Launch via API-first developer marketplaces targeting Israeli fintech ventures and Singaporean proptech firms with consumption-based billing that scales with headcount volatility. Sovereign cloud certification in Jakarta and Bangkok captures whitespace as MAS guidelines push regional banks toward locally hosted alternatives. Vertical CRM-native positioning outperforms generic messaging pitches in Indian retail chain segments. For Investors and Strategic Acquirers: Valuations sit cheapest among regional hosting providers with incomplete zero-trust security stacks but established data center footprints in secondary European markets. Long-term viability over the coming decade hinges on post-quantum cryptography migration readiness and AI governance documentation infrastructure. Watch for EU AI Act enforcement actions against automated email triage systems as an inflection indicator for compliance-tech acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Security Acquisition | CRYSTALS-Kyber protocol support satisfies Frankfurt financial institution procurement mandates ahead of regulatory deadlines. |
| Sovereign Cloud Certification | MAS attestation enables Singaporean hosting providers to capture Jakarta banking headquarters relocating from Hong Kong. |
| API Consumption Metering Buildout | Usage-variable billing infrastructure captures margin from Manchester managed service provider unbundling strategies. |
| Vertical CRM Integration | Native Zoho and Salesforce connectors penetrate Indian retail chain and Brazilian professional services segments. |
| AI Governance Documentation Platform | Algorithmic impact assessment tools address EU AI Act requirements delaying German automotive supplier deployments. |
Study Parameters
Direct dialogue with CISOs, IT procurement officers, managed service provider principals, and integration specialists grounded qualitative findings in operational constraints faced during enterprise email migrations. Secondary validation drew from SEC 10-K infrastructure disclosures, ISO certification registries, hyperscaler capex breakdowns, and EU regulatory filing databases. Bottom-up seat-count modeling and top-down enterprise IT spend allocation triangulated market sizing across deployment models and customer types.
Segment-level projections across hosted, on-premises, hybrid, and archiving service types incorporated organization size bands, vertical regulatory exposure, and regional data sovereignty requirements over the projection horizon. CAGRs derived from fitted adoption curves weighted by compliance deadline proximity and infrastructure refresh cycles. Quantum-resistant protocol procurement timelines and AI feature deployment delays in EU jurisdictions served as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or certificate authority consolidation events. Model outputs reflect assumptions regarding migration friction costs and vendor consolidation patterns. A model refresh is warranted upon material change in post-quantum cryptography standardization timelines or sovereign cloud certification reciprocity agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
MRP Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Global Personalisation Software Market
Software & Services
Workshop Management Software Market
Software & Services
Cemetery Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Performance Management Software Market
Software & Services
API Testing Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Smartphone OS Market
Software & Services
Towing Software Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Team Collaboration Software Market
Software & Services
Sales Platforms Software Market
Software & Services
Ad Creation Software Market