
 North America IT Services Market | 2026-2036
North America IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America IT Services Market Outlook
The U.S. Securities and Exchange Commission's climate disclosure mandate is realigning enterprise IT spending toward audit-ready data infrastructure and carbon accounting platforms. IBM sustains deep vertical integration across hybrid cloud and quantum-safe security stacks. Amazon Web Services Professional Services dominates federal cloud migration contracts through cleared personnel and air-gapped regions. Accenture differentiates via its proprietary myConcerto platform for industry-specific transformation roadmaps.
North America IT services encompass the design, implementation, management, and optimization of information technology systems spanning infrastructure, applications, and data platforms, typically delivered through service-level agreements specifying uptime thresholds, response times, and security compliance parameters. These services enable enterprises to externalize technical complexity, accelerate digital capability deployment, and maintain operational continuity across distributed workforces. Cloud Services and Managed Services command the largest revenue pools as enterprises retire legacy data centers, while Cybersecurity and Artificial Intelligence represent the fastest-expanding technology segments where specialist margins exceed commoditized infrastructure management. Hybrid deployment models attract the steepest growth trajectory as regulated industries balance sovereignty requirements with cloud elasticity.
The Federal Risk and Authorization Management Program and Canada's Directive on Security Management shape product standards and market access by mandating continuous monitoring, encryption protocols, and supply chain attestation for vendors serving government clients. State-level privacy frameworks, including California's Consumer Privacy Act and Virginia's Consumer Data Protection Act, fragment compliance architectures and drive demand for jurisdictional data governance tooling. Stakeholders must monitor emerging state AI legislation and procurement localization requirements that could bifurcate service delivery models across the U.S.-Canada corridor.
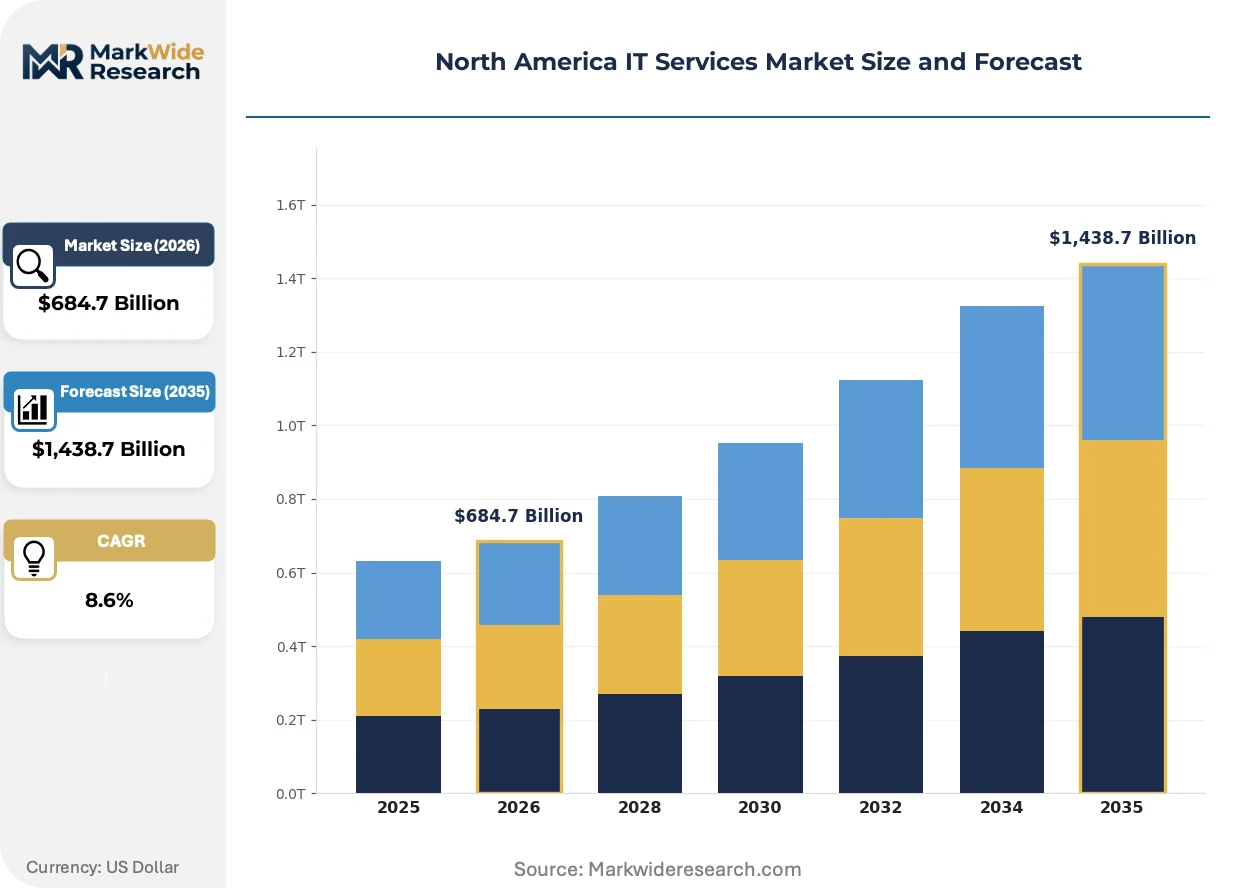
Market Dynamics
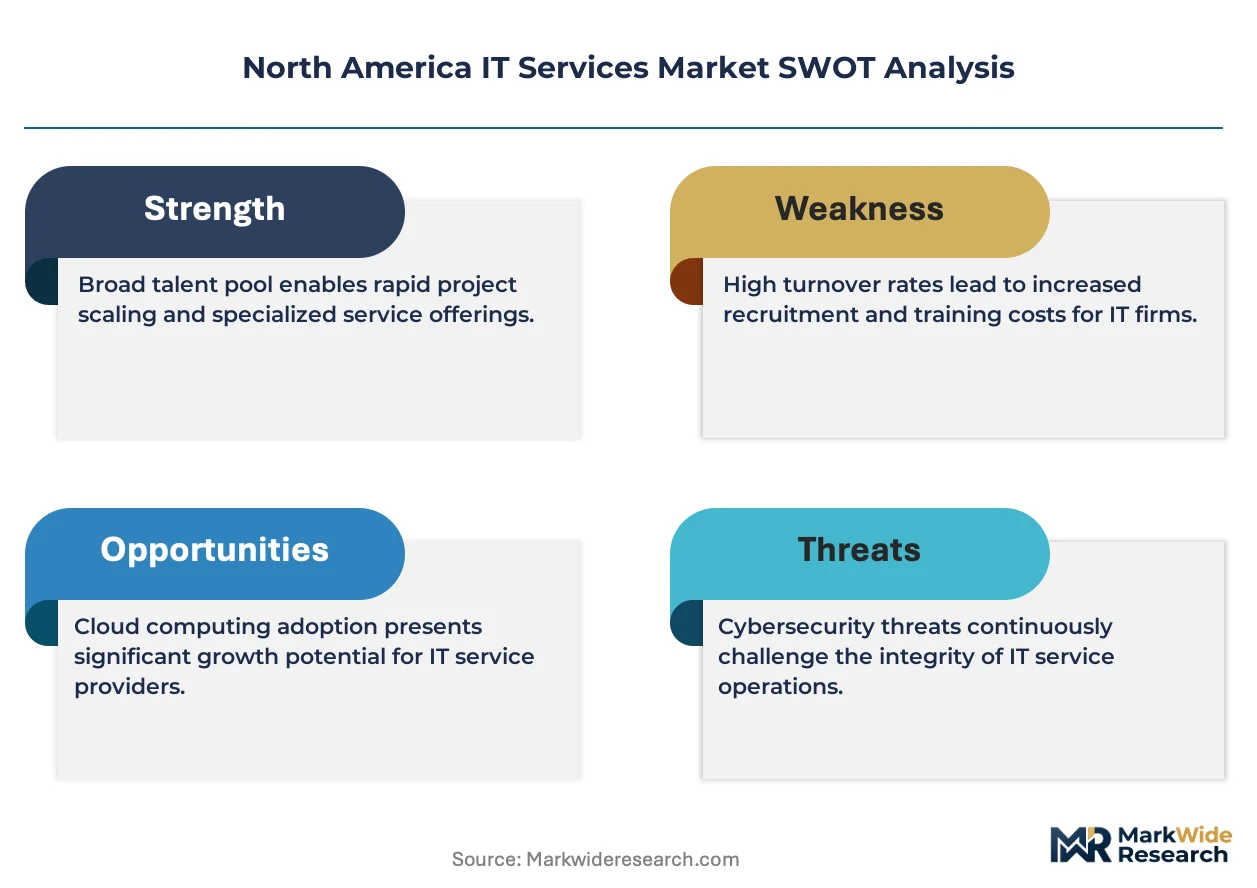
The U.S. Securities and Exchange Commission's climate disclosure mandate is forcing enterprise IT departments to rebuild data infrastructure for audit-ready carbon accounting and emissions tracking. This regulatory pressure is cascading through supply chains, reshaping procurement criteria and vendor selection across financial services, healthcare, and energy verticals.
Growth Catalysts
- Healthcare digitization:Hospital systems across the United States and Canada are accelerating electronic health record modernization and telehealth platform deployment to meet patient access mandates.
- FedRAMP authorization requirements:Federal cloud migration contracts now require continuous monitoring and encryption protocols, creating dedicated demand for cleared personnel and air-gapped infrastructure specialists.
- Quantum-safe cryptography:NIST's post-quantum encryption standards are driving replacement cycles for legacy security stacks in banking and defense applications.
Market Restraints
- Specialized talent scarcity:Clearance-cleared cloud architects and AI/ML engineers command compensation premiums that compress service provider margins.
- State privacy fragmentation:California's Consumer Privacy Act and Virginia's Consumer Data Protection Act impose conflicting data governance requirements, multiplying compliance architecture costs.
- Legacy system entrenchment:COBOL-dependent financial institutions and government agencies face prohibitive migration costs for core transactional platforms.
Strategic Opportunities
- Canadian healthcare IT renewal:Provincial health authorities are modernizing clinical information systems, creating demand for interoperable patient data platforms.
- AI governance tooling:Emerging state AI legislation in Colorado and Illinois is generating demand for model audit, bias detection, and explainability infrastructure.
- Edge-to-cloud orchestration:Manufacturing and logistics operators are converging 5G private networks with containerized workloads for real-time supply chain visibility.
Industry Challenges
- Interoperability debt:Healthcare providers struggle to integrate SaaS point solutions with on-premise electronic health record systems without data fidelity loss.
- Certification timeline compression:FedRAMP and StateRAMP authorization cycles now exceed eighteen months, delaying revenue recognition for cloud service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America IT Services Market |
| Market Size in 2026 | $684.7 Billion |
| Market Size in 2035 | $1,438.7 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Consulting, Managed Services, IT Outsourcing Client Type: Small Enterprises, Medium Enterprises, Large Enterprises, Government Technology: Artificial Intelligence, Machine Learning, Blockchain, Cybersecurity Deployment Model: On-Premises, Hybrid, Public Cloud, Private Cloud |
| Companies Covered | Wipro Limited, Accenture, IBM, Logicalis US, CGI, Microsoft Corporation, Amazon Web Services Professional Services, NWN Corporation, TCS Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America IT Services Market Strategic Shifts
Generative AI capabilities are compressing software development cycles and redefining service delivery models across the North American IT services landscape. This technological inflection is simultaneously creating new service categories and eroding traditional labor-intensive revenue pools.
Agentic AI systems are expanding into enterprise workflow automation, orchestrating multi-step business processes without human intervention. Mid-market financial services firms and regional healthcare networks are piloting autonomous claims processing and clinical documentation workflows. This capability compression is displacing tier-one help desk and routine business process outsourcing contracts.
The SEC's climate disclosure rules are mandating granular emissions data collection across Scope 1, 2, and 3 categories, forcing enterprises to deploy carbon accounting platforms with audit-grade traceability. Industrial conglomerates and asset managers are rebuilding data lakes to support attestation-ready sustainability reporting. Energy and materials sectors face the steepest compliance architecture investments.
Enterprise buyers are unbundling managed services contracts into discrete outcome-based statements of work with penalty clauses for missed service levels. Federal agencies and Fortune 500 procurement departments are replacing multi-year tower arrangements with competitive task order competitions. This pattern is most pronounced in defense and healthcare verticals where budget accountability pressures intensify.
North America IT Services Market Segmentation
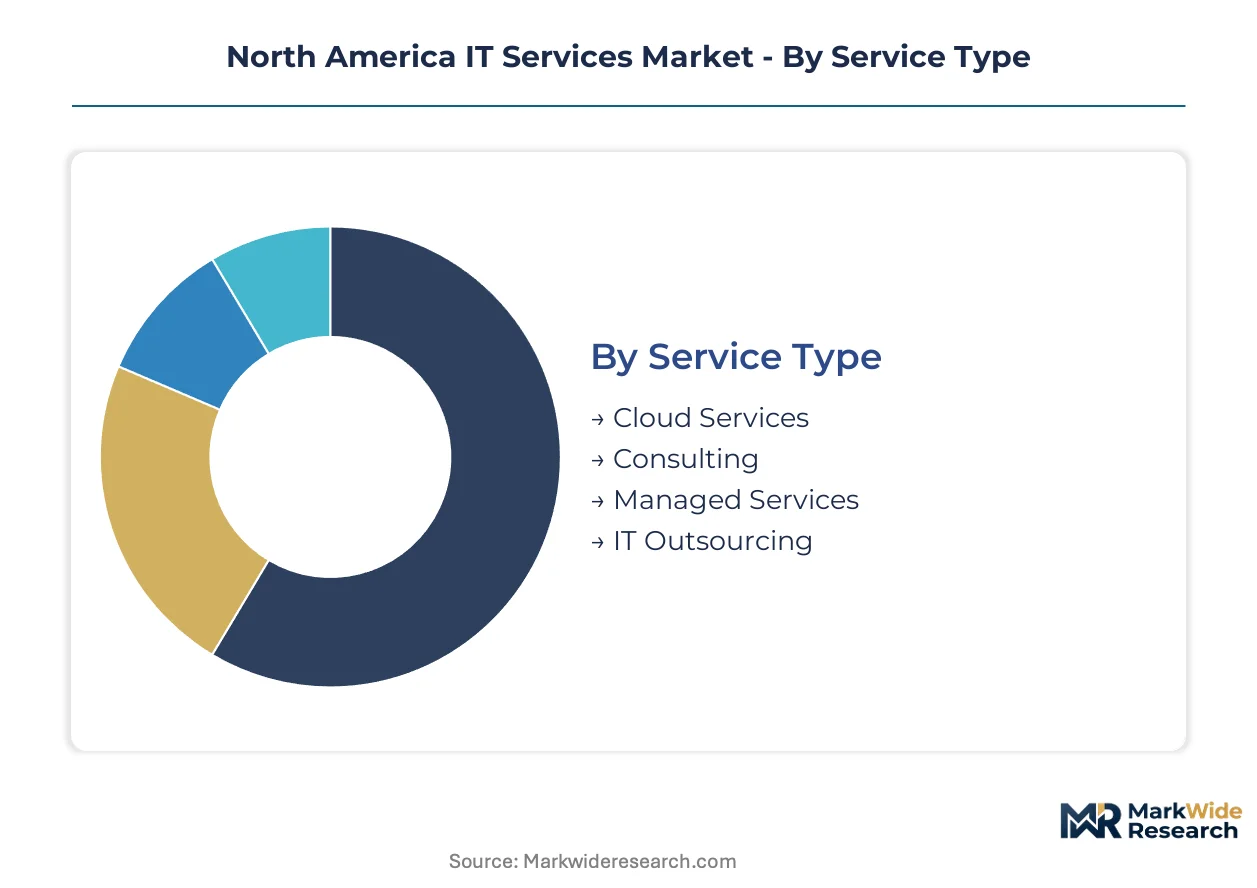
IT services segmentation in North America reveals how procurement authority, security clearance requirements, and legacy infrastructure constraints fragment demand across service categories. Understanding these axes helps vendors calibrate pricing, staffing, and compliance investments to specific buyer archetypes.
Service Type:
Technical sophistication and regulatory burden separate service tiers, with federal authorization requirements creating distinct competitive moats around certain delivery models.
- Cloud Services:Infrastructure-as-a-Service and platform deployments requiring FedRAMP authorization for federal clients. Demand concentrates in U.S. civilian agencies modernizing legacy data centers under OMB cloud-first mandates, with cleared personnel shortages constraining provider capacity.
- Managed Services:Continuous monitoring, patch management, and SLA-governed infrastructure operations delivered through multi-year contracts. Hospital systems across Ontario and Texas are unbundling these from traditional outsourcing to gain operational control.
- Consulting:Advisory engagements spanning cloud migration roadmapping, cybersecurity posture assessments, and regulatory compliance architecture. Canadian provincial health authorities are procuring these services separately from implementation to improve vendor accountability.
- IT Outsourcing:Comprehensive function transfer including help desk, data center operations, and application maintenance. State governments in California and Virginia are reversing prior outsourcing decisions to rebuild in-house technical capabilities.
Mature deployment sits with IT Outsourcing. Newer deployment is concentrated in Cloud Services.
Client Type:
Budget authority and procurement complexity create four distinct buyer segments with incompatible sales cycles and contract structures.
- Large Enterprises:Fortune 500 and equivalent organizations with dedicated procurement teams and multi-source vendor strategies. Financial services firms in New York and Chicago are driving demand for quantum-safe cryptography implementations ahead of NIST deadlines.
- Government:Federal, state, provincial, and municipal entities bound by competitive bidding rules and security clearance requirements. FedRAMP authorization timelines exceeding eighteen months are delaying cloud migration programs across civilian agencies.
- Medium Enterprises:Regional healthcare networks, manufacturing firms, and professional services organizations with limited internal IT capacity. These buyers are adopting managed security services to address cybersecurity insurance requirements.
- Small Enterprises:Independent practices, local governments, and specialty retailers purchasing through channel partners and MSP aggregators. Compliance automation tools are displacing manual security assessments in this segment.
Procurement sophistication peaks with Large Enterprises. Fastest budget growth is appearing in Government.
Technology:
Capability maturity and implementation risk separate technologies into proven infrastructure layers versus experimental competitive differentiators.
- Cybersecurity:Identity management, threat detection, and zero-trust architecture implementations. SEC climate disclosure rules are expanding this category to include carbon accounting platform security and emissions data integrity controls.
- Artificial Intelligence:Generative AI deployment, autonomous workflow orchestration, and predictive analytics. Colorado's emerging AI legislation is creating demand for model audit and bias detection infrastructure among Denver-based financial services firms.
- Machine Learning:Supervised learning models for fraud detection, clinical decision support, and supply chain optimization. Healthcare providers in Massachusetts and British Columbia are piloting these for diagnostic imaging workflows.
- Blockchain:Distributed ledger implementations for supply chain provenance, digital identity, and smart contract automation. Adoption concentrates in trade finance and pharmaceutical serialization applications with stringent traceability requirements.
Commercial traction is deepest with Cybersecurity. Steepest capability expansion is occurring in Artificial Intelligence.
Deployment Model:
Data sovereignty requirements and latency sensitivity are reshaping how workloads distribute across infrastructure layers.
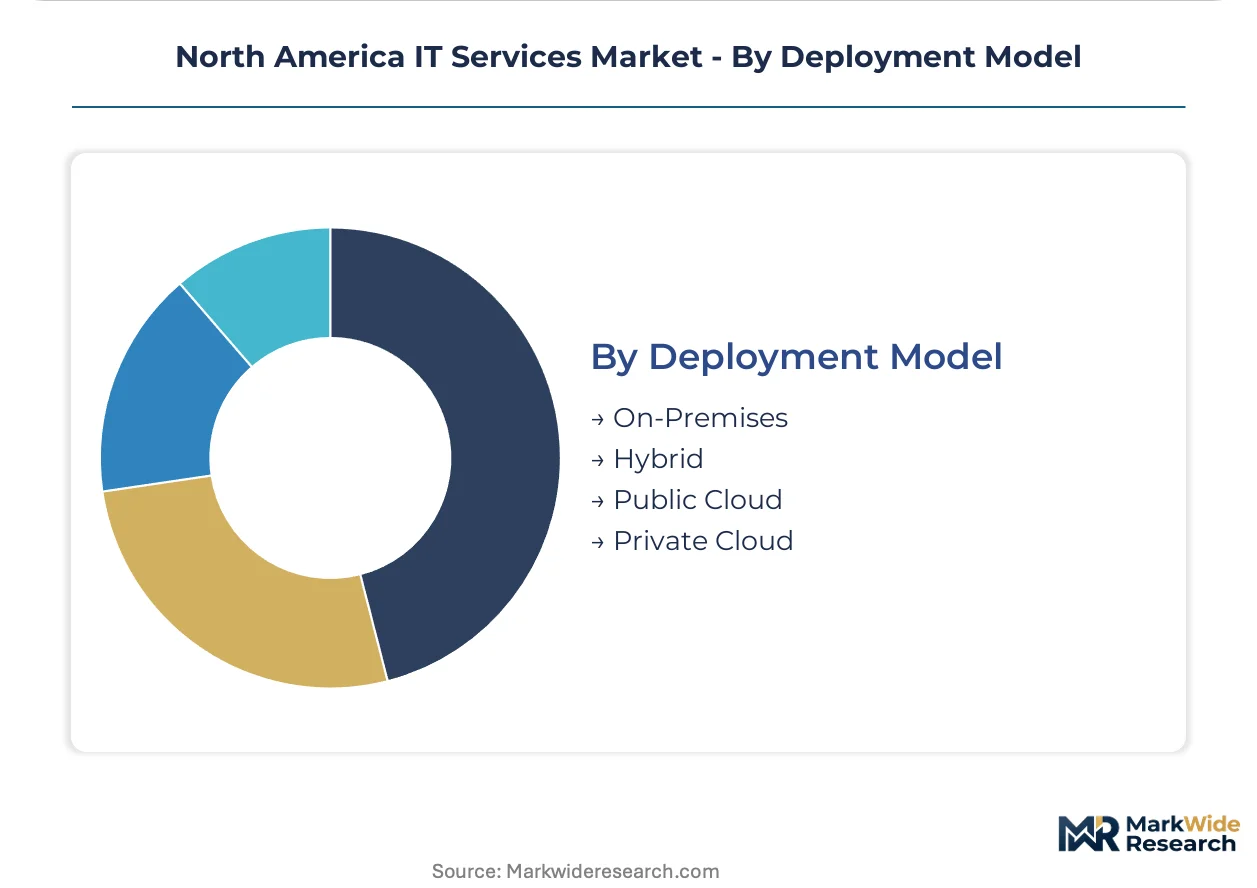
- Hybrid:Orchestrated workloads spanning on-premises infrastructure and multiple cloud providers with unified management planes. Regulated industries including banking and healthcare are adopting this model to satisfy data residency requirements while accessing cloud elasticity.
- Public Cloud:Shared infrastructure services from hyperscale providers with consumption-based pricing. Federal agencies are migrating non-classified workloads to FedRAMP-authorized regions, though authorization backlogs constrain adoption velocity.
- Private Cloud:Dedicated infrastructure environments offering single-tenant isolation and customized security controls. Defense contractors and intelligence community components require these for classified processing environments.
- On-Premises:Traditional data center operations with owned hardware and direct operational control. COBOL-dependent financial institutions and legacy government systems maintain these for core transactional platforms where migration costs prove prohibitive.
Legacy dominance persists with On-Premises. Fastest architectural shift is appearing in Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the dominant share of IT services demand across North America, while Canada and Mexico concentrate specialized delivery capabilities. Production of cleared personnel and air-gapped infrastructure clusters in Washington DC and Toronto corridors.
United States
Federal cloud modernization and SEC climate disclosure compliance drive enterprise spending. FedRAMP authorization timelines exceeding eighteen months constrain provider capacity for civilian agencies. The Washington DC metro area concentrates cleared personnel specialists serving defense and intelligence community contracts.
Canada
Provincial health authorities are modernizing clinical information systems and interoperable patient data platforms. Health Canada and the Directive on Security Management shape vendor certification requirements. Toronto anchors healthcare IT delivery clusters serving Ontario's hospital network digitization programs.
Mexico
Nearshore delivery centers support U.S. enterprise application development and bilingual customer experience operations. The central bank and telecommunications regulator shape data localization requirements. Guadalajara and Mexico City metro areas concentrate software engineering talent pools serving North American clients.
North America IT Services Market Competitive Environment
The competitive structure tilts toward hyperscale cloud providers with federal authorization credentials and global systems integrators with vertical-specific platforms. Tier-one players combine cleared personnel networks with proprietary orchestration tools, while mid-market specialists compete on jurisdictional compliance expertise. Dominant competitive moves include strategic partnerships for air-gapped region access and portfolio diversification into quantum-safe security stacks.
Among India-based systems integrators, Wipro Limited and TCS Limited occupy positions emphasizing scale-driven delivery models and federal contracting presence. Accenture exemplifies the vertical platform archetype through industry-specific transformation frameworks. IBM represents integrated infrastructure and security stack providers competing on hybrid cloud orchestration capabilities.
| Leading Market Players |
|---|
| Wipro Limited |
| Accenture |
| IBM |
| Logicalis US |
| CGI |
| Microsoft Corporation |
| Amazon Web Services Professional Services |
| NWN Corporation |
| TCS Limited |
| Others |
Value Chain & Pricing Dynamics
Federal procurement officers concentrated in Washington DC and civilian agencies drive contract-based long-term pricing with FedRAMP-authorized vendors. This buyer concentration rewards cleared personnel networks and air-gapped infrastructure investments with pricing power, while squeezing providers lacking federal credentials into commodity managed services tiers.
Pricing Analysis
Margin tightening in cloud migration services reflects eighteen-month FedRAMP authorization backlogs that constrain cleared personnel supply. Three-tier pricing structure across premium cleared-credential, standard commercial-cloud, and economy managed-service levels segments buyers by security requirements and procurement sophistication. Cost-down pressure on mid-market consulting accelerates as Canadian provincial health authorities unbundle advisory from implementation contracts. Government buyers exhibit lowest price sensitivity due to mandate-driven procurement, while small enterprises purchasing through MSP aggregators face highest cost consciousness.
Supply Chain Analysis
Direct-to-agency channels handle hyperscale federal demand, while systems integrators and MSP aggregators serve mid-market and small enterprise segments. Talent supply concentrates in the United States, Canada, and India, with cleared personnel pipelines anchored in Washington DC and Toronto corridors. Raw material dependencies rest on specialized cloud infrastructure, quantum-safe encryption modules, and AI/ML compute accelerators. Single-source vulnerability in FedRAMP-authorized personnel creates authorization timeline risk. Distribution runs through cleared staffing networks, hyperscaler partner programs, and vertical-specific platform ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America IT Services Market operates as a cost-of-compliance story where FedRAMP authorization requirements create durable barrier-to-entry moats for credential-holding incumbents.
For Market Incumbents: Anticipate margin compression from agentic AI automation by accelerating proprietary orchestration platform development and quantum-safe security stack integration. Defensive consolidation through cleared personnel acquisition in Washington DC and Toronto corridors counters emerging cloud-native competitors lacking federal credentials. FedRAMP StateRAMP reciprocity expansion threatens to commoditize authorization advantages.
For New Entrants and Emerging Players: Channel partner routes through MSP aggregators serving small enterprise compliance automation offer lowest credential barriers. Canadian provincial healthcare IT renewal presents most penetrable geography given unbundled procurement patterns and interoperability platform demand. Colorado and Illinois AI governance tooling represents white-space application with emerging regulatory tailwinds.
For Investors and Strategic Acquirers: The window for entry favors cleared-credential specialists with established FedRAMP authorization pipelines and healthcare vertical expertise. Long-term viability hinges on hybrid cloud orchestration capabilities and proprietary AI governance tooling. Watch for NIST post-quantum encryption standard finalization as inflection signal accelerating replacement cycle demand.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Shortens eighteen-month timelines to capture civilian agency cloud migration budgets. |
| Quantum-Safe Security Stack Integration | Positions providers ahead of NIST post-quantum encryption standard mandates in banking. |
| AI Governance Tooling Development | Addresses Colorado and Illinois emerging legislation for model audit infrastructure. |
| Canadian Healthcare Partnership Expansion | Captures provincial clinical information system modernization procurement in Ontario. |
| Cleared Personnel Network Acquisition | Secures scarce talent commanding compensation premiums in Washington DC corridor. |
Study Parameters
Independent corroboration across CTO interviews, federal procurement officer discussions, and systems integrator executive consultations underwrites the qualitative findings. Primary fieldwork engaged cloud architects, cybersecurity practice leads, healthcare IT directors, and channel partner managers across the United States and Canada. Secondary validation drew from SEC climate disclosure filings, FedRAMP authorization databases, Canadian provincial procurement records, and hyperscaler capex disclosures. Bottom-up service line sizing and top-down macroeconomic triangulation anchored market estimates.
Comparable-period anchoring to historical federal IT spending patterns and healthcare digitization investment cycles structured the projection horizon. The analytical framework modeled deployment model, client type, service category, and technology adoption velocity dimensions across the analysis window. CAGRs derived from regression analysis against federal budget authority trajectories, provincial health authority capital plans, and enterprise cloud migration pipeline data. Quantum-safe cryptography replacement cycles and AI governance regulatory timeline assumptions shaped segment-specific growth rates.
The model holds under stable federal procurement authorization timelines and continued state privacy framework fragmentation; deviation in FedRAMP reciprocity expansion or NIST standard acceleration would shift provider competitive positioning. Forecasts reflect assumptions regarding cleared personnel supply elasticity and healthcare interoperability mandate enforcement. Periodic stress-testing of base assumptions against authorization backlog trends and provincial budget execution is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Statistics Software Market
Software & Services
MEP Software Market
Software & Services
Product Optimization Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Data Integration Software Market
Software & Services
Global Open Source Services Market
Software & Services
Account Reconciliation Software Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
API Design Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Global Childcare Management Software Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Skills Management Software Market
Software & Services
Global Content Management Systems (CMS) Market