
 Global Cloud-Based Call Center Software Market | 2026-2036
Global Cloud-Based Call Center Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud-Based Call Center Software Market Foresight
North American software infrastructure providers is repositioning global delivery models around multi-tenant cloud architectures. Genesys Telecommunications Laboratories leverages extensive partner ecosystems to sustain enterprise loyalty across Fortune 500 accounts. Cisco Systems anchors its position through deep integration with existing corporate networking stacks. Five9 competes aggressively on AI-native workforce optimization capabilities.
Cloud-based call center software denotes a hosted service model delivering telephony routing, agent management, and customer interaction tools via internet-connected servers rather than on-premise hardware. The architecture typically operates through browser-based dashboards with sub-100-millisecond latency requirements for voice packet transmission, enabling distributed agent pools without dedicated PBX equipment. Public cloud deployment leads current infrastructure choices due to elastic scaling and minimal capital commitment, while hybrid cloud configurations capture growing interest from regulated sectors requiring data residency controls. Interactive voice response and automatic call distribution form the mature revenue core, though analytics and reporting solutions command expanding margin pools as enterprises prioritize real-time sentiment analysis.
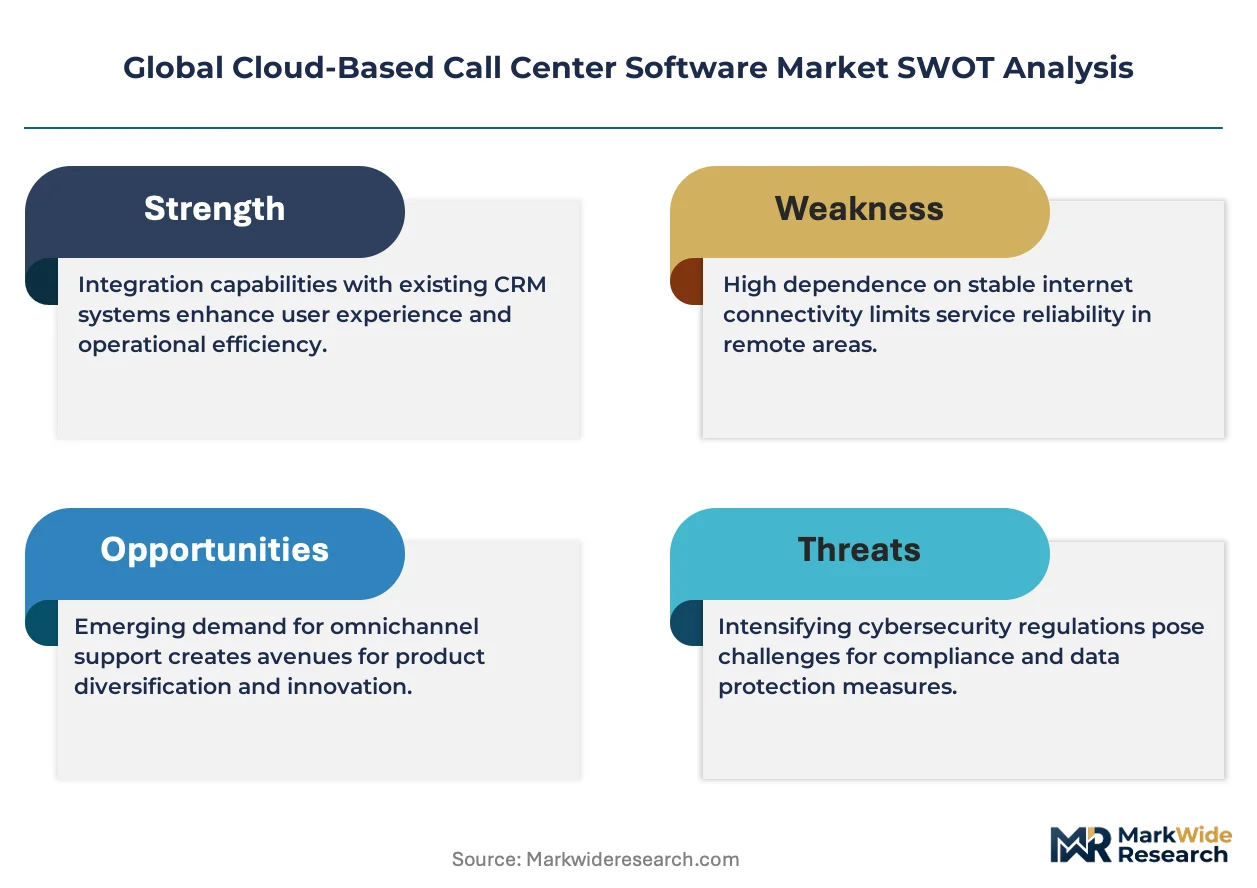
FCC guidelines on robocall mitigation and STIR/SHAKEN authentication protocols shape product roadmaps for US-facing vendors. GDPR data localization requirements and EU AI Act risk classifications constrain how European customer data traverses cloud boundaries. ISO 27001 and SOC 2 Type II certifications function as baseline market access credentials rather than differentiators. Stakeholders must evaluate whether vendor AI training practices align with emerging algorithmic accountability frameworks before committing to long-term platform contracts.
Market Dynamics
Financial services firms are accelerating migration from on-premise PBX systems to multi-tenant cloud architectures, compressing deployment cycles from 18-month hardware refresh programs to 90-day software rollouts.
Growth Catalysts
- GDPR-compliant data architectures:European enterprises are mandating EU-sovereign cloud zones for customer interaction records, expanding addressable market for vendors with localized infrastructure.
- AI-native workforce optimization:Real-time sentiment analysis and predictive routing algorithms are reducing average handle times in high-volume contact centers.
- India IT services scaling:Domestic providers are building captive cloud contact center capacity to serve multinational banking and technology clients from Mumbai and Bengaluru delivery hubs.
Market Restraints
- STIR/SHAKEN compliance costs:FCC-mandated robocall authentication protocols require certificate infrastructure investments that burden mid-market vendors.
- Latency sensitivity:Sub-100-millisecond voice packet transmission requirements constrain viable data center placement to within 50 kilometers of agent populations.
- EU AI Act risk classification:Automated decision-making in customer scoring triggers high-risk system obligations, extending sales cycles by 6-9 months for European deployments.
Strategic Opportunities
- Hybrid cloud configurations:Regulated sectors in Germany and France are adopting split architectures with on-premise voice recording and cloud-based analytics.
- Browser-based agent desktops:Thin-client delivery eliminates endpoint hardware refresh cycles, opening SMB segments previously blocked by capital constraints.
- ISO 27701 privacy certification:Vendors achieving this extension to ISO 27001 are capturing RFP preference in healthcare and government verticals.
Industry Challenges
- Legacy PBX integration complexity:SIP trunk interoperability with decade-old Avaya and Cisco on-premise systems consumes 40% of implementation engineering hours.
- Agent desktop AI literacy gaps:Frontline supervisors lack training to interpret real-time coaching prompts, degrading workforce optimization ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud-Based Call Center Software Market |
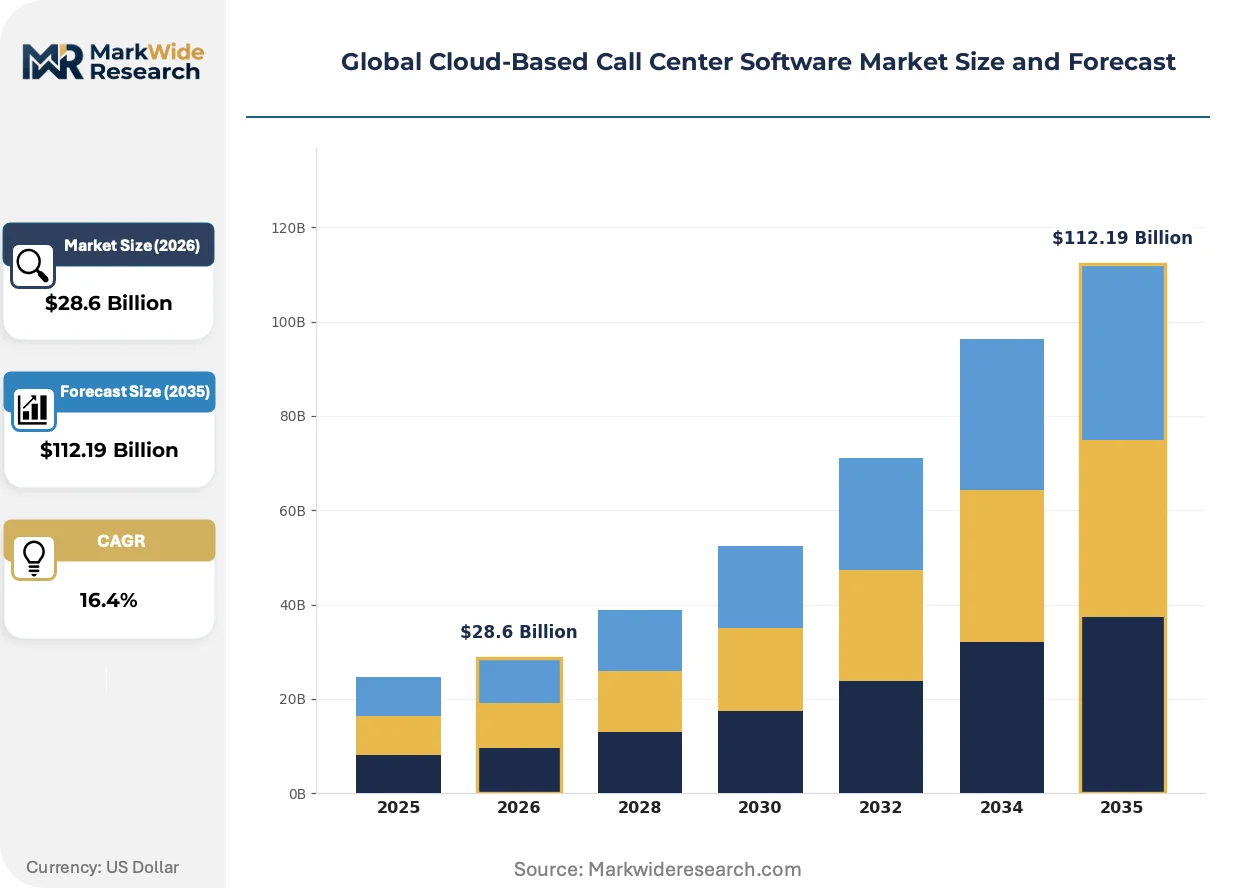
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Application: Customer Support, Telemarketing, Helpdesk, Technical Assistance, Sales Support End User Industry: Telecommunications, Financial Services, E-commerce, Travel & Hospitality, Utilities Solution Offering: Interactive Voice Response, Automatic Call Distribution, Workforce Management, Analytics & Reporting, Omnichannel Support |
| Companies Covered | Genesys Telecommunications Laboratories, Cisco Systems, Five9, Avaya, RingCentral, NICE, 8x8, Talkdesk, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud-Based Call Center Software Market Shifts & Advancements
Cloud-native architectures are overtaking legacy voice infrastructure through browser-based delivery models that eliminate dedicated telephony hardware. Three convergent forces are compressing vendor margins while expanding functional scope.
Real-time speech analytics is overtaking post-call quality assurance in enterprise deployments. These systems transcribe and score 100% of customer interactions against compliance and satisfaction frameworks. Fortune 500 retailers are adopting the technology within 18-month procurement windows. The shift is compressing third-party quality assurance vendor revenue pools by half.
The EU AI Act's risk classification system is reshaping product roadmaps for vendors serving European financial services. High-risk system obligations now mandate human oversight interfaces for automated credit decisions. German and French banking contact centers are delaying AI rollout timelines to embed compliance controls. Vendors without EU-established data processing agreements are losing RFP qualification status.
Consumption-based pricing is displacing perpetual seat licenses in mid-market procurement. Monthly active user metrics now determine contract value for software vendors. United Kingdom insurance brokers and Netherlands e-commerce operators are leading this transition. The model compresses upfront revenue recognition while extending customer lifetime value visibility.
Global Cloud-Based Call Center Software Market Segmentation
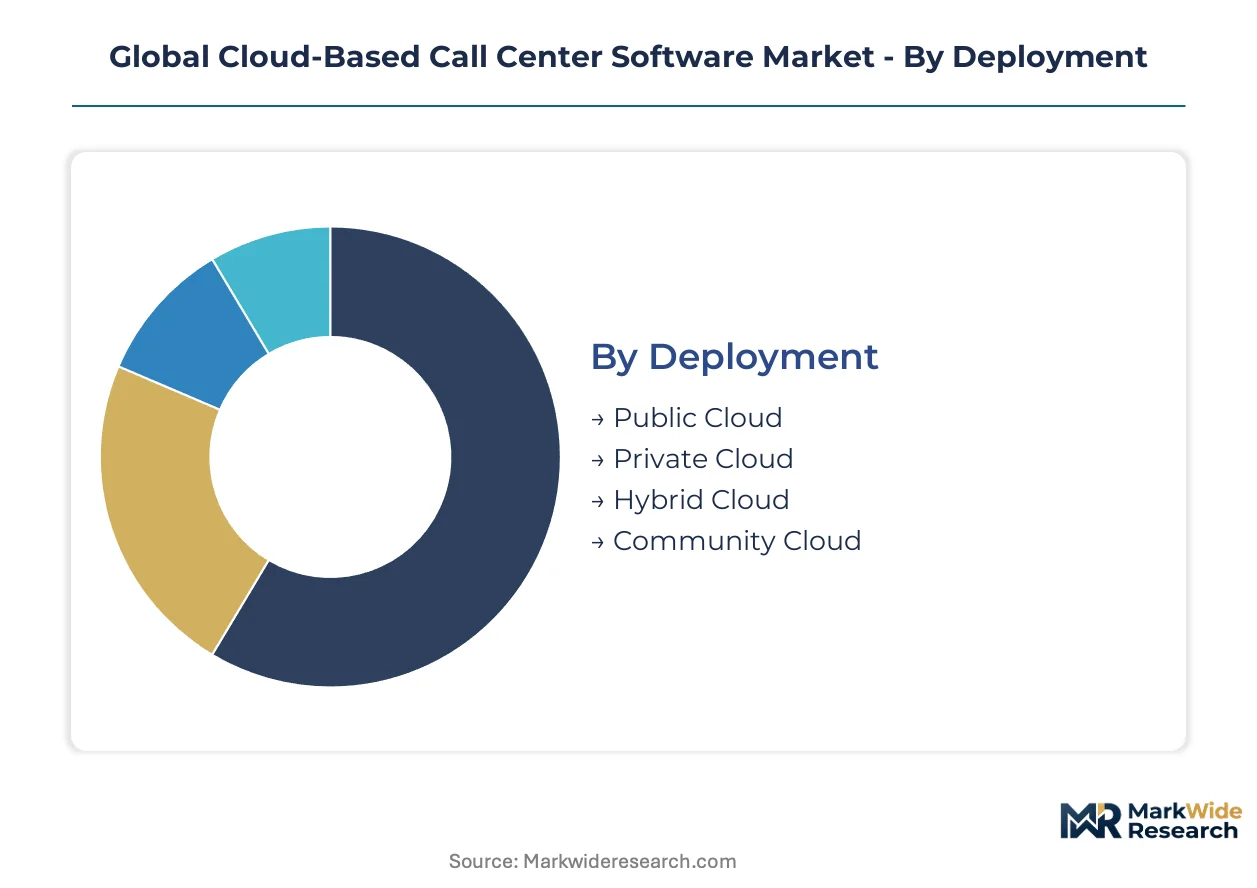
Cloud-based call center software segments diverge sharply on compliance burden. ISO 27001 and SOC 2 Type II certifications function as baseline credentials across deployment modes, while EU AI Act risk classifications and GDPR data residency requirements create tiered vendor qualification barriers.
Deployment:
Public cloud deployments require ISO 27001 and SOC 2 Type II as table stakes, whereas hybrid and private configurations demand additional EU-established data processing agreements for GDPR compliance in European financial services.
- Public Cloud:Multi-tenant infrastructure delivers elastic scaling through browser-based dashboards with sub-100-millisecond latency. Demand concentrates among United States e-commerce operators and India-based IT services providers scaling for multinational clients, driven by minimal capital commitment requirements.
- Hybrid Cloud:Split architectures separate on-premise voice recording from cloud-based analytics. German and French banking contact centers are adopting this model to satisfy data residency controls while accessing AI-native workforce optimization.
- Private Cloud:Single-tenant dedicated infrastructure serves regulated sectors requiring complete data sovereignty. Healthcare and government verticals in Switzerland and Canada mandate this deployment for patient and citizen interaction records.
- Community Cloud:Shared infrastructure among organizations with common compliance profiles. European telecommunications consortiums utilize this model to distribute GDPR compliance costs across member operators.
Leading the category by volume: Public Cloud. Growing fastest: Hybrid Cloud.
Application:
Application segments stratify by average handle time sensitivity and real-time coaching complexity, with customer support and technical assistance commanding premium pricing for sentiment analysis integration.
- Customer Support:High-volume interaction handling with real-time sentiment scoring against satisfaction frameworks. Fortune 500 retailers in the United States deploy these systems within compressed procurement windows to replace third-party quality assurance vendors.
- Technical Assistance:Complex troubleshooting workflows requiring predictive routing algorithms and agent desktop AI literacy. India-based delivery hubs for multinational technology clients drive expansion here.
- Telemarketing:Outbound campaign management with FCC STIR/SHAKEN authentication protocol compliance. United States-facing vendors bear certificate infrastructure investments that burden mid-market operators.
- Helpdesk:Internal employee service desk operations with automated ticket routing. United Kingdom insurance brokers lead adoption of consumption-based pricing models in this segment.
- Sales Support:Opportunity qualification and lead routing with CRM integration. Netherlands e-commerce operators prioritize this application for seasonal demand scaling.
Dominating revenue: Customer Support. Expanding most quickly: Technical Assistance.
End User Industry:
Industry verticals impose distinct regulatory overlays, with financial services triggering EU AI Act high-risk system obligations and telecommunications facing FCC robocall mitigation mandates.
- Financial Services:Automated credit decisions and customer scoring trigger high-risk classification under EU AI Act, extending European sales cycles. German and French banking contact centers delay AI rollouts to embed human oversight interfaces.
- Telecommunications:FCC guidelines on robocall mitigation shape product roadmaps for US-facing vendors. STIR/SHAKEN compliance costs concentrate in this vertical.
- E-commerce:Seasonal demand spikes and omnichannel integration requirements. United States and United Kingdom operators lead migration from on-premise PBX systems to 90-day software rollouts.
- Travel & Hospitality:24/7 multilingual support with real-time booking modification. Mumbai and Bengaluru delivery hubs serve this vertical for multinational clients.
- Utilities:Outage reporting and emergency response with geographic redundancy requirements. Regulated sectors in France and Germany adopt hybrid configurations for critical infrastructure protection.
Highest compliance complexity: Financial Services. Steepest cloud migration trajectory: E-commerce.
Solution Offering:
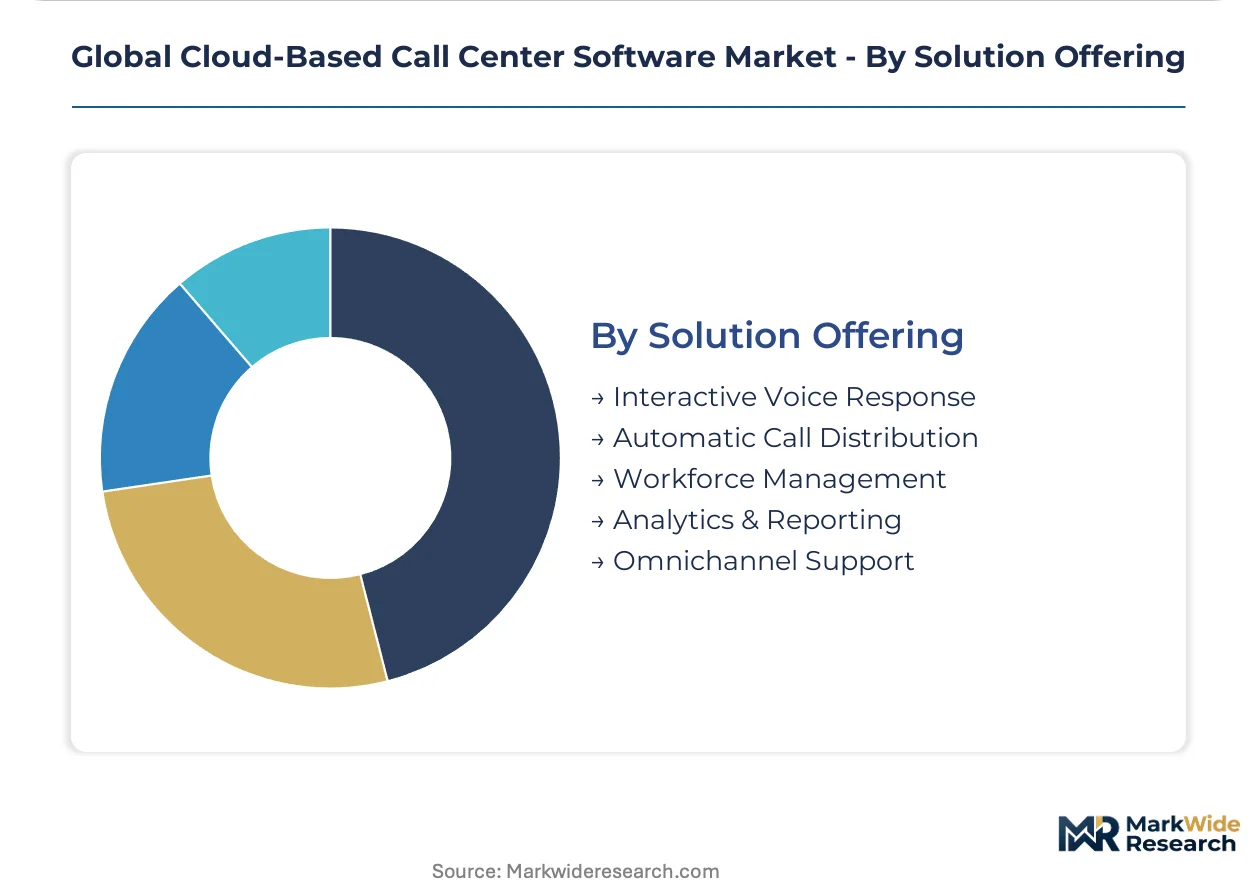
Solution components range from mature telephony infrastructure to emerging analytics platforms, with workforce management and omnichannel support capturing expanding margin pools.
- Interactive Voice Response:Automated menu systems with natural language processing for call routing. Mature revenue core with compressed margins, though speech recognition upgrades sustain replacement demand.
- Automatic Call Distribution:Skills-based routing engines distributing interactions across agent pools. Essential infrastructure component with SIP trunk interoperability consuming implementation engineering hours.
- Analytics & Reporting:Real-time transcription and sentiment scoring against compliance frameworks. Fortune 500 retailers compress third-party quality assurance vendor revenue pools by half through 100% interaction coverage.
- Workforce Management:Scheduling and forecasting tools with AI-native optimization. Predictive routing algorithms reduce average handle times in high-volume India-based contact centers.
- Omnichannel Support:Unified handling of voice, chat, email, and social interactions through single agent desktop. Browser-based thin-client delivery opens SMB segments previously blocked by capital constraints.
Widest installed base: Interactive Voice Response. Gaining share fastest: Analytics & Reporting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadband infrastructure density in the United States anchors cloud contact center deployment velocity, while data sovereignty requirements in Germany and India reshape vendor qualification criteria across three continents.
United States
E-commerce operators and Fortune 500 retailers compress procurement windows to 90-day software rollouts. FCC STIR/SHAKEN authentication protocols impose certificate infrastructure costs on mid-market vendors. Silicon Valley and Seattle clusters concentrate AI-native workforce optimization development for distributed agent pools.
Germany
Banking contact centers in Frankfurt and Munich delay AI rollouts to embed human oversight interfaces for automated credit decisions. EU AI Act high-risk system obligations extend sales cycles by 6-9 months. Baden-Württemberg manufacturing hubs adopt hybrid cloud configurations splitting on-premise voice recording from cloud analytics.
India
Domestic IT services providers scale captive cloud contact center capacity for multinational banking and technology clients. TRAI regulations on data localization influence vendor selection for voice interaction records. Mumbai and Bengaluru delivery hubs drive technical assistance application expansion with predictive routing algorithms.
United Kingdom
Insurance brokers lead consumption-based pricing transitions away from perpetual seat licenses. GDPR-compliant data architectures mandate EU-sovereign cloud zones for customer interaction records. London financial services firms accelerate migration from legacy Avaya and Cisco on-premise PBX systems.
Japan
Enterprise adopters prioritize ISO 27701 privacy certification for healthcare and government verticals. METI guidelines on AI governance shape product roadmaps for automated decision-making systems. Tokyo and Osaka metropolitan areas concentrate omnichannel support demand for seasonal retail scaling.
Global Cloud-Based Call Center Software Market Competitive Landscape
Global majors compete with regional champions across compliance certification and latency-optimized infrastructure deployment. The vendor base stratifies into three tiers: enterprise incumbents with Fortune 500 loyalty, mid-market specialists on consumption-based pricing, and hyperscale cloud platforms integrating contact center modules. Dominant competitive moves include strategic partnerships for SIP trunk interoperability and portfolio diversification into real-time speech analytics.
Within the enterprise incumbent tier, Genesys Telecommunications Laboratories and Cisco Systems exemplify archetypes sustaining account control through deep integration with existing corporate networking stacks. Five9 occupies a position representing AI-native workforce optimization specialists competing aggressively on predictive routing capabilities. These three entities anchor the competitive structure while regional champions in India and Europe capture share through GDPR-compliant data architectures and localized infrastructure deployment.
| Leading Market Players |
|---|
| Genesys Telecommunications Laboratories |
| Cisco Systems |
| Five9 |
| Avaya |
| RingCentral |
| NICE |
| 8x8 |
| Talkdesk |
| Amazon Web Services |
| Others |
Supply & Pricing Matrix
Fortune 500 retailers and India-based IT services providers anchor demand concentration, locking the market into consumption-based SaaS pricing that scales with monthly active user metrics rather than perpetual licensing commitments.
Pricing Analysis
Warranty and service bundling separates premium tiers from standard offerings, with ISO 27701 privacy certification and real-time sentiment analytics included at upper levels while basic voice routing sits unbundled. Three-tier pricing structure across premium, standard, and economy levels differentiates by compliance certification depth and AI-native feature penetration. Cost compression in the mid-market intensifies because STIR/SHAKEN certificate infrastructure burdens smaller vendors without enterprise scale. SMB buyers exhibit highest price sensitivity, constrained by thin-client deployment preferences, while regulated financial services accept premium tiers for EU AI Act compliance coverage.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications function as non-negotiable supplier qualifications, filtering vendor participation before commercial negotiation begins. Cloud infrastructure concentrates in the United States, India, and Germany, with hyperscale data center investments in Mumbai, Frankfurt, and Northern Virginia anchoring regional delivery. Software development draws from specialized labor pools in Bengaluru, Seattle, and Tel Aviv for AI-native workforce optimization engineering. Single-source vulnerability runs through hyperscale cloud platform dependencies for compute and storage. Distribution runs through direct enterprise sales teams and systems integrator partnerships for legacy PBX migration projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EU AI Act compliance costs and certification overhead force sub-scale vendors toward acquisition exits, concentrating share among multi-tenant platform operators with established GDPR data architectures.
For Market Incumbents: Anticipate margin compression from hyperscale cloud platforms integrating contact center modules by deepening SIP trunk interoperability investments and embedding real-time speech analytics as standard features. Lock in Fortune 500 loyalty through exclusive EU-sovereign cloud zone partnerships that emerging entrants cannot replicate without capital scale. For New Entrants and Emerging Players: Begin with browser-based thin-client delivery targeting United Kingdom insurance brokers and Netherlands e-commerce operators where consumption-based pricing transitions create procurement flexibility. Capture technical assistance application share in India-based delivery hubs for multinational technology clients before incumbents localize predictive routing algorithms. For Investors and Strategic Acquirers: The window for entry favors mid-market vendors with ISO 27701 certification progress and established healthcare or government vertical relationships. Watch for inflection when EU AI Act enforcement actions disqualify non-compliant vendors from German and French banking RFPs, compressing viable target pools.| Strategic Initiative | Industry Significance |
|---|---|
| EU-Sovereign Cloud Zone Expansion | Captures GDPR-mandated data residency demand from Frankfurt and Munich banking contact centers. |
| Real-Time Speech Analytics Integration | Compresses third-party quality assurance vendor revenue pools for Fortune 500 retailers. |
| ISO 27701 Privacy Certification Achievement | Opens healthcare and government verticals in Switzerland and Canada to vendor participation. |
| Hyperscale Cloud Platform Partnership | Distributes STIR/SHAKEN compliance infrastructure costs across multi-tenant customer bases. |
| Browser-Based Agent Desktop Development | Eliminates endpoint hardware refresh cycles for SMB segments in United Kingdom insurance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with CTOs, IT procurement officers, contact center operations directors, and systems integrator partners. FCC dockets on robocall mitigation, EU AI Act implementation guidance, and TRAI data localization circulars provided regulatory boundary conditions. SEC filings from hyperscale cloud operators and contact center software vendors supplied financial validation points. Bottom-up deployment counts triangulated against top-down IT services spending estimates.
Granularity-level modeling tracked public, hybrid, private, and community cloud configurations separately across deployment mode, organization size, vertical industry, and regional adoption pattern dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating latency sensitivity constraints and compliance-driven sales cycle extensions. Workforce optimization AI penetration rates and consumption-based pricing transition velocities served as industry-specific forecast inputs throughout the projection horizon.
Underlying measurement precision varies by segment; public cloud deployments carry tighter precision than private cloud configurations given disclosure transparency from hyperscale operators. Forecasts reflect assumptions about EU AI Act enforcement timing and FCC STIR/SHAKEN compliance deadline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Telecom IT Services Market
Software & Services
Video Server Software Market
Software & Services
Acoustic Simulation Software Market
Software & Services
Projector Software Market
Software & Services
Global Printing Software Market
Software & Services
Database Monitoring Software Market
Software & Services
Data Conversion Services Market
Software & Services
Inventory Management Software Market
Software & Services
Content Curation Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Asia-Pacific IT Services Market
Software & Services
Family Law Software Market