
 Valsartan Market | 2026-2036
Valsartan Market Size, Share, and Industry Trends Forecast 2026-2036
Valsartan Market Insights
EMA nitrosamine guidance is recalibrating the cost-of-entry calculus for generic angiotensin receptor blocker manufacturers. Sun Pharmaceutical Industries leverages backward integration into active pharmaceutical ingredient production to control quality verification costs. Novartis AG anchors its position through sustained brand recognition in the originator segment despite patent expiry.
Valsartan is a nonpeptide tetrazole derivative that selectively antagonizes angiotensin II type 1 receptors, typically formulated as the free base or as valsartan sacubitril co-crystals for oral administration at dosages ranging from 40 mg to 320 mg. The compound serves as first-line therapy for hypertension management and post-myocardial infarction cardioprotection through reduction of systolic and diastolic blood pressure. Tablets dominate the product type landscape due to manufacturing scalability and patient compliance familiarity, while the heart failure application segment draws intensifying clinical focus following sacubitril-valsartan combination approvals. Oral delivery mode retains structural precedence over intravenous alternatives because of outpatient treatment economics and established bioavailability profiles.
FDA, EMA, and India's CDSCO collectively enforce evolving nitrosamine impurity thresholds that determine batch release eligibility and import authorization for valsartan APIs. These frameworks compel manufacturers to deploy enhanced analytical testing protocols and revalidate supplier qualifications, directly shaping procurement decisions across hospital and pharmacy channels. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which manufacturing sites will face accelerated inspection schedules.
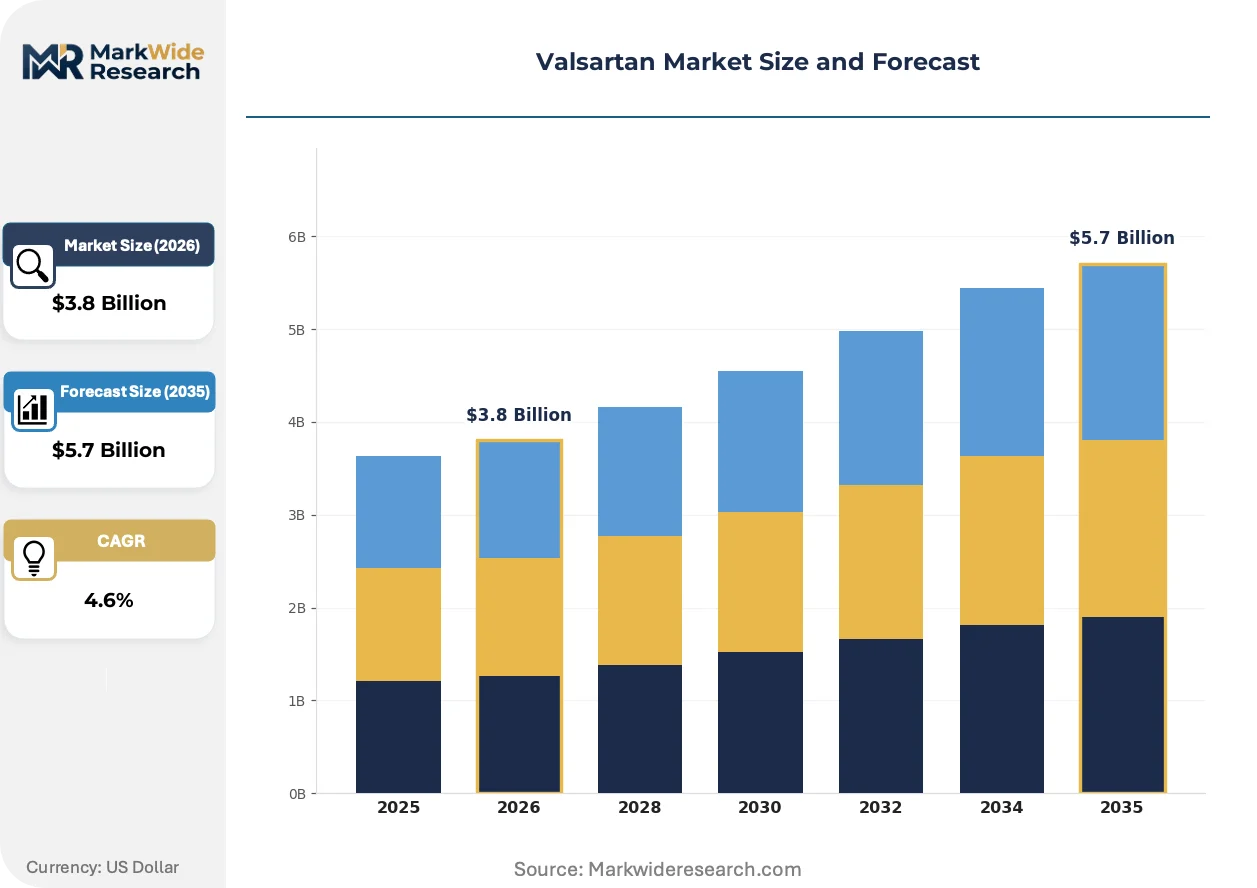
Market Dynamics
Nitrosamine impurity screening protocols are recalibrating active pharmaceutical ingredient sourcing economics, forcing manufacturers to revalidate supplier qualifications and deploy enhanced analytical testing across batch release workflows.
Growth Catalysts
- EMA nitrosamine guidance:Stringent impurity thresholds are accelerating quality verification investments, creating competitive moats for compliant manufacturers in European hospital procurement channels.
- Hypertension prevalence:First-line therapy positioning for systolic and diastolic blood pressure management sustains prescription volumes in outpatient cardiology clinics.
- India contract manufacturing:Oral solid dosage form production clusters in Hyderabad and Ahmedabad attract API-to-finished-dose integration investments from multinational sponsors.
Market Restraints
- API supply concentration:Zhejiang and Jiangsu province manufacturers dominate tetrazole intermediate production, creating single-source vulnerability for European and North American formulators.
- CDSCO import authorization delays:Extended batch release timelines for nitrosamine retesting compress working capital cycles for distributors serving Indian pharmacy networks.
- Sacubitril-valsartan substitution:Heart failure prescribing guidelines in cardiology practices are elevating fixed-dose combination preference over standalone angiotensin receptor blocker therapy.
Strategic Opportunities
- Post-myocardial infarction cardioprotection:Expanded indication labeling for secondary prevention protocols opens reimbursement pathways in German and French hospital formularies.
- Continuous manufacturing technology:FDA Quality by Design incentives for real-time release testing are attracting capital deployment toward direct compression line conversions.
- Middle East hospital procurement:MOHAP and SFDA localization mandates are creating joint-venture openings for sterile and non-sterile oral solid dose capacity in Saudi Arabia and UAE free zones.
Industry Challenges
- Analytical chemistry talent scarcity:LC-MS/MS method development and validation expertise for nitrosamine quantitation commands premium compensation, constraining quality control department scaling.
- Legacy ERP integration:Track-and-trace serialization requirements for EU Falsified Medicines Directive compliance strain SAP and Oracle system architectures at mid-tier generic houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valsartan Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injection, Liquid End User: Clinics, Hospitals, Home Care, Pharmacies Application: Hypertension, Heart Failure, Post-Myocardial Infarction, Diabetic Nephropathy Delivery Mode: Oral, Intravenous, Sublingual, Topical |
| Companies Covered | Sun Pharmaceutical Industries, Lupin Limited, Novartis AG, Zhejiang Huahai Pharmaceutical, Hetero Labs Limited, Teva Pharmaceutical Industries Ltd, Aurobindo Pharma Limited, Dr Reddy's Laboratories Ltd., Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valsartan Market Trends and Innovations
Quality-by-Design methodologies are displacing traditional end-point testing in oral solid dose manufacturing, compressing batch failure rates while elevating real-time analytical capability requirements across contract manufacturing organizations.
Continuous direct compression platforms are expanding into high-volume valsartan tablet production, replacing batch fluid bed granulation with integrated powder feeding, roller compaction, and tablet press sequences. European and North American contract manufacturers are adopting these lines to reduce in-process testing burdens. The technology is expanding into cost-sensitive markets by enabling smaller footprint facilities with reduced cleanroom classification requirements.
FDA nitrosamine guidance updates are mandating risk assessment documentation for all tetrazole-containing APIs, compelling manufacturers to submit comprehensive nitrosamine risk evaluation reports with each drug master file amendment. This regulatory friction is favoring backward-integrated suppliers with captive tetrazole synthesis capabilities. Generic sponsors in the United States are responding by consolidating supplier audits and demanding extended stability data packages from Indian and Chinese API houses.
Hospital procurement consortia are consolidating annual contract negotiations for essential medicines, displacing fragmented pharmacy-level purchasing with centralized tender administration. This buyer concentration is compressing price realization for commodity oral solid doses while elevating service-level requirements for just-in-time delivery. The shift is most visible in German Krankenhausversorgung and French Groupements Hospitaliers de Territoire frameworks.
Valsartan Market Segmentation
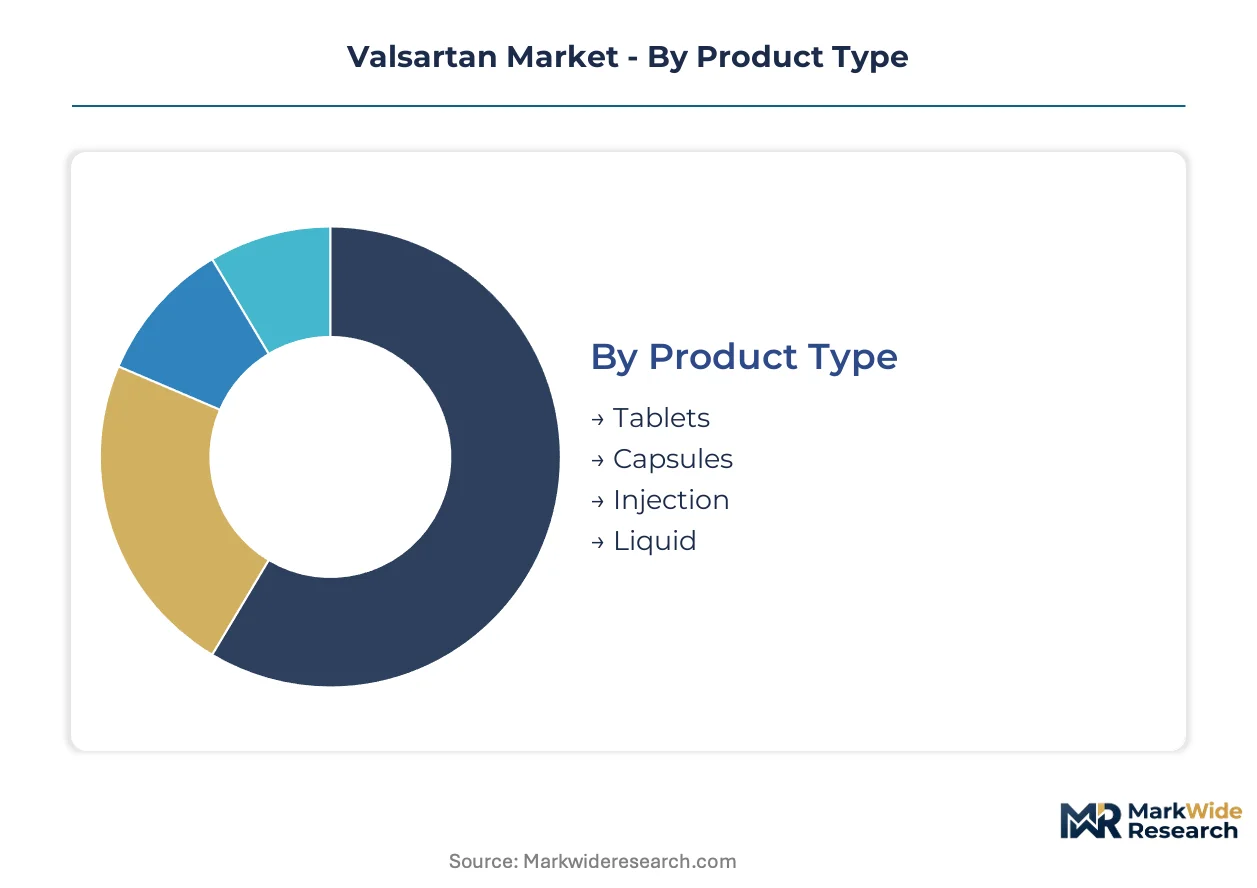
Segmentation in the valsartan market reveals how regulatory certification burdens, route-of-administration economics, and prescriber setting requirements fragment procurement patterns across hospital formulary tiers and retail pharmacy channels.
Product Type:
Tablet formulations carry lighter FDA bioequivalence documentation loads than modified-release alternatives, while injectable presentations require sterile facility inspections that constrain supplier pools.
- Tablets:Immediate-release and film-coated variants dominate outpatient dispensing due to manufacturing scalability and established USP dissolution specifications. Hospital procurement consortia in Germany and France concentrate annual contract volumes here, driven by hypertension maintenance therapy protocols and just-in-time inventory requirements.
- Capsules:Hard gelatin shells accommodate valsartan powder blends with excipient flexibility for moisture-sensitive APIs, though EMA nitrosamine retesting obligations extend batch release timelines. Demand clusters in Indian pharmacy networks where CDSCO import authorization workflows favor established capsule manufacturers with validated tetrazole supply chains.
- Injection:Sterile solution formulations for acute hypertensive crisis management require aseptic processing suites and endotoxin testing protocols that elevate cost-of-entry.
- Liquid:Oral suspension presentations serve pediatric and geriatric populations with swallowing difficulties, compounding pharmacy preparation requirements.
Leading the category by volume: Tablets. Growing fastest: Capsules.
End User:
Procurement authority concentration varies sharply across settings, with hospital consortia wielding tender-based price compression while home care channels prioritize patient adherence packaging.
- Hospitals:Centralized purchasing through German Krankenhausversorgung and French Groupements Hospitaliers de Territoire frameworks aggregates demand for essential medicines, compressing unit economics while elevating service-level requirements for stockless inventory programs.
- Clinics:Outpatient cardiology practices in the United States drive sacubitril-valsartan combination prescribing, displacing standalone ARB volumes through heart failure guideline adherence.
- Pharmacies:Community retail channels in India manage working capital cycles around CDSCO batch release delays for nitrosamine retesting.
- Home Care:Long-term hypertension management programs emphasize blister packaging and adherence monitoring technologies for elderly patient populations.
Hospitals command the largest procurement volumes. Home care channels are expanding most quickly on aging-population demographics.
Application:
Indication-specific labeling determines reimbursement tier placement and formulary inclusion depth across national health technology assessment frameworks.
- Hypertension:First-line systolic and diastolic blood pressure management indication sustains the broadest prescriber base, with JNC-8 and ESC/ESH guideline alignment supporting generic substitution rates exceeding 90% in mature markets.
- Heart Failure:Sacubitril-valsartan co-crystal approvals for reduced ejection fraction patients are elevating fixed-dose combination preference over standalone therapy in cardiology practice patterns.
- Post-Myocardial Infarction:Secondary prevention labeling opens specialized reimbursement pathways in German and French hospital formularies.
- Diabetic Nephropathy:Renoprotective indication utilization concentrates in endocrinology co-management protocols with nephrology consultation requirements.
Hypertension anchors volume. Heart failure applications are gaining share fastest on combination therapy uptake.
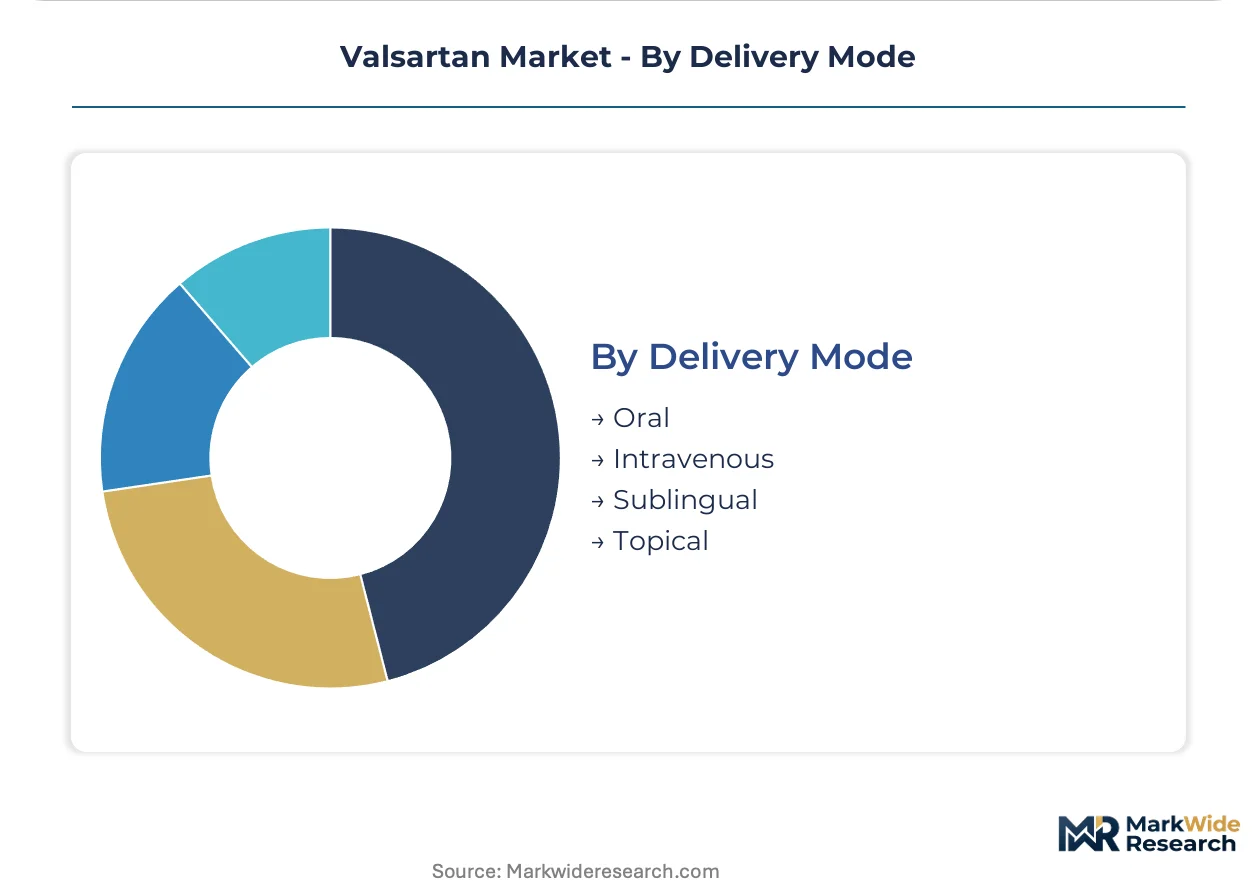
Delivery Mode:
Route selection locks in manufacturing facility classification, bioavailability study requirements, and cold chain infrastructure needs that shape supplier qualification timelines.
- Oral:Bioavailability profiles exceeding 25% for valsartan free base eliminate first-pass metabolism concerns, supporting outpatient treatment economics across tablet, capsule, and liquid presentations with ambient storage requirements.
- Intravenous:Acute hypertensive emergency administration requires sterile manufacturing suites and USP <797> compliance that limit supplier pools to specialized CMOs with validated aseptic processing lines.
- Sublingual:Rapid absorption formulations for breakthrough hypertension episodes face limited commercial penetration due to taste masking challenges and stability concerns.
- Topical:Transdermal patch development for valsartan remains preclinical, constrained by molecular weight and lipophilicity barriers to percutaneous absorption.
Oral delivery dominates volume. Intravenous presentations show steepest expansion trajectory on hospital acute care protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Visakhapatnam Special Economic Zone and Pithampur Pharma SEZ concentrate API-to-finished-dose manufacturing for European and North American export markets. These tax-advantaged enclaves attract multinational sponsors seeking nitrosamine-compliant production capacity.
United States
Hospital procurement consortia and outpatient cardiology practices drive prescription volumes for hypertension and heart failure indications. FDA nitrosamine guidance mandates risk assessment documentation for all tetrazole-containing APIs, compelling manufacturers to submit comprehensive evaluation reports with each drug master file amendment. New Jersey and North Carolina host formulation facilities serving domestic hospital networks.
Germany
Krankenhausversorgung frameworks aggregate demand for essential medicines through centralized tender administration, compressing unit economics while elevating service-level requirements. EMA nitrosamine thresholds determine batch release eligibility for valsartan APIs imported from Asian manufacturing sites. Bavaria and North Rhine-Westphalia concentrate quality control laboratories serving European hospital consortia.
India
Contract manufacturing clusters in Hyderabad and Ahmedabad attract API-to-finished-dose integration investments from multinational sponsors seeking cost-efficient oral solid dosage production. CDSCO import authorization delays for nitrosamine retesting compress working capital cycles for distributors serving pharmacy networks. Maharashtra and Gujarat house backward-integrated suppliers with captive tetrazole synthesis capabilities.
China
Zhejiang and Jiangsu province manufacturers dominate tetrazole intermediate production, creating single-source vulnerability for European and North American formulators. NMPA alignment with ICH nitrosamine guidelines drives enhanced analytical testing protocol adoption across API export facilities. Taizhou and Taixing chemical industrial parks concentrate intermediate synthesis operations serving global generic sponsors.
Saudi Arabia
SFDA localization mandates create joint-venture openings for sterile and non-sterile oral solid dose capacity in Saudi free zones serving Gulf Cooperation Council hospital networks. MOHAP procurement frameworks in neighboring UAE reinforce regional demand for import-substituted cardiovascular therapeutics. Jeddah and Riyadh industrial cities attract pharmaceutical manufacturing investments targeting Middle East hospital procurement channels.
Valsartan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the valsartan manufacturing base. The market structure fragments across three tiers: backward-integrated API producers controlling tetrazole supply chains, formulation-focused houses dependent on external active pharmaceutical ingredient sourcing, and originator-branded operations sustaining patent-expired recognition. Strategic moves concentrate on supplier audit consolidation, captive intermediate production, and continuous manufacturing line conversions to reduce in-process testing burdens.
Among Indian pharmaceutical conglomerates, Sun Pharmaceutical Industries and Dr Reddy's Laboratories occupy positions exemplifying backward-integrated API-to-finished-dose capabilities. Zhejiang Huahai Pharmaceutical represents the Chinese specialist archetype with concentrated tetrazole intermediate operations. Novartis AG anchors the originator-tier positioning through sustained brand recognition in cardiovascular therapeutic categories despite long-completed patent expiry.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries |
| Lupin Limited |
| Novartis AG |
| Zhejiang Huahai Pharmaceutical |
| Hetero Labs Limited |
| Teva Pharmaceutical Industries Ltd |
| Aurobindo Pharma Limited |
| Dr Reddy's Laboratories Ltd. |
| Mylan N.V. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap API producers in Zhejiang and Gujarat anchor tetrazole intermediate supply, translating concentrated ownership into disciplined capacity expansion and selective customer qualification that shields pricing from spot-market volatility while hospital procurement consortia squeeze finished-dose margins.
Pricing Analysis
Short lead-time premiums command pricing separation from spot inventory liquidations as hospital procurement consortia compress contract durations. Three-tier pricing structure across nitrosamine-certified premium, standard CDSCO-authorized, and economy non-validated tiers reflects EMA batch release status and tetrazole provenance. Cost compression in the economy tier intensifies because Indian distributors absorb working capital strain from extended retesting timelines. Community pharmacy networks in India exhibit highest price sensitivity while German Krankenhausversorgung frameworks prioritize service-level guarantees over unit cost.
Supply Chain Analysis
Analytical chemistry talent scarcity in Hyderabad and Ahmedabad constrains quality control department scaling at contract manufacturing organizations serving export markets. API production draws from Zhejiang tetrazole specialists, Indian finished-dose houses, and North American formulation facilities. Raw material dependencies center on 4-cyanobenzyl bromide, valine methyl ester, and sodium azide. Single-source vulnerability pervades tetrazole intermediate supply. Distribution runs through hospital procurement consortia, pharmacy wholesale distributors, and direct-to-institution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA nitrosamine guidance recalibrates cost-of-entry calculus, forcing sub-scale generic manufacturers toward exit or acquisition as compliance investments outstrip margin recovery.
For Market Incumbents: Hedge sacubitril-valsartan substitution risk by securing post-myocardial infarction indication labeling in German and French hospital formularies. Anchor backward integration into tetrazole synthesis to control quality verification costs and supplier audit consolidation. Continuous manufacturing line conversions reduce in-process testing burdens and defend against price erosion from spot-market competitors. For New Entrants and Emerging Players: CDSCO import authorization delays in India open a window for domestic API-to-finished-dose integrators with validated nitrosamine testing protocols. Target pediatric and geriatric liquid formulation segments underserved by tablet-centric incumbents. Pursue joint-venture structures with Saudi free zone developers to capture MOHAP and SFDA localization mandates. For Investors and Strategic Acquirers: Accelerated FDA inspection schedules at Zhejiang API facilities is the leading indicator that supply concentration risk will trigger procurement diversification toward Indian backward-integrated houses. Frame long-term viability around five-to-ten-year regulatory compliance moats rather than volume scale. Monitor EMA nitrosamine risk evaluation report submission rates as inflection signal for supplier qualification pipeline depth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tetrazole Synthesis | Captive intermediate production shields Sun Pharmaceutical and Dr Reddy's from CDSCO import authorization delays. |
| Continuous Manufacturing Line Conversion | FDA Quality by Design incentives for real-time release testing attract capital toward direct compression platforms. |
| Post-Myocardial Infarction Indication Expansion | Specialized reimbursement pathways in German Krankenhausversorgung frameworks offset sacubitril-valsartan substitution. |
| Joint Venture in Saudi Free Zones | SFDA localization mandates create sterile and non-sterile oral solid dose capacity for Gulf Cooperation Council hospital networks. |
| Analytical Chemistry Talent Acquisition | LC-MS/MS method development expertise commands premium compensation, constraining quality control scaling at mid-tier houses. |
Research Methodology
Independent corroboration across FDA drug master file amendments, EMA nitrosamine risk evaluation reports, and CDSCO import authorization records underwrites the qualitative findings. Primary interviews with regulatory affairs leads at API manufacturers, formulary directors at German hospital consortia, and procurement managers at Indian pharmacy distributors combined with secondary validation from ClinicalTrials.gov entries, SEC 10-K pharmaceutical filings, and hospital procurement database extracts. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis triangulate market sizing.
Comparable-period anchoring to historical nitrosamine recall events and subsequent supply reconfiguration patterns informed the projection horizon. Segmentation dimensions span dosage form, delivery mode, application indication, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to hypertension prevalence trajectories, heart failure guideline adoption rates, and contract manufacturing capacity expansion announcements across the analysis window.
Caveats apply where EMA nitrosamine threshold revisions, CDSCO inspection backlog clearance, or tetrazole intermediate supply disruptions could materially shift the outlook. Forecasts reflect assumptions around regulatory harmonization pace and hospital procurement consolidation trajectory. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antithrombin Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market