
 Nanoparticle Contract Manufacturing Market | 2026-2036
Nanoparticle Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoparticle Contract Manufacturing Market Foresight
North American specialty chemical producers is consolidating nanoparticle contract manufacturing capacity after years of fragmented pilot-scale operations. Evonik Industries AG leverages its lipid nanoparticle platform to anchor pharmaceutical client relationships across multiple continents. Merck KGaA sustains integrated supply chains spanning excipient production through finished nanomedicine formulation. Ascendia Pharmaceuticals competes on complex nanosuspension and amorphous dispersion technologies for poorly soluble APIs.
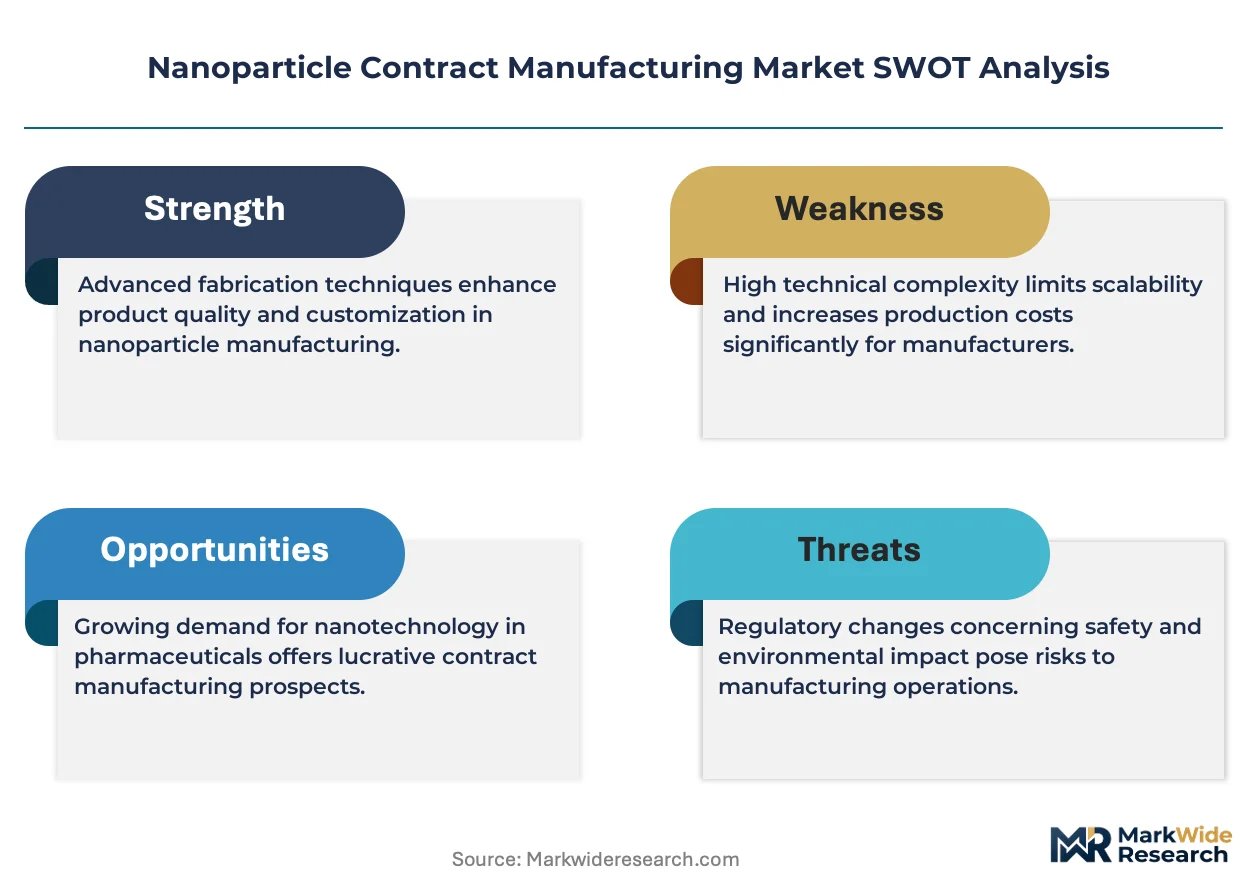
Nanoparticle contract manufacturing encompasses the outsourced production of engineered particles with at least one dimension between 1 and 100 nanometers, typically synthesized through controlled precipitation, emulsification, or top-down milling to achieve precise size distribution and surface functionalization for targeted drug delivery, catalytic enhancement, or electronic property modification. Metallic nanoparticles dominate current revenue contribution due to established gold and silver particle demand in diagnostics and antimicrobial coatings, while polymeric nanoparticles represent the fastest-expanding material category as PLGA and PEGylated systems displace conventional liposomal formulations in oncology applications. The drug delivery application segment captures the deepest margin pools, though catalysis applications in green chemistry processes are attracting accelerated capital allocation from process industry clients.
The FDA's nanotechnology guidance framework and the EMA's quality guidelines for nanomedicines impose stringent characterization requirements that filter out underqualified contract manufacturers and elevate compliance costs for remaining participants. REACH registration obligations in Europe and evolving EPA reporting standards for engineered nanomaterials in the United States further shape market access conditions and client qualification timelines. Stakeholders must monitor how regulatory convergence between FDA and EMA approaches to bioequivalence for generic nanomedicines will reshape competitive barriers and outsourcing decision criteria for originator and biosimilar developers alike.
Market Dynamics
Pharmaceutical outsourcing of lipid nanoparticle production is compressing development timelines for mRNA therapeutics, forcing contract manufacturers to integrate continuous processing capabilities or lose multi-year client commitments to competitors with proven scale-up infrastructure.
Growth Catalysts
- mRNA vaccine platform expansion:Post-pandemic therapeutic applications beyond infectious disease are pulling dedicated manufacturing capacity online across North American and European production clusters.
- FDA nanotechnology guidance harmonization:Standardized characterization protocols for nanomedicines are reducing client qualification cycles and accelerating technology transfer between sponsors and contract manufacturers.
- PLGA-PEG copolymer formulation advances:Tunable degradation profiles in polymeric nanoparticles are opening oncology applications previously dominated by conventional liposomal delivery systems.
Market Restraints
- Specialized excipient supply concentration:Ionizable lipid production for LNP systems depends on a limited supplier base concentrated in Germany and Switzerland, creating input vulnerability.
- EMA quality guideline compliance costs:Batch release testing for nanomedicines requires analytical capabilities beyond standard pharmaceutical quality control, elevating capital barriers for new entrants.
- Top-down milling equipment limitations:Achieving sub-100 nanometer particle size distributions with narrow polydispersity remains technically constrained for high-melting-point active pharmaceutical ingredients.
Strategic Opportunities
- India CDMO capacity buildout:CDSCO's streamlined approval pathways for nanosimilar products are attracting investment in specialized formulation facilities near Hyderabad and Ahmedabad.
- CRISPR delivery vector convergence:Lipid nanoparticle systems optimized for mRNA are transferring directly to gene editing applications, expanding addressable therapeutic categories without platform redevelopment.
- Green chemistry catalysis mandates:EU Green Deal industrial decarbonization targets are pulling demand for metal nanoparticle catalysts in pharmaceutical and fine chemical process intensification.
Industry Challenges
- Process analytical technology integration:Real-time particle size monitoring during continuous manufacturing requires cross-functional expertise spanning spectroscopy, fluid dynamics, and GMP validation that remains scarce in the talent market.
- IP thickets around surface functionalization:PEGylation chemistries and targeting ligand conjugation methods are encumbered by overlapping patent estates, complicating freedom-to-operate assessments for client projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoparticle Contract Manufacturing Market |
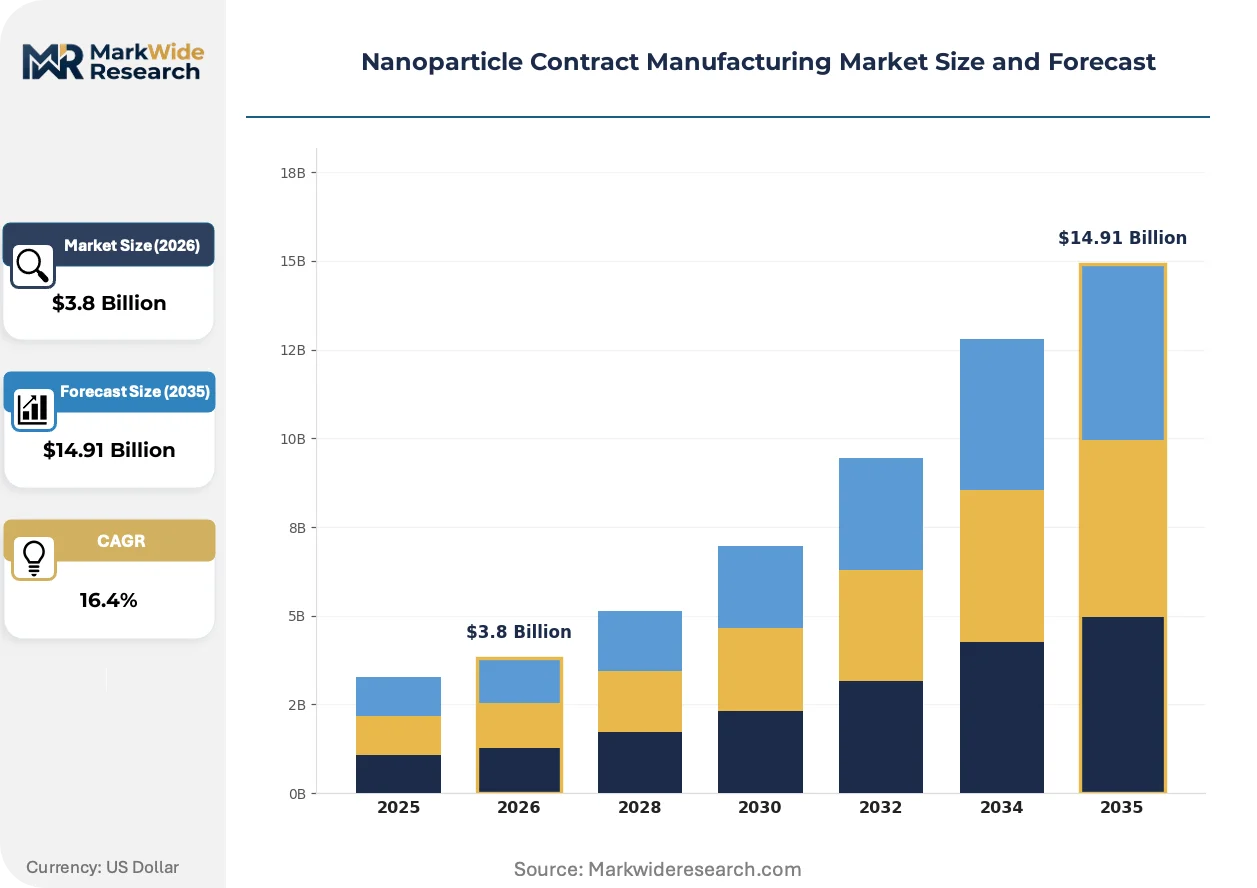
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Sol-gel, Chemical Vapor Deposition, Laser Ablation, Ball Milling Material Type: Metallic Nanoparticles, Polymeric Nanoparticles, Ceramic Nanoparticles, Composite Nanoparticles End User: Pharmaceuticals, Electronics, Energy, Biomedical Application: Drug Delivery, Catalysis, Imaging, Sensors |
| Companies Covered | Evonik Industries AG, Merck KGaA, American Elements, AstraZeneca, Ardena Holding NV, Ascendia Pharmaceuticals, Nanocomposix, SkySpring Nanomaterials, MCH Nano Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoparticle Contract Manufacturing Market Shifts & Advancements
Continuous manufacturing platforms are displacing batch processing as the default production modality, while regulatory convergence between FDA and EMA frameworks is compressing dual-approval timelines for multinational sponsors.
Microfluidic mixing technology is electrifying lipid nanoparticle synthesis by replacing conventional bulk emulsification with precisely controlled laminar flow conditions. Gene therapy developers and mRNA vaccine sponsors are adopting these platforms at pilot scale within twelve-month procurement cycles. The shift is compressing particle size distribution variability and enabling real-time process control that batch methods cannot replicate.
REACH registration obligations for engineered nanomaterials are tightening supply chain transparency requirements across European manufacturing networks. ECHA's updated guidance on substance identification for nanoforms is forcing raw material suppliers to disclose production methods previously treated as proprietary. Polymeric nanoparticle manufacturers serving EU markets are responding by qualifying alternative excipient sources or absorbing registration costs into long-term client contracts.
Biopharma procurement teams are consolidating supplier relationships around full-service CDMOs with integrated analytical and regulatory capabilities. Small and mid-cap drug developers are abandoning fragmented outsourcing models that separate formulation development from commercial manufacturing. The concentration is most visible in the United States, where venture-backed oncology companies now prioritize single-source partnerships over multi-vendor qualification strategies.
Nanoparticle Contract Manufacturing Market Segmentation
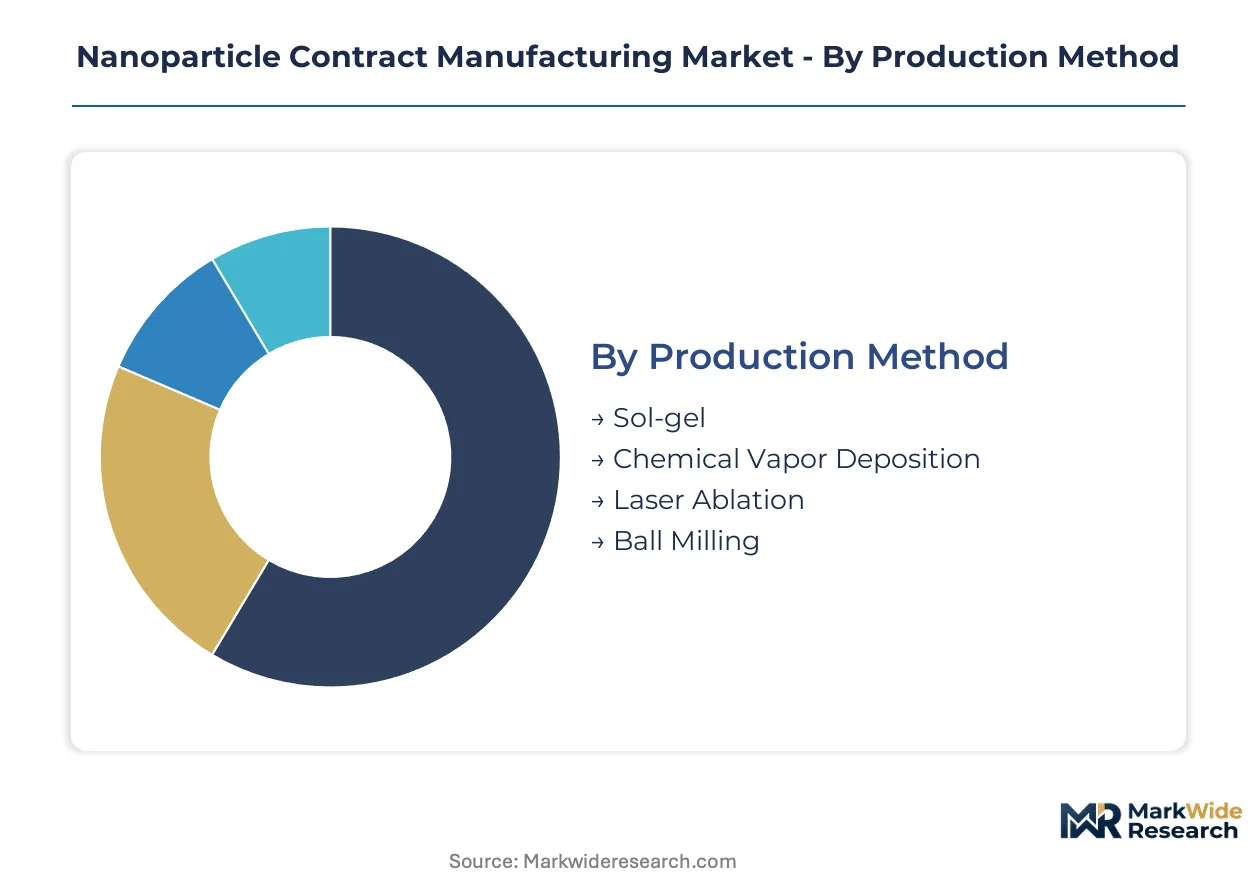
Segmentation in nanoparticle contract manufacturing reveals distinct capital requirements and margin profiles across synthesis methods and material categories. Contract manufacturers align facility investments with client demand patterns in mRNA therapeutics, oncology formulations, and green chemistry applications.
Production Method:
Capital intensity varies sharply across synthesis platforms, with vapor-phase and continuous-flow systems demanding substantially higher upfront investment than mechanical milling operations.
- Sol-gel:Wet chemical synthesis enables precise control over particle morphology and surface chemistry through hydrolysis and condensation reactions. Pharmaceutical clients in the United States specify sol-gel methods for silica-based drug carriers where batch-to-batch consistency determines regulatory approval timelines.
- Chemical Vapor Deposition:Gas-phase synthesis produces ultra-high-purity metallic and ceramic nanoparticles with exceptional crystallinity. Electronics manufacturers in Germany and Japan commission CVD capacity for quantum dot and semiconductor applications where contamination tolerance approaches parts-per-billion thresholds.
- Laser Ablation:Pulsed laser irradiation of solid targets generates ligand-free nanoparticles without chemical precursors. Biomedical researchers value this method for gold and silver colloids used in diagnostic assays.
- Ball Milling:Top-down mechanical attrition reduces bulk powders to nanoscale dimensions using high-energy grinding media. Energy sector clients employ ball milling for scalable production of battery electrode materials.
Chemical Vapor Deposition absorbs the bulk of installed capacity; Sol-gel is expanding most quickly.
Material Type:
Raw material sourcing complexity and excipient qualification burdens create divergent supply chain risk profiles across material categories.
- Metallic Nanoparticles:Gold, silver, and iron oxide particles serve established diagnostic imaging and antimicrobial coating markets with reproducible synthesis protocols. Demand concentrates in United States and German healthcare clusters where FDA and EMA quality guidelines enforce stringent batch characterization.
- Polymeric Nanoparticles:PLGA-PEG copolymer systems enable tunable drug release kinetics and surface functionalization for targeted oncology delivery. CDSCO approval pathway streamlining in India is pulling manufacturing investment toward Hyderabad and Ahmedabad production zones.
- Ceramic Nanoparticles:Oxide and nitride ceramics provide thermal stability and mechanical hardness for catalytic and structural applications. Energy sector procurement favors ceramic nanoparticles for solid-state battery electrolytes.
- Composite Nanoparticles:Hybrid core-shell architectures combine multiple material properties in single particle systems. Electronics manufacturers specify composite structures for multifunctional sensor platforms.
Metallic Nanoparticles command the deepest existing capacity base; Polymeric Nanoparticles are climbing the fastest.
End User:
Customer sophistication and regulatory burden intensity segment the addressable market into distinct service tiers with varying margin structures.
- Pharmaceuticals:mRNA vaccine sponsors and gene therapy developers require GMP-compliant lipid nanoparticle production with integrated analytical and regulatory support. Boston-Cambridge and Research Triangle Park clusters host the densest concentration of qualified CDMO facilities serving this segment.
- Electronics:Semiconductor and display manufacturers demand sub-10 nanometer particle size distributions with tight polydispersity indices. Japanese and South Korean electronics conglomerates specify dedicated production lines to prevent cross-contamination.
- Energy:Battery and fuel cell developers commission metal oxide and carbon-based nanoparticles for electrode and catalyst applications. EU Green Deal industrial decarbonization targets are accelerating procurement for process intensification catalysts.
- Biomedical:Academic research institutions and diagnostic companies purchase smaller volumes with higher customization requirements. REACH registration obligations in Europe constrain supplier flexibility for engineered nanomaterial orders.
Pharmaceuticals lock in the majority of specialized capacity; Energy is gaining share fastest.
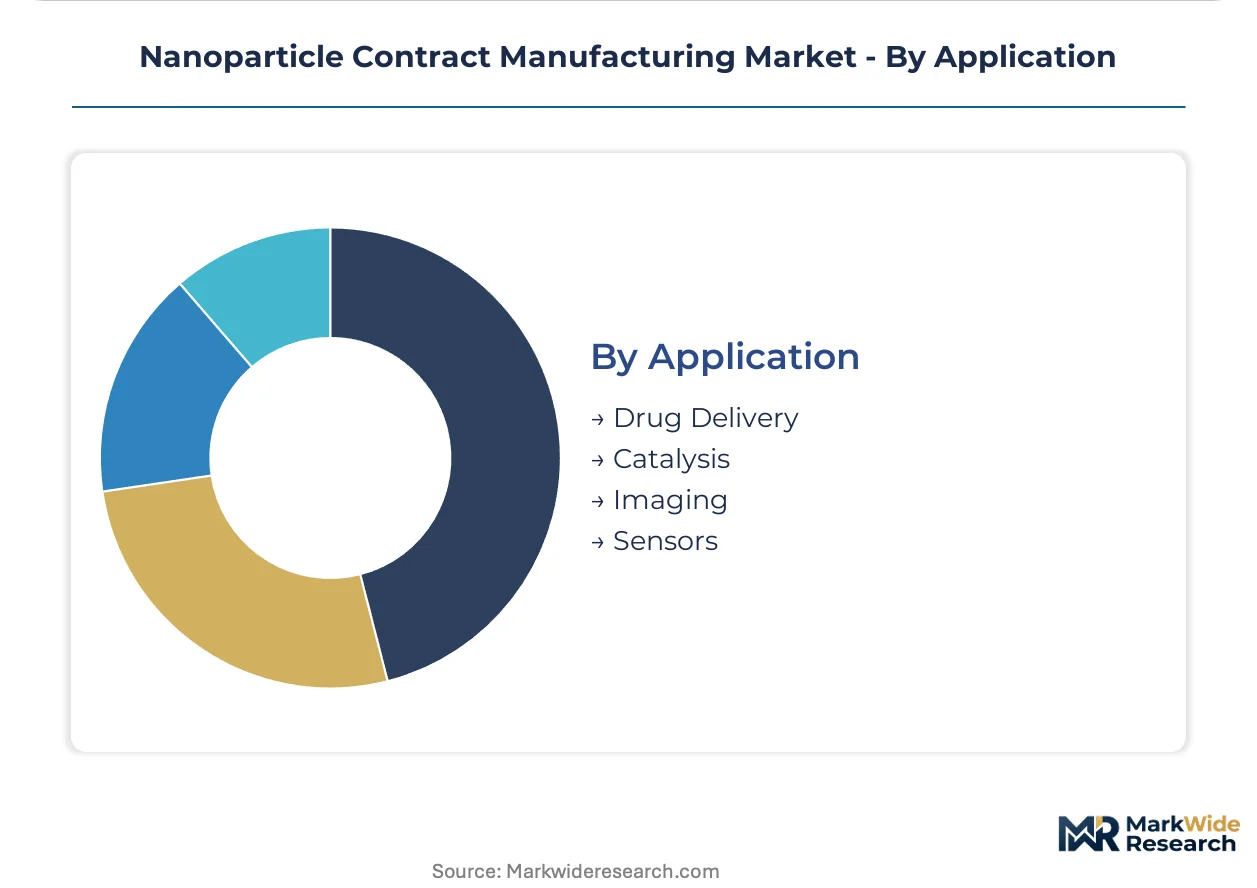
Application:
Functional performance requirements dictate manufacturing process selection and quality control intensity across application domains.
- Drug Delivery:Liposomal and polymeric nanoparticle formulations require sterile processing and endotoxin control for parenteral administration. FDA nanotechnology guidance harmonization is compressing technology transfer timelines between sponsors and contract manufacturers.
- Catalysis:Metal nanoparticle catalysts enable selective chemical transformations with reduced energy input and waste generation. German and Swiss fine chemical producers are expanding outsourced catalyst manufacturing to meet EU Green Deal emissions reduction mandates.
- Imaging:Contrast agents and fluorescent probes demand precise optical and magnetic property tuning. Diagnostic imaging centers in the United States and Japan specify iron oxide and quantum dot formulations.
- Sensors:Surface-functionalized nanoparticles provide signal amplification and selectivity in chemical and biological detection platforms. Environmental monitoring applications are emerging in European industrial compliance markets.
Drug Delivery captures the largest committed capacity footprint; Catalysis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's ionizable lipid production infrastructure anchors European pharmaceutical nanoparticle supply chains, while specialized manufacturing clusters in the United States and Asia-Pacific concentrate client-sponsor relationships for mRNA therapeutics.
United States
FDA nanotechnology guidance harmonization accelerates sponsor-CDMO technology transfer timelines for lipid nanoparticle formulations. The 21st Century Cures Act provisions streamline nanomedicine approval pathways for oncology applications. Boston-Cambridge and Research Triangle Park host the densest concentration of qualified GMP facilities serving mRNA vaccine developers.
Germany
REACH registration obligations for engineered nanomaterials enforce supply chain transparency across excipient sourcing networks. ECHA substance identification guidance for nanoforms compels raw material disclosure from proprietary production methods. Frankfurt-Rhine-Main and Munich clusters concentrate ionizable lipid manufacturing capacity serving European pharmaceutical sponsors.
Switzerland
Swissmedic quality guidelines for nanomedicines impose stringent batch characterization requirements that elevate compliance barriers for contract manufacturers. Federal Act on Research on Human Embryos and Stem Cells provisions shape gene therapy vector development timelines. Basel and Zurich host specialized formulation facilities serving global biopharma procurement teams.
India
CDSCO streamlined approval pathways for nanosimilar products attract manufacturing investment toward specialized formulation infrastructure. PLI scheme incentives for active pharmaceutical ingredients extend to nanomaterial excipient production. Hyderabad and Ahmedabad production zones build dedicated capacity for polymeric nanoparticle oncology formulations.
Japan
PMDA guidance on quality control of nanomedicines aligns characterization protocols with FDA and EMA frameworks for multinational sponsor submissions. METI industrial decarbonization targets pull demand for metal nanoparticle catalysts in pharmaceutical process intensification. Kanto and Kansai regions concentrate electronics-grade nanoparticle production for semiconductor applications.
Nanoparticle Contract Manufacturing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microfluidic platform specialization and continuous processing capabilities. The vendor base stratifies across integrated chemical conglomerates, pharmaceutical-anchored CDMOs, and materials-science specialists. Three archetypes dominate: diversified chemical producers with captive excipient supply, pharmaceutical service providers with integrated analytical-regulatory capabilities, and nanoparticle-focused technology licensors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with sponsors consolidating supplier relationships around full-service providers.
Among diversified chemical producers, Evonik Industries AG and Merck KGaA represent the integrated infrastructure archetype spanning excipient production through finished formulation. Ascendia Pharmaceuticals exemplifies the pharmaceutical-specialist tier competing on complex nanosuspension technologies. These three entities occupy positions reflecting distinct strategic postures: chemical conglomerates leverage backward integration into lipid supply, while specialized CDMOs compete on formulation complexity and client intimacy.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Merck KGaA |
| American Elements |
| AstraZeneca |
| Ardena Holding NV |
| Ascendia Pharmaceuticals |
| Nanocomposix |
| SkySpring Nanomaterials |
| MCH Nano Solutions |
| Others |
Supply & Pricing Matrix
Ionizable lipid excipient costs cascade through three distinct service tiers, with GMP-certified batch release testing and regulatory documentation bundled at the premium level while pilot-scale clients absorb unbundled analytical fees separately. CDMOs in Germany and Switzerland leverage captive lipid supply to command price premiums, whereas North American competitors compete on integrated formulation-to-filing service packages.
Pricing Analysis
Service bundling separates qualified GMP manufacturing with integrated FDA submission support from basic formulation-only contracts that exclude regulatory documentation and stability testing. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA-registered facilities commanding substantial premiums over pre-clinical pilot operators. Pricing pressure stems from sponsor consolidation around single-source partnerships that compress per-unit margins through volume commitments. Small-cap biotech developers exhibit acute price sensitivity, while multinational vaccine sponsors prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Direct-to-pharma channels handle sponsor-scale demand for lipid nanoparticle formulations, while distributor-mediated procurement serves academic and diagnostic research volumes. Ionizable lipid production concentrates in Germany and Switzerland, with secondary capacity emerging in India under PLI scheme incentives. Raw material dependencies include phospholipid excipients, PEGylation reagents, and high-purity organic solvents. Single-source vulnerability in ionizable lipid supply creates structural risk, particularly for mRNA therapeutic developers with accelerated approval timelines. Distribution runs through qualified GMP logistics networks with cold-chain integrity requirements for lipid formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous microfluidic manufacturing platforms are displacing legacy batch emulsification methods, compressing particle size variability and enabling real-time process control that incumbent infrastructure cannot replicate.
For Market Incumbents: Deploy backward integration into ionizable lipid production to neutralize supply concentration risk from German and Swiss suppliers. Incumbent CDMOs must add continuous processing capacity in Boston-Cambridge and Research Triangle Park clusters to defend against sponsors migrating to competitors with proven scale-up infrastructure. FDA nanotechnology guidance harmonization accelerates client qualification cycles, rewarding manufacturers with pre-validated analytical methods. For New Entrants and Emerging Players: Microfluidic platform specialization offers entry into sponsor relationships previously locked by multi-year incumbent contracts. New entrants should target India CDSCO nanosimilar approval pathways as the most penetrable regulatory entry point, building polymeric nanoparticle capacity in Hyderabad and Ahmedabad production zones. A technology-licensing go-to-market angle with embedded process analytical technology differentiates against equipment-only vendors. For Investors and Strategic Acquirers: Sponsor consolidation around single-source CDMO partnerships is the leading indicator that integrated analytical-regulatory capabilities will command acquisition premiums over pure-play manufacturing assets. Long-term viability favors full-service providers with captive excipient supply and continuous processing validation. Investors should monitor CDSCO approval volume trends as the inflection signal for India manufacturing investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Microfluidic platforms reduce particle size variability below batch method thresholds for mRNA applications. |
| Backward Integration into Lipid Supply | Captive ionizable lipid production neutralizes German-Swiss supplier concentration vulnerability. |
| Regulatory Documentation Bundling | Integrated FDA submission support differentiates premium-tier CDMOs from formulation-only competitors. |
| India Manufacturing Footprint Expansion | CDSCO streamlined nanosimilar pathways attract polymeric nanoparticle capacity to Hyderabad clusters. |
| Process Analytical Technology Integration | Real-time particle monitoring enables continuous release testing that compresses batch turnaround times. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this nanoparticle contract manufacturing analysis. Primary interviews with pharmaceutical development executives, CDMO regulatory affairs leads, biotech procurement managers, and ionizable lipid supply specialists combined with FDA nanotechnology guidance documents, EMA quality guideline submissions, CDSCO approval databases, and REACH registration records. Bottom-up facility capacity assessments and top-down sponsor spending estimates were triangulated to validate market sizing.
Segmentation granularity spanned production method, material type, end user, and application dimensions across the analysis window. Drug delivery, catalysis, imaging, and sensor applications were modeled separately with distinct regulatory compliance cost structures. CAGRs were derived from sponsor pipeline analysis and capacity expansion announcements. Forecast inputs included mRNA therapeutic clinical trial advancement rates, CDSCO nanosimilar approval velocity, and EU Green Deal catalysis procurement mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA nanotechnology guidance revision scenarios or ionizable lipid supply disruption events. Forecasts reflect assumptions regarding sponsor outsourcing penetration rates and continuous manufacturing adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanomaterial Supercapacitors Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Global Nano Calcium Carbonate Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Titanium Dioxide Nanomaterials Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Graphene Aerogel Market