
 Methyl P-Hydroxybenzoate Market | 2026-2036
Methyl P-Hydroxybenzoate Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl P-Hydroxybenzoate Market Foresight
Green chemistry process intensification is reshaping methyl p-hydroxybenzoate production economics, replacing solvent-heavy esterification with continuous-flow catalytic systems. BASF SE leverages its integrated specialty chemicals platform to sustain cost advantages in high-purity grades. Evonik Industries AG anchors its position through membrane-based purification technology that competes on yield against conventional crystallization. Shanghai Smart Chemicals Co. Ltd. dominates regional supply to Asian formulators with localized manufacturing scale.
Methyl p-hydroxybenzoate, the methyl ester of p-hydroxybenzoic acid (CAS 99-76-3), functions primarily as a broad-spectrum antimicrobial preservative effective against yeasts, molds, and gram-positive bacteria in acidic to neutral pH environments; industrial synthesis proceeds via acid-catalyzed esterification of p-hydroxybenzoic acid with methanol, yielding white crystalline powder at minimum purity. The preservative product type occupies the largest volume share given its irreplaceable role in extending shelf stability of water-based cosmetics and topical pharmaceuticals. Powder form leads pharmaceutical procurement due to handling precision and dosing reproducibility, while liquid emulsions gain traction in personal care manufacturing for direct incorporation into aqueous phases without dissolution steps.
EMA guidelines on paraben concentration limits in cosmetic products directly constrain formulation flexibility and drive demand toward compliant methyl ester variants with documented safety profiles. EPA oversight of chemical manufacturing emissions shapes plant location decisions and capital allocation for pollution control equipment. FDA food additive regulations and ECHA REACH substance evaluation collectively determine market access thresholds for new suppliers entering North American and European supply chains. Stakeholders must monitor evolving regulatory divergence between jurisdictions to anticipate reformulation mandates before they disrupt established supply relationships.
Market Dynamics
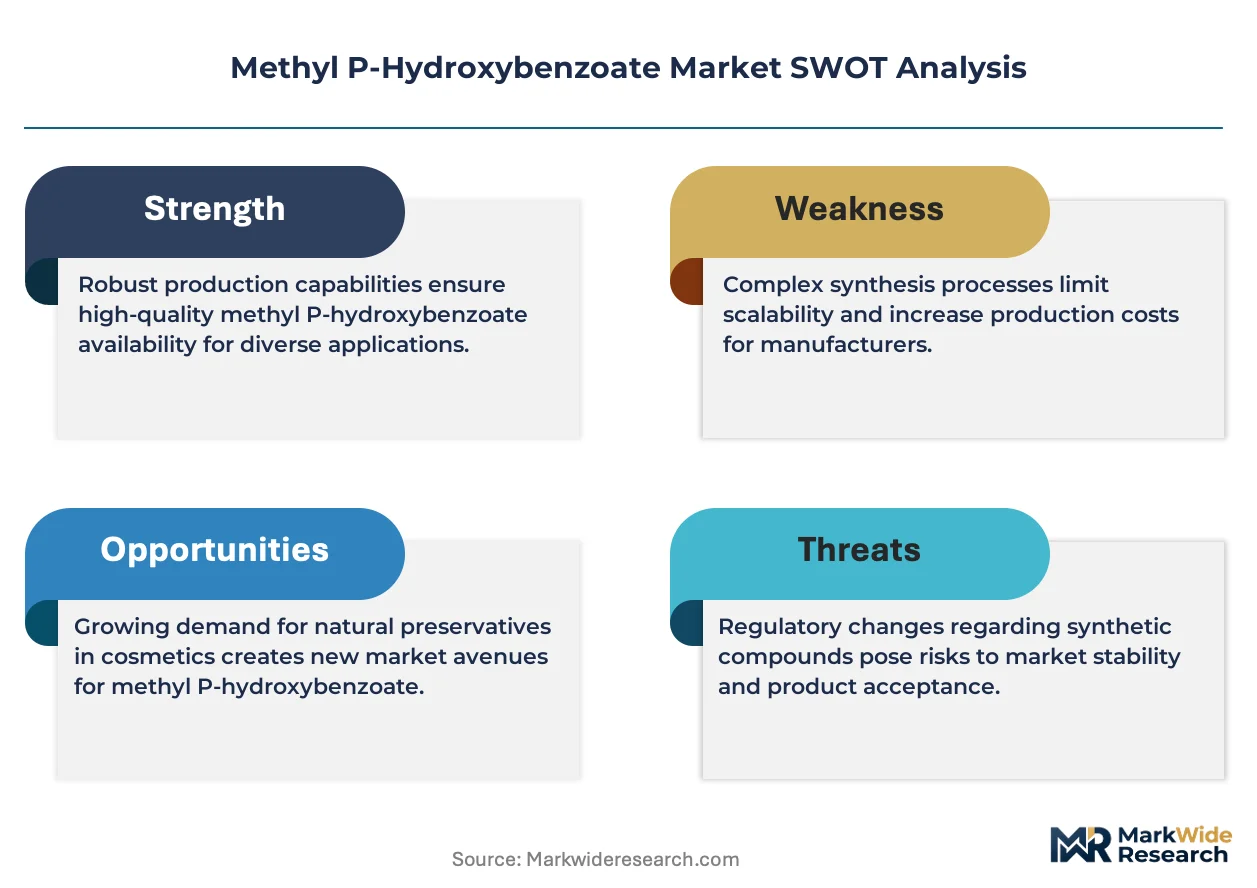
Continuous-flow catalytic esterification is compressing production costs for methyl p-hydroxybenzoate manufacturers, forcing legacy batch-reactor operators to accelerate capital deployment or exit high-purity segments. This process intensification wave is redistributing margin capture upstream toward integrated specialty chemical platforms.
Growth Catalysts
- ECHA REACH substance evaluation:Documented safety profiles for methyl ester variants unlock formulation flexibility in European personal care, accelerating compliant preservative procurement.
- Pharmaceutical manufacturing expansion:China and India concentrate new capacity for water-based topical drugs, driving antimicrobial preservative volume demand.
- Membrane-based purification:Yield advantages over crystallization methods improve unit economics for high-purity powder grades targeting injectable formulations.
Market Restraints
- Methanol feedstock volatility:Natural gas price swings transmit directly to esterification input costs, compressing margin predictability for non-integrated producers.
- Regional supply concentration:Asian manufacturing clusters dominate technical-grade output, creating geographic vulnerability for European and North American formulators.
- Paraben substitution pressure:Phenoxyethanol and organic acid blends capture share in clean-label cosmetic segments, constraining volume growth in prestige personal care.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-aligned manufacturing investments create captive demand for preservative suppliers establishing local technical service presence.
- Biocide Product Regulation compliance:EU BPR registration for methyl p-hydroxybenzoate opens professional hygiene applications beyond cosmetic preservation.
- Digital formulation platforms:AI-driven compatibility screening accelerates preservative selection for multinational brands, rewarding suppliers with structured efficacy datasets.
Industry Challenges
- Process analytical technology integration:PAT implementation for real-time quality assurance demands capital expenditure and specialized engineering talent scarce in mid-scale operations.
- Cross-jurisdictional dossier harmonization:Divergent data requirements between FDA food additive petitions and ECHA REACH updates extend regulatory approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl P-Hydroxybenzoate Market |
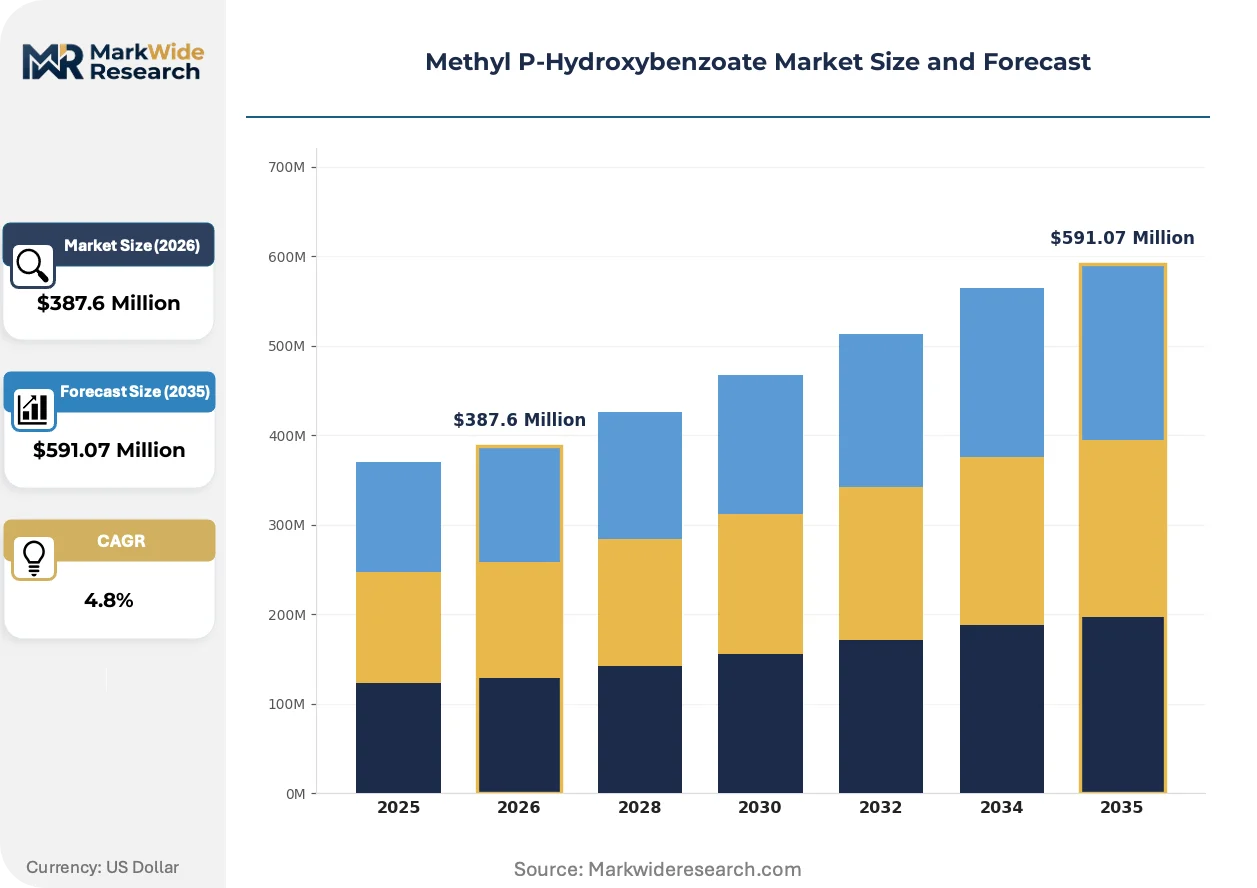
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservative, Fragrance Agent, Antimicrobial Agent, Cosmetic Additive Application: Personal Care, Pharmaceuticals, Food & Beverages, Household Products End User: Manufacturers, Retailers, Distributors, Healthcare Facilities Form: Liquid, Powder, Granule, Emulsion |
| Companies Covered | Merck KGaA, Sigma-Aldrich Co. LLC, Clariant, Ashland, Evonik Industries AG, BASF SE, Shanghai Smart Chemicals Co. Ltd., Acme-Hardesty, Ami Organics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl P-Hydroxybenzoate Market Shifts & Advancements
Green chemistry process redesign is collapsing the capital-intensity gap between commodity and specialty preservative production. Three converging developments are restructuring competitive advantage.
Continuous-flow microreactor technology is virtualizing traditional batch esterification economics. Pharmaceutical-grade manufacturers adopt these systems to compress residence times from hours to minutes. The technology is virtualizing scale-based barriers, enabling mid-cap producers to match historical cost positions of integrated majors.
EMA guidelines on paraben concentration limits are constraining formulation latitude for cosmetic compounders. Brands reformulate toward compliant methyl ester variants with complete toxicological dossiers. European personal care manufacturers accelerate supplier qualification timelines to preempt regulatory enforcement windows.
Direct liquid emulsion procurement is displacing powder dissolution steps in high-volume personal care manufacturing. Contract manufacturers in Germany and France consolidate preservative purchasing through distributor-managed inventory programs. This channel consolidation concentrates volume with suppliers offering technical application support and just-in-time logistics capabilities.
Methyl P-Hydroxybenzoate Market Segmentation
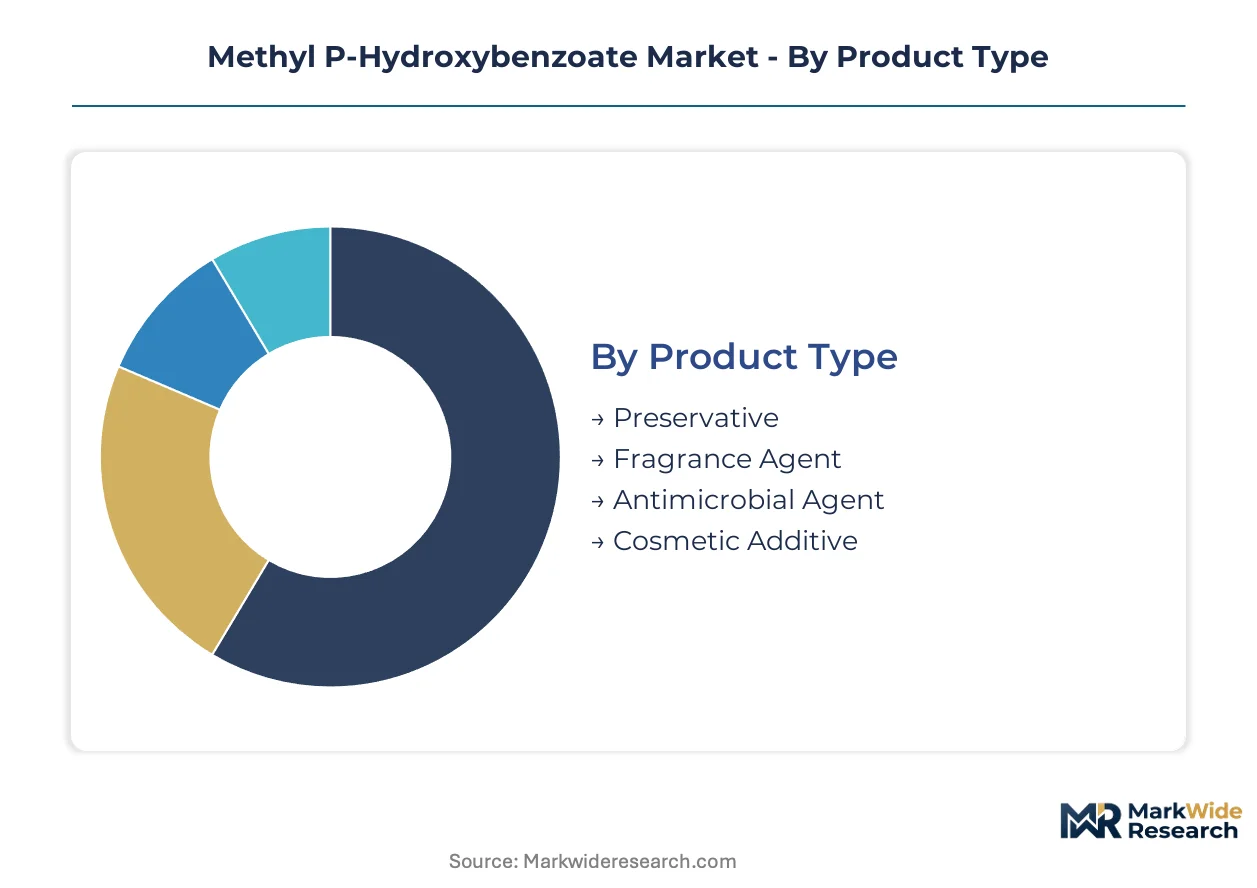
Preservative procurement patterns diverge sharply across end-use specifications, with pharmaceutical-grade purity requirements commanding fundamentally different supply relationships than technical grades for household formulations. Understanding these segment boundaries clarifies where margin capture concentrates and which technical capabilities determine supplier viability.
Product Type:
Mature applications anchor volume demand while emerging functional roles reshape procurement priorities for compounders seeking multi-benefit ingredients.
- Preservative:Broad-spectrum antimicrobial protection against yeasts, molds, and gram-positive bacteria in acidic to neutral pH matrices. Water-based cosmetics and topical pharmaceuticals in China and India drive procurement volume as manufacturing capacity expands. ECHA REACH compliance documentation determines supplier qualification for European personal care brands.
- Fragrance Agent:Low-odor methyl ester variants serve as fragrance stabilizers and fixatives in fine fragrance formulations. Niche demand concentrates with prestige cosmetic houses in France and Germany seeking paraben-compliant alternatives. Regulatory pressure on traditional fragrance allergens accelerates technical-grade interest.
- Antimicrobial Agent:Active ingredient in professional hygiene and surface disinfection applications. EU Biocide Product Regulation registration opens institutional procurement channels beyond cosmetic preservation.
- Cosmetic Additive:Secondary emollient and skin-conditioning functions in multifunctional formulations. Clean-label brands incorporate the ingredient for dual-benefit marketing claims.
Preservative retains volume leadership; antimicrobial agent holds the steepest expansion curve.
Application:
Cost-tier stratification separates premium pharmaceutical grades from commodity technical specifications, with certification requirements determining accessible market tiers.
- Personal Care:Shampoos, lotions, and creams requiring shelf-stable preservation against microbial contamination. EMA concentration limit guidelines constrain formulation latitude and drive compliant methyl ester procurement. German and French contract manufacturers consolidate purchasing through distributor-managed inventory programs.
- Pharmaceuticals:Injectable and ophthalmic formulations demanding USP-grade purity with documented stability profiles. Powder form dominates procurement for handling precision in sterile manufacturing environments. CDSCO-aligned manufacturing investments in India create captive demand for high-purity supply.
- Food & Beverages:Limited application scope constrained by FDA food additive regulations and regional preservative restrictions. Natural preservation trends compress addressable market.
- Household Products:Surface cleaners and laundry formulations utilizing technical-grade specifications. Price-sensitive procurement favors Asian supply clusters.
Personal care commands the broadest supplier base; pharmaceuticals extract the steepest purity premiums.
End User:
Customer-type differentiation separates specification-driven technical partnerships from transactional volume purchasing.
- Manufacturers:Integrated formulators requiring certificate-of-analysis documentation and batch-to-batch consistency. Direct technical service relationships determine supplier stickiness.
- Retailers:Private-label brands sourcing through consolidated distributor channels with standardized specifications.
- Distributors:Inventory-carrying intermediaries managing just-in-time logistics for mid-scale compounders. Channel consolidation favors suppliers with regional warehousing.
- Healthcare Facilities:Hospital pharmacies and compounding operations requiring small-batch flexibility and rapid regulatory documentation access.
Manufacturers retain procurement volume leadership; healthcare facilities demonstrate the steepest service-requirement escalation.
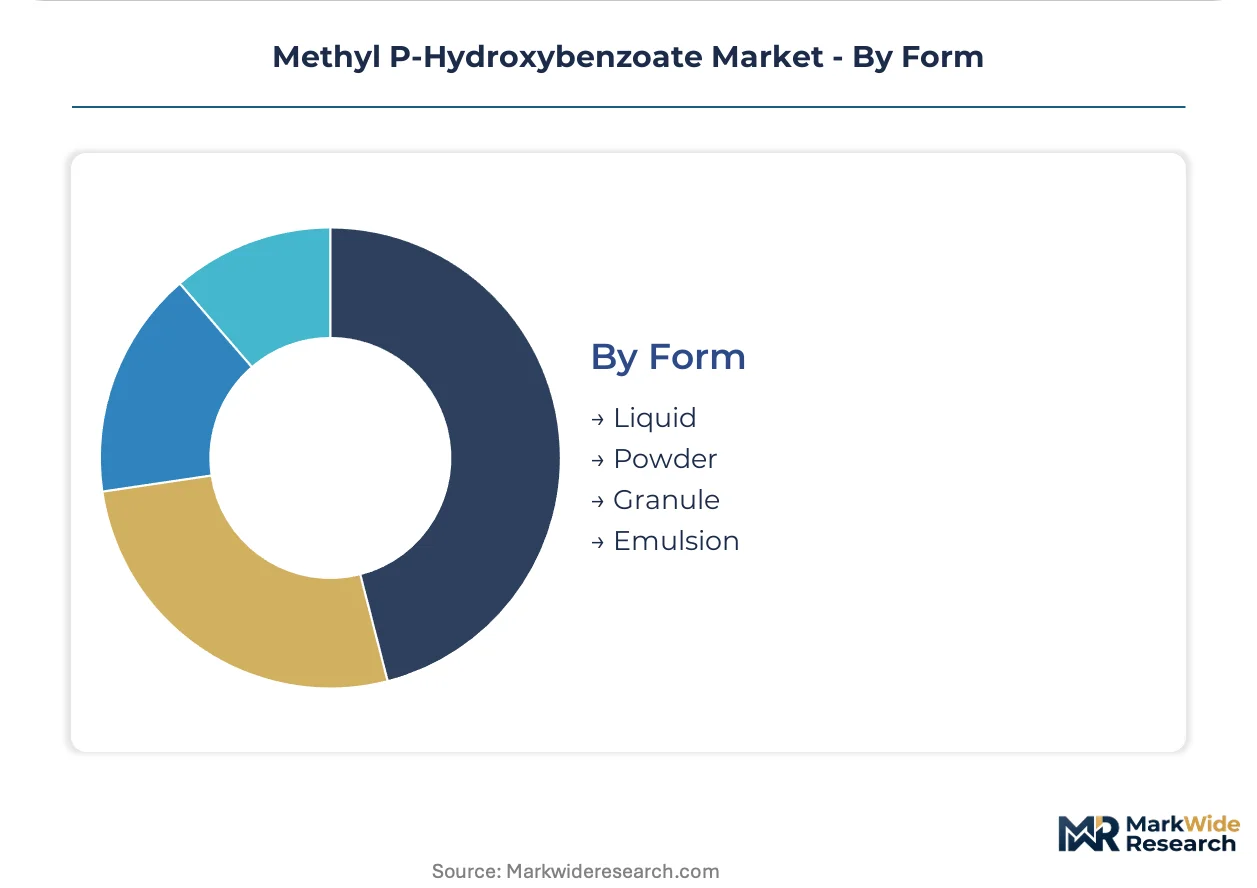
Form:
Supply concentration in powder production contrasts with emerging liquid emulsion capabilities reshaping manufacturing economics.
- Liquid:Pre-dissolved solutions eliminating dissolution steps in high-throughput personal care manufacturing. Direct incorporation into aqueous phases reduces batch cycle times.
- Powder:Crystalline white solid at minimum purity specifications, dominant in pharmaceutical procurement for dosing reproducibility. Membrane-based purification technology competes on yield against conventional crystallization.
- Granule:Intermediate particle size for specialized handling requirements in automated manufacturing systems.
- Emulsion:Stabilized liquid dispersions for direct addition to oil-in-water formulations. Traction gains in German and French contract manufacturing.
Powder retains volume leadership; emulsion holds the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese methyl p-hydroxybenzoate exports flow primarily to European personal care formulators and Indian pharmaceutical manufacturers, establishing a trade corridor that concentrates supply-side leverage in Asian production clusters while European and North American buyers absorb high-purity grades for regulated applications.
China
Pharmaceutical manufacturing expansion and personal care contract manufacturing drive preservative consumption in Jiangsu and Zhejiang provinces. NMPA registration requirements for excipient-grade materials shape supplier qualification protocols for domestic drug makers. The Yangtze River Delta chemical corridor hosts integrated esterification facilities serving both export markets and local formulators.
Germany
EMA concentration limit enforcement accelerates compliant methyl ester procurement from cosmetic compounders in North Rhine-Westphalia. REACH substance evaluation documentation determines supplier access for brands seeking European market continuity. The Cologne-Düsseldorf industrial zone concentrates distributor-managed inventory programs serving contract manufacturers.
India
CDSCO-aligned pharmaceutical investments in Maharashtra and Gujarat generate captive demand for USP-grade powder specifications. FSSAI preservative restrictions in food applications compress addressable market scope for technical grades. The Mumbai-Pune pharmaceutical cluster anchors procurement volume for injectable and ophthalmic formulations.
United States
FDA food additive regulations constrain methyl p-hydroxybenzoate penetration in beverage preservation while pharmaceutical applications sustain high-purity demand. EPA emissions oversight shapes domestic manufacturing location decisions for esterification capacity. New Jersey and Pennsylvania chemical corridors host specialty distributors serving compounding pharmacies and topical drug manufacturers.
Japan
METI chemical safety standards and PMDA pharmaceutical excipient requirements filter supplier entry for preservative procurement. Cosmetic manufacturers in Osaka and Tokyo metropolitan areas reformulate toward documented safety profiles under industry self-regulation. The Kansai industrial region maintains specialized handling capabilities for high-purity crystalline grades.
Methyl P-Hydroxybenzoate Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated specialty chemical platforms and regional purification specialists, with mid-scale producers occupying technical-grade segments through cost-optimized batch operations. German and Swiss majors anchor premium-tier positions through membrane-based yield advantages, while Chinese and Indian operators compete on localized manufacturing scale. Strategic moves center on backward integration into p-hydroxybenzoic acid supply and continuous-flow reactor licensing for process intensification.
Among German-based integrated platforms, BASF SE and Evonik Industries AG exemplify the specialty chemicals archetype combining captive feedstock access with high-purity purification capabilities. Shanghai Smart Chemicals Co. Ltd. occupies a position within the Asia-Pacific regional supply tier, serving formulators through localized manufacturing scale without multinational platform integration. These three anchors illustrate the geographic and capability segmentation that structures competitive positioning across regulated and technical-grade market tiers.
| Leading Market Players |
|---|
| Merck KGaA |
| Sigma-Aldrich Co. LLC |
| Clariant |
| Ashland |
| Evonik Industries AG |
| BASF SE |
| Shanghai Smart Chemicals Co. Ltd. |
| Acme-Hardesty |
| Ami Organics Ltd. |
| Others |
Supply & Pricing Matrix
Jiangsu and Zhejiang province chemical clusters concentrate p-hydroxybenzoic acid esterification capacity, anchoring margin capture at the upstream feedstock tier while European and North American formulators absorb purity premiums for pharmaceutical-grade specifications. This geographic asymmetry compresses pricing power for non-integrated distributors serving mid-scale personal care compounders.
Pricing Analysis
Batch-reactor legacy systems versus continuous-flow microreactor installations versus licensed catalytic technology create a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade powder commands certification premiums tied to USP documentation and EMA compliance dossiers, while technical-grade liquid emulsions compete on volume scale and just-in-time logistics bundling. Cost compression in standard grades is intensifying because Chinese operators deploy unlicensed continuous-flow equipment, eroding historical cost barriers. Contract manufacturers in Germany and France demonstrate the least price sensitivity given reformulation urgency under REACH substance evaluation windows.
Supply Chain Analysis
ECHA REACH substance evaluation and EU Biocide Product Regulation registration requirements constrain supplier qualification flows into European personal care and professional hygiene channels. Manufacturing concentrates in China, India, and Germany, with the Yangtze River Delta and Mumbai-Pune pharmaceutical clusters anchoring crystalline powder output. Methanol feedstock and p-hydroxybenzoic acid precursor supply rest on petrochemical value chains exposed to natural gas price volatility. Single-source vulnerability concentrates in membrane-based purification technology licensing held by German integrated majors. Distribution runs through inventory-carrying intermediaries managing just-in-time programs for North Rhine-Westphalia contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical manufacturing expansion in India and China represents an early-cycle adoption wave for USP-grade antimicrobial preservatives, with ECHA REACH compliance documentation creating qualification backlogs that extend supplier selection timelines.
For Market Incumbents: Entrench membrane-based purification yield advantages through exclusive licensing agreements with microreactor technology providers, blocking mid-scale rivals from matching pharmaceutical-grade cost positions. Accelerate backward integration into p-hydroxybenzoic acid supply to insulate margin structures from methanol feedstock volatility threatening non-integrated operators. For New Entrants and Emerging Players: CDSCO-aligned pharmaceutical manufacturing investments in Maharashtra and Gujarat represent the most penetrable entry point for USP-grade powder suppliers establishing local technical service presence. EU Biocide Product Regulation registration for professional hygiene applications offers a compliance-moat pathway distinct from saturated cosmetic preservation channels. Direct technical partnership with Indian generic drug exporters bypasses distributor consolidation in European personal care. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Chinese esterification operators lacking REACH dossier capabilities but holding Yangtze River Delta manufacturing scale. Five-to-ten year viability hinges on regulatory documentation translation rather than capacity expansion. The signal to watch is ECHA substance evaluation enforcement windows triggering supplier disqualification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into p-Hydroxybenzoic Acid | Captive feedstock supply insulates margin structures from petrochemical volatility affecting non-integrated rivals. |
| Continuous-Flow Microreactor Licensing | Yield advantages compress residence times from hours to minutes, virtualizing scale-based competitive barriers. |
| EU Biocide Product Regulation Registration | Professional hygiene channel access extends addressable market beyond cosmetic preservation saturation. |
| CDSCO-Aligned Technical Service Presence | Indian pharmaceutical export growth creates captive demand for suppliers with localized regulatory support. |
| Membrane-Based Purification Scale-Up | Yield competition against crystallization methods captures premium-tier pharmaceutical procurement volume. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at esterification facilities, procurement leads at downstream personal care OEMs, distribution channel partners managing inventory programs, and regulatory affairs directors navigating REACH compliance. Secondary validation drew from ECHA substance evaluation databases, CDSCO pharmaceutical manufacturing investment filings, customs trade data for methyl p-hydroxybenzoate flows, and SEC 10-K disclosures from integrated specialty chemical platforms. Bottom-up capacity modeling and top-down demand segmentation were cross-referenced to anchor volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeled across preservative grade tier, end-use industry application, powder versus liquid emulsion format, and regional regulatory cluster. CAGRs were derived from compound annual growth trajectory analysis incorporating pharmaceutical manufacturing capacity expansion rates, personal care reformulation timelines under EMA guidelines, and process intensification adoption curves for continuous-flow technology.
Stress conditions across methanol feedstock price bands, ECHA enforcement intensity, and paraben substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization timelines and technology licensing diffusion rates. Material shifts in REACH substance evaluation outcomes or continuous-flow reactor patent expirations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
RO Membrane Chemicals Market
Chemicals
United States Construction Chemicals Market
Chemicals
Iso Nonanol Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Inorganic Chemicals Market
Chemicals
Brazil Methanol Market
Chemicals
Quaternium-15 Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Nonanoic Acid Market
Chemicals
Methoprene Market
Chemicals
US Methanol Market
Chemicals
Lauryl Dimethyl Amine Oxide Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Phenothiazine Market
Chemicals
Wood Preservation Chemicals Market