
 Azodicarbonamide (ADC) Market | 2026-2036
Azodicarbonamide (ADC) Market Size, Share, and Industry Trends Forecast 2026-2036
Azodicarbonamide (ADC) Market Analysis
A shortage of chemical process engineers with azo-compound synthesis expertise is redrawing competitive boundaries among ADC suppliers. Kum Yang leverages its integrated manufacturing base in South Korea to control feedstock costs across polymer additive grades. Arkema sustains technology leadership in high-purity industrial formulations through continuous R&D investment at its European facilities.
Azodicarbonamide is an organic compound with the formula C₂H₄N₄O₂ that functions as a blowing agent, releasing nitrogen gas upon thermal decomposition to create cellular structures in polymers. The compound typically decomposes at temperatures between 195°C and 215°C, making it suitable for polyvinyl chloride and polyolefin processing. Polymer additives represent the dominant product category, anchored by decades of proven performance in insulation and footwear applications. Foamed products constitute the fastest-growing application segment, driven by thermal efficiency mandates in building codes across multiple jurisdictions.
REACH regulations in Europe and FDA standards in the United States impose strict purity thresholds and usage restrictions on azodicarbonamide, particularly in food-contact applications. China's GB standards and India's BIS certification requirements create additional compliance layers for market entry. Stakeholders must monitor evolving chemical safety assessments in major consuming regions to anticipate reformulation requirements and substitution risks.
Market Dynamics
REACH restrictions and FDA oversight are compressing food-grade ADC availability while redirecting investment toward industrial-grade formulations for polymer foaming applications.
Growth Catalysts
- Automotive lightweighting mandates:OEM specifications for fuel-efficiency improvements are accelerating polymer foam adoption in vehicle interiors across Germany, Japan, and the United States.
- REACH compliance deadlines:European chemical safety assessments are forcing reformulation investments that favor high-purity ADC grades with documented decomposition profiles.
- Building code thermal efficiency standards:China's GB standards and India's BIS certification requirements are mandating improved insulation performance in commercial construction.
Market Restraints
- Urea feedstock price volatility:Hydrazine and urea cost fluctuations directly compress margins for ADC manufacturers without captive synthesis capabilities.
- Substitution by physical blowing agents:Hydrocarbon and CO₂-based alternatives are gaining share in flexible foam applications where decomposition temperature flexibility matters less.
- Regulatory fragmentation:Divergent purity thresholds between ECHA, FDA, and China's SAMR create compliance overhead that disadvantages smaller compounders.
Strategic Opportunities
- India's construction chemicals sector:BIS certification expansion and infrastructure investment under the PLI scheme are opening distribution partnerships for technical-grade ADC.
- Electric vehicle battery encapsulation:Thermal runaway protection requirements are creating specifications for high-temperature-stable foamed polymers in pack housings.
- Recyclable polymer formulations:Compatibility with closed-loop PVC recycling streams is differentiating ADC grades in European window profile and flooring applications.
Industry Challenges
- Specialized chemical engineering talent:Azo-compound synthesis expertise scarcity is lengthening commissioning timelines for new production lines.
- Cross-border certification synchronization:Staggered ECHA, FDA, and NMPA review cycles delay product launches by 18-24 months for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azodicarbonamide (ADC) Market |
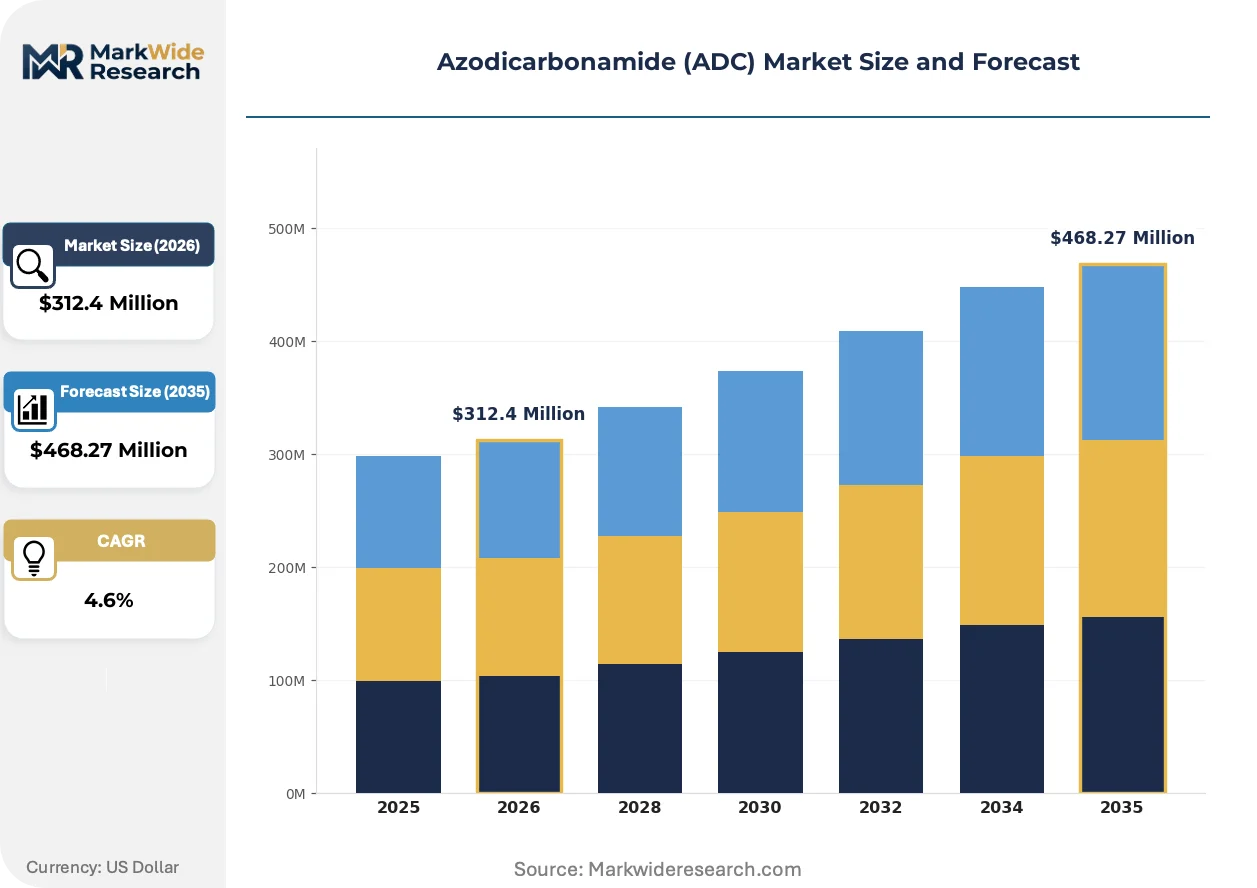
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $468.27 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Additives, Food Grade, Industrial Grade, Plasticizers Application: Plastics, Rubber, Food Packaging, Foamed Products End User: Manufacturers, Food Industry, Consumer Goods, Automotive Sector Form: Granule, Powder, Liquid, Tablet |
| Companies Covered | Kum Yang, Abtonsmart Chemicals, Arkema, Ajanta Chemical Industries, Honeywell International, Otsuka Chemical, Weifang Yaxing Chemical, Jiangxi Selon Industrial, Lanxess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azodicarbonamide (ADC) Market Emerging Trajectories
Formulation science and regulatory chemistry are converging to redefine competitive advantage in ADC supply, with purity documentation and decomposition control replacing commodity volume as the primary value lever.
Modified ADC grades with encapsulated activators are miniaturizing the effective processing window for polyolefin foaming. Automotive tier suppliers in Germany and the United States are specifying these grades for consistent cell structure in bumper cores and door panels. The technology is miniaturizing batch-to-batch variation tolerance, compressing quality control overhead for compounders serving just-in-time polymer processors.
REACH candidate list expansion is tightening residual hydrazine limits in industrial-grade ADC destined for European construction markets. ECHA's 2023-2024 substance evaluation wave has triggered reformulation investments among suppliers without integrated purification capabilities. Polymer additive distributors are consolidating their approved supplier lists to reduce documentation burden, concentrating procurement among three to four certified compounders.
Specification-driven procurement is replacing spot-market purchasing for volume polymer processors. Tier-one automotive suppliers and multinational insulation manufacturers are mandating lot-traceable ADC with certificates of analysis for every delivery. This pattern is most pronounced in Germany and South Korea, where OEM audit requirements have eliminated unqualified compounders from approved vendor lists.
Azodicarbonamide (ADC) Market Segmentation
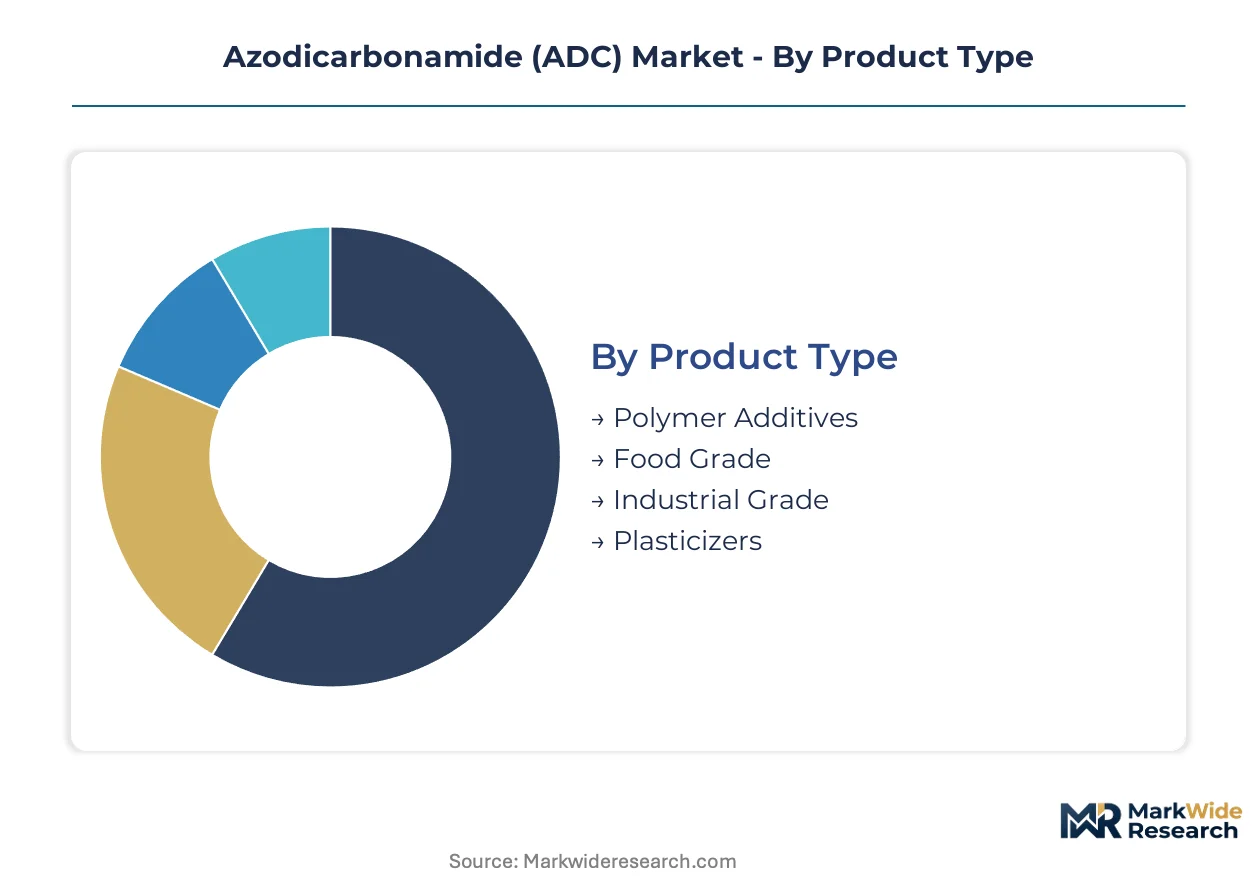
ADC market segmentation reveals divergent margin structures across purity grades and application requirements. Technical specifications in polymer foaming command premium positioning, while regulatory constraints fragment food-contact opportunities.
Product Type:
Margin pools concentrate in industrial formulations where decomposition control and residual hydrazine documentation justify price premiums over commodity grades.
- Polymer Additives:These formulations incorporate ADC as a nitrogen-releasing blowing agent for PVC and polyolefin processing. Automotive interior specifications in Germany and Japan concentrate demand for consistent cell structure in bumper cores and door panels. REACH documentation requirements favor suppliers with integrated purification capabilities.
- Industrial Grade:High-purity ADC with controlled decomposition profiles serves construction insulation and technical foaming applications. China's GB standards and India's BIS certification requirements are mandating improved thermal efficiency performance in commercial building envelopes. ECHA substance evaluations are tightening residual hydrazine thresholds for European market access.
- Food Grade:FDA purity thresholds and usage restrictions constrain availability for flour bleaching and dough conditioning.
- Plasticizers:Compatibility additives modify processing characteristics in flexible PVC compounds.
The dominant share belongs to Polymer Additives, while Industrial Grade is closing the gap fastest.
Application:
Application-based demand splits sharply between thermal efficiency mandates driving construction chemistry and lightweighting specifications reshaping automotive procurement.
- Foamed Products:Cellular polymer structures for thermal insulation dominate volume growth as building codes tighten across multiple jurisdictions. China's commercial construction sector and India's infrastructure investment under PLI scheme provisions are expanding specification-driven procurement for technical-grade ADC with lot-traceable documentation.
- Plastics:PVC and polyolefin processing for window profiles, flooring, and packaging applications anchors baseline demand. European recyclability requirements for closed-loop PVC streams are differentiating compatible ADC grades in specification-sensitive markets.
- Rubber:Cellular rubber compounds for footwear and industrial applications maintain steady offtake.
- Food Packaging:Regulatory constraints limit deployment to non-contact barrier layers with documented migration testing.
Foamed Products leads volume expansion, while Plastics retains the largest installed base.
End User:
Customer-type segmentation tracks procurement sophistication, with tier-one manufacturers mandating certificates of analysis and approved vendor list consolidation.
- Automotive Sector:OEM lightweighting mandates and fuel-efficiency specifications are accelerating polymer foam adoption in vehicle interiors. Just-in-time processors in Germany and South Korea require lot-traceable ADC with batch-specific decomposition data.
- Manufacturers:Compounders and polymer processors serving construction and consumer goods represent the broadest customer base. Specification-driven procurement is displacing spot-market purchasing among volume buyers.
- Consumer Goods:Footwear and appliance applications maintain consistent technical requirements.
- Food Industry:Regulatory fragmentation between FDA, EFSA, and national regulators compresses addressable market scope.
Manufacturers command the deepest penetration, though Automotive Sector is gaining share fastest.
Form:
Physical form selection reflects handling economics and processing integration requirements across continuous and batch operations.
- Powder:Standard free-flowing ADC dominates commodity polymer processing for cost-sensitive applications.
- Granule:Dust-reduced formulations improve workplace safety compliance and metering accuracy in automated compounding lines.
- Liquid:Dispersion concentrates enable precise dosing in specialized foam systems.
- Tablet:Pre-weighed units simplify batch processing for small-scale compounders.
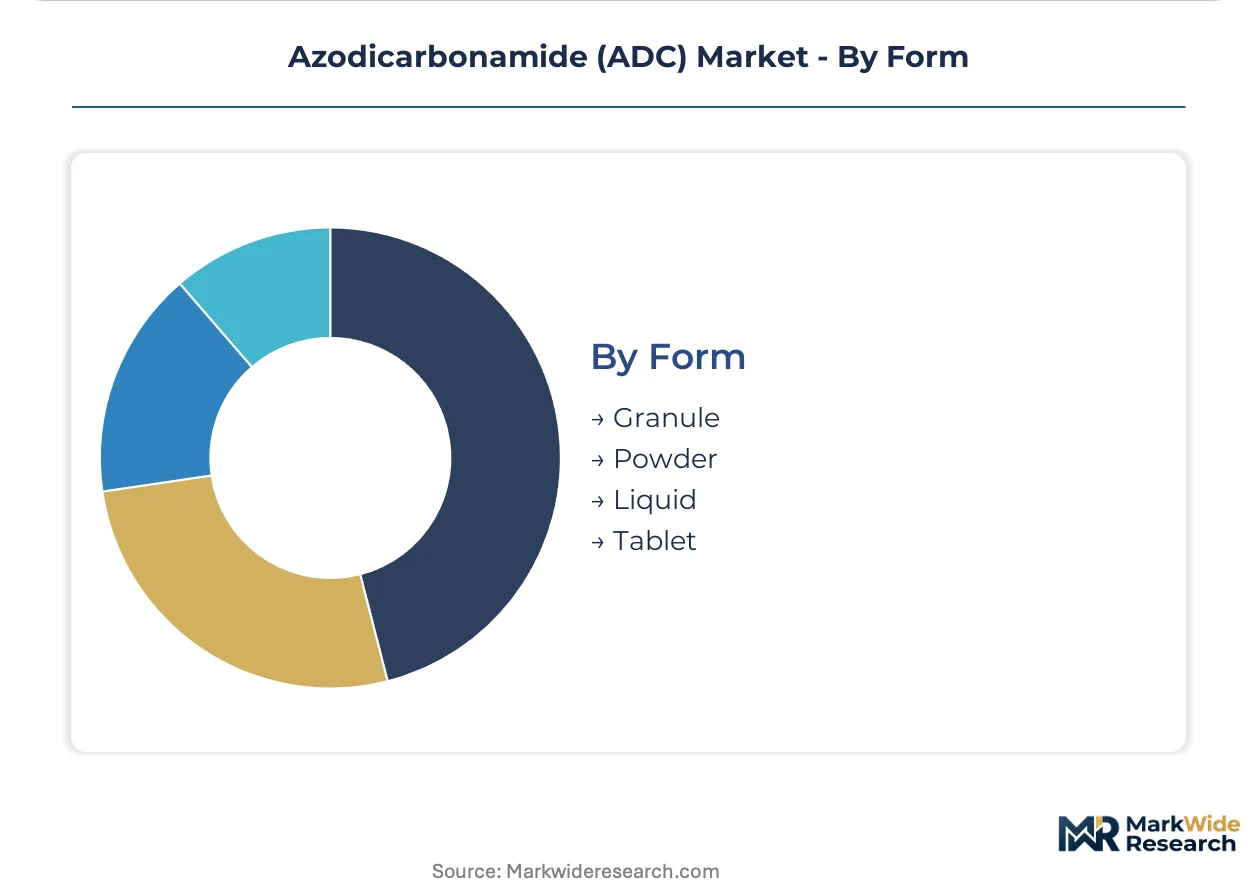
Powder maintains the dominant position, while Granule is expanding most quickly on safety compliance drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes ADC predominantly for construction insulation foams, while Germany and the United States prioritize automotive lightweighting applications. India bridges both use cases with infrastructure-driven thermal efficiency mandates gaining traction. This consumption-mix differential shapes regulatory investment and supplier qualification requirements across major markets.
China
Commercial building codes under GB standards are mandating higher thermal performance in envelope insulation across the Yangtze River Delta. SAMR enforcement of chemical safety documentation is compressing supplier lists to compounders with integrated purification. Shanghai and Jiangsu province host the densest concentration of ADC-consuming polymer processors serving domestic construction demand.
Germany
OEM fuel-efficiency specifications are accelerating polymer foam adoption in vehicle interiors for BMW, Mercedes-Benz, and Volkswagen supply chains. ECHA substance evaluations under REACH are tightening residual hydrazine thresholds for construction-grade ADC. The Rhine-Ruhr industrial corridor concentrates compounding capacity serving both automotive tier suppliers and cross-border insulation manufacturers.
United States
EPA energy efficiency standards and state-level building codes are expanding specification-driven procurement for technical-grade blowing agents. FDA oversight constrains food-contact applications while redirecting investment toward industrial formulations. The Gulf Coast petrochemical corridor and Midwest automotive belt represent distinct demand centers with divergent purity requirements.
India
Infrastructure investment under the PLI scheme and BIS certification expansion are opening distribution partnerships for construction-grade ADC. CDSCO chemical safety assessments are beginning to align with international purity documentation standards. Maharashtra and Gujarat host the primary polymer processing clusters serving domestic insulation and automotive component markets.
South Korea
Hyundai and Kia lightweighting mandates are driving specification-grade ADC demand for consistent cell structure in bumper cores. MFDS chemical safety protocols are harmonizing with REACH documentation requirements for export-oriented compounders. The Ulsan-Busan industrial corridor anchors polymer additive demand with integrated supply chains serving both domestic OEMs and regional export markets.
Azodicarbonamide (ADC) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in ADC supply. The upper tier controls captive feedstock synthesis and purification infrastructure. The specialist tier competes on formulation flexibility and regional certification speed. Three archetypes dominate: integrated chemical conglomerates with azo-compound heritage, regional compounders serving construction markets, and diversified polymer additive houses. Competitive moves concentrate on backward integration into hydrazine supply and portfolio diversification toward encapsulated activator grades.
Among Asian fabricators, Kum Yang and Weifang Yaxing Chemical occupy positions within the integrated tier, while Arkema represents the European specialty chemical archetype with documented decomposition profile capabilities. These three exemplify the geographic and structural segmentation of qualified supply: Korean and Chinese integrated producers anchor volume positions, while European specialists command premium positioning through regulatory documentation depth.
| Leading Market Players |
|---|
| Kum Yang |
| Abtonsmart Chemicals |
| Arkema |
| Ajanta Chemical Industries |
| Honeywell International |
| Otsuka Chemical |
| Weifang Yaxing Chemical |
| Jiangxi Selon Industrial |
| Lanxess |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Korean integrated producers and German automotive tier suppliers lock in both feedstock access and decomposition-profile documentation, insulating qualified compounders from spot hydrazine volatility while compressing margin flexibility for non-integrated competitors serving price-sensitive construction markets in India and China.
Pricing Analysis
Contract-based long-term offtake dominates procurement between integrated manufacturers and specification-driven buyers, while spot transactions persist for commodity-grade powder in cost-sensitive applications. Price differentiation rests on REACH documentation depth and residual hydrazine certification tiers. Cost compression in standard-grade powder is intensifying because urea feedstock volatility transfers directly to compounders without captive synthesis. Small-scale footwear compounders in India exhibit highest price sensitivity, whereas German automotive tier suppliers prioritize lot-traceable documentation over unit economics.
Supply Chain Analysis
Hydrazine monohydrate availability from Chinese and Korean petrochemical corridors anchors global ADC synthesis capacity, creating single-source vulnerability for European compounders lacking backward integration into feedstock production. Raw material dependencies span hydrazine hydrate, urea, and sodium hypochlorite, with logistics chokepoints concentrated at Shanghai and Busan port clusters. Distribution runs through approved vendor lists consolidated by multinational insulation manufacturers and automotive OEMs, compressing channel access for uncertified regional suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized azo-compound synthesis expertise scarcity is lengthening commissioning timelines and consolidating procurement power among integrated manufacturers with in-house technical capabilities, reshaping competitive boundaries across polymer additive supply.
For Market Incumbents: Shield margin position by deepening backward integration into hydrazine supply and accelerating encapsulated activator grade development before substitution by physical blowing agents accelerates in flexible foam segments. Prioritize REACH documentation investment to maintain approved vendor list status as ECHA substance evaluations tighten residual purity thresholds. For New Entrants and Emerging Players: Differentiate on BIS certification speed and technical service proximity to India's Maharashtra and Gujarat polymer processing clusters, where infrastructure investment under PLI scheme provisions outpaces qualified local supply. Target construction-grade granule formulations for dust-sensitive automated compounding lines as the most penetrable white space. For Investors and Strategic Acquirers: Regional compounders with integrated purification infrastructure and existing SAMR or MFDS registrations represent the most defensible acquisition profile for exposure to Asian construction and automotive demand. Monitor ECHA candidate list expansion pace as the critical inflection signal for reformulation-driven replacement cycles and consolidation pressure on non-integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrazine | Captive feedstock supply insulates Kum Yang and Weifang Yaxing from commodity volatility compressing non-integrated margins. |
| Encapsulated Activator Grade Development | Miniaturized processing windows specified by BMW and Volkswagen tier suppliers command premium positioning over commodity powder. |
| REACH Documentation Investment | ECHA substance evaluation compliance separates approved suppliers from distribution list consolidation eliminating uncertified compounders. |
| BIS Certification Expansion | PLI scheme infrastructure investment in Maharashtra and Gujarat opens partnership opportunities for technical-grade ADC with local documentation. |
| Recyclable Formulation Compatibility | Closed-loop PVC stream alignment differentiates supply for European window profile and flooring specifications tightening circularity requirements. |
Methodological Framework
A spread of perspectives from plant managers at integrated ADC manufacturers, procurement leads at German automotive tier suppliers, distribution channel partners serving Indian construction markets, and technical R&D directors at polymer additive houses converged on the working assumptions. These primary insights were cross-validated against customs and trade data, ACC and Cefic chemical industry reports, SEC filings from diversified materials conglomerates, and SAMR regulatory disclosure databases. Bottom-up volume builds from grade-specific consumption patterns were triangulated against top-down market sizing from production capacity analysis.
Segmentation dimensions modeled span purity grade tier, end-use industry vertical, physical form factor, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections incorporating automotive lightweighting mandates, building code thermal efficiency adoption curves, and substitution dynamics from physical blowing agent penetration. Industry-specific forecast inputs included OEM specification timelines for electric vehicle battery encapsulation foams and BIS certification rollout schedules for Indian construction chemicals.
Material uncertainties — hydrazine feedstock price spikes, staggered ECHA-FDA-NMPA review cycle delays, and accelerated substitution by hydrocarbon blowing agents — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as REACH candidate list expansion and SAMR enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Potassium Fluoride Market
Chemicals
Phenylethyl Market
Chemicals
Household Insecticides Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Fluorene Market
Chemicals
Chemical Distribution Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Acetic Ether Market
Chemicals
Sodium Ethyl P-Hydroxybenzoate Market
Chemicals
Elemental Fluorine Market
Chemicals
Global Glycine Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Pinoxaden Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Fungicide Active Ingredients Market
Chemicals
North America Tartaric Acid Market