
 Heptaldehyde Market | 2026-2036
Heptaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Heptaldehyde Market Analytics
Capital-intensity divergence between integrated petrochemical producers and specialty chemical specialists is bifurcating competitive dynamics in heptaldehyde supply. BASF SE leverages backward integration into C7 feedstock streams to control raw material costs across European production sites. Eastman Chemical Company sustains a differentiated position through dedicated reagent-grade purification capabilities serving pharmaceutical contract manufacturers. Jinan Haohua Industry anchors Asia-Pacific supply with focused manufacturing scale in Shandong Province.
Heptaldehyde, also known as heptanal, is a saturated seven-carbon aliphatic aldehyde with the molecular formula C7H14O, typically produced via oxo synthesis or castor oil pyrolysis, and functions primarily as a chemical intermediate and flavor precursor in industrial applications. Industrial grade heptaldehyde dominates volume flows into chemical intermediates for plasticizers and lubricant additives, while pharmaceutical grade commands premium pricing through stringent impurity controls demanded by FDA and EMA filing requirements. Flavors application segments are gaining structural momentum as synthetic aroma compound formulators substitute natural extracts with consistent-quality aldehyde derivatives.
EPA industrial chemical standards, REACH registration requirements, and FDA food-contact substance regulations collectively elevate compliance costs for non-integrated producers seeking multi-regional market access. BIS certification pressures in India and evolving GB standards in China add further layering to product specification complexity for exporters. Stakeholders must monitor feedstock volatility in palm kernel and castor oil markets while evaluating captive versus merchant supply strategies for C7 aldehyde derivatives.
Market Dynamics
Flavors and fragrances formulators are accelerating substitution of natural extracts with synthetic aroma compounds, compressing procurement cycles for food-grade heptaldehyde while tightening purity specifications across pharmaceutical and industrial grade segments.
Growth Catalysts
- REACH registration thresholds:European ECHA mandates for chemical intermediates are elevating compliance barriers that favor established producers with dedicated purification infrastructure, consolidating procurement toward certified suppliers.
- Castor oil pyrolysis advancement:Bio-based C7 feedstock processing is gaining traction among specialty chemical manufacturers seeking renewable attribution for flavor precursor applications.
- China flavor house expansion:Domestic synthetic aroma compound production in Shandong and Jiangsu provinces is anchoring regional heptaldehyde demand growth through captive intermediate consumption.
Market Restraints
- Palm kernel oil volatility:Feedstock price swings in Southeast Asian oleochemical markets transmit directly to oxo-synthesis production economics, compressing margin stability for non-integrated producers.
- Shandong supply concentration:Geographic clustering of Chinese manufacturing capacity creates single-point vulnerability for Asia-Pacific procurement chains dependent on Jinan-centered production nodes.
- Pharmaceutical impurity ceilings:FDA and EMA filing requirements for reagent-grade heptaldehyde impose technical barriers that exclude commodity-grade producers from premium pricing tiers.
Strategic Opportunities
- Indian BIS certification pathways:Emerging formaldehyde-free flavor precursor demand in domestic processed food manufacturing creates entry wedge for compliant importers.
- Lubricant additive reformulation:Synthetic base oil producers are evaluating C7 aldehyde derivatives as friction modifier components in high-performance engine formulations.
- EU Green Deal chemical transition:Renewable feedstock mandates for industrial intermediates are redirecting R&D investment toward castor oil-derived heptaldehyde process optimization.
Industry Challenges
- Analytical chemistry talent scarcity:Gas chromatography and mass spectrometry expertise for trace impurity quantification is concentrating at contract research organizations, limiting in-house quality control capabilities.
- Multi-regional certification timelines:Parallel FDA food-contact substance notifications and REACH dossier preparations extend product launch cycles by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heptaldehyde Market |
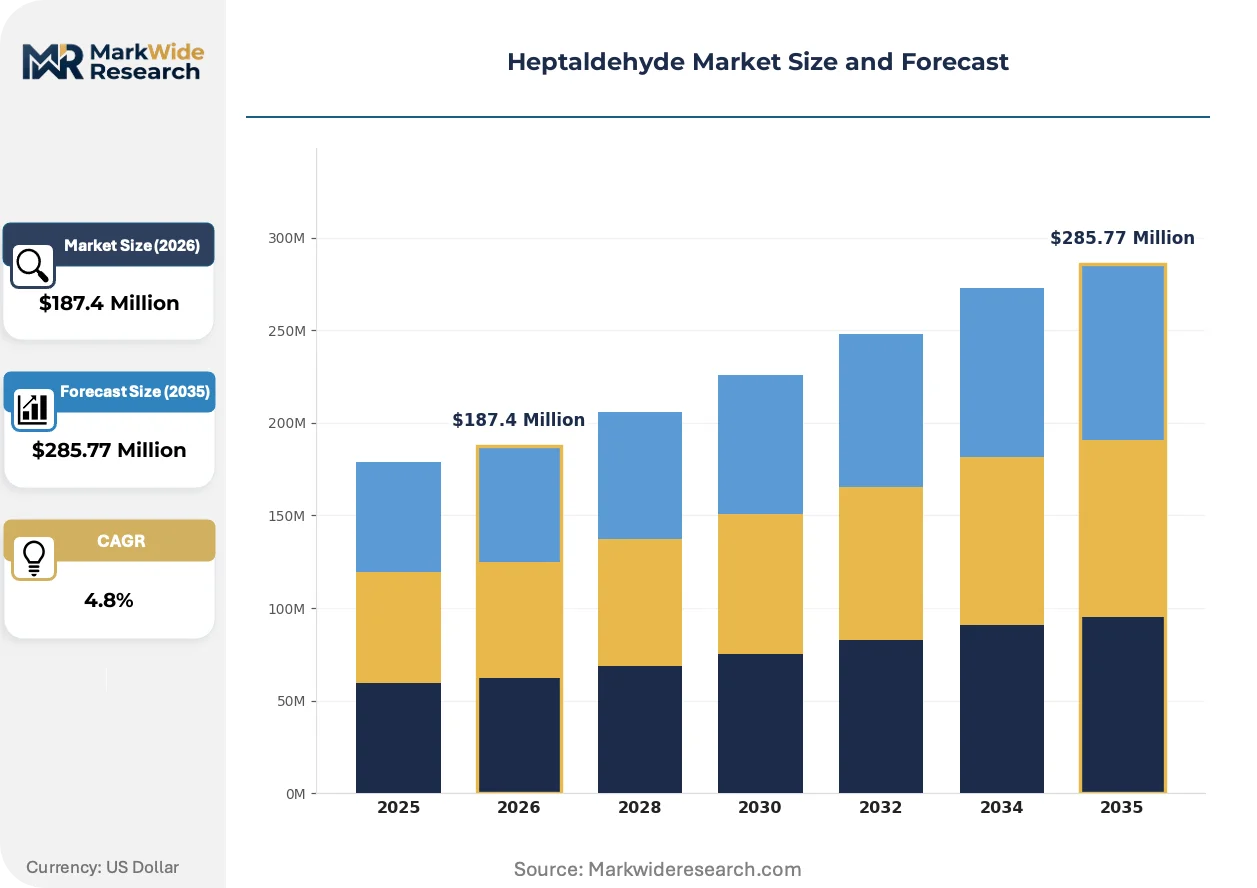
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Food Grade, Pharmaceutical Grade Application: Flavors, Fragrances, Chemical Intermediates, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers End User: Food Industry, Chemical Manufacturing, Personal Care, Pharmaceutical Industry |
| Companies Covered | Arkema Group, Solvay S.A., BASF SE, Kao Corporation, Evonik Industries AG, Merck KGaA, Eastman Chemical Company, Jinan Haohua Industry Co., Ltd., LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heptaldehyde Market Evolving Landscape
Continuous processing technology and bio-attribution certification are restructuring competitive advantage in heptaldehyde manufacturing, separating capital-intensive integrated producers from batch-oriented specialists.
Membrane separation technology for aldehyde purification is fragmenting the traditional distillation-dominated process landscape. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting nanofiltration modules for impurity reduction below 50 ppm thresholds. This diffusion is compressing the technology gap between dedicated reagent-grade facilities and upgraded industrial-grade plants.
REACH authorization requirements for Substances of Very High Concern are tightening documentation burdens across European chemical intermediate supply chains. Downstream formulators in France and Italy are demanding full mass-balance certification for synthetic aroma compound inputs. Flavors manufacturers with EU export exposure are consolidating procurement toward REACH-registered suppliers with complete SVHC disclosure.
Direct sourcing contracts between fragrance houses and C7 aldehyde producers are displacing traditional distributor intermediaries in North American supply chains. Givaudan and Firmenich procurement teams in New Jersey are negotiating multi-year offtake agreements with guaranteed purity bands. This channel compression is most advanced in the Northeast corridor, where logistics optimization favors rail-tanker delivery over packaged goods distribution.
Heptaldehyde Market Segmentation
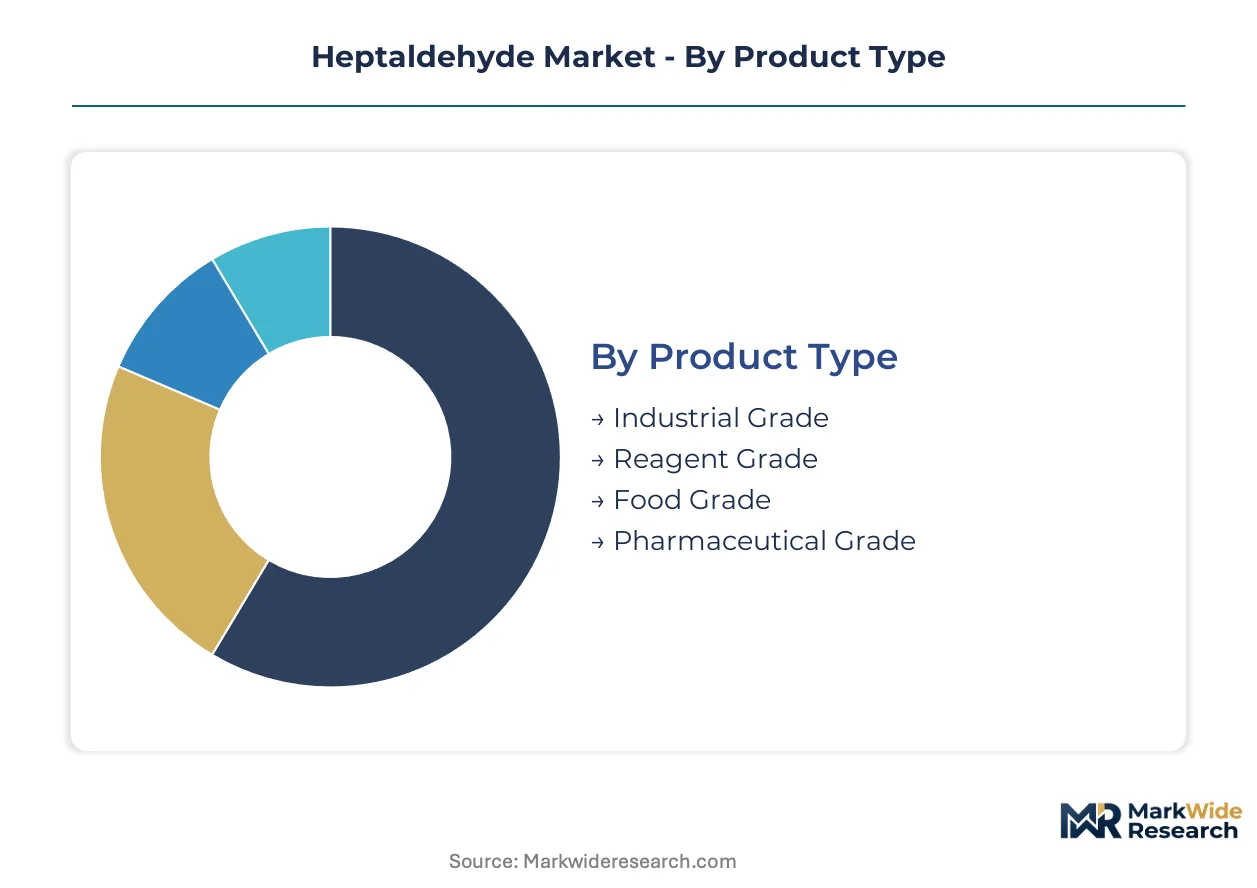
Heptaldehyde procurement patterns diverge sharply across purity grades and end-use specifications, with flavor houses and pharmaceutical formulators driving tiered demand structures. Substitution dynamics between natural extracts and synthetic aroma compounds reshape volume allocation across product categories.
Product Type:
Natural extract substitution pressures concentrate most intensely on food-grade specifications, where synthetic aroma compound formulators seek cost parity with botanical sources.
- Industrial Grade:Saturated seven-carbon aldehyde with standard oxo-synthesis purity levels serves plasticizer and lubricant additive manufacturers. Demand concentrates in Shandong Province chemical clusters where Jinan Haohua Industry anchors regional supply chains for C7 derivative production.
- Food Grade:Refined heptanal meeting FSSAI and FDA food-contact substance thresholds supplies synthetic aroma compound formulators replacing natural extracts. Stringent impurity controls under REACH SVHC disclosure requirements favor established producers with dedicated purification infrastructure.
- Reagent Grade:High-purity C7 aldehyde for analytical and research applications.
- Pharmaceutical Grade:Ultra-pure heptanal meeting EMA and FDA filing specifications for active pharmaceutical ingredient synthesis.
Industrial grade anchors the volume base while food grade gains share at the steepest rate.
Application:
Cost tier differentiation separates commodity chemical intermediate demand from premium flavor and pharmaceutical precursor segments.
- Chemical Intermediates:C7 aldehyde derivatives for plasticizer and lubricant additive production constitute the largest volume flow. Procurement concentrates among integrated petrochemical producers leveraging backward integration into C7 feedstock streams to control raw material costs.
- Flavors:Synthetic aroma compound precursors for processed food and beverage formulations. Formulators in France and Italy demand full mass-balance certification under REACH authorization requirements, consolidating procurement toward registered suppliers.
- Fragrances:Aldehyde components for perfume and personal care product formulations.
- Pharmaceuticals:Reagent-grade heptanal for drug synthesis and pharmaceutical manufacturing.
Chemical intermediates anchor the volume base while flavors climbs the fastest.
Distribution Channel:
Customer type segmentation separates bulk chemical procurement from specialized reagent purchasing patterns.
- Direct Sales:Long-term offtake agreements between C7 aldehyde producers and fragrance houses displace traditional intermediaries. Givaudan and Firmenich procurement teams negotiate multi-year contracts with guaranteed purity bands, compressing channel margins.
- Distributors:Packaged goods distribution for smaller-volume pharmaceutical and research customers. Logistics optimization in the Northeast corridor favors rail-tanker delivery for bulk direct sales over packaged distributor channels.
- Online Retail:E-commerce platforms for small-quantity reagent and research-grade procurement.
- Wholesalers:Regional bulk chemical intermediaries serving industrial-grade customers.
Direct sales anchors the volume base while online retail expands most quickly.
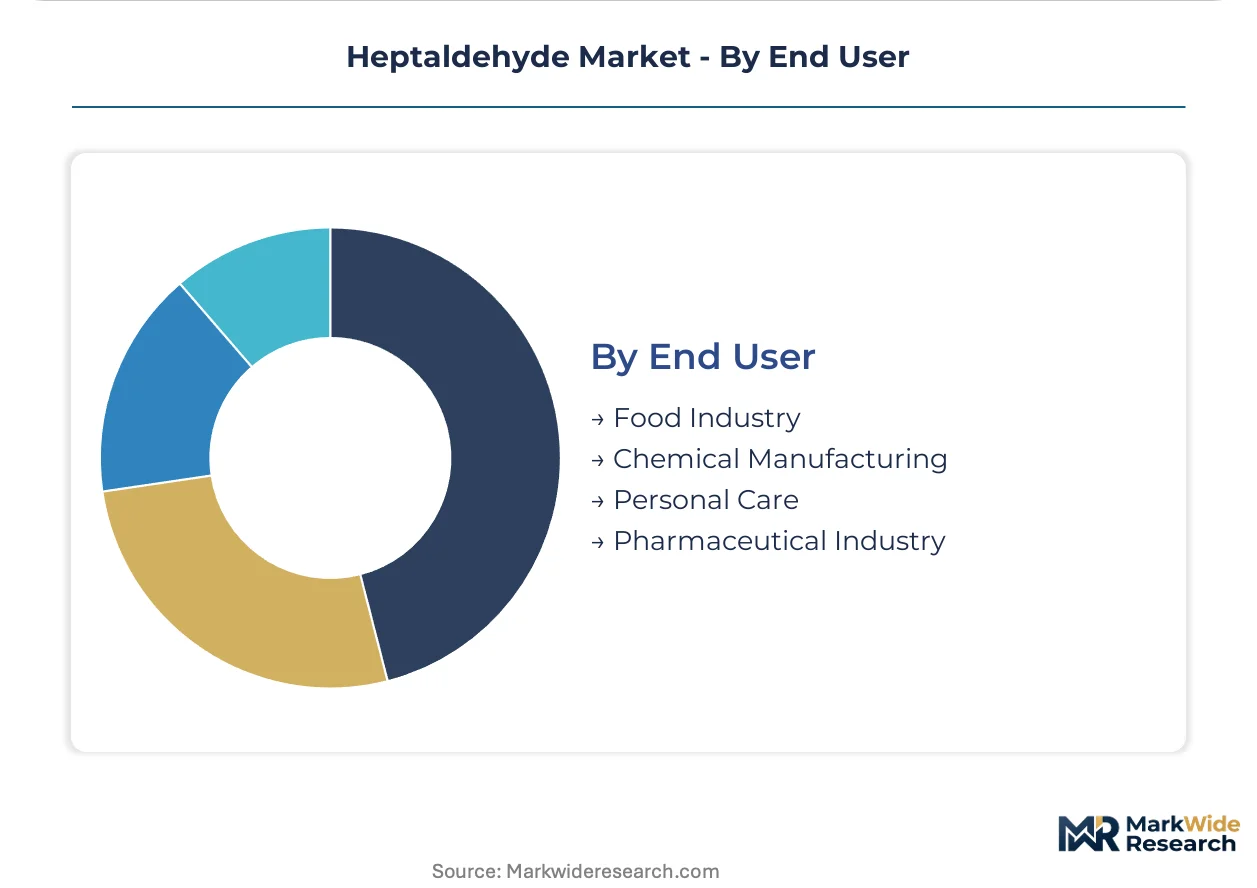
End User:
Supply concentration patterns align with geographic clustering of manufacturing capacity and regulatory jurisdiction.
- Chemical Manufacturing:Integrated petrochemical and specialty chemical producers consuming industrial-grade heptaldehyde for C7 derivative synthesis. Shandong supply concentration creates single-point vulnerability for Asia-Pacific procurement chains.
- Food Industry:Processed food manufacturers and flavor houses sourcing food-grade heptanal. Indian BIS certification pathways create entry wedges for compliant importers serving domestic synthetic aroma compound demand.
- Pharmaceutical Industry:Drug manufacturers requiring reagent-grade and pharmaceutical-grade specifications.
- Personal Care:Cosmetic and fragrance product formulators.
Chemical manufacturing anchors the volume base while food industry gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in heptaldehyde track the geographic dispersion of flavor house procurement and pharmaceutical contract manufacturing. Countries with concentrated synthetic aroma compound production dominate import demand, while integrated petrochemical bases anchor supply-side export capacity.
China
Domestic flavor houses in Shandong and Jiangsu provinces drive food-grade heptanal consumption for synthetic aroma compound manufacturing. GB standards under SAMR oversight mandate purity documentation for food-contact substance applications. Jinan-centered production clusters in Shandong Province supply regional chemical intermediate demand while serving export markets across Asia-Pacific.
United States
Fragrance houses in New Jersey negotiate direct offtake agreements with guaranteed purity specifications for perfume formulations. EPA industrial chemical standards and FDA food-contact substance regulations elevate compliance costs for imported material. Northeast corridor logistics favor rail-tanker delivery from domestic producers over packaged distributor channels.
Germany
Pharmaceutical contract manufacturers in Switzerland and Germany adopt membrane separation technology for impurity reduction below 50 ppm thresholds. REACH registration requirements through ECHA consolidate procurement toward certified suppliers with complete SVHC disclosure. BASF SE leverages backward integration into C7 feedstock streams across European production sites.
India
Processed food manufacturers generate emerging demand for formaldehyde-free flavor precursors in domestic synthetic aroma compound applications. BIS certification pressures create entry pathways for compliant importers serving flavor house procurement. Chemical manufacturing clusters in Maharashtra and Gujarat consume industrial-grade material for plasticizer derivative production.
France
Flavor formulators demand full mass-balance certification for synthetic aroma compound inputs under EU Green Deal chemical transition mandates. ECHA authorization requirements for Substances of Very High Concern tighten documentation burdens across supply chains. Givaudan procurement teams negotiate multi-year contracts with guaranteed purity bands for fragrance applications.
Heptaldehyde Market Competitive Landscape
Concentration sits with integrated petrochemical producers and specialty chemical specialists bifurcating supply-side structure. Three archetypes dominate: backward-integrated majors controlling C7 feedstock economics, dedicated purification specialists serving pharmaceutical grade requirements, and regional scale players anchoring Asia-Pacific supply chains. Competitive moves center on capacity expansion in Shandong Province and strategic partnerships between fragrance houses and aldehyde producers displacing traditional distributor intermediaries.
Among European-based chemical conglomerates, BASF SE, Solvay S.A., and Evonik Industries AG exemplify the integrated archetype with upstream control over feedstock streams. Eastman Chemical Company occupies a position within the purification-specialist tier, while Jinan Haohua Industry Co., Ltd. anchors regional manufacturing scale in Shandong Province. Arkema Group and LANXESS AG sit within diversified chemical portfolios with intermediate chemical exposure. Kao Corporation and Merck KGaA represent divergent end-market orientations spanning consumer products and life science reagents respectively.
| Leading Market Players |
|---|
| Arkema Group |
| Solvay S.A. |
| BASF SE |
| Kao Corporation |
| Evonik Industries AG |
| Merck KGaA |
| Eastman Chemical Company |
| Jinan Haohua Industry Co., Ltd. |
| LANXESS AG |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between fragrance houses and C7 aldehyde producers lock in multi-year supply access while anchoring price visibility through guaranteed purity bands, insulating buyers from castor oil feedstock volatility and Shandong supply concentration risks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across chemical intermediate tiers, while pharmaceutical formulators absorb premium-mid-economy pricing differentiation driven by FDA and EMA certification levels and volume scale. Pricing pressure stems from palm kernel oil volatility transmitting directly to oxo-synthesis production economics, squeezing margin stability for non-integrated producers. Flavor houses exhibit highest price sensitivity due to substitution pressures from natural extracts, whereas pharmaceutical contract manufacturers demonstrate lowest sensitivity given reagent-grade impurity ceiling requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European flavor houses dependent on Shandong-sourced material, compressing working capital cycles. Supply concentrates in China, Germany, and the United States, with raw material dependencies spanning castor oil from India, palm kernel oil from Southeast Asia, and C7 olefin feedstocks from integrated petrochemical complexes. Single-source vulnerability around Jinan-centered production clusters creates structural risk for Asia-Pacific procurement chains. Distribution runs through direct rail-tanker delivery for bulk fragrance house contracts, displacing traditional packaged goods intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as synthetic aroma compound formulators accelerate natural extract substitution, creating tiered entry points across food-grade, pharmaceutical-grade, and industrial-grade specification bands.
For Market Incumbents: Shield market position by deepening backward integration into C7 feedstock streams to control raw material cost volatility, while accelerating REACH-registered capacity expansion in Shandong Province to consolidate procurement share from emerging Indian flavor houses. Invest in membrane separation technology to compress the purity gap between industrial-grade and reagent-grade production, defending against specialty chemical specialists.
For New Entrants and Emerging Players: Contract research organization partnerships for analytical chemistry talent represent a service-layer gap where incumbents under-serve pharmaceutical-grade demand, enabling rapid quality control capability acquisition without in-house gas chromatography infrastructure. Target Indian BIS certification pathways for formaldehyde-free flavor precursors, leveraging domestic processed food manufacturing growth. Pursue castor oil pyrolysis bio-attribution as a differentiated go-to-market angle for EU Green Deal compliance.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors purification-specialist archetypes with dedicated pharmaceutical-grade infrastructure and established FDA filing relationships. Long-term viability over a multi-year horizon rests on captive feedstock economics and multi-regional certification coverage. Watch for REACH authorization timeline compression as an inflection indicator signaling regulatory barrier elevation that favors scaled registrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C7 Feedstock Streams | BASF SE leverages upstream control to insulate margin stability from palm kernel oil volatility. |
| Membrane Separation Technology Adoption | Pharmaceutical contract manufacturers in Switzerland deploy nanofiltration to achieve sub-50 ppm impurity thresholds. |
| REACH-Registered Capacity Expansion | Shandong Province production clusters consolidate procurement share through ECHA compliance infrastructure. |
| Direct Offtake Agreement Negotiation | Givaudan procurement teams in New Jersey displace distributor intermediaries through guaranteed purity band contracts. |
| Castor Oil Pyrolysis Process Optimization | Specialty chemical manufacturers secure renewable attribution for EU Green Deal chemical transition mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with flavor house procurement directors, pharmaceutical contract manufacturing executives, chemical plant managers in Shandong Province, and distribution channel partners across the Northeast corridor. Secondary validation drew from customs and trade flow databases, SEC 10-K filings of listed chemical conglomerates, ECHA REACH registration dossiers, and FDA food-contact substance notifications. Bottom-up volume modeling triangulated against top-down value estimates derived from petrochemical feedstock cost structures.
Across the analysis window, the quantitative framework modeled segmentation dimensions spanning grade tier, end-use industry, and regional production hub, with CAGRs derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporated castor oil and palm kernel oil price trajectory assumptions, REACH authorization timeline evolution, and synthetic aroma compound substitution rate parameters.
Forecasts assume regulatory continuity in REACH, FDA food-contact substance, and BIS certification regimes; material policy shifts would require re-modeling. Specific risk factors include feedstock price volatility in Southeast Asian oleochemical markets, Shandong supply concentration disruptions, and pharmaceutical impurity ceiling revisions by EMA or FDA. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Brazil Methanol Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
Global Chiral Chemicals Market
Chemicals
Carcinogenic Chemical Alternatives Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Anhydrides Market
Chemicals
Potassium Zirconium Fluoride Market
Chemicals
Formalin Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Acid Anhydrides Market
Chemicals
Tanning Agents Market