
 Diethyl Sulfate Market | 2026-2036
Diethyl Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Diethyl Sulfate Market Analysis
Project finance for dedicated alkylation units is narrowing the field of viable producers. BASF leverages integrated ethylene oxide streams to sustain captive diethyl sulfate output. Aarti Industries anchors South Asian supply through backward integration into sulfonation chemistry. WeylChem International differentiates via pharmaceutical-grade certification and European regulatory alignment.
Diethyl sulfate is a colorless, oily liquid with the formula (C₂H₅)₂SO₄, synthesized through ethylene oxide absorption in sulfuric acid or ethanol reaction with sulfur trioxide; it functions primarily as a potent ethylating agent in organic synthesis and pharmaceutical intermediate production. Industrial grade dominates volume throughput for agrochemical and bulk chemical manufacturing, while pharmaceutical grade commands premium positioning due to stringent impurity thresholds and validated batch documentation. Reagent grade occupies a mature niche in analytical laboratories, with margin pools shifting toward application-specific formulations in herbicide additive segments.
EPA oversight under the Toxic Substances Control Act and OSHA permissible exposure limits constrain domestic production economics and worker safety protocols. EMA pharmaceutical impurity guidelines and REACH authorization requirements govern European import eligibility and end-use registration. China's MEE environmental compliance audits and NMPA pharmaceutical raw material standards shape East Asian supply qualification timelines. Stakeholders must monitor evolving carcinogenicity classifications across jurisdictions to anticipate reformulation mandates and substitution pressures.
Market Dynamics
Contract pharmaceutical manufacturers in India and China are consolidating ethylating agent procurement around fewer qualified suppliers as REACH authorization timelines and EPA toxicity reviews simultaneously tighten. This dual regulatory pressure is compressing the viable producer base while elevating pharmaceutical-grade certification as the primary competitive differentiator.
Growth Catalysts
- Pharmaceutical outsourcing clusters:East Asian contract manufacturing organizations are expanding dedicated alkylation capacity for active pharmaceutical ingredient synthesis. CDSCO and NMPA inspections are accelerating qualification of diethyl sulfate feedstock suppliers.
- Agrochemical formulation demand:Herbicide additive segments are absorbing industrial-grade volumes as sulfonylurea chemistry expands. Brazil's ANVISA and India's Central Insecticides Board are registering new ethylated intermediates for crop protection.
- REACH authorization compliance:European ethylating agent users are securing authorized supplier relationships ahead of sunset date deadlines. ECHA's candidate list updates are redirecting procurement toward pre-registered tonnage holders.
Market Restraints
- Ethylene oxide feedstock volatility:Captive ethylene oxide supply determines cost competitiveness for integrated producers. Spot market exposure squeezes margin structures for non-integrated manufacturers.
- Carcinogenicity classification friction:IARC evaluations and EPA IRIS assessments are elevating hazard communication requirements. Worker exposure protocols are extending batch documentation burdens.
- Dimethyl sulfate substitution pressure:Methylating alternatives are capturing select pharmaceutical applications where ethylation specificity is non-critical. Process chemists are evaluating methyl-to-ethyl switching economics.
Strategic Opportunities
- Indian pharmaceutical corridors:Hyderabad and Ahmedabad manufacturing zones lack sufficient domestic ethylating capacity. Backward integration into sulfonation chemistry offers supply security advantages.
- Continuous flow alkylation:Microreactor technology is enabling smaller-batch pharmaceutical-grade production with enhanced thermal control. Process intensification reduces hold-up volumes and safety inventory requirements.
- Green chemistry procurement mandates:Large pharma sustainability scorecards are prioritizing suppliers with verified bio-based feedstock pathways. Mass balance certification is opening premium pricing tiers.
Industry Challenges
- Process safety engineering scarcity:Qualified professionals for highly energetic chemistry risk assessment are concentrated at established producers. Training pipelines have not matched capacity expansion timelines.
- Multi-jurisdiction dossier synchronization:REACH, TSCA, and NMPA filing requirements diverge on impurity threshold specifications. Harmonized analytical methods remain undeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethyl Sulfate Market |
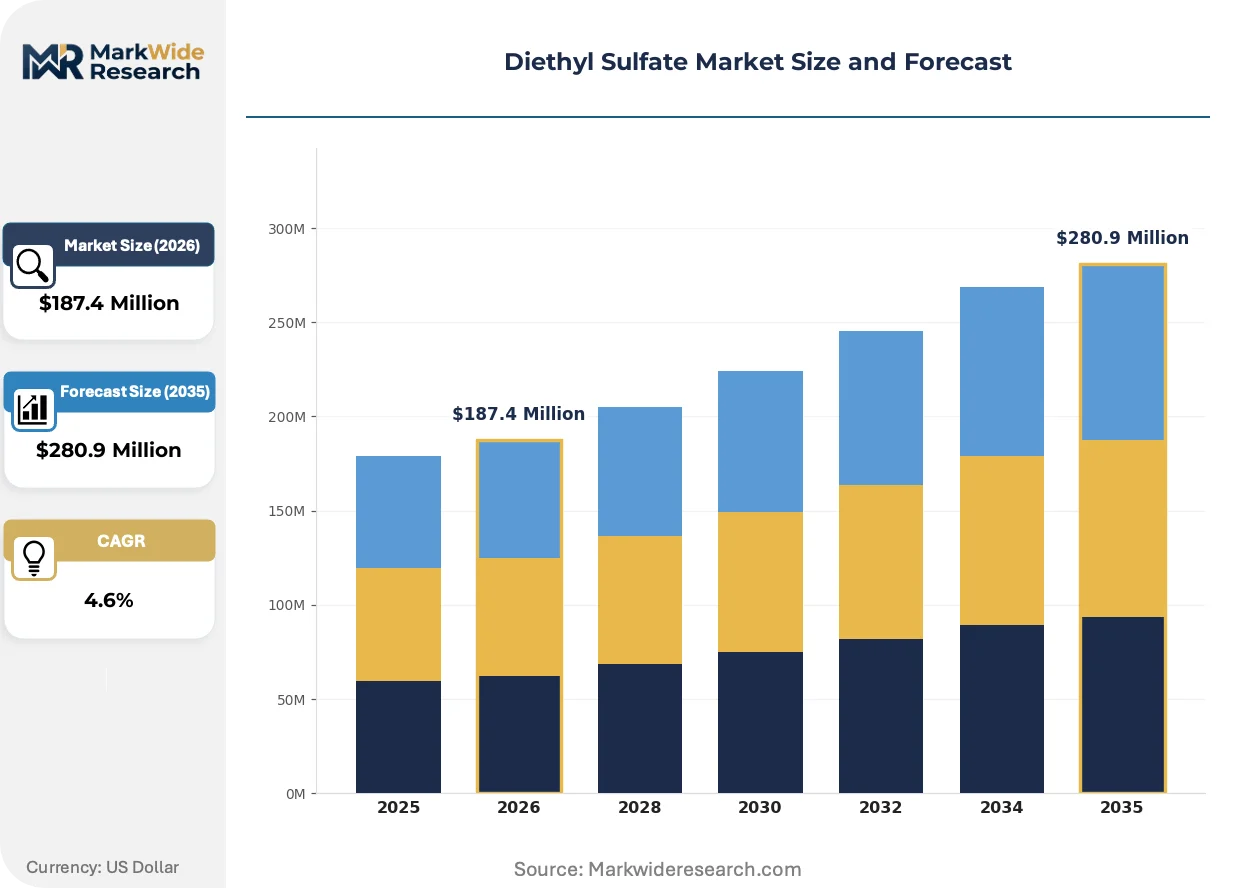
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Pharmaceutical Grade, Laboratory Grade Application: Intermediate for Synthesis, Solvent, Additive in Herbicides, Chemical Reagent End User: Chemical Manufacturing, Pharmaceutical Industry, Agrochemicals, Research Laboratories Packaging Type: Drum, Bottle, Canister, Bulk Container |
| Companies Covered | Aarti Industries, Taian Havay Group, Sinochem International Advanced Materials (Hebei), BASF, Merck KGaA, Alfa Aesar, Honeywell International, Chevron Phillips Chemical Company, WeylChem International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethyl Sulfate Market Emerging Trajectories
Alkylation technology is fragmenting into divergent process architectures as batch pharmaceutical manufacturers confront continuous-flow agrochemical producers. The competitive boundary between these modalities is shifting faster than equipment depreciation cycles.
Membrane-based ethylene oxide absorption is collapsing the traditional sulfuric acid dilution step in diethyl sulfate synthesis. Pharmaceutical-grade producers in Switzerland and Germany are piloting ceramic membrane modules that eliminate neutralization waste streams. This technology is collapsing capital intensity for mid-scale pharmaceutical-grade units while compressing regulatory approval timelines for greenfield installations.
REACH authorization requirements for carcinogenic substances are forcing end-use registration granularity that previous framework iterations avoided. ECHA's 2024 updates to Annex XIV entry conditions now mandate substance-specific downstream user notifications. Pharmaceutical formulators in the Netherlands and Belgium are restructuring supply agreements to transfer registration obligations upstream to diethyl sulfate manufacturers.
Consolidated procurement desks at top-20 pharmaceutical companies are unbundling ethylating agent supply from full-service intermediate packages. Merck KGaA and Lonza are establishing direct supplier relationships with sulfonation specialists, bypassing traditional distributor markups. This pattern is most visible in German and Swiss manufacturing networks where qualified supplier lists have narrowed to three certified sources.
Diethyl Sulfate Market Segmentation
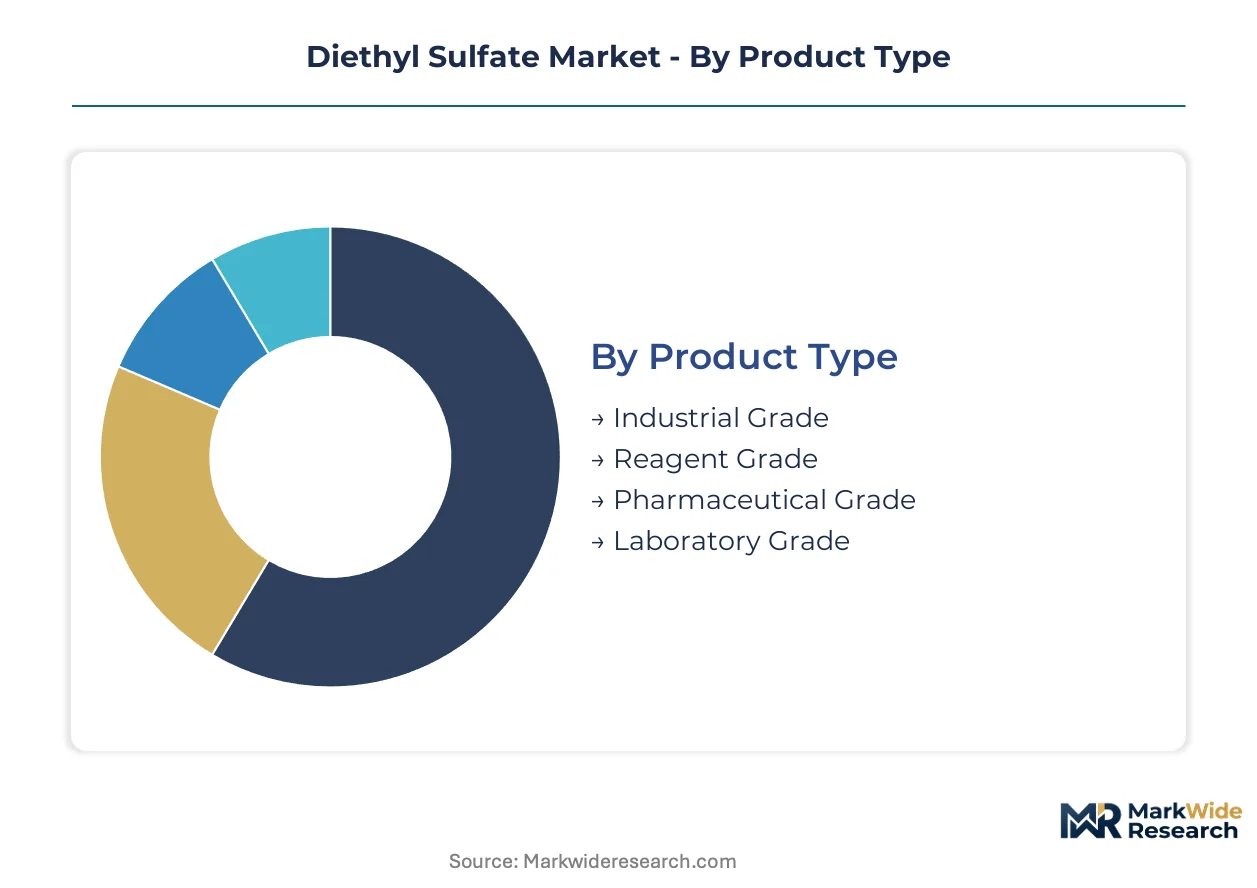
Segmentation in the diethyl sulfate market exposes divergent margin structures across purity tiers and packaging formats. Pharmaceutical-grade specifications command validation-intensive procurement cycles, while industrial-grade volumes turn on feedstock economics and agrochemical seasonality.
Product Type:
Cycle times compress from years for pharmaceutical-grade qualification to weeks for industrial-grade spot orders, creating distinct working capital profiles across tiers.
- Industrial Grade:Specifications tolerate higher sulfuric acid residuals and moisture content for bulk chemical manufacturing. Agrochemical formulators in India and Brazil absorb the largest volumes during herbicide synthesis campaigns. ANVISA registration timelines for ethylated crop protection intermediates extend procurement planning horizons.
- Pharmaceutical Grade:Impurity thresholds below 0.1% for specified contaminants with full batch documentation and stability data. East Asian contract manufacturers in Hyderabad and Shanghai clusters now require ICH Q7-compliant suppliers. CDSCO and NMPA inspections compress the qualified supplier base to pre-registered tonnage holders.
- Reagent Grade:Analytical laboratories specify consistent lot-to-lot performance for chromatographic applications.
- Laboratory Grade:Academic and R&D facilities prioritize small-package availability over certificate of analysis depth.
Industrial grade dominates installed base. Pharmaceutical grade is where expansion concentrates.
Application:
Cost tier stratification separates validated pharmaceutical intermediates from commodity chemical processing.
- Intermediate for Synthesis:Ethylation of amines, phenols, and carboxylic acids in active pharmaceutical ingredient construction. Swiss and German manufacturers of oncology intermediates specify ceramic membrane-purified material. REACH authorization obligations now transfer upstream from formulators to diethyl sulfate producers.
- Additive in Herbicides:Sulfonylurea chemistry applications absorb industrial-grade volumes with seasonal demand spikes. Brazil's Central-West soybean belt drives Q3 procurement surges for ethylated herbicide components.
- Solvent:Polar aprotic solvent applications in polymer chemistry favor bulk container logistics.
- Chemical Reagent:Standardized analytical methods for quality control laboratories emphasize lot traceability.
Intermediate for synthesis commands premium pricing tiers. Additive in herbicides generates highest absolute throughput.
End User:
Customer type fragmentation concentrates procurement power in consolidated pharmaceutical desks while dispersing agrochemical demand.
- Pharmaceutical Industry:Top-20 global pharma companies now unbundle ethylating agent supply from full-service intermediate packages. Direct supplier relationships with sulfonation specialists bypass traditional distributor markups in German and Swiss manufacturing networks.
- Agrochemicals:Formulators in Brazil and India register new ethylated active ingredients with national crop protection boards. Seasonal demand patterns require flexible inventory positioning.
- Chemical Manufacturing:Bulk chemical producers integrate backward into captive sulfonation capacity where ethylene oxide supply permits.
- Research Laboratories:Academic and government research facilities generate stable baseline demand with limited price sensitivity.
Chemical manufacturing holds deepest installed consumption. Pharmaceutical industry is climbing the fastest.
Packaging Type:
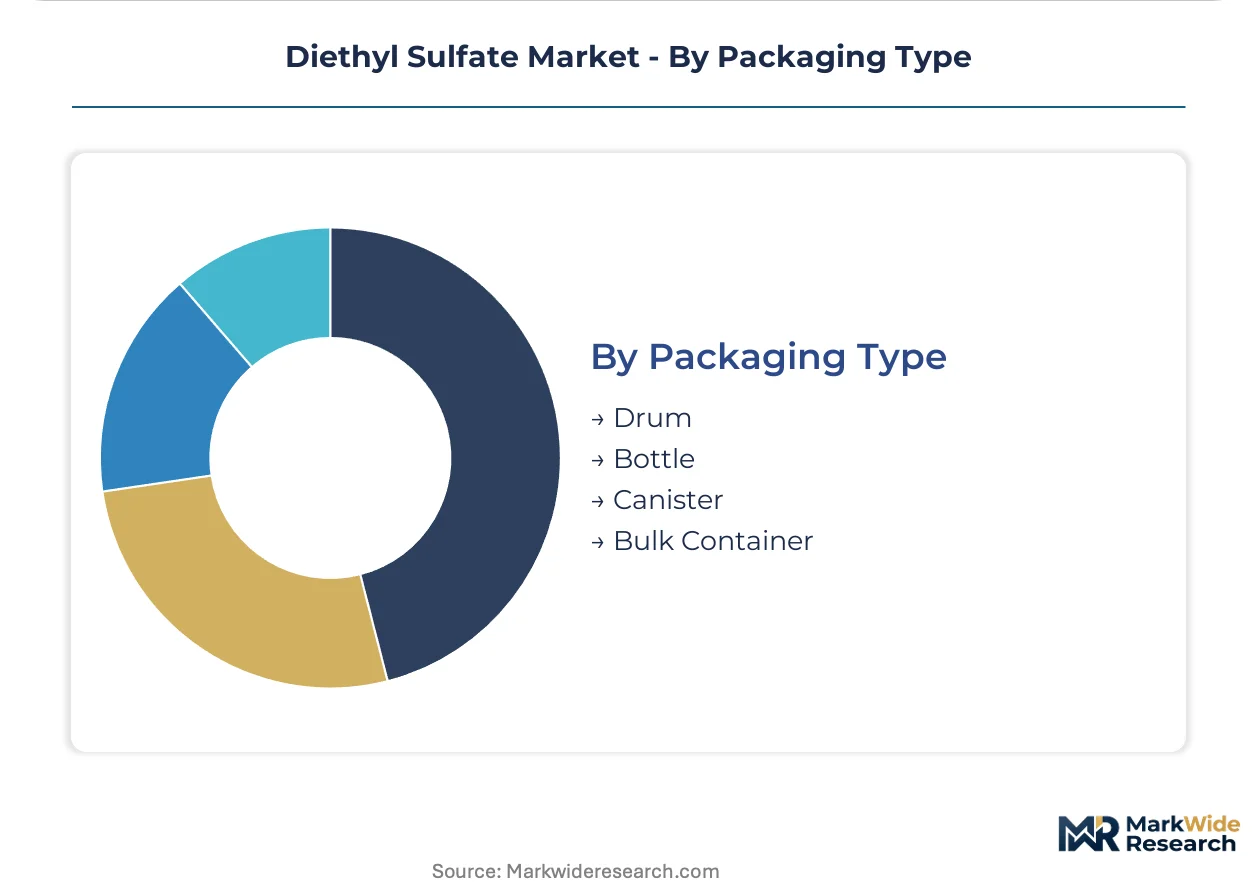
Supply concentration in drum and bulk container formats reflects divergent safety engineering and logistics economics.
- Drum:Standard 200-liter steel drums with UN certification for hazardous liquid transport. Pharmaceutical-grade drum lots require nitrogen blanket and sealed closure integrity verification.
- Bulk Container:ISO tank and flexitank configurations for industrial-grade agrochemical shipments. Port infrastructure in Santos and Mumbai determines viable export economics.
- Bottle:Amber glass and fluoropolymer-lined containers for reagent-grade laboratory distribution.
- Canister:Pressurized dispensing systems for specialized analytical applications.
Drum format dominates cross-border shipment volumes. Bulk container is gaining share fastest in agrochemical corridor supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade diethyl sulfate commands 40% price premiums in Switzerland and Germany against industrial-grade spot markets in India and Brazil. This asymmetry reflects divergent regulatory stringency and captive ethylene oxide integration economics across manufacturing corridors.
United States
EPA toxicity evaluations under TSCA and OSHA permissible exposure limits constrain domestic production economics for non-integrated manufacturers. The agency's IRIS assessments are elevating hazard communication requirements for ethylating agents. Houston-Gulf Coast petrochemical corridors maintain captive sulfonation capacity where ethylene oxide supply permits downstream diethyl sulfate output.
Germany
REACH authorization requirements for carcinogenic substances mandate substance-specific downstream user notifications ahead of sunset date deadlines. ECHA's 2024 Annex XIV updates now transfer registration obligations upstream from pharmaceutical formulators to diethyl sulfate producers. Ludwigshafen and Frankfurt-Rhine-Main manufacturing networks have narrowed qualified supplier lists to three certified sources.
China
NMPA pharmaceutical raw material standards and MEE environmental compliance audits are accelerating qualification timelines for diethyl sulfate feedstock suppliers. Contract manufacturing organizations in Shanghai and Jiangsu provinces are expanding dedicated alkylation capacity for active pharmaceutical ingredient synthesis. Yangtze River Delta clusters absorb the largest pharmaceutical-grade volumes.
India
CDSCO inspections are compressing the qualified supplier base to pre-registered tonnage holders for pharmaceutical-grade specifications. Hyderabad and Ahmedabad manufacturing zones lack sufficient domestic ethylating capacity relative to contract manufacturing demand. Gujarat-based producers are backward integrating into sulfonation chemistry to secure supply advantages.
Switzerland
Swissmedic pharmaceutical impurity guidelines and ICH Q7 compliance requirements govern import eligibility for ethylating intermediates. Basel and Zurich pharmaceutical corridors specify ceramic membrane-purified material for oncology intermediate manufacturing. Swiss producers pilot continuous-flow microreactor technology for smaller-batch pharmaceutical-grade production.
Diethyl Sulfate Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sulfonation chemistry with divergent margin structures. The field narrows around ethylene oxide captive supply and REACH-authorized tonnage registration. Three archetypes dominate: integrated petrochemical platforms with ethylene oxide streams, sulfonation specialists with pharmaceutical-grade certification, and regional chemical distributors serving spot industrial demand. Capacity expansion and backward integration into sulfonation chemistry represent the dominant competitive vectors.
Among integrated petrochemical platforms, BASF anchors European supply through captive ethylene oxide integration. Aarti Industries occupies a position within the South Asian specialist tier, representing sulfonation-focused producers serving pharmaceutical corridors. WeylChem International exemplifies the certification-differentiated archetype with European regulatory alignment. These three sit within distinct competitive vectors shaped by feedstock access and registration status rather than direct product rivalry.
| Leading Market Players |
|---|
| Aarti Industries |
| Taian Havay Group |
| Sinochem International Advanced Materials (Hebei) |
| BASF |
| Merck KGaA |
| Alfa Aesar |
| Honeywell International |
| Chevron Phillips Chemical Company |
| WeylChem International |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge freight corridors transmit ethylene oxide feedstock cost volatility directly into diethyl sulfate pricing spreads, amplifying the margin compression between captive-integrated German producers and spot-exposed Indian manufacturers while pharmaceutical-grade certification premiums widen across downstream buyer tiers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing stratification across pharmaceutical-grade, industrial-grade, and reagent-grade certification levels. Price differentiation rests on REACH authorization status and ICH Q7 compliance depth, with European-registered tonnage commanding substantial premiums over non-authorized Asian supply. Cost compression in industrial-grade segments is intensifying because Brazilian and Indian agrochemical formulators are consolidating procurement volumes around fewer qualified drum-shipment suppliers. Spot industrial buyers exhibit highest price sensitivity, while Swiss and German oncology intermediate manufacturers demonstrate lowest sensitivity due to validated supplier switching costs.
Supply Chain Analysis
Ethylene oxide availability centers on Ludwigshafen, Houston-Gulf Coast, and Yangtze River Delta production nodes, with sulfuric acid quality and membrane purification technology serving as critical input differentiators. Raw material dependencies draw from petrochemical ethylene streams, sulfuric acid concentration grades, and ceramic filtration module supply. Single-source vulnerability concentrates in European REACH-authorized tonnage holders, where sunset date deadlines have compressed viable supplier lists to three certified sources. Distribution runs through drum-format cross-border shipments for pharmaceutical-grade material and ISO tank configurations for industrial-grade agrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diethyl sulfate demand sits in early-cycle expansion as East Asian contract manufacturing organizations accelerate dedicated alkylation capacity buildouts for active pharmaceutical ingredient synthesis.
For Market Incumbents: Harden regulatory registration moats by accelerating REACH Annex XIV authorization dossiers ahead of downstream user notification deadlines. Deepen captive ethylene oxide integration through sulfonation chemistry backward integration in Hyderabad and Ahmedabad corridors to offset feedstock volatility exposure from spot market purchases. Dimethyl sulfate substitution pressure in methyl-to-ethyl switching economics represents the primary substitution threat requiring process-specific defensibility investments. For New Entrants and Emerging Players: Swiss and German pharmaceutical-grade supply gaps offer white-space entry points where ceramic membrane-purified material commands premium positioning. Target continuous-flow microreactor technology deployment for smaller-batch oncology intermediate production, bypassing the capital intensity barriers that protect incumbent batch-scale assets. Qualification through Swissmedic and EMA pre-submission pathways provides the fastest regulatory credibility build versus full REACH authorization timelines. For Investors and Strategic Acquirers: Sulfonation specialists with pharmaceutical-grade certification and pre-registered REACH tonnage represent the most defensible acquisition archetype within a five-to-ten year viability window. Monitor ECHA candidate list updates for carcinogenicity reclassification signals that would trigger accelerated substitution R&D spending across downstream formulators. CDSCO and NMPA inspection pass rates for Indian feedstock suppliers serve as early indicators of supply base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Authorization Completion | Secures European market access beyond sunset date deadlines for carcinogenic substances. |
| Backward Integration into Sulfonation | Captures ethylene oxide cost advantages and insulates margin structures from spot volatility. |
| Ceramic Membrane Technology Deployment | Eliminates neutralization waste streams and compresses regulatory approval timelines for greenfield units. |
| Continuous-Flow Microreactor Installation | Enables smaller-batch pharmaceutical-grade production with enhanced thermal safety control. |
| Pharmaceutical-Grade Certification Investment | Opens premium pricing tiers through ICH Q7 compliance and validated batch documentation. |
Methodological Framework
Operator-level perspectives from plant managers at sulfonation facilities, procurement leads at pharmaceutical contract manufacturers, distribution channel partners in drum and bulk logistics, and technical R&D directors in alkylation chemistry anchored the qualitative base. Secondary validation drew from customs and trade data, ECHA registration dossiers, SEC 10-K chemical segment disclosures, and CDSCO inspection outcome records. Bottom-up capacity and utilization estimates triangulated against top-down demand aggregation across pharmaceutical, agrochemical, and bulk chemical end-use segments.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning grade tier, end-use industry concentration, packaging format logistics economics, and regional production hub regulatory alignment. CAGRs derived from intensity-of-use modeling tied to active pharmaceutical ingredient production forecasts and herbicide formulation campaign cycles. Forecast inputs incorporated REACH authorization timeline probability assessments and ethylene oxide feedstock cost curve trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed petrochemical platforms or accelerated dimethyl sulfate substitution adoption by process chemists would shift outcomes materially. Cross-checking against ECHA tonnage registration databases and NMPA pharmaceutical raw material approval records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Tin Chemicals Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Calcium Carbide Market
Chemicals
Cyclopentylamine Market
Chemicals
Oxybenzone Market
Chemicals
Linear Mercaptans Market
Chemicals
Maleic Acid Market
Chemicals
Calcium Hydroxide Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Elemental Fluorine Market
Chemicals
Acetophenone Market
Chemicals
Aluminum Phosphide Market
Chemicals
Hydrazine Hydrate Market
Chemicals
Flatting Agents Market