
 5G Processor Market | 2026-2036
5G Processor Market Size, Share, and Industry Trends Forecast 2026-2036
5G Processor Market Analysis
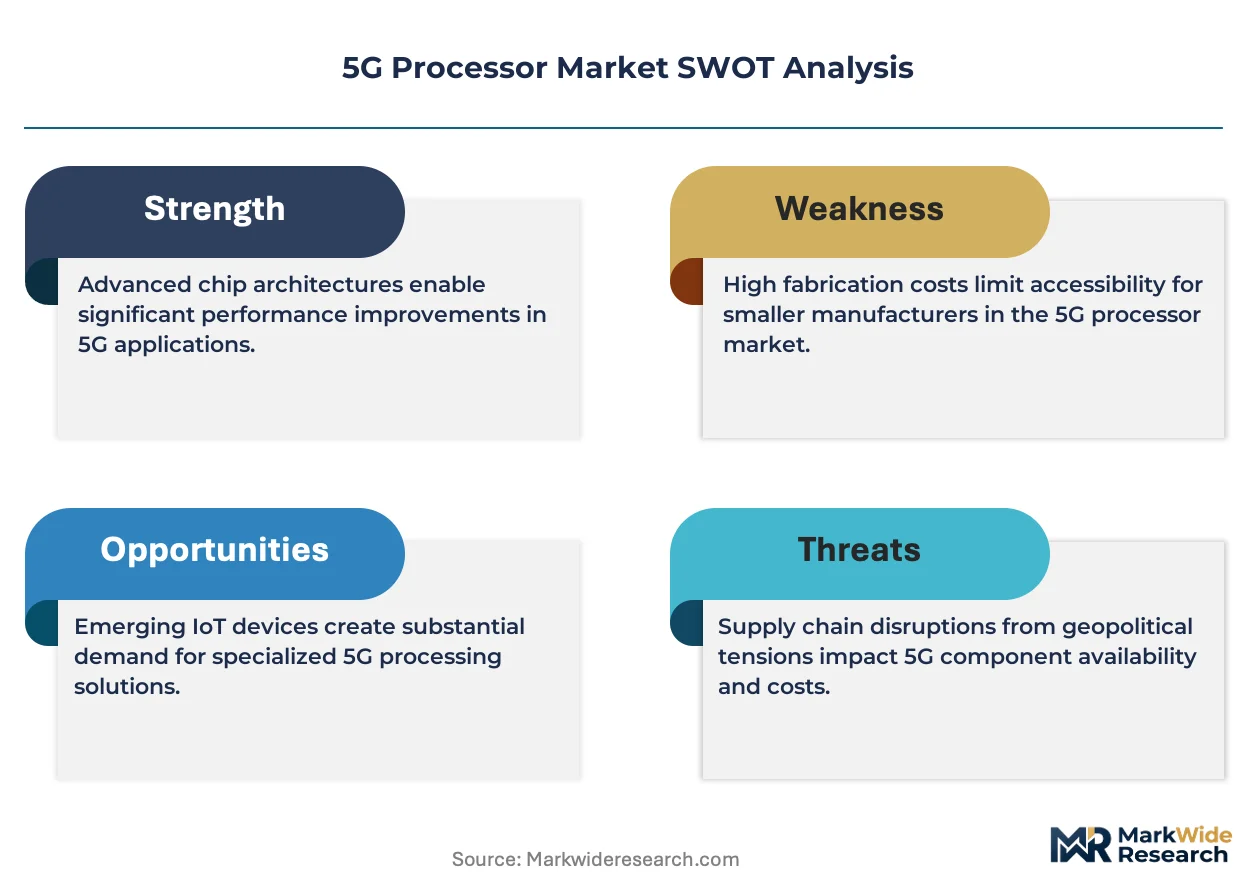
REACH compliance is broadening the cost-of-entry calculus for fabless 5G processor designers targeting European device manufacturers. Qualcomm anchors its position through deep R&D partnerships with infrastructure OEMs across multiple spectrum bands. MediaTek competes aggressively on price-performance metrics in the mid-tier smartphone segment across emerging economies. TSMC sustains manufacturing leadership through advanced node allocation dedicated to 5G baseband and RF front-end integration.
A 5G processor is a system-on-chip or dedicated integrated circuit that modulates and demodulates radio signals across sub-6 GHz and millimeter-wave frequencies, typically fabricated on 7 nm or smaller process nodes to achieve power efficiency below 1 watt per gigabit throughput. Its primary purpose is to enable high-data-rate wireless connectivity for consumer, industrial, and vehicular endpoints. SoC architectures now dominate smartphone deployments where baseband, application processing, and AI acceleration must coexist on a single die. Infrastructure ASICs command premium margins due to carrier-grade reliability requirements and custom protocol stack integration. FPGA variants serve prototyping and low-volume defense or satellite communication applications where reconfigurability outweighs unit cost.
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct certification regimes for 5G new radio equipment, forcing silicon vendors to maintain parallel validation laboratories and regional firmware branches. The EU AI Act and emerging cybersecurity labeling requirements are adding conformance layers to processor shipments destined for enterprise IoT and automotive gateways. Stakeholders must monitor spectrum re-farming decisions in major economies, as these directly dictate which frequency combinations processors must support in next-generation designs.
Market Dynamics
Automotive OEM procurement of 5G modems for connected vehicle platforms is compressing qualification timelines and forcing foundry capacity reallocation toward automotive-grade silicon certification.
Growth Catalysts
- FCC Mid-Band Auctions:Compressed licensing timelines in the United States have intensified chipset qualification cycles, pulling forward demand for sub-6 GHz capable silicon across infrastructure OEMs.
- Connected Vehicle Mandates:Automotive platforms requiring V2X communication protocols are embedding 5G baseband processors directly into telematics control units, bypassing aftermarket retrofit channels.
- South Korean Foundry Investment:Government-backed advanced packaging capacity consolidation is capturing mmWave and sub-6 GHz tape-out volumes from fabless designers seeking turnkey integration.
Market Restraints
- Advanced Node Concentration:7 nm and smaller process availability clusters at single-source foundries in Taiwan and South Korea, creating supply vulnerability for baseband and RF front-end integration.
- REACH Compliance Burden:ECHA substance restrictions on semiconductor materials are broadening cost-of-entry calculus for fabless designers targeting European device manufacturers.
- mmWave Propagation Limitations:Signal attenuation through physical obstacles constrains indoor and dense urban deployment, limiting addressable use cases for high-bandwidth 5G processors.
Strategic Opportunities
- Enterprise IoT Gateways:EU AI Act cybersecurity labeling requirements are creating conformance-driven demand for processors with hardware-rooted trust execution environments in industrial automation.
- India Manufacturing Incentives:PLI scheme allocations for telecom equipment are attracting assembly and test investments that could support regional 5G module production for domestic carriers.
- Open RAN Convergence:Disaggregation of baseband processing from proprietary hardware is modularizing procurement, enabling merchant silicon vendors to supply distributed unit architectures.
Industry Challenges
- Multi-Band Certification Complexity:Parallel validation laboratories for FCC, ETSI, and MIIT regimes force firmware branching and regional SKU proliferation, extending time-to-revenue.
- RF-Baseband Integration Talent Scarcity:Compound semiconductor design expertise for millimeter-wave front-ends remains concentrated among experienced engineering teams at incumbent suppliers.
- Automotive Functional Safety:ISO 26262 ASIL-D compliance for processor cores in autonomous vehicle platforms demands fault-tolerant architectures that inflate die area and validation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Processor Market |
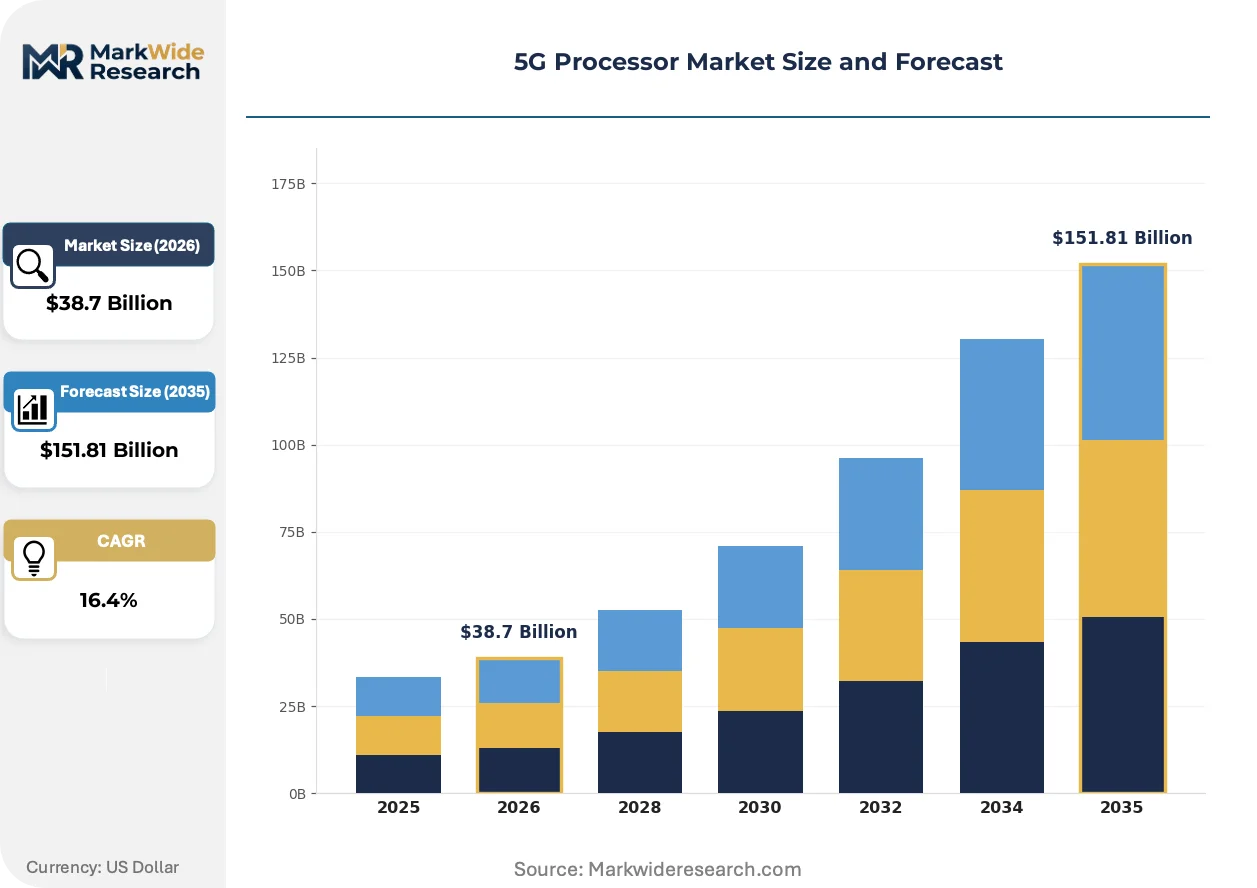
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SoC, ASIC, FPGA, DSP Application: Smartphones, IoT Devices, Infrastructure, Automotive End User: Telecom Operators, Device Manufacturers, Automotive OEMs, Enterprises Technology: Massive MIMO, Beamforming, Network Slicing, Edge Computing |
| Companies Covered | Samsung, HiSilicon, Qualcomm, TSMC, Unisoc, Apple, Google, Samsung Foundry, MediaTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Processor Market Emerging Trajectories
Silicon architectures are fragmenting across application-specific optimizations as power-performance requirements diverge between consumer handsets, infrastructure equipment, and vehicular platforms.
Chiplet-based baseband designs are modularizing 5G modem construction. These disaggregated architectures separate RF transceivers from digital baseband processing, enabling foundry process optimization for each functional block. Infrastructure OEMs are adopting chiplet configurations to mix-and-match protocol stack accelerators, compressing development cycles for carrier-specific feature variants. This approach is modularizing what had been monolithic SoC roadmaps.
ETSI cybersecurity certification frameworks for critical infrastructure are mandating hardware security module integration in 5G new radio equipment. The EU Cybersecurity Act's Common Criteria evaluation is extending procurement timelines for base station processors destined for European carriers. Vendors are responding by embedding post-quantum cryptographic accelerators and secure boot architectures earlier in product development cycles.
Automotive tier-one suppliers are consolidating modem sourcing under long-term capacity reservation contracts. This behavioral shift displaces spot-market purchasing, locking foundry wafers years ahead of vehicle platform launches. German and Japanese automotive clusters exhibit the most pronounced contract duration extension, with some agreements spanning full model generation lifecycles.
5G Processor Market Segmentation
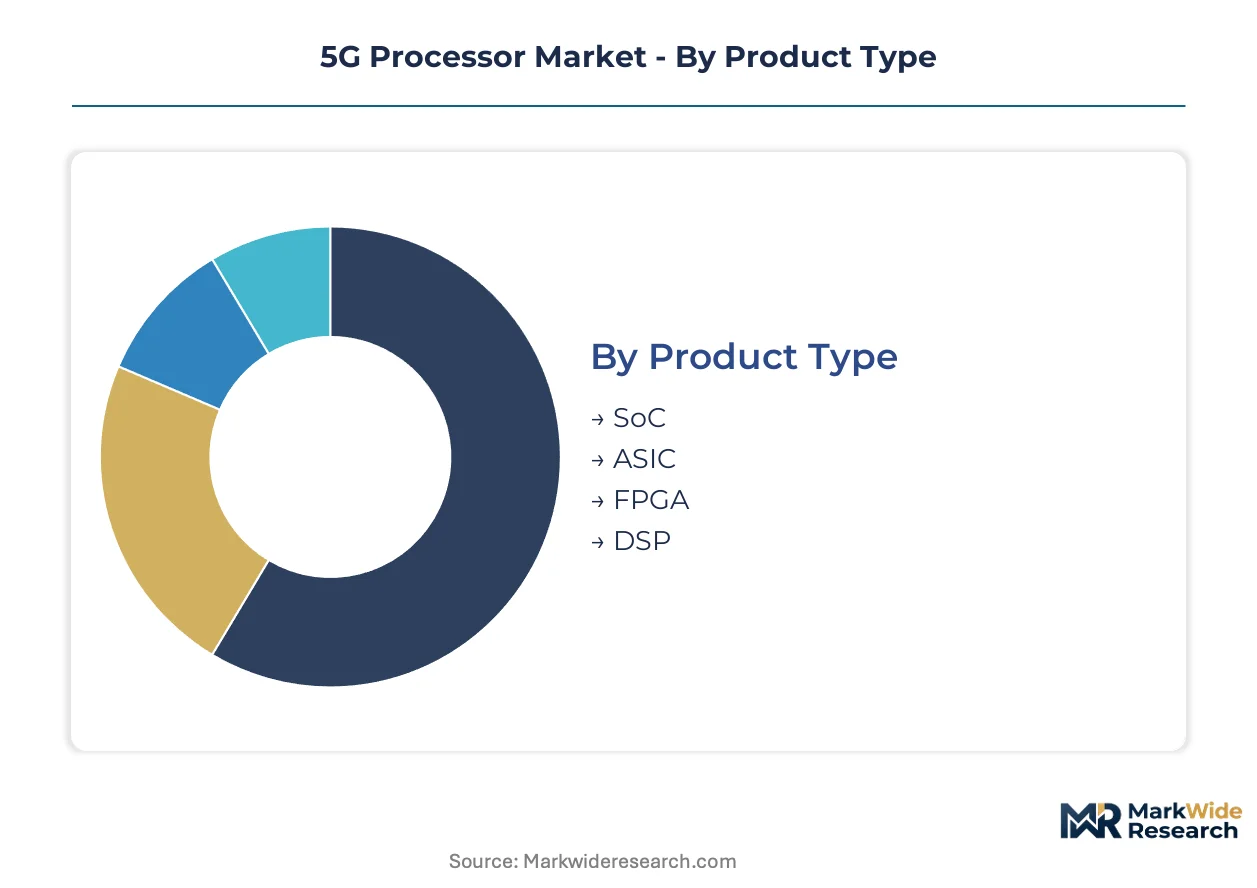
5G processor architectures fragment sharply across power envelopes, certification regimes, and integration requirements. Each segment category carries distinct margin profiles and foundry allocation priorities that reshape competitive positioning.
Product Type:
Volume shipments concentrate in consumer-facing silicon, while premium margins attach to specialized compute architectures.
- SoC:Monolithic dies integrate baseband, application cores, and AI accelerators on 7 nm or smaller nodes. Smartphone OEMs in South Korea and China drive procurement volumes exceeding infrastructure deployments by an order of magnitude.
- ASIC:Custom silicon for carrier-grade base stations commands extended validation cycles and multi-year supply agreements. Telecom operators specify ASIC architectures to embed proprietary protocol optimizations unavailable in merchant silicon.
- FPGA:Reconfigurable logic serves defense prototyping and satellite communication where firmware updates must outpace hardware replacement.
- DSP:Digital signal processors handle computationally intensive physical layer functions in legacy infrastructure upgrades where full baseband replacement is uneconomical.
Today's leader: SoC. Tomorrow's challenger: ASIC.
Application:
Demand intensity varies by certification burden and unit economics, with automotive platforms exhibiting the steepest qualification requirements.
- Smartphones:Handset SoCs dominate wafer allocation at leading foundries. MediaTek and Qualcomm anchor procurement volumes across mid-tier and flagship tiers respectively.
- Infrastructure:Base station processors require thermal design power envelopes above 15 watts and hardware redundancy for carrier-grade reliability.
- Automotive:Telematics control units embed 5G modems under ISO 26262 ASIL-D functional safety mandates. German and Japanese OEMs lock foundry capacity through model-generation-spanning contracts.
- IoT Devices:Narrowband-IoT and reduced-capability chipsets serve industrial sensors where sub-gigabit throughput suffices.
Infrastructure captures the highest per-unit margins. Automotive represents the fastest volume expansion trajectory.
End User:
Procurement authority concentrates differently across volume scale, technical specification control, and supply chain leverage.
- Telecom Operators:Carriers specify baseband architectures for macro cells and small cells, often mandating ETSI cybersecurity certification for European deployments.
- Device Manufacturers:Smartphone OEMs negotiate die allocation years ahead of flagship launches, compressing time-to-market windows for modem integration.
- Automotive OEMs:Vehicle platforms require 15-year silicon supply guarantees and AEC-Q100 automotive qualification.
- Enterprises:Private 5G networks for manufacturing and logistics drive demand for industrial-grade gateways with hardware security module integration.
Device manufacturers command the largest procurement volumes. Automotive OEMs are reshaping contract structures toward long-term reservation.
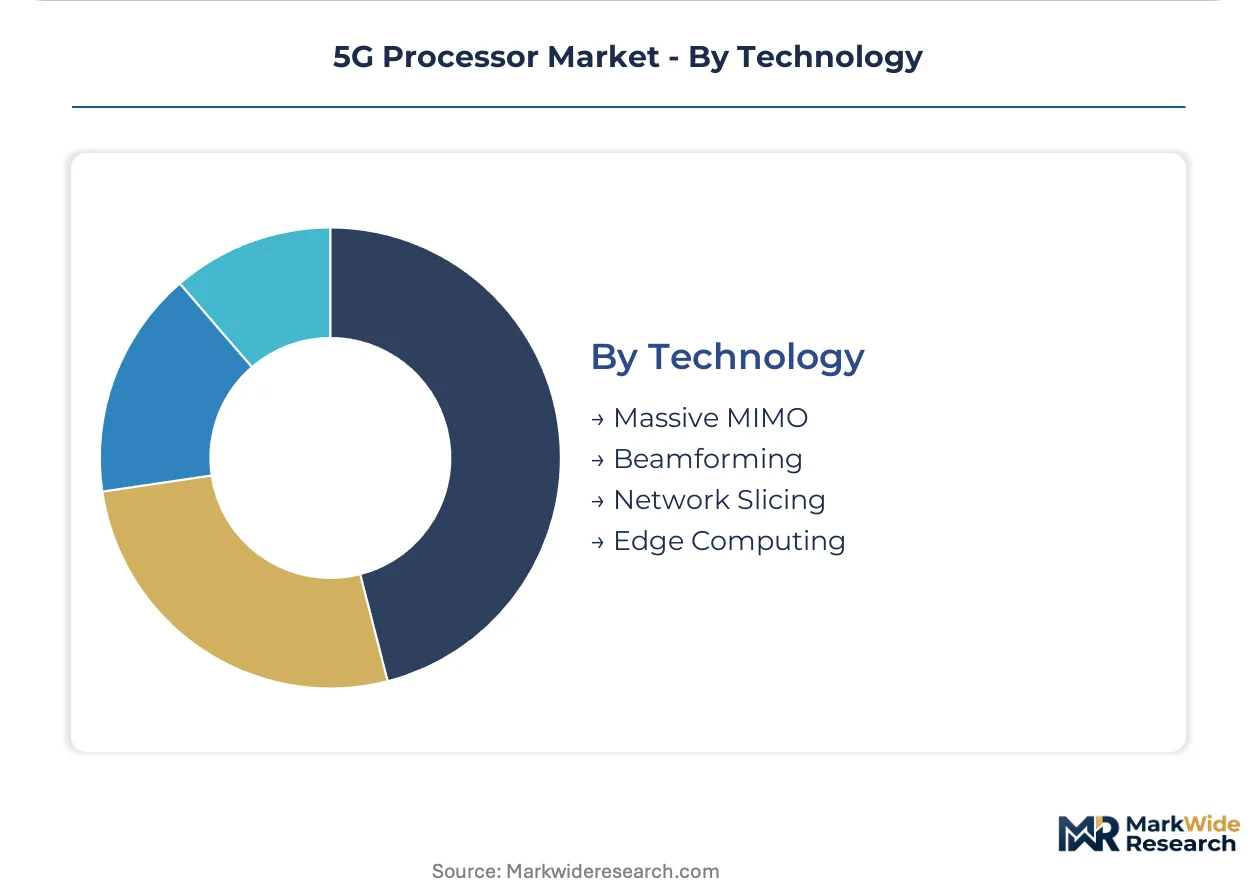
Technology:
Radio layer innovations determine spectral efficiency and capital expenditure requirements for network buildouts.
- Massive MIMO:64T64R antenna configurations multiply baseband processing requirements, concentrating ASIC demand at infrastructure OEMs.
- Beamforming:Analog and hybrid beamforming architectures for mmWave frequencies require tight RF-baseband co-design.
- Network Slicing:Virtualized core functions push edge computing requirements into distributed unit processors.
- Edge Computing:Multi-access edge computing nodes embed AI inference accelerators alongside 5G baseband for ultra-low latency applications.
Massive MIMO anchors current infrastructure investment. Edge computing is gaining share fastest as latency requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor design talent clusters in the United States, South Korea, Taiwan, and China anchor 5G processor innovation pipelines. Foundry capacity concentrates in East Asian manufacturing corridors where government-backed incentives reshape tape-out decisions. Regulatory divergence across FCC, ETSI, and MIIT regimes forces parallel certification tracks that extend time-to-market.
United States
FCC mid-band spectrum auctions have compressed licensing timelines and intensified chipset qualification cycles across infrastructure OEMs. The CHIPS and Science Act allocates fabrication subsidies that pull advanced node capacity toward domestic facilities. Austin and Phoenix anchor emerging foundry clusters where TSMC and Samsung Foundry expand 3 nm and 4 nm production lines for baseband silicon.
South Korea
Samsung and government-backed foundry investments consolidate advanced packaging capacity for sub-6 GHz and mmWave silicon tape-outs. The Ministry of Trade, Industry and Energy directs fiscal support toward heterogeneous integration facilities in Pyeongtaek. Seoul Capital Area design houses accelerate chiplet-based modem architectures that separate RF transceivers from digital baseband blocks.
China
MIIT certification mandates for 5G new radio equipment enforce domestic protocol stack requirements that favor local baseband designers. The dual carbon goals program imposes energy efficiency standards on semiconductor manufacturing that reshape foundry process selection. Yangtze River Delta fabrication complexes in Shanghai and Wuxi concentrate 7 nm and 14 nm capacity for infrastructure ASIC production.
Taiwan
TSMC sustains manufacturing leadership through advanced node allocation dedicated to 5G baseband and RF front-end integration. The National Development Council coordinates supply chain resilience initiatives that secure precursor chemical flows for leading-edge fabs. Hsinchu Science Park anchors the densest concentration of fabless design talent serving smartphone and infrastructure OEMs.
Germany
Automotive OEM procurement of 5G modems for connected vehicle platforms compresses qualification timelines and forces foundry capacity reallocation toward automotive-grade silicon. The KBA enforces type approval protocols for V2X communication modules that extend validation cycles. Bavaria and Baden-Württemberg host tier-one supplier clusters where telematics control unit integration concentrates.
5G Processor Market Vendor Landscape
The competitive structure tilts toward integrated device manufacturers and fabless specialists with captive foundry relationships. Market concentration remains high at the leading edge where 3 nm and 4 nm baseband production clusters at single-source facilities. Two archetypes dominate: vertically integrated electronics conglomerates controlling design-through-fabrication workflows, and fabless chip designers dependent on merchant foundry allocation. Competitive moves center on long-term capacity reservation contracts and strategic R&D partnerships with infrastructure OEMs.
Among vertically integrated players, Samsung and Apple exemplify the design-capture-fabrication archetype through in-house modem development and captive foundry access. Qualcomm and MediaTek occupy positions as fabless specialists anchoring merchant silicon supply for smartphone OEMs across mid-tier and flagship tiers. TSMC represents the foundry-centric archetype that enables competitive positioning for non-integrated designers through advanced node allocation.
| Leading Market Players |
|---|
| Samsung |
| HiSilicon |
| Qualcomm |
| TSMC |
| Unisoc |
| Apple |
| Samsung Foundry |
| MediaTek |
| Others |
Supply Flow & Price Mechanics
REACH substance restrictions from ECHA gate qualified supply for European automotive and industrial gateways, compressing vendor pools and sustaining premium-tier pricing for compliant silicon. Foundry allocation battles between smartphone OEMs and automotive platforms concentrate pricing power at advanced nodes where certification-validated supply remains scarce.
Pricing Analysis
SoC pricing separates bundled modem-application processor integration from unbundled baseband-only procurement, with smartphone OEMs capturing volume discounts through multi-year die allocation commitments. Price differentiation hinges on certification grade—ETSI cybersecurity labeling and ISO 26262 ASIL-D compliance inflate unit economics by fifteen to thirty percent—and foundry node geometry, where 3 nm tape-outs command substantial premiums over 7 nm alternatives. Cost compression in mid-tier smartphone silicon is intensifying because MediaTek and Unisoc are racing price-performance benchmarks in emerging economies. Telecom operators exhibit the lowest price sensitivity due to carrier-grade reliability mandates, while IoT gateway manufacturers face acute margin pressure from hardware security module integration requirements.
Supply Chain Analysis
ETSI, FCC, and MIIT certification gating forces parallel validation tracks that fragment inventory and extend procurement cycles for multi-region deployments. Manufacturing concentrates in Taiwan, South Korea, and the United States, with TSMC and Samsung Foundry anchoring advanced node capacity for baseband and RF front-end integration. Raw material dependencies draw from silicon wafers, compound semiconductor substrates for mmWave front-ends, and advanced packaging materials for chiplet-based architectures. Single-source vulnerability at 3 nm and 4 nm production lines creates supply risk for flagship smartphone and infrastructure silicon. Distribution runs through direct foundry relationships for automotive OEMs and tier-one infrastructure vendors, while merchant silicon reaches handset manufacturers via consolidated electronics manufacturing service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive functional safety mandates and ETSI cybersecurity frameworks are concentrating procurement authority with vendors holding validated supply. Premium specifications now dominate RFP criteria across connected vehicle and critical infrastructure segments.
For Market Incumbents: Cement long-term foundry capacity reservations through model-generation-spanning contracts with automotive clusters in Germany and Japan, insulating against spot-market volatility. Deepen R&D partnerships with infrastructure OEMs for Open RAN distributed unit architectures, defending against merchant silicon encroachment from chiplet-based competitors. Prioritize backward integration into advanced packaging capabilities to capture margin pools currently flowing to outsourced assembly and test providers.
For New Entrants and Emerging Players: Chiplet-based baseband disaggregation offers a technology-first wedge into infrastructure markets where incumbent monolithic SoC roadmaps face carrier pressure for modular procurement. Target private 5G network deployments in European manufacturing and logistics, where EU AI Act compliance requirements favor new hardware-rooted trust execution environments over legacy silicon retrofits. Pursue strategic partnerships with Indian PLI scheme beneficiaries to establish regional assembly and test footprints for domestic carrier supply.
For Investors and Strategic Acquirers: Roll-up economics work for fabless baseband specialists with captive RF design talent because compound semiconductor expertise remains concentrated among experienced engineering teams at incumbent suppliers. Five-to-ten year viability hinges on securing foundry allocation at nodes below 7 nm as smartphone and automotive demand converges. Watch for inflection in FCC spectrum re-farming decisions, which directly dictate frequency combination requirements for next-generation processor designs and reshape addressable market size for sub-6 GHz versus mmWave-capable silicon.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Foundry Capacity Reservation | Automotive OEMs in Germany lock wafer supply through full vehicle model generation lifecycles. |
| Chiplet-Based Modem Architecture Development | Infrastructure OEMs mix-and-match protocol stack accelerators for carrier-specific feature variants. |
| ETSI Cybersecurity Certification Investment | Hardware security module integration extends procurement timelines for European base station deployments. |
| Open RAN Distributed Unit Supply | Merchant silicon vendors bypass proprietary hardware lock-in through modular baseband procurement. |
| Automotive-Grade Silicon Qualification | AEC-Q100 validation and ISO 26262 ASIL-D compliance open telematics control unit integration channels. |
Methodological Framework
Bottom-up smartphone and infrastructure deployment modeling reconciled against top-down foundry capacity and wafer allocation tracking forms the analytical core of this study. Primary interviews with baseband engineering directors, automotive platform procurement managers, telecom operator network planning executives, and foundry customer business unit heads combined with secondary validation from SEC 10-K filings, MIIT certification registries, FCC equipment authorization databases, and ETSI standardization committee records. Triangulation across these sources ensures demand-side shipment estimates align with supply-side manufacturing constraints.
Historical trendline analysis of sub-6 GHz and mmWave processor shipments across the projection horizon informs growth trajectory calibration. Segmentation modeling spans product architecture, application vertical, end-user procurement authority, and radio layer technology, with specific treatment of automotive functional safety tier and ETSI cybersecurity certification status as forecast modifiers. CAGRs derive from regression analysis against semiconductor capital expenditure cycles and spectrum auction timing in major economies.
The model holds under stable foundry capacity expansion and regulatory certification timeline assumptions; deviation in FCC mid-band auction velocity or REACH substance restriction enforcement would shift volume and value outputs. Forecasts reflect documented assumptions regarding smartphone refresh cycles, connected vehicle platform launch schedules, and private 5G network deployment cadence. A model refresh is warranted upon material change in MIIT domestic protocol stack requirements or TSMC advanced node allocation priorities for baseband silicon.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
United States Data Center Processor Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Car Chip Market