
 Coated Wood Free Papers Market | 2026-2036
Coated Wood Free Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Wood Free Papers Market Analytics
Single-source pulp procurement is decoupling from long-term supplier contracts across the coated wood free papers value chain. UPM Kymmene Corporation leverages its integrated Nordic pulp assets to control raw material flow from forest to mill. Sappi Limited anchors its competitive stance through specialized fine paper grades for publishing clients. Oji Holdings Corporation competes via extensive Asian distribution networks serving commercial printers.
Coated wood free papers consist of bleached chemical pulp sheets with mineral coating layers applied through blade or air-knife processes, yielding surface finishes between 70 and 150 gloss units at 75 degrees for high-resolution image reproduction. The publishing segment retains mature volume pools across magazine and catalog grades, though margin compression persists in standard-tier coated sheets. Packaging applications represent the fastest-expanding end-use channel as brand owners substitute plastic substrates with printable paper-based barriers. Premium-grade coated rolls command disproportionate margin contribution relative to their volume share due to stringent brightness and smoothness specifications.
FDA food-contact substance regulations govern coated paper barriers migrating into direct packaging applications, while REACH restricts specific chemical additives in European coating formulations. The EU Deforestation Regulation mandates geolocation traceability for all pulp fiber entering EU-consumed coated papers, elevating compliance costs for non-integrated converters. Stakeholders must monitor pulp futures volatility and certification scheme fragmentation as dual pressures on input cost predictability.
Market Dynamics
EU Deforestation Regulation traceability mandates are forcing pulp converters to reconfigure sourcing networks, decoupling from spot-market fiber purchases toward geolocated supply chains with documented chain-of-custody certification.
Growth Catalysts
- EU Green Deal packaging mandates:Luxury cosmetics and spirits brands are substituting plastic laminates with printable coated barriers to meet circular economy targets, pulling premium-grade volume through German and French converters.
- Barrier coating chemistry advances:Mineral-polymer hybrid formulations now achieve grease resistance equivalent to polyethylene, unlocking food-contact applications previously reserved for plastic substrates.
- Rhine-Ruhr industrial corridor concentration:Integrated mills in North Rhine-Westphalia benefit from barge-accessible pulp terminals and on-site coating lines, compressing logistics costs for European publishers.
Market Restraints
- Pulp futures volatility:Hardwood fiber contracts indexed to NBSK pricing expose non-integrated converters to margin compression when Scandinavian supply tightens.
- REACH chemical restrictions:ECHA scrutiny of fluorinated barrier chemistries limits coating formulation flexibility for food-contact grades entering European distribution.
- Digital substitution in publishing:Magazine and catalog volume pools face structural decline as retail brands migrate seasonal content to interactive digital platforms.
Strategic Opportunities
- Underpenetrated Indian packaging conversion:Domestic fine paper mills lack barrier coating capacity, creating white space for technical partnerships with European equipment suppliers.
- Pharmaceutical serialization compliance:EU Falsified Medicines Directive track-and-trace requirements favor coated papers with embedded security features for secondary packaging.
- Carbon accounting integration:CSRD disclosure rules reward pulp suppliers with verified Scope 3 data, favoring vertically integrated forest products groups over merchant market buyers.
Industry Challenges
- Geolocation certification backlog:EU Deforestation Regulation compliance timelines outpace auditor capacity, delaying market access for converters dependent on mixed tropical-hardwood fiber blends.
- Coating line retrofit capex:Blade-to-air-knife process conversions require seven-figure capital commitments with payback periods exceeding typical contract durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Wood Free Papers Market |
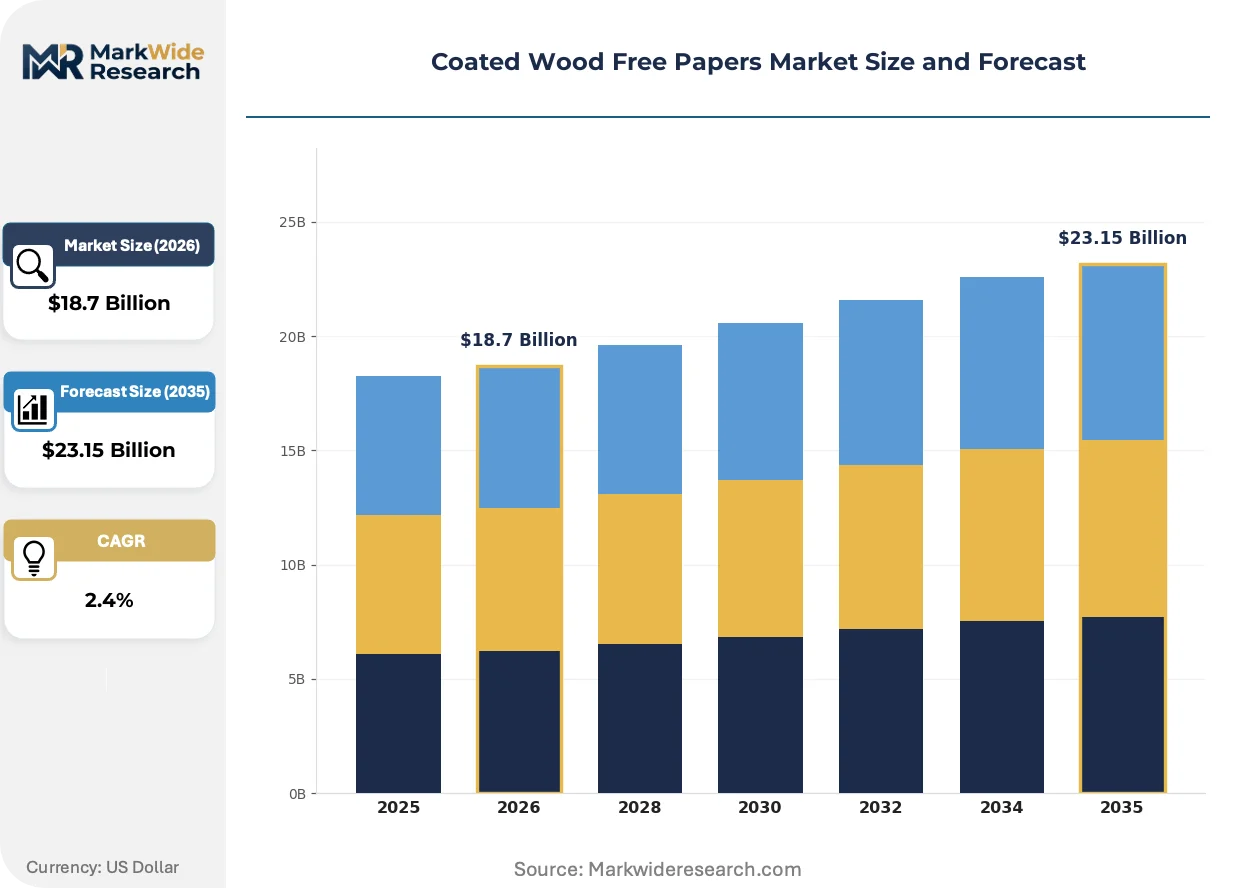
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $23.15 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Sheets, Coated Rolls, Magazines, Catalogs End Use: Publishing, Packaging, Commercial Printing, Stationery Grade: High-Quality, Premium, Standard, Economic Distribution Channel: Online, Retail Stores, Direct Sales, Distributors |
| Companies Covered | UPM Kymmene Corporation, Nippon Paper Industries Co Ltd, Sappi Limited, Puyang Longfeng Paper Co., Ltd., Oji Holdings Corporation, International Paper, Stora Enso Oyj, Neenah Paper, Lecta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Wood Free Papers Market Evolving Landscape
Active coating deposition methods and pulp traceability systems are compressing the gap between commodity grades and performance-specified barriers, reshaping how converters segment their product portfolios and price differentiated output.
Biopolymer-infused mineral coatings is converging with conventional blade application equipment to produce compostable barrier papers. Specialty coffee roasters in Scandinavia and premium chocolate brands in Belgium are piloting these substrates for direct food contact. The technology is converging with existing coating infrastructure, allowing mid-scale converters to enter barrier packaging without greenfield investment.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy greaseproof chemistries from European coating kitchens. Formulators are pivoting toward cellulose-derivative and starch-based alternatives with comparable Cobb values. Food-service packaging grades for quick-service restaurant chains face the steepest compliance timeline, driving accelerated qualification cycles at German and Dutch pilot plants.
Brand-owner sustainability scorecards now weight recycled fiber content above brightness specifications in coated paper procurement decisions. Publishing houses and luxury goods marketers are accepting modest gloss-unit tradeoffs to secure FSC-certified supply with documented post-consumer waste streams. This preference rotation is most visible in French and Italian packaging design studios, where environmental claims support premium positioning against plastic competitors.
Coated Wood Free Papers Market Segmentation
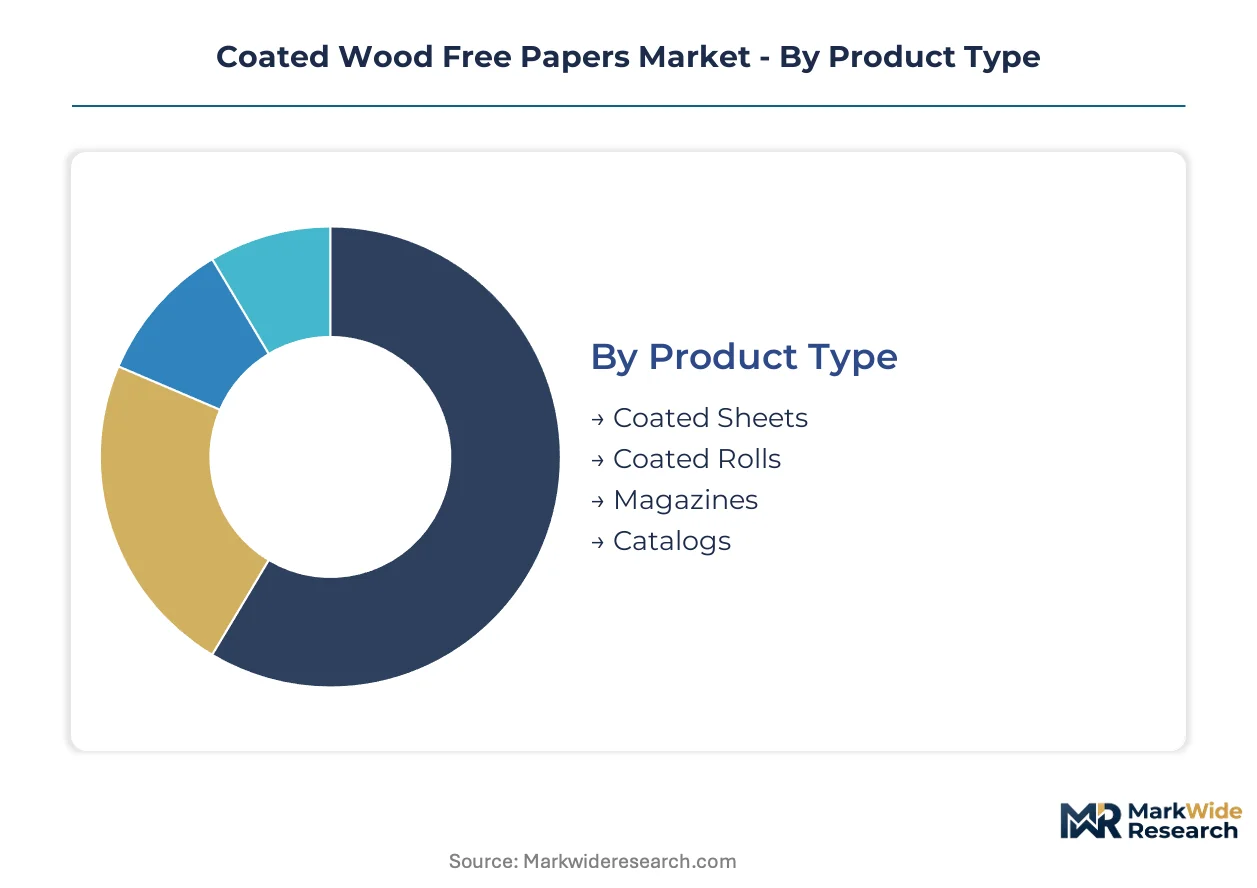
Segmentation in coated wood free papers reveals how coating technology and supply chain configuration split value capture between commodity converters and specialized barrier producers. Each dimension—product form, end application, quality tier, and channel—carries distinct margin profiles and capital requirements.
Product Type:
Coated sheets and rolls serve fundamentally different integration depths: rolls feed continuous coating lines at integrated mills, while sheets reach converters as discrete inputs for downstream finishing.
- Coated Sheets:Precut dimensions from 640×900mm to 700×1000mm ship flat-packed to commercial printers and packaging converters. German publishing houses in the Rhine-Ruhr corridor source these for short-run magazine work where sheet-fed offset dominates.
- Coated Rolls:Jumbo reels up to 10 meters wide run through blade or air-knife coaters at integrated facilities, then slit to customer widths. Demand clusters at North Rhine-Westphalia mills with barge-accessible pulp terminals and on-site coating infrastructure.
- Magazines:Lightweight grades from 60-90 gsm with calibrated bulk for postal efficiency. French and Italian design studios specify these for luxury brand collateral where environmental claims support premium positioning.
- Catalogs:Heavier basis weights from 100-150 gsm with enhanced opacity for double-sided image reproduction. Retail brands migrating seasonal content to digital platforms have compressed volume pools for standard catalog grades.
Volume placements concentrate in coated rolls; the faster expansion belongs to coated sheets as packaging converters seek format flexibility for barrier applications.
End Use:
End-use segmentation tracks how coated wood free papers compete against plastic substrates and digital alternatives across distinct value chains.
- Publishing:Magazine and catalog grades face structural decline as advertising spend shifts to interactive platforms. Remaining demand concentrates in premium art-book and annual report segments where tactile quality commands persistent budgets.
- Packaging:Barrier-coated papers with mineral-polymer hybrid formulations achieve grease resistance equivalent to polyethylene. Belgian chocolate brands and Scandinavian coffee roasters pilot these for direct food contact, pulling volume through German and French converters.
- Commercial Printing:General-purpose coated stocks for corporate collateral, direct mail, and point-of-sale materials. This segment absorbs excess capacity from publishing-grade assets repurposed for shorter runs.
- Stationery:High-brightness sheets for premium writing papers and corporate identity systems. Italian and French stationery houses source these with documented post-consumer waste streams to meet brand-owner sustainability scorecards.
Revenue concentration sits with publishing heritage assets; packaging applications are climbing the fastest as EU Green Deal mandates displace plastic laminates.
Grade:
Grade stratification separates specification-driven premium tiers from price-sensitive commodity pools, with certification status now outweighing brightness in procurement decisions.
- High-Quality:Brightness above 96 ISO with stringent smoothness specifications for high-resolution image reproduction. These grades command disproportionate margin contribution relative to volume share in luxury cosmetics and spirits packaging.
- Premium:FSC-certified supply with documented chain-of-custody and post-consumer waste content. French packaging design studios specify these for brand owners accepting modest gloss-unit tradeoffs to secure environmental claims.
- Standard:Mid-tier brightness and surface finish for general commercial applications. REACH chemical restrictions on fluorinated barrier chemistries have limited formulation flexibility for food-contact grades in this tier.
- Economic:Basic coated stocks for price-sensitive applications with minimal certification requirements. Margin compression persists here as pulp futures volatility exposes non-integrated converters to input cost swings.
Margin capture concentrates in high-quality grades; premium certified supply is gaining share fastest as CSRD disclosure rules reward verified Scope 3 data.
Distribution Channel:
Channel structure reflects the tension between mill-direct efficiency for volume accounts and distributor flexibility for fragmented converter bases.
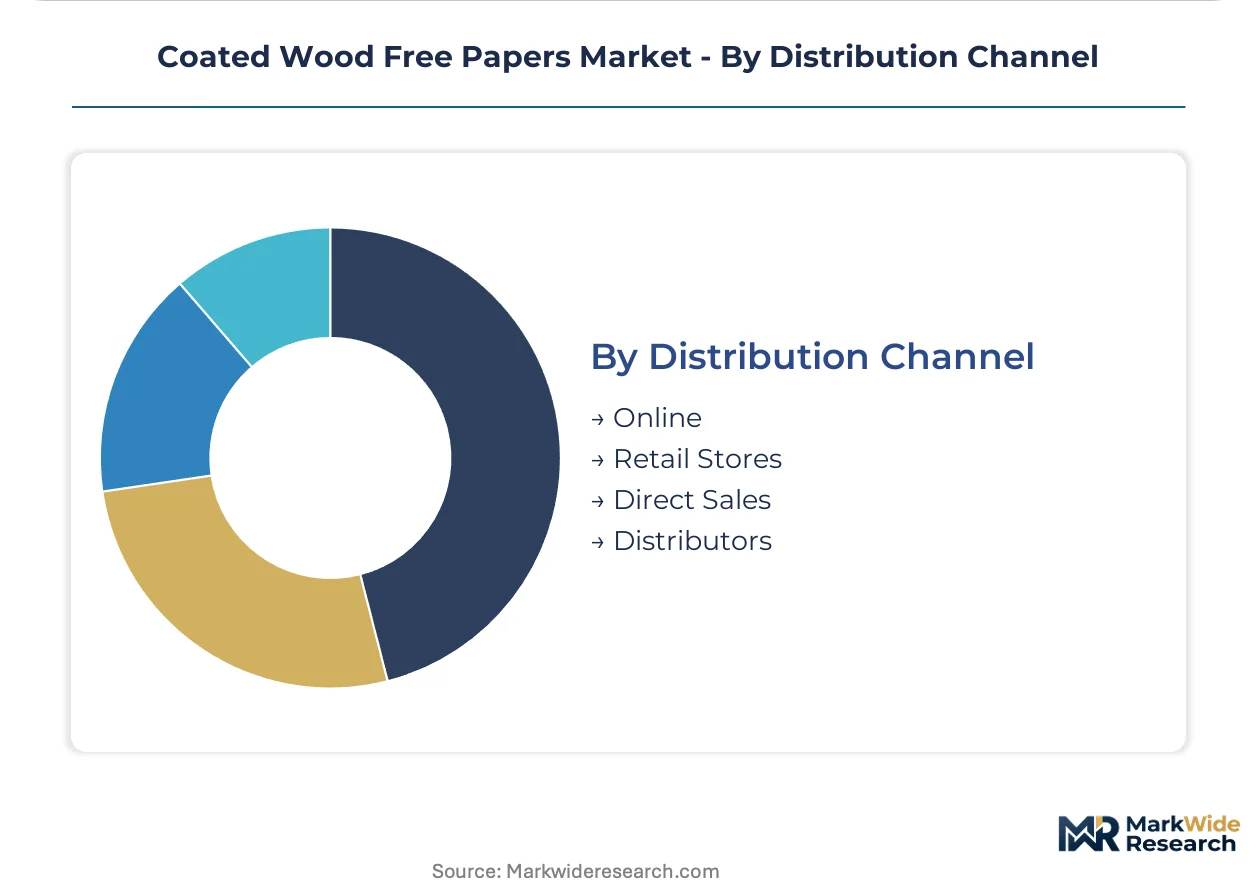
- Online:Digital procurement platforms for standardized grades with transparent pricing and rapid turnaround. Small commercial printers in fragmented European markets use these for spot purchases outside contracted volumes.
- Retail Stores:Physical paper merchants serving local print shops and design studios with immediate availability and technical consultation. This channel retains importance for color-critical applications requiring physical sample verification.
- Direct Sales:Mill-direct relationships for volume publishers and major packaging converters with dedicated account management. Integrated producers like those with Nordic pulp assets leverage this channel to control raw material flow from forest to finished product.
- Distributors:Regional wholesalers holding inventory for just-in-time delivery to mid-scale converters. EU Deforestation Regulation traceability mandates are forcing these intermediaries to reconfigure sourcing networks toward geolocated supply chains.
Transaction volume concentrates in direct sales; online channels are expanding most quickly as procurement digitization penetrates smaller converter accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic pulp forests anchor the coated wood free papers value chain, with integrated mills controlling raw material flow from timber stands to finished reels. German and French converters dominate premium packaging conversion, while Asian producers scale capacity for export-grade coated sheets.
Germany
Luxury cosmetics and spirits brands in the Rhine-Ruhr corridor are substituting plastic laminates with printable coated barriers to meet EU Green Deal circular economy targets. The EU Deforestation Regulation mandates geolocation traceability for all pulp fiber entering German-consumed coated papers. North Rhine-Westphalia mills with barge-accessible pulp terminals compress logistics costs through on-site coating infrastructure and integrated supply chains.
France
French packaging design studios specify FSC-certified coated papers with documented post-consumer waste streams to support premium positioning against plastic competitors. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy greaseproof chemistries from coating kitchens. Paris and Lyon-based converters pilot biopolymer-infused mineral coatings for Belgian chocolate and Scandinavian coffee brand applications.
Finland
Integrated Nordic pulp assets in Finnish forest regions control raw material flow from timber harvesting to bleached chemical pulp production. The EU Green Deal's deforestation-free supply chain requirements favor domestic fiber sourcing with verified chain-of-custody certification. Tampere and Kotka mill complexes leverage captive pulp supply to stabilize input costs against NBSK futures volatility.
China
Domestic fine paper mills lack barrier coating capacity, creating white space for technical partnerships with European equipment suppliers. The country's national environmental regulator enforces dual carbon goals that constrain expansion of fossil-intensive coating processes. Zhejiang and Shandong province producers focus on standard-grade coated sheets for commercial printing while importing premium barrier formulations.
United States
FDA food-contact substance regulations govern coated paper barriers migrating into direct packaging applications for quick-service restaurant chains. EPA scrutiny of fluorinated chemistries limits coating formulation flexibility for grease-resistant grades entering food-service distribution. Wisconsin and Maine paper mill clusters repurpose publishing-grade assets for shorter-run commercial printing and specialty packaging conversion.
Coated Wood Free Papers Market Competitive Landscape
Backward integration into captive pulp supply dominates the current landscape as converters seek insulation from hardwood fiber contract volatility. The vendor base splits between integrated forest products groups controlling timber-to-reel value chains and merchant market buyers exposed to NBSK pricing swings. Three archetypes define positioning: Nordic-integrated producers with forest assets, Asian-scale manufacturers with distribution breadth, and European specialists in barrier coating technology. M&A activity targets coating line assets in premium packaging corridors, while strategic partnerships transfer barrier formulation know-how to underpenetrated conversion markets.
Among Nordic-integrated producers, UPM Kymmene Corporation and Stora Enso Oyj exemplify the forest-to-mill archetype with captive pulp supply stabilizing raw material costs. Sappi Limited occupies a position within the specialized fine paper tier, anchoring competitive stance through publishing-grade expertise. Oji Holdings Corporation represents the Asian-scale model, leveraging extensive distribution networks to serve commercial printing markets across multiple geographies.
| Leading Market Players |
|---|
| UPM Kymmene Corporation |
| Nippon Paper Industries Co Ltd |
| Sappi Limited |
| Puyang Longfeng Paper Co., Ltd. |
| Oji Holdings Corporation |
| International Paper |
| Stora Enso Oyj |
| Neenah Paper |
| Lecta Group |
| Others |
Value Network & Pricing Analysis
EU Deforestation Regulation geolocation mandates are compelling converters to abandon spot-market fiber purchases, forcing supply chain reconfiguration toward certified chain-of-custody networks that elevate input costs and compress margins for non-integrated players.
Pricing Analysis
Service bundling separates mill-direct relationships from distributor transactions, with technical consultation and just-in-time delivery commanding premiums. Three-tier pricing structure across premium, standard, and economy levels tracks certification status and brightness specifications, with FSC-certified supply carrying 15-20 point gloss-unit tradeoffs accepted by sustainability-focused buyers. Cost compression in standard-tier coated sheets is intensifying because NBSK-indexed hardwood fiber contracts expose merchant converters to Scandinavian supply tightness. Small commercial printers exhibit highest price sensitivity through digital procurement platforms, while luxury cosmetics brands demonstrate lowest sensitivity for barrier-coated grades.
Supply Chain Analysis
Single-source vulnerability sits with Nordic hardwood fiber suppliers dominating bleached chemical pulp production for European coating lines. Manufacturing concentration centers on Finland, Germany, and Sweden, with captive pulp supply stabilizing input costs for integrated forest products groups. Raw material flows draw from Scandinavian timber stands, mineral coating additives, and biopolymer barrier formulations. Tariff exposure on imported barrier chemistries threatens formulation flexibility for food-contact grades. Distribution runs through barge-accessible Rhine-Ruhr terminals for integrated mills, regional wholesalers for mid-scale converters, and digital platforms for fragmented commercial printers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Deforestation Regulation creates a compliance moat favoring vertically integrated producers with documented chain-of-custody certification, raising capital barriers for spot-market dependent converters.
For Market Incumbents: Acquire coating line assets in premium packaging corridors to capture barrier-grade volume expansion. UPM Kymmene Corporation's Nordic pulp integration model demonstrates how captive fiber supply insulates against NBSK futures volatility. Defend margin position by retrofitting blade coaters to air-knife processes for mineral-polymer hybrid formulations serving Belgian chocolate and Scandinavian coffee brands. For New Entrants and Emerging Players: Specialty pharmaceutical converters seeking EU Falsified Medicines Directive-compliant serialization substrates represent an underserved buyer archetype with technical qualification requirements that deter commodity competition. Indian domestic fine paper mills lacking barrier coating capacity offer partnership entry points with European equipment suppliers. Target technical licensing arrangements over greenfield mill construction to compress capital intensity. For Investors and Strategic Acquirers: The window for entry favors integrated forest products groups with verified Scope 3 carbon accounting ahead of CSRD disclosure implementation. Mid-scale barrier coating specialists in German and French packaging corridors present acquisition targets with differentiated formulation know-how. Monitor EU Deforestation Regulation auditor capacity expansion as the signal indicating accelerated market access for compliant converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Assets | Captive Nordic fiber supply stabilizes input costs against NBSK futures volatility for integrated mills. |
| Barrier Coating Line Retrofit | Air-knife process conversion unlocks mineral-polymer hybrid formulations for Belgian chocolate packaging applications. |
| Geolocation Certification Investment | EU Deforestation Regulation compliance enables market access for German and French converter networks. |
| Technical Partnership with Equipment Suppliers | European coating technology transfer addresses capacity gaps in Indian domestic fine paper mills. |
| Carbon Accounting Integration | Verified Scope 3 data rewards vertically integrated groups under CSRD disclosure rules favoring forest-to-reel traceability. |
Research Methodology
Multi-period observation of pulp futures volatility, coating capacity utilization, and certification scheme adoption anchored the trend analysis, supplemented by interviews with mill operations directors, procurement leads at luxury packaging converters, coating formulation chemists, and commercial printing procurement officers. Secondary validation drew from EU Deforestation Regulation implementation timelines, REACH Annex XVII restriction updates, FSC chain-of-custody databases, and Nordic pulp export statistics. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators.
Input-output matrices mapped bleached chemical pulp flows through coating line configurations to end-use segments across the projection horizon. Segmentation dimensions modeled include product form, end-use application, quality tier, and distribution channel, with regional regulatory clusters capturing EU Green Deal, FDA food-contact, and dual carbon goal frameworks. CAGRs were derived from elasticity-adjusted demand projections incorporating substitution effects from digital publishing and plastic barrier displacement.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pulp futures volatility, auditor certification backlog resolution, and REACH chemical restriction expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Paper Machinery Market
Paper Products
Medical Grade Paper Market
Paper Products
Acrylic Paper Market
Paper Products
White Top Testliner Market
Paper Products
Printing and Writing Papers Market
Paper Products
Paper Products Market
Paper Products
Thermal Paper Market
Paper Products
North America Medium-Density Fiberboard Market
Paper Products
Veneer Sheets Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Sawn Wood Market
Paper Products
Global Wood Pulp Market
Paper Products
Pigmented Paper Market
Paper Products
Clay Coated Paper Market
Paper Products
Solid Bleached Board Market