
 Global Mobile Middleware Market | 2026-2036
Global Mobile Middleware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Middleware Market Foresight
Enterprise-grade API security certification is reorganizing procurement criteria across the Global Mobile Middleware Market. Microsoft Corporation leverages its Azure integration stack to anchor cloud-native middleware deployments in regulated industries. IBM Corporation sustains mainframe-to-mobile connectivity pipelines through specialized transaction processing modules. Oracle Corporation dominates database middleware licensing across large financial services accounts.
Mobile middleware comprises software infrastructure that mediates data exchange between mobile applications, enterprise backends, and third-party services through protocol translation, message queuing, and API management layers. The technology enables synchronous and asynchronous communication across heterogeneous operating systems, typically supporting REST, SOAP, MQTT, and AMQP protocols for real-time enterprise mobility. Cloud-based deployment models are capturing the fastest expansion as organizations retire on-premises integration servers. Event-driven middleware architectures are attracting premium pricing due to their role in IoT and real-time analytics pipelines. Object request broker segments retain steady demand within legacy manufacturing and government systems where CORBA-based infrastructure persists.
FDA 21 CFR Part 11 guidelines in the United States shape validation requirements for middleware handling electronic records in life sciences mobile applications. EMA's data integrity standards and the EU AI Act's risk classification framework compel European vendors to embed audit trails and algorithmic transparency into middleware platforms. India's BIS cloud security guidelines and RBI data localization mandates are redirecting deployment architectures toward hybrid models. Stakeholders must weigh sovereignty-compliant hosting against latency optimization as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Event-driven middleware architectures are compressing integration timelines as enterprises replace synchronous request-response patterns with asynchronous streaming pipelines for real-time mobile workloads.
Growth Catalysts
- EU AI Act risk classification:Financial services institutions in Germany and France are procuring middleware with embedded algorithmic audit trails to satisfy high-risk system documentation mandates.
- MQTT protocol adoption:Industrial IoT deployments across manufacturing floors are driving message broker upgrades that support lightweight publish-subscribe patterns for sensor-to-mobile data flows.
- RBI data localization:Indian banks and payment processors are deploying hybrid middleware stacks to route transaction data through domestic infrastructure while maintaining global API connectivity.
Market Restraints
- Specialized engineering talent scarcity:Deep expertise in CORBA-to-REST protocol bridging commands salary premiums that inflate implementation costs for legacy modernization projects.
- Cloud egress fee volatility:Hyperscaler data transfer pricing unpredictability distorts total cost of ownership calculations for multi-cloud middleware deployments.
- On-premises license inertia:Oracle and IBM database middleware incumbents leverage contractual renewal clauses that delay cloud migration timelines in enterprise accounts.
Strategic Opportunities
- Edge middleware nodes:5G MEC infrastructure rollouts in South Korea and Japan create demand for lightweight integration agents deployed at cellular base stations.
- ISO 27001 certification convergence:Unified information security management certification is streamlining vendor qualification processes across European healthcare and banking procurement.
- Embedded finance APIs:Non-financial mobile applications in retail and logistics are integrating payment and lending middleware layers that previously required banking charters.
Industry Challenges
- FDA 21 CFR Part 11 validation:Life sciences mobile applications require extensive electronic record audit trail documentation that extends middleware deployment cycles by quarters.
- Multi-protocol integration debt:Enterprises maintaining SOAP, REST, GraphQL, and gRPC endpoints simultaneously face exponential testing matrix complexity.
- API versioning governance:Consumer-facing mobile applications demand backward-compatible middleware interfaces that constrain architectural refactoring velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Middleware Market |
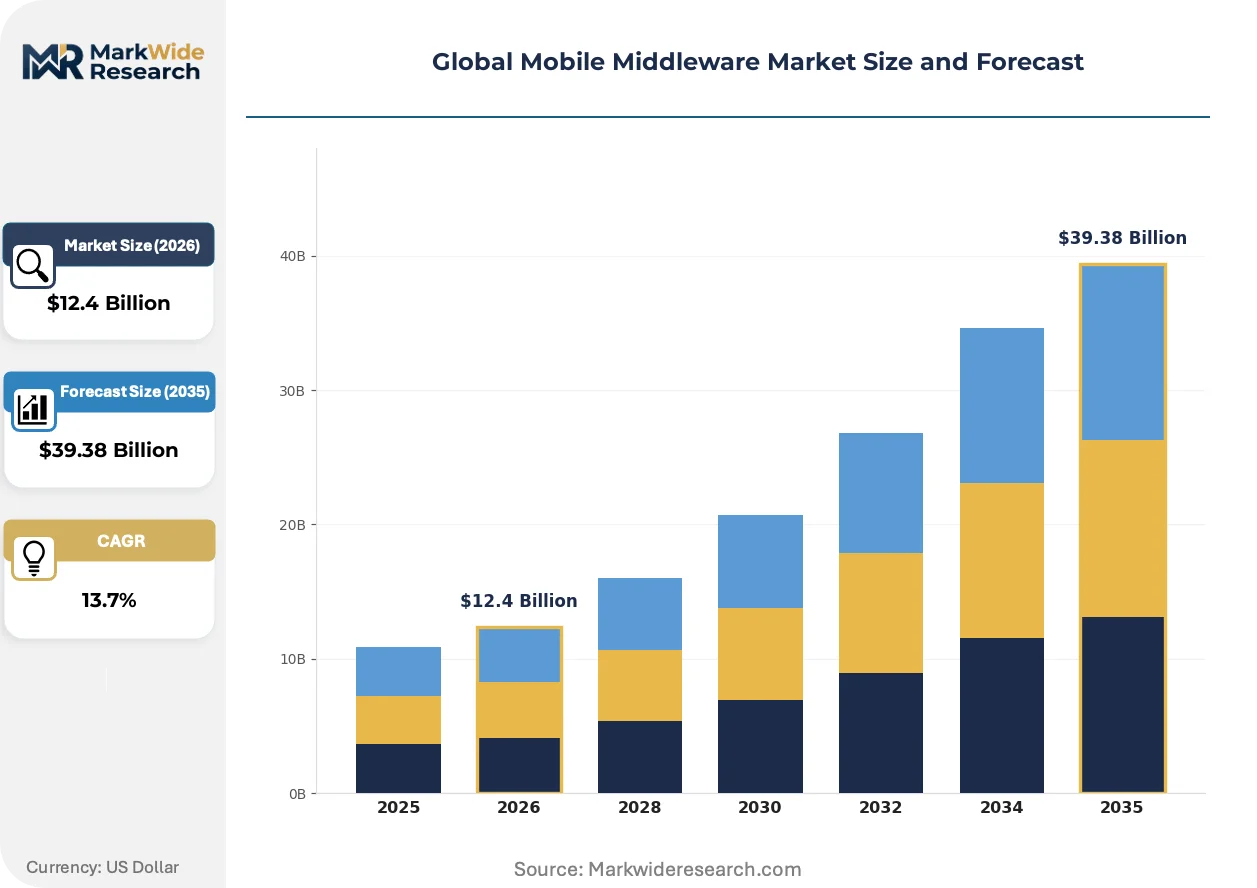
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $39.38 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Middleware Type: Message-Oriented, Object Request Broker, Database Middleware, Remote Procedure Call, Transaction Processing, Event-Driven Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services, Edge Computing Application: Enterprise Resource Planning, Customer Relationship Management, Supply Chain Management, Mobile Commerce, Real-Time Analytics, Social Networking End User Industry: Telecommunications, Financial Services, Manufacturing, Government, Education, Transportation |
| Companies Covered | Microsoft Corporation, Axway Inc., IBM Corporation, BlackBerry Limited, Adobe Inc., Oracle Corporation, TIBCO Software Inc., Red Hat Inc., SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Middleware Market Shifts & Advancements
Service mesh sidecar proxies are fragmenting the traditional middleware stack as platform engineering teams embed connectivity logic directly into Kubernetes application pods.
WebAssembly runtime modules are supplanting traditional Java-based middleware containers for edge deployment scenarios. Telecommunications operators deploying 5G network functions use Wasm binaries to execute integration logic with cold-start latencies under fifty milliseconds. This compression is enabling real-time middleware placement in base station hardware previously restricted to static configuration.
EMA data integrity standards and the EU AI Act's algorithmic transparency mandates are forcing middleware vendors to embed immutable audit logging at the message broker layer. Pharmaceutical manufacturers deploying mobile laboratory applications must now demonstrate complete data lineage from sensor capture through cloud storage. European vendors are responding with blockchain-anchored provenance modules that satisfy both regulatory frameworks.
Subscription-based API consumption is displacing perpetual license models for middleware infrastructure. Enterprise procurement teams in United States financial services now meter integration platform usage through consumption tiers rather than upfront capital commitments. This shift is most visible among mid-market fintechs that scale middleware spend directly with transaction volume rather than provisioned capacity.
Global Mobile Middleware Market Segmentation
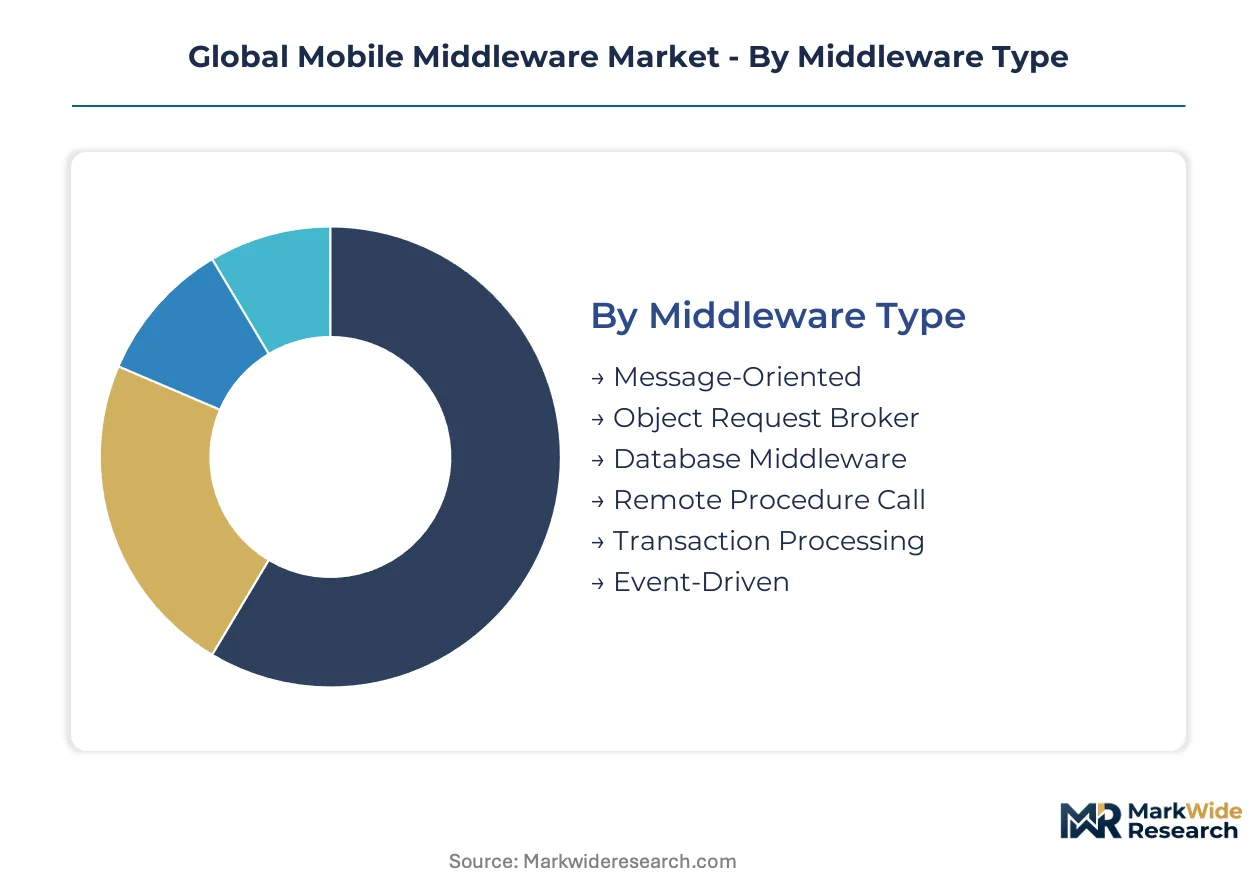
Mobile middleware segmentation reveals distinct procurement patterns across infrastructure types and deployment models. Financial services institutions in Germany and India drive premium pricing for compliance-heavy segments, while telecommunications operators in South Korea and Japan accelerate edge-native adoption.
Middleware Type:
Geographic demand splits sharply: message-oriented and event-driven segments serve export-led IoT pipelines from East Asian manufacturing hubs, while object request broker and database middleware remain concentrated in domestic legacy modernization projects across North American and European enterprises.
- Message-Oriented:Implements asynchronous queuing protocols including MQTT and AMQP for reliable sensor-to-mobile data transmission. Demand concentrates in Indian industrial automation corridors where RBI data localization mandates require domestic message broker hosting.
- Event-Driven:Streams real-time data through publish-subscribe architectures optimized for sub-100-millisecond latency. German automotive manufacturers deploy these systems for shop-floor-to-mobile analytics, driven by EU AI Act algorithmic transparency requirements.
- Object Request Broker:Bridges CORBA legacy systems to modern REST endpoints in government and defense installations.
- Database Middleware:Mediates heterogeneous data sources through connection pooling and query optimization layers.
- Remote Procedure Call:Enables synchronous client-server communication across distributed microservices architectures.
- Transaction Processing:Ensures ACID compliance for financial services mobile payment workflows.
Database middleware holds the largest share; momentum sits with event-driven architectures.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises licensing from consumption-metered cloud alternatives, with hybrid deployments commanding premium professional services margins.
- Cloud-Based:Delivers elastic integration platform capacity through containerized runtime environments. United States fintechs meter API consumption against transaction volumes, displacing perpetual license commitments.
- Hybrid:Orchestrates sensitive data processing through on-premises nodes while routing non-critical workloads to public cloud infrastructure. Indian banks deploy these architectures to satisfy RBI data localization without sacrificing global connectivity.
- On-Premises:Retains dedicated hardware integration servers for classified government and defense applications.
- Managed Services:Offloads middleware operations to third-party specialists under SLA-governed contracts.
- Edge Computing:Places lightweight integration agents at 5G base stations for ultra-low-latency mobile workloads.
Cloud-based deployment captures the steepest expansion trajectory; hybrid models retain the largest installed base among regulated industries.
Application:
Customer maturity varies: ERP and CRM integrations dominate established enterprise accounts, while real-time analytics and mobile commerce attract venture-funded growth-stage companies.
- Real-Time Analytics:Ingests streaming mobile telemetry through complex event processing engines for immediate operational intelligence. Japanese telecommunications operators deploy these pipelines for 5G network optimization, leveraging METI infrastructure investment programs.
- Mobile Commerce:Embeds payment authentication and inventory synchronization into consumer-facing retail applications. French luxury brands integrate these layers to comply with GDPR consent management and EMA data integrity standards.
- Enterprise Resource Planning:Synchronizes mobile field service data with centralized SAP and Oracle backend systems.
- Customer Relationship Management:Connects Salesforce and Microsoft Dynamics instances to mobile salesforce automation tools.
- Supply Chain Management:Tracks mobile-enabled logistics visibility from port to warehouse.
- Social Networking:Scales message broker clusters for viral content distribution and real-time notification delivery.
ERP integration holds the largest share; mobile commerce gains share fastest among mid-market retailers.
End User Industry:
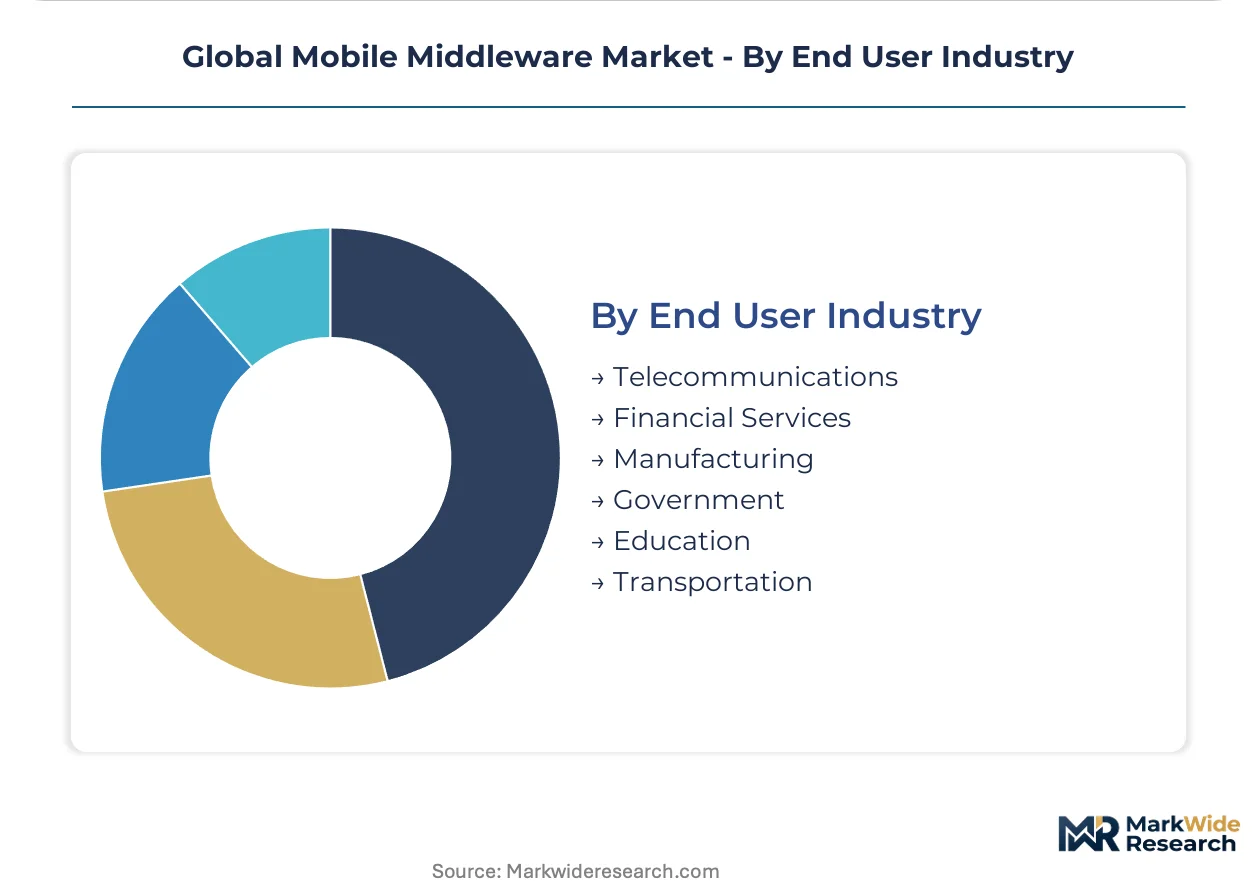
Supply concentration clusters in financial services and telecommunications, with government and education segments exhibiting elongated procurement cycles and price-sensitive RFP processes.
- Financial Services:Deploys middleware for real-time transaction settlement, fraud detection, and regulatory reporting across mobile banking channels. German institutions procure algorithmic audit trail capabilities to satisfy EU AI Act high-risk system documentation mandates.
- Telecommunications:Orchestrates 5G network functions and customer-facing service portals through containerized integration layers. South Korean operators lead edge middleware adoption through government-backed MEC infrastructure rollouts.
- Manufacturing:Connects industrial IoT sensors to mobile maintenance dashboards and quality control systems.
- Government:Maintains secure cross-agency data exchange through classified middleware gateways.
- Education:Integrates learning management systems with mobile campus applications.
- Transportation:Synchronizes fleet telemetry with mobile dispatch and route optimization platforms.
Financial services holds the largest share; telecommunications shows the strongest momentum from 5G infrastructure investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Middleware vendors concentrate engineering capacity in three regulatory jurisdictions where financial services and telecommunications procurement volumes intersect. United States hyperscalers, German automotive manufacturers, and Indian payment processors generate disproportionate demand for compliance-anchored integration infrastructure.
United States
FDA 21 CFR Part 11 validation requirements shape middleware procurement for life sciences mobile applications in Boston and San Francisco biotech corridors. Financial services institutions in New York and Chicago meter API consumption through consumption-based tiers rather than perpetual licenses. Cloud-native deployment dominates as enterprises retire on-premises integration servers.
Germany
EU AI Act high-risk system documentation mandates drive algorithmic audit trail procurement across Frankfurt and Munich banking centers. Automotive manufacturers in Stuttgart and Wolfsburg deploy event-driven middleware for shop-floor-to-mobile analytics pipelines. EMA data integrity standards compel pharmaceutical manufacturers to embed immutable logging at message broker layers.
India
RBI data localization requirements redirect deployment architectures toward hybrid models across Mumbai and Bangalore financial districts. BIS cloud security guidelines accelerate domestic message broker hosting for industrial automation corridors in Pune and Hyderabad. Payment processors route transaction data through domestic infrastructure while maintaining global API connectivity.
Japan
METI infrastructure investment programs fund 5G network optimization middleware deployment by Tokyo and Osaka telecommunications operators. Real-time analytics pipelines ingest streaming mobile telemetry for network performance management. Edge middleware nodes at cellular base stations enable ultra-low-latency mobile workloads.
South Korea
Government-backed MEC infrastructure rollouts create demand for lightweight integration agents at Seoul and Busan cellular base stations. Telecommunications operators lead edge-native middleware adoption through containerized runtime environments. Manufacturing automation in Gyeonggi Province drives MQTT protocol adoption for sensor-to-mobile data flows.
Global Mobile Middleware Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the middleware stack. The market exhibits tiered consolidation with hyperscale cloud providers anchoring premium segments while open-source specialists capture mid-market share. Three archetypes dominate: cloud-native platform vendors, legacy infrastructure incumbents with mainframe connectivity modules, and API management specialists. Competitive moves concentrate on strategic partnerships with telecommunications operators and portfolio diversification into edge computing nodes.
Within the cloud-native platform tier, Microsoft Corporation and Oracle Corporation exemplify divergent approaches to enterprise middleware deployment. Microsoft leverages its Azure integration stack to anchor regulated industry accounts, while Oracle dominates database middleware licensing across large financial services installations. IBM Corporation occupies a distinct position bridging mainframe-to-mobile connectivity through specialized transaction processing modules.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Axway Inc. |
| IBM Corporation |
| BlackBerry Limited |
| Adobe Inc. |
| Oracle Corporation |
| TIBCO Software Inc. |
| Red Hat Inc. |
| SAP SE |
| Others |
Supply & Pricing Matrix
Containerized runtime environments replacing perpetual license servers are redrawing supply geography toward hyperscaler regions while compressing pricing economics toward consumption-metered tiers. This substitution simultaneously concentrates vendor engineering capacity in United States, German, and Indian cloud corridors and erodes traditional on-premises margin structures.
Pricing Analysis
EU AI Act risk classification dictates the pricing tier structure across compliance-heavy middleware segments. Three-tier pricing structure across premium, standard, and economy levels separates algorithmic audit trail modules from basic API gateways and open-source alternatives. Price differentiation rests on ISO 27001 certification grade and embedded regulatory documentation capabilities. Cost compression in mid-market SaaS tiers is intensifying because hyperscaler marketplace listings commoditize baseline integration features. Government and defense buyers show least price sensitivity due to classified hosting mandates; mid-market fintechs exhibit highest sensitivity as they meter spend directly against transaction volumes.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native middleware procurement, though regulated Indian banks maintain strategic stockpiles of hybrid infrastructure for RBI data localization compliance. Engineering talent supply concentrates in United States, Germany, and India. Component dependencies include Kubernetes runtime environments, message broker clusters, and cryptographic hardware security modules. Single-source vulnerability runs through hyperscaler API gateway services. Distribution runs through direct enterprise sales teams and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile middleware constitutes a defensive-moat market where regulatory entrenchment creates formidable switching costs. EU AI Act documentation mandates and RBI data localization requirements embed incumbent platforms deeply into enterprise workflows.
For Market Incumbents: Shield installed base relationships through embedded algorithmic audit trail capabilities that satisfy EU AI Act high-risk system mandates. Deepen vertical integration into edge computing hardware partnerships with South Korean and Japanese telecommunications operators to capture 5G MEC infrastructure cycles. Counter open-source message broker substitution by layering proprietary compliance modules atop standardized protocols.
For New Entrants and Emerging Players: API versioning governance gaps in legacy incumbent platforms present service-layer entry points for developer-experience-focused challengers. Target mid-market Indian fintechs underserved by Oracle and IBM database middleware incumbents with consumption-metered hybrid deployment models. Pursue go-to-market angles through ISO 27001 certification bundling that accelerates European healthcare procurement qualification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed API management specialists holding stagnant on-premises revenue streams. Long-term viability hinges on cloud-native architecture migration velocity and edge computing capability integration. Acquisition target archetypes include event-driven middleware vendors with automotive manufacturing penetration. Watch MQTT protocol standardization momentum as inflection indicator for industrial IoT segment consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure stack anchors regulated financial services accounts through embedded compliance modules. |
| Edge Computing Expansion | 5G MEC infrastructure partnerships with South Korean operators create ultra-low-latency deployment channels. |
| Regulatory Certification Investment | EU AI Act algorithmic transparency capabilities differentiate premium tiers in German banking procurement. |
| Strategic Partnership | Telecommunications operator alliances in Japan leverage METI infrastructure programs for network optimization middleware. |
| Acquisition of Specialist Firm | CORBA-to-REST bridging expertise commands scarcity premiums in North American government modernization projects. |
Research Methodology
A standing panel of enterprise architects, platform engineering directors, regulatory compliance officers, and cloud procurement leads provided ongoing calibration across the study period. Primary interviews with middleware vendor product managers and systems integrator deployment specialists combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents. Bottom-up deployment volume estimates triangulated against top-down enterprise IT spend allocations across financial services, telecommunications, and manufacturing verticals.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. Segmentation dimensions modeled include middleware type, deployment architecture, application use case, and end-user industry vertical alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves incorporating enterprise mobility adoption rates, 5G infrastructure investment cycles, and compliance mandate implementation timelines. Industry-specific inputs encompassed RBI data localization enforcement patterns and FDA 21 CFR Part 11 validation requirement diffusion.
Underlying assumptions cover sustained hyperscaler marketplace growth, regulatory fragmentation persistence, and edge computing infrastructure deployment velocity, with deviation risk concentrated in cloud egress fee volatility and specialized engineering talent availability. Revision becomes warranted when EU AI Act enforcement intensity or RBI localization mandate scope crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Generative Design Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Global Software Quality Assurance Market
Software & Services
Global Landscape Software Market
Software & Services
Equipment Management Software Market
Software & Services
Global Equity Management Software Market
Software & Services
HR Tech Market
Software & Services
BFSI Software Market
Software & Services
Document Capture Software Market
Software & Services
CAD Modeling Software Market
Software & Services
UK Point of Sale Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
IT Service Management Tools Market
Software & Services
Plant Design Software Market