
 Mobile Analytics Market | 2026-2036
Mobile Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Analytics Market Analysis
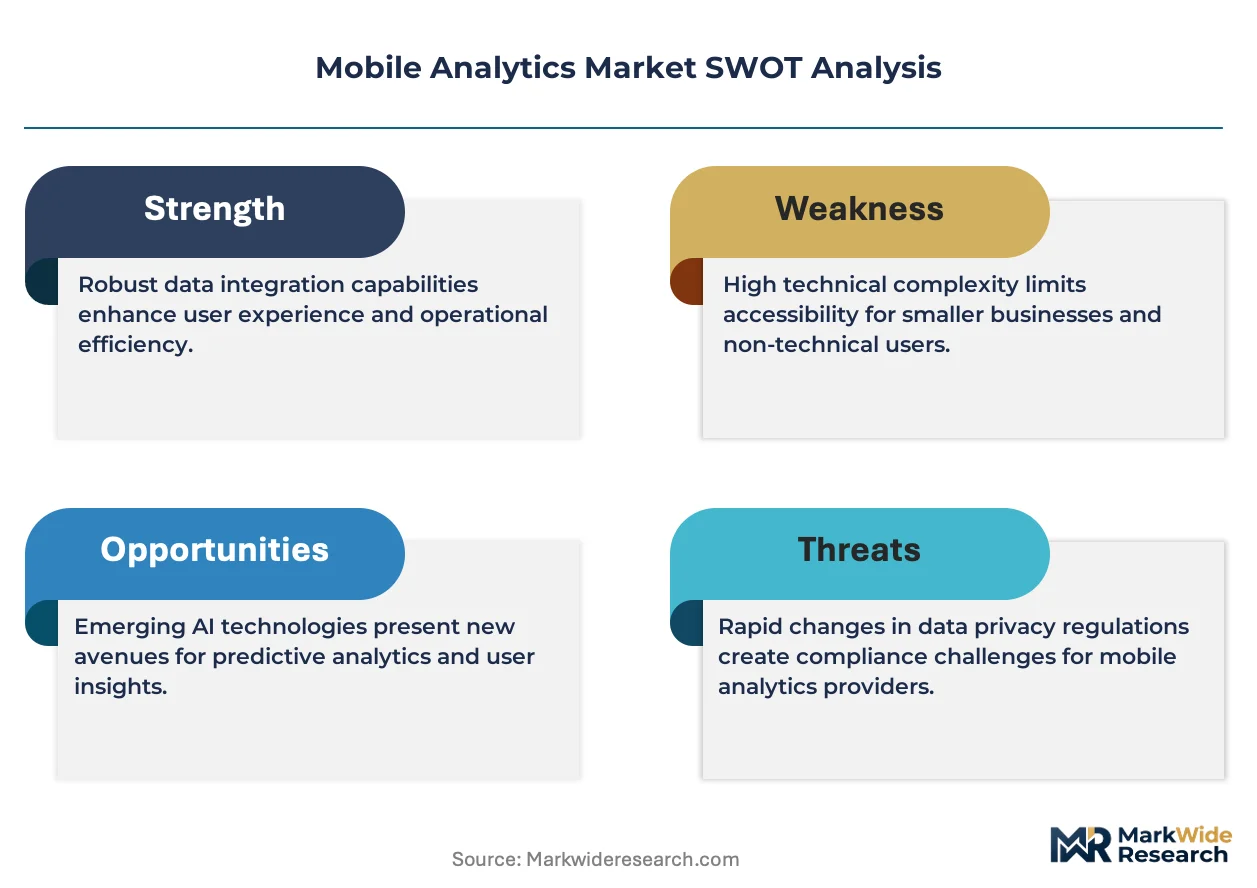
GDPR enforcement is rebalancing the cost-of-entry calculus for mobile analytics vendors serving European users. Google leverages its first-party data infrastructure to sustain measurement capabilities without third-party identifiers. Adobe competes through specialized privacy-preserving attribution tools that navigate fragmented consent requirements. Amplitude anchors its growth in product analytics depth rather than broad advertising measurement.
Mobile analytics encompasses the collection, processing, and visualization of user behavior data from smartphone and tablet applications, typically ingesting event streams at millisecond latency to generate cohort retention curves, funnel conversion metrics, and predictive churn scores. Cloud-based deployment leads structural investment due to elastic compute scaling for seasonal app traffic spikes, while real-time technology commands premium positioning as finance and gaming sectors demand sub-second decision latency. On-premise alternatives occupy niche demand among government end users with sovereign data requirements.
The EU AI Act, FDA guidance on software-as-medical-device, and India's DPDP Bill collectively reshape product standards for cross-border data processing and algorithmic transparency. The EU AI Act specifically imposes conformity assessments on analytics engines that profile users for credit or health decisions. Stakeholders must monitor regulatory divergence between Brussels and New Delhi to determine whether unified platform architectures or region-specific instances deliver superior compliance economics.
Market Dynamics
Behavioral data monetization faces structural recalibration as privacy-preserving computation and sovereign data mandates fragment previously unified measurement architectures. The EU AI Act's risk-tiered conformity requirements impose divergent compliance burdens on predictive analytics engines versus descriptive dashboards.
Growth Catalysts
- EU AI Act deployment obligations:High-risk analytics systems for credit and health profiling trigger mandatory conformity assessments, creating certified vendor demand from regulated financial and healthcare app publishers.
- Edge computing latency requirements:Gaming and fintech applications drive sub-50 millisecond event processing at the device level, expanding hardware-software integrated analytics stacks.
- India's DPDP Bill consent frameworks:Digital-native enterprises in Bengaluru and Mumbai scale first-party data infrastructure to meet granular purpose-limitation mandates.
Market Restraints
- Identifier deprecation cost structure:Apple's ATT framework and Google's Privacy Sandbox eliminate deterministic attribution, forcing probabilistic modeling investments that inflate customer acquisition cost baselines by 15-40 percent for performance marketers.
- Cloud concentration risk:AWS, Azure, and Google Cloud dominate elastic compute for seasonal traffic spikes, creating vendor lock-in and egress cost volatility for mid-tier analytics platforms.
- Cross-border data localization:Russia's data residency law and China's PIPL fragment unified data lakes, requiring redundant infrastructure deployment that compresses vendor margins.
Strategic Opportunities
- On-device federated learning:Differential privacy techniques enable model training without raw data centralization, opening regulated healthcare and government segments previously blocked by sovereign data requirements.
- Indonesia's digital economy acceleration:Southeast Asia's largest mobile-first population lacks mature analytics infrastructure, creating greenfield deployment opportunities for cloud-native behavioral analytics suites.
- Real-time decisioning convergence:Streaming analytics platforms integrate with MLOps pipelines to enable sub-second personalization in sports betting and buy-now-pay-later credit decisions.
Industry Challenges
- Differential privacy engineering scarcity:Mathematicians capable of implementing formal privacy guarantees remain concentrated at academic institutions and large technology employers, constraining mid-market vendor capability builds.
- Legacy SDK integration friction:Enterprise applications running decade-old Objective-C and Java codebases require bridging layers to modern event streaming architectures, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Analytics Market |
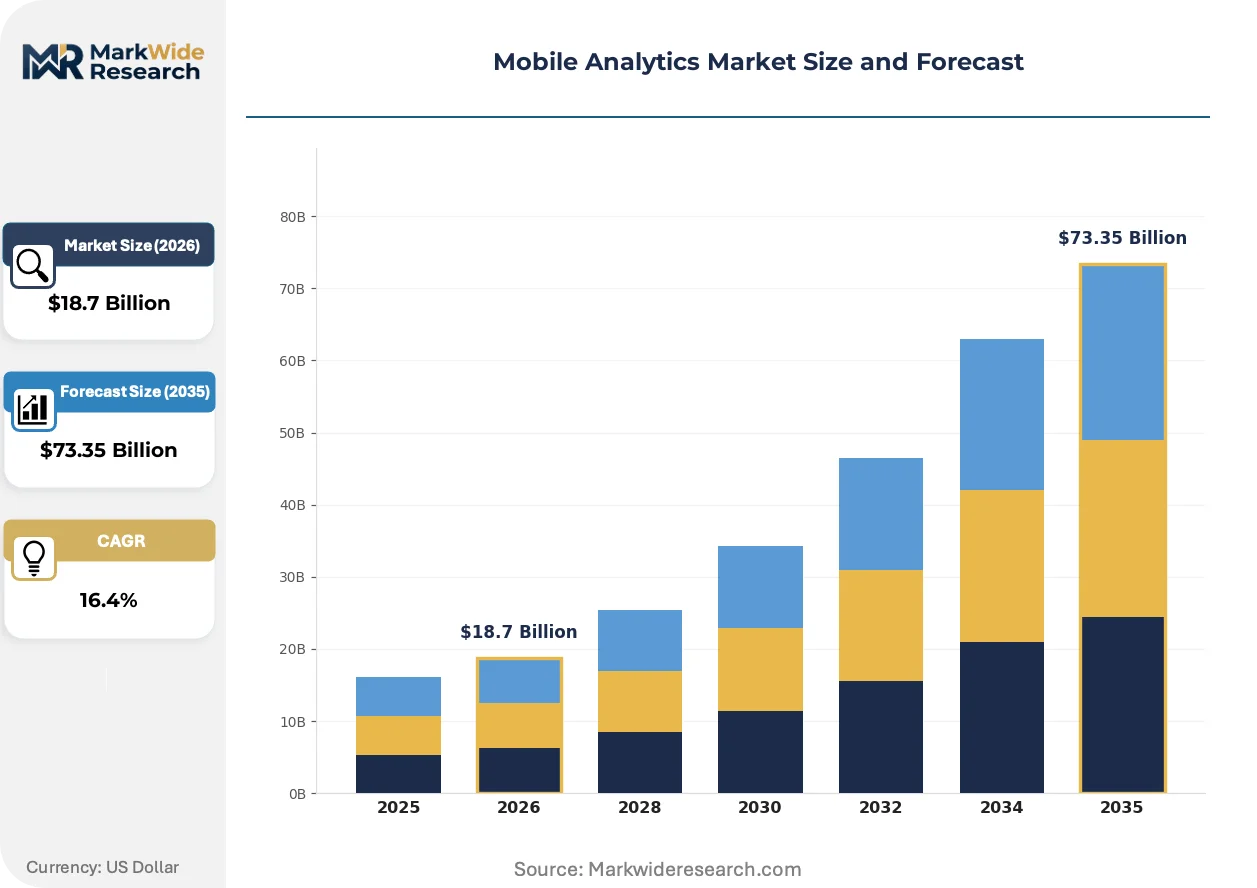
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Retail, Healthcare, Finance, Gaming Technology: Cloud-Based, On-Premise, Hybrid, Real-Time End User: Small Business, Medium Business, Large Enterprise, Government Deployment: Public Cloud, Private Cloud, Multi-Cloud, Edge Computing |
| Companies Covered | Google, Adobe, Amplitude, AppsFlyer, Amazon Web Services, Mixpanel, Meta Platforms, Microsoft, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Analytics Market Emerging Trajectories
Real-time stream processing architectures are displacing batch-oriented data pipelines as finance and gaming applications demand millisecond-latency behavioral signals. This infrastructure shift reconfigures vendor competitive advantage toward operational excellence in elastic scaling rather than static feature depth.
Edge-deployed analytics engines are expanding into mobile devices through on-chip neural processing units that execute inference without network round-trips. Gaming studios in Helsinki and Stockholm adopt these capabilities for cheat detection and dynamic difficulty adjustment. The technology is expanding into privacy-sensitive health applications where raw biometric data never leaves the device.
GDPR enforcement actions by CNIL, ICO, and Hamburg DPA are compressing permissible data retention windows for pseudonymous identifiers. Analytics vendors must implement automated deletion orchestration and purpose-limitation audit trails. Retail and travel app publishers face the steepest operational adaptation as they rely on extended lookback windows for seasonality modeling.
Subscription-based analytics procurement is displacing seat-based licensing as product teams scale headcount faster than per-analyst tool adoption. Mid-market SaaS vendors in Berlin and Singapore now bundle unlimited user access with event volume tiers. This model compresses sales cycles but requires vendors to engineer multi-tenant architectures that isolate query performance across customer density.
Mobile Analytics Market Segmentation
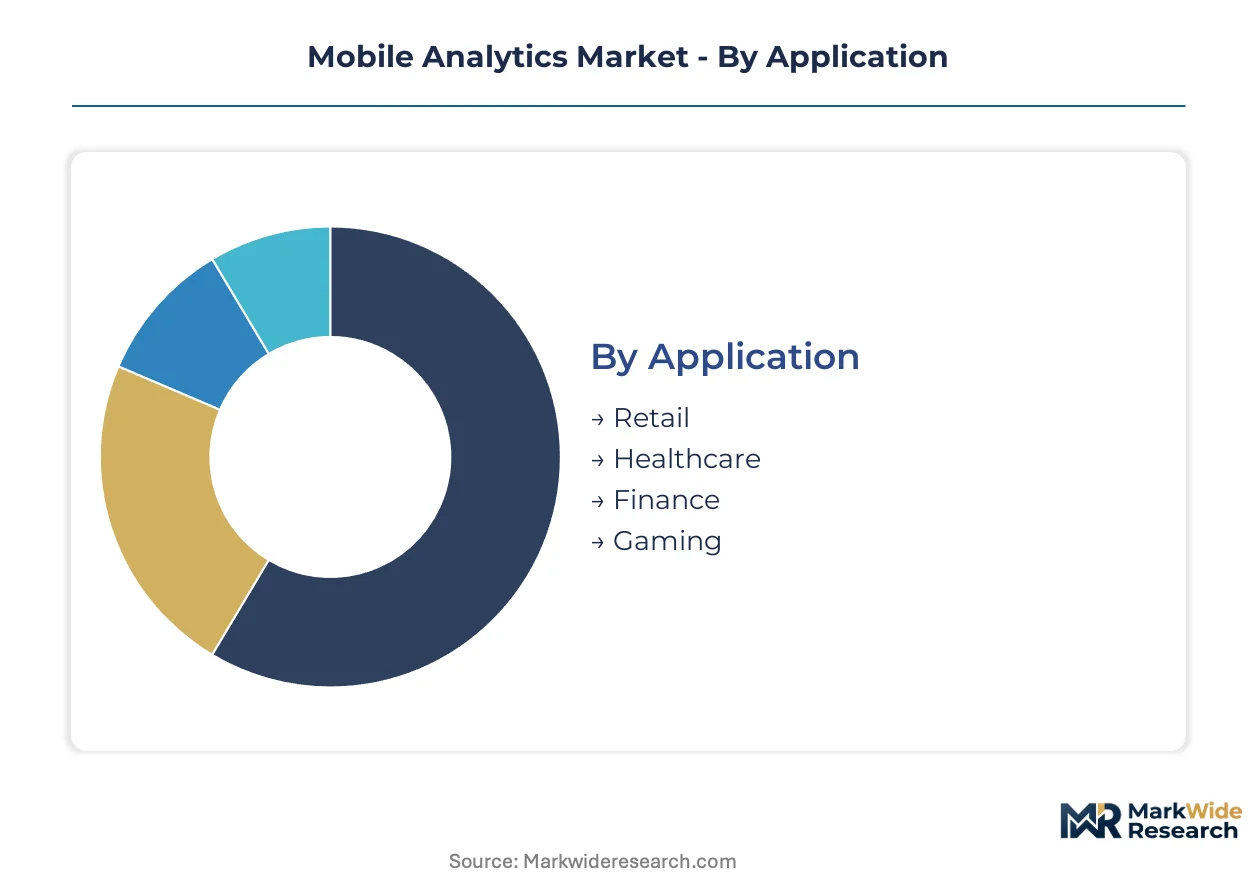
Mobile analytics procurement hinges on latency requirements, data sovereignty mandates, and elastic scaling needs. Buyers weight cloud concentration risk against edge computing premiums. The report dissects four structural dimensions shaping vendor selection and platform architecture decisions.
Application:
Retail buyers prioritize real-time personalization engines; healthcare procurement emphasizes HIPAA and FDA software-as-medical-device compliance.
- Retail:Behavioral analytics suites track cohort retention curves and funnel conversion metrics across seasonal traffic spikes. App publishers in India deploy first-party data infrastructure to navigate purpose-limitation mandates under the DPDP Bill. This segment leads on scale.
- Healthcare:Predictive churn scores and patient engagement platforms trigger EU AI Act conformity assessments for high-risk profiling systems. Edge-deployed engines with on-chip neural processing units execute inference without network round-trips, keeping biometric data on-device. This segment leads on momentum.
- Finance:Sub-50 millisecond event processing enables real-time credit decisions and fraud detection in buy-now-pay-later applications.
- Gaming:Dynamic difficulty adjustment and cheat detection drive hardware-software integrated analytics stacks in Helsinki and Stockholm studios.
Retail anchors current revenue concentration; healthcare climbs the fastest on regulatory tailwinds.
Technology:
Cost tier determines architecture selection, with real-time commanding premium positioning against batch-oriented alternatives.
- Cloud-Based:Elastic compute scaling accommodates seasonal app traffic spikes through AWS, Azure, and Google Cloud infrastructure. Mid-tier platforms face vendor lock-in and egress cost volatility. This segment leads on scale.
- Real-Time:Millisecond-latency event streams displace batch pipelines in sports betting and algorithmic trading applications. Finance and gaming sectors demand sub-second decision latency. This segment leads on momentum.
- On-Premise:Sovereign data requirements from government end users in Russia and China mandate localized infrastructure outside hyperscaler control.
- Hybrid:Bridging layers connect legacy Objective-C and Java codebases to modern event streaming architectures, extending implementation timelines for decade-old enterprise applications.
Cloud-based deployment captures the broadest installed base; real-time analytics gains share fastest on latency-sensitive use case expansion.
End User:
Customer type shapes pricing model preference, with subscription-based procurement displacing seat-based licensing among scaling product teams.
- Large Enterprise:Multi-tenant architectures isolate query performance across customer density while bundling unlimited user access with event volume tiers. Berlin and Singapore SaaS vendors compress sales cycles through this model. This segment leads on scale.
- Small Business:Self-serve onboarding and pre-built dashboard templates reduce implementation friction for teams lacking dedicated data engineering resources. This segment leads on momentum.
- Medium Business:Purpose-built connectors to Shopify, Salesforce, and Segment accelerate time-to-value without custom SDK development.
- Government:Automated deletion orchestration and purpose-limitation audit trails satisfy CNIL, ICO, and Hamburg DPA enforcement actions compressing data retention windows.
Large enterprise dominates current spending; small business expands most quickly on democratized tooling availability.
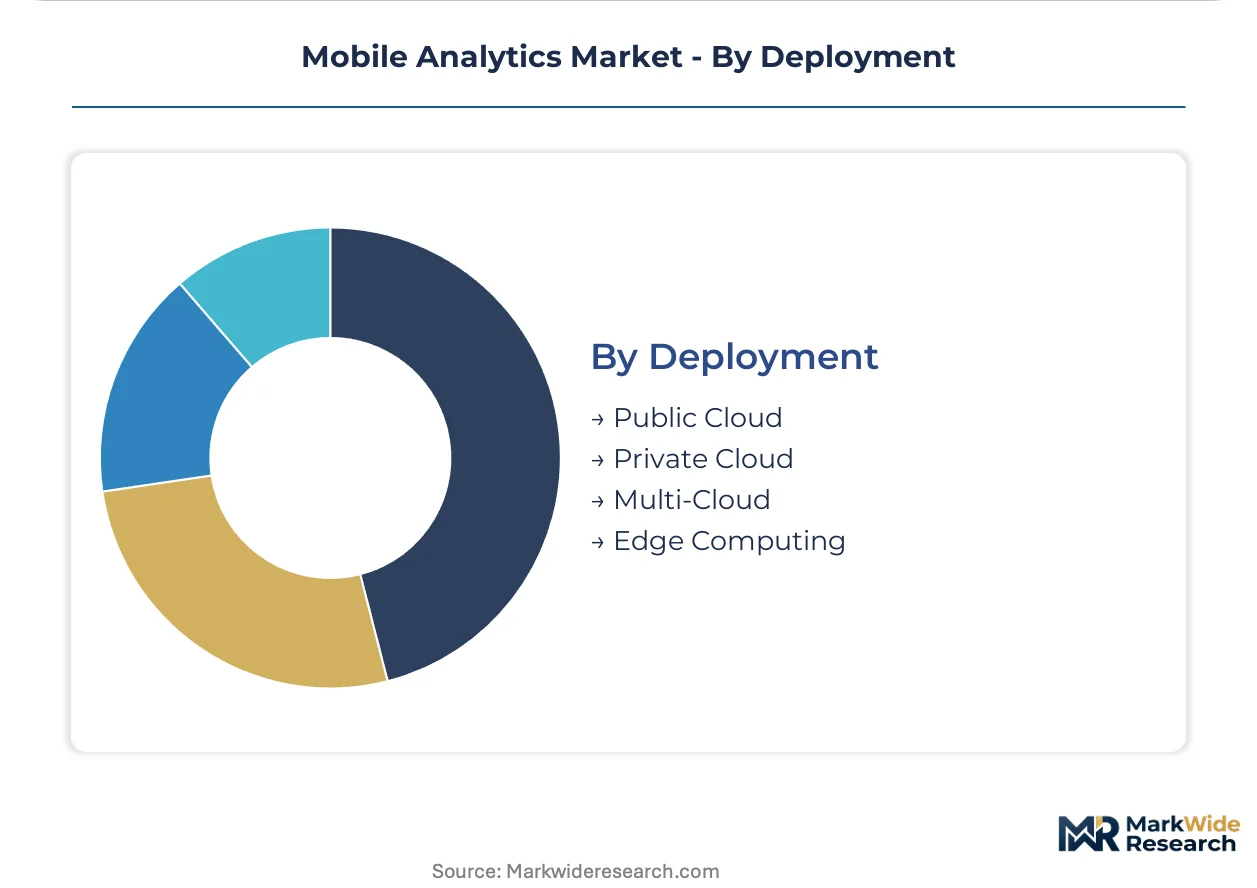
Deployment:
Volume concentration and margin structure vary sharply across infrastructure topology choices.
- Public Cloud:Shared infrastructure delivers lowest unit economics for variable workloads, though cross-border data localization fragments unified data lakes. This segment leads on scale.
- Edge Computing:On-device federated learning enables model training without raw data centralization, opening regulated segments previously blocked by sovereign data requirements. This segment leads on momentum.
- Private Cloud:Single-tenant isolation addresses financial services compliance mandates for audit trail completeness and access control granularity.
- Multi-Cloud:Redundant deployment across AWS and Azure mitigages concentration risk, though operational complexity inflates platform engineering headcount requirements.
Public cloud maintains the deepest installed base; edge computing shows the steepest expansion trajectory on privacy-preserving computation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data engineering talent clusters in Bengaluru, Berlin, and the San Francisco Bay Area anchor regional platform development. Cloud infrastructure density and regulatory stringency shape where vendors localize analytics stacks. Sovereign data mandates fragment previously unified architectures into jurisdiction-specific instances.
United States
Retail app publishers in New York and Los Angeles deploy real-time personalization engines at scale. FDA guidance on software-as-medical-device triggers compliance investments for healthcare analytics vendors. The San Francisco Bay Area concentrates venture-backed analytics startups building privacy-preserving attribution tools.
Germany
Automotive OEMs in Munich and Stuttgart integrate mobile behavioral data into connected vehicle platforms. GDPR enforcement by Hamburg DPA compresses data retention windows for pseudonymous identifiers. Berlin hosts mid-market SaaS vendors bundling unlimited user access with event volume tiers.
India
Digital-native enterprises in Bengaluru and Mumbai scale first-party data infrastructure under DPDP Bill consent frameworks. RBI oversight of fintech credit decisions imposes audit trail requirements on predictive analytics engines. Hyderabad's cloud engineering talent supports multi-tenant architecture development for subscription-based procurement models.
United Kingdom
Fintech applications in London demand sub-50 millisecond event processing for real-time credit decisions. ICO enforcement actions mandate automated deletion orchestration for behavioral data retention. Manchester and Edinburgh host gaming studios adopting edge-deployed analytics for cheat detection.
Singapore
Southeast Asian headquarters for global analytics vendors serve Indonesia's greenfield mobile-first population. The country's data protection authority shapes cross-border processing standards for regional deployments. Fintech clusters in Marina Bay integrate streaming analytics with MLOps pipelines for buy-now-pay-later platforms.
Mobile Analytics Market Vendor Landscape
The competitive structure tilts toward hyperscaler-backed platforms with first-party data infrastructure. Cloud concentration creates tiered vendor stratification between elastic compute providers and specialized analytics suites. Three archetypes dominate: infrastructure-integrated suites, privacy-preserving attribution specialists, and product analytics depth players. Strategic moves center on federated learning capability builds and edge computing partnerships.
Within the infrastructure-integrated tier, Google and Amazon Web Services anchor positions through elastic compute scaling and first-party measurement continuity. Adobe occupies a specialized privacy-preserving attribution position navigating fragmented consent requirements across European jurisdictions. Amplitude exemplifies the product analytics depth archetype, anchoring growth in cohort retention and funnel conversion tooling rather than broad advertising measurement.
| Leading Market Players |
|---|
| Adobe |
| Amplitude |
| AppsFlyer |
| Amazon Web Services |
| Mixpanel |
| Meta Platforms |
| Microsoft |
| Oracle |
| Others |
Supply Flow & Price Mechanics
Venture-backed analytics specialists rolled up through private-equity platforms anchor supply-side discipline through multi-tenant infrastructure consolidation, while subscription bundling compresses price transparency across event-volume tiers. This ownership pattern concentrates pricing power with hyperscaler-backed incumbents who amortize elastic compute investments across seasonal traffic spikes.
Pricing Analysis
Bundled subscription tiers displace unbundled per-seat licensing as the dominant structure, with unlimited user access packaged against event-volume thresholds. Price differentiation centers on real-time latency guarantees and edge-computing hardware integration, with premium tiers commanding positioning for sub-50 millisecond processing. Pricing pressure intensifies in the mid-market segment as identifier deprecation inflates probabilistic modeling costs for performance marketers. Small business buyers exhibit highest price sensitivity, while large enterprises prioritize query-performance isolation over per-unit cost.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate vendor participation in financial services and healthcare procurement, filtering mid-tier platforms from regulated segments. Cloud infrastructure concentrates in the United States, Ireland, and Singapore, with neural processing unit fabrication anchored in Taiwan and South Korea. Raw material dependencies span silicon wafers, specialized memory modules, and hyperscaler egress bandwidth. Single-source vulnerability in NPU supply chains threatens edge-computing rollout timelines. Distribution runs through direct enterprise sales teams and self-serve product-led growth channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where engineering talent cost differentials between Bengaluru and San Francisco Bay Area clusters enable margin expansion for vendors with distributed development footprints.
For Market Incumbents: Extend federated learning capabilities to capture healthcare and government segments blocked by sovereign data mandates. Defend against privacy-preserving attribution specialists through first-party data infrastructure investments. Deepen vertical integration into edge-computing hardware partnerships to secure sub-50 millisecond latency guarantees for gaming and fintech buyers. For New Entrants and Emerging Players: Enter via Indonesia's greenfield mobile-first population, where mature analytics infrastructure remains underdeveloped. Target digital-native enterprises in Jakarta and Surabaya with cloud-native behavioral analytics suites. Pursue partnership-led go-to-market strategies with regional system integrators familiar with DPDP Bill compliance requirements. For Investors and Strategic Acquirers: Hyperscaler cloud divisions are the most active acquirer in this space, seeking product analytics depth to complement infrastructure offerings. The five-to-ten-year viability window favors platforms with demonstrated multi-tenant architecture scale. Acquisition targets should demonstrate automated deletion orchestration and purpose-limitation audit trail capabilities. Watch for EU AI Act conformity assessment bottlenecks as inflection indicators for certified vendor demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Adobe's privacy-preserving attribution tools navigate fragmented GDPR consent requirements across European jurisdictions. |
| Edge Computing Partnership | Gaming studios in Helsinki deploy on-chip neural processing units for cheat detection without network round-trips. |
| Geographic Expansion | Mid-market SaaS vendors in Berlin bundle unlimited user access to compress sales cycles under subscription models. |
| Acquisition of Specialist Firm | Amplitude's product analytics depth anchors growth in cohort retention tooling rather than advertising measurement. |
| Strategic Partnership | Google leverages first-party data infrastructure to sustain measurement capabilities without third-party identifiers. |
Methodological Framework
Direct dialogue with mobile app publishers, data engineering leads, privacy officers, and cloud procurement managers grounded qualitative findings in operational reality. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie usage data, and EU AI Act implementation guidance. Bottom-up event-volume modeling triangulated against top-down addressable market sizing from cloud infrastructure spend patterns.
Segment-level outputs across deployment topology, application vertical, organization size, and regional regulatory cluster fed into consolidated projections. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure investment trajectories. Model inputs incorporated DPDP Bill consent-framework implementation timelines and FDA software-as-medical-device guidance evolution.
Inputs from cloud vendor transparency reports and national data protection authority enforcement databases were available through the study window; gaps in real-time edge-computing deployment metrics introduce uncertainty bands around latency-sensitive segment forecasts. A model refresh is warranted upon material change in EU AI Act conformity assessment processing timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Enterprise Performance Management Market
Analytics
Embedded Analytics Market
Analytics
Global Operational Analytics Market
Analytics
Procurement Analytics Market
Analytics
Tourism Industry Big Data Analytics Market
Analytics
Content Analytics and Search Software Market
Analytics
Iraq ICT Market
Analytics
Emotion Analytics Market
Analytics
Learning Analytics Solution Market
Analytics
UAE Geospatial Analytics Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Active Data Warehousing Market
Analytics
Retail Analytics Market
Analytics
APAC Data Wrangling Market