
 Middleware Market | 2026-2036
Middleware Market Size, Share, and Industry Trends Forecast 2026-2036
Middleware Market Analysis
Financial services is shifting toward event-driven architectures for real-time transaction processing, pulling middleware spend away from legacy batch-oriented deployments. IBM sustains dominance in mainframe connectivity layers that bridge core banking systems to modern APIs. Oracle competes through database middleware that anchors enterprise data fabric strategies across hybrid estates. Fujitsu specializes in integration frameworks for telecommunications operators managing 5G network slicing orchestration.
Middleware constitutes software that sits between operating systems and applications, enabling communication, data management, and distributed computing across heterogeneous systems through protocols such as message queuing, remote procedure calls, and transaction processing monitors. Its primary industrial purpose is to abstract infrastructure complexity so developers can build scalable, interoperable applications without managing low-level network or hardware interfaces. Application server middleware leads in revenue contribution due to entrenched enterprise Java deployments, while microservices solutions represent the fastest-expanding segment as organizations decompose monolithic codebases. Cloud-based deployment is capturing margin pools from on-premises installations, though hybrid configurations persist in regulated industries requiring data residency controls.
The EU AI Act and GDPR impose algorithmic transparency and data localization requirements that reshape how middleware vendors architect cross-border data flows, particularly for BFSI and healthcare end users. The US Federal Trade Commission and Securities and Exchange Commission scrutinize API security and audit trails in financial middleware, elevating compliance costs for vendors serving American banks. Stakeholders must monitor whether sovereign cloud mandates fragment middleware standards or create openings for region-specific integration platforms.
Market Dynamics
The Middleware Market faces structural compression from cloud-native container orchestration, which is fragmenting traditional application server revenue pools as enterprises decompose monolithic workloads into microservices architectures. This shift forces incumbent vendors to recast licensing models around consumption-based pricing while defending installed bases in regulated sectors.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements in financial services are accelerating middleware replacement cycles for audit-ready integration layers.
- 5G network slicing orchestration:Telecommunications operators are deploying event-driven middleware to manage latency-sensitive service partitions across distributed radio access networks.
- German industrial automation clusters:High-throughput integration demand from automotive and precision manufacturing hubs is concentrating procurement in specialized application server frameworks.
Market Restraints
- Cloud hyperscaler bundling:Native integration services from AWS, Azure, and GCP are commoditizing standalone middleware in price-sensitive enterprise accounts.
- Open-source substitution:Apache Kafka, Istio, and Kubernetes ecosystems are capturing developer mindshare from commercial message queuing and service mesh offerings.
- GDPR cross-border friction:Data localization requirements are fragmenting middleware architectures and inflating operational complexity for multi-tenant deployments.
Strategic Opportunities
- Edge computing convergence:Latency-critical IoT and autonomous systems are creating demand for lightweight middleware runtimes deployed at network peripheries.
- Healthcare data fabric expansion:HIPAA-compliant interoperability layers for electronic health record integration remain underpenetrated relative to financial services adoption curves.
- India PLI scheme spillover:Manufacturing incentives are attracting industrial automation investments that require localized middleware for equipment connectivity.
Industry Challenges
- Legacy mainframe integration complexity:COBOL-era systems in core banking require specialized bridging expertise that commands premium labor costs and extends project timelines.
- API security certification backlog:SOC 2 and ISO 27001 audit queues are delaying go-live dates for middleware vendors serving US financial institutions under SEC scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middleware Market |
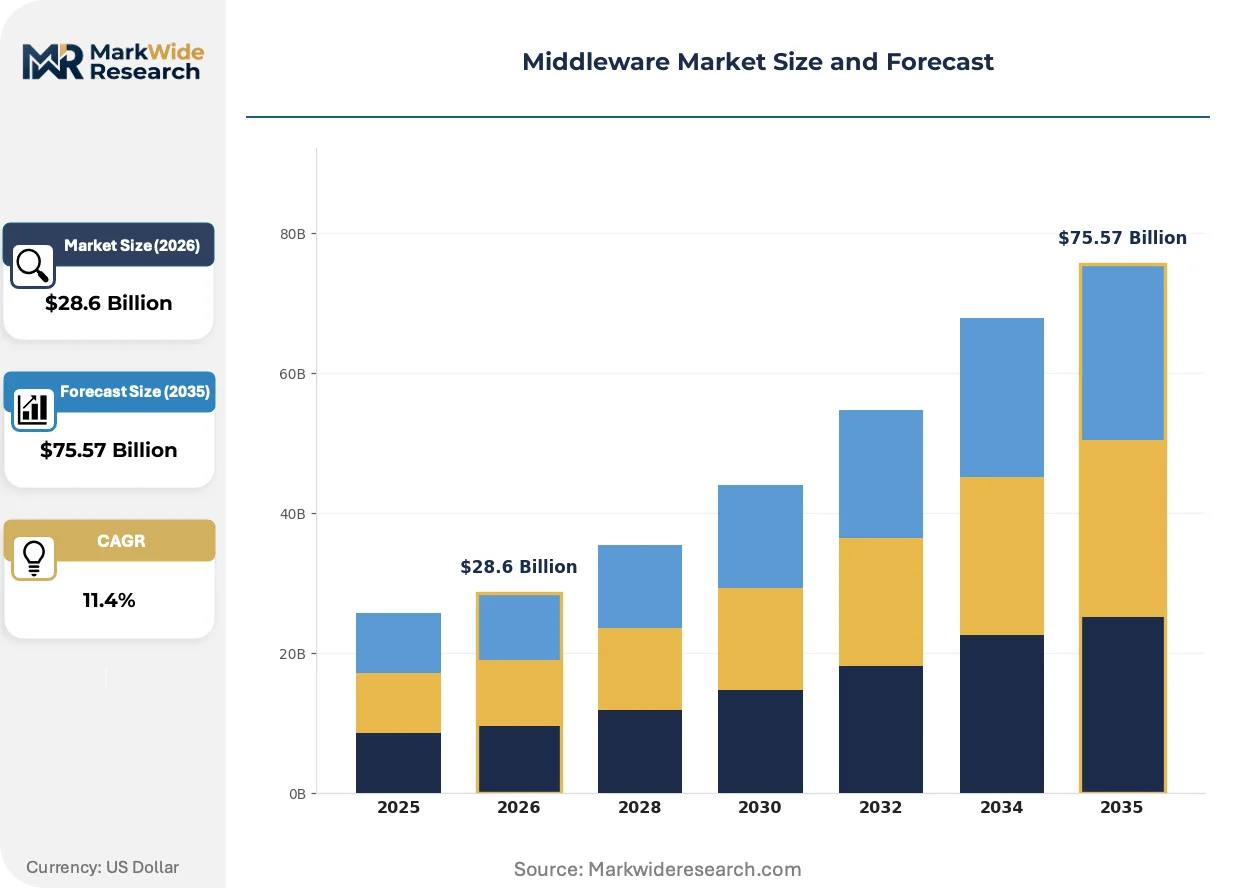
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Message Oriented Middleware, Database Middleware, Application Server, Web Middleware Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Healthcare, Retail, BFSI, Telecommunications Solution: Integration Solutions, API Management, Business Process Management, Microservices |
| Companies Covered | Amazon Web Services, Software AG, IBM, SAP SE, TIBCO Software, Oracle, Google Cloud, Fujitsu, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middleware Market Emerging Trajectories
Event-driven architecture is displacing request-response patterns across enterprise integration stacks, compressing transaction latency from seconds to milliseconds while expanding the addressable market for stream-processing middleware. This architectural pivot rewards vendors with native Kafka compatibility and cloud-agnostic deployment options.
Service mesh technology is converging with zero-trust security frameworks to enable fine-grained policy enforcement across microservices communications. Financial services firms in Singapore and Switzerland are piloting these converged stacks for real-time payment orchestration. The structural consequence is collapsing the boundary between networking infrastructure and application middleware, forcing traditional vendors to acquire or partner for service mesh capabilities.
EU AI Act algorithmic transparency mandates are compelling middleware vendors to embed explainability hooks and audit logging into integration pipelines. Healthcare and BFSI deployments in France and Germany face the steepest compliance ramps. Affected enterprises are prioritizing vendors with pre-certified governance modules rather than retrofitting open-source alternatives.
Subscription-based consumption models are displacing perpetual licensing in enterprise procurement cycles for middleware infrastructure. Systems integrators and managed service providers are capturing margin pools that previously accrued to software vendors. This shift is most visible in Nordic markets where public sector frameworks mandate operational expenditure treatment for cloud-adjacent software acquisitions.
Middleware Market Segmentation
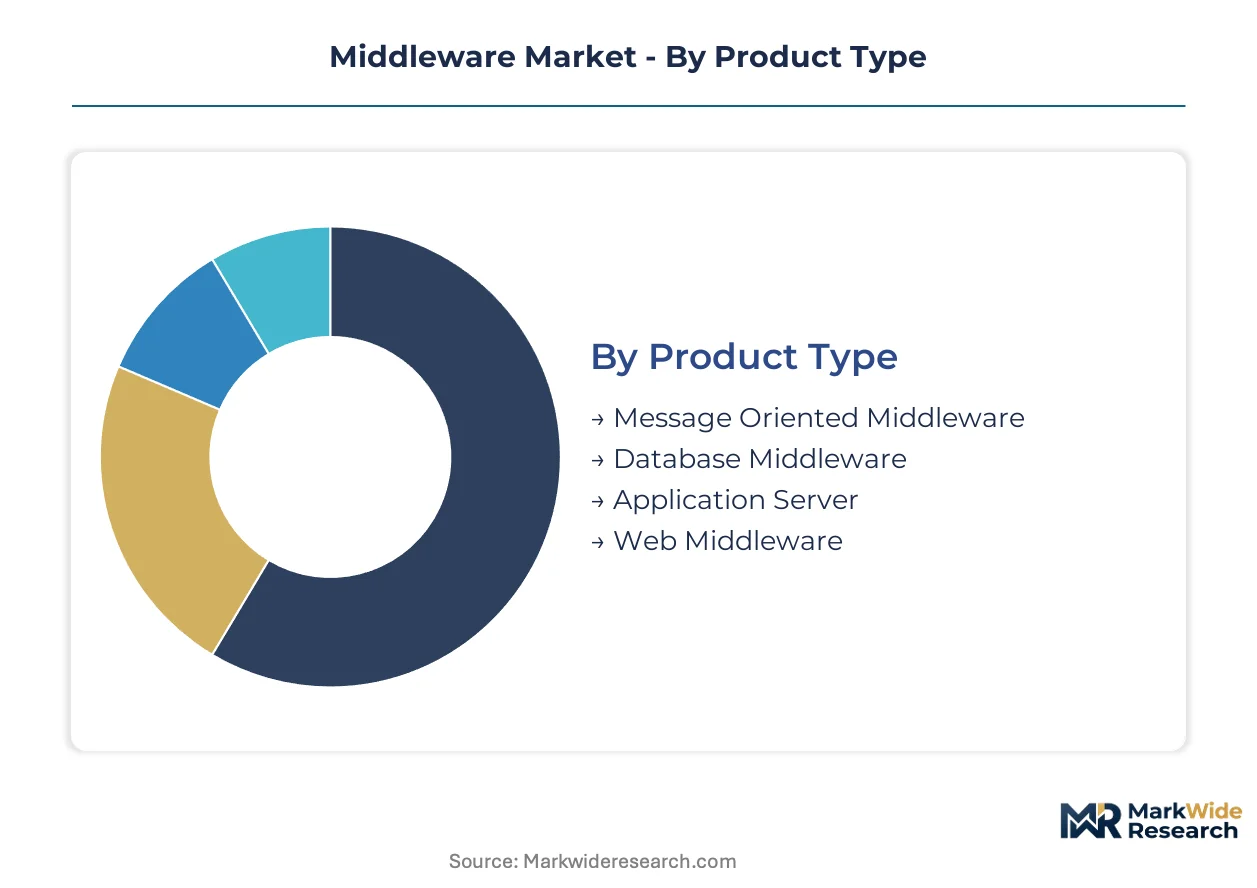
Middleware procurement patterns diverge sharply across deployment models and end-use verticals, with regulated industries demanding hybrid architectures while cloud-native enterprises prioritize container-ready integration stacks. Understanding these fault lines reveals where vendor margins concentrate and which technology transitions threaten incumbent positions.
Product Type:
Supply concentration in application server middleware reflects decades of enterprise Java entrenchment, though cloud-native alternatives are fragmenting procurement toward lighter-weight integration layers.
- Application Server:These runtime environments host Java EE and Jakarta EE applications across clustered configurations, providing transaction management, security, and resource pooling. German automotive manufacturers and financial institutions in Frankfurt sustain demand for high-availability deployments that bridge COBOL mainframes to REST APIs. Legacy skill scarcity and certification requirements protect incumbent vendors despite containerization pressure.
- Message Oriented Middleware:Message queuing and publish-subscribe systems enable asynchronous communication between distributed applications through guaranteed delivery semantics. Telecommunications operators in Singapore and Switzerland deploy event-driven middleware for real-time payment orchestration and 5G network slicing. Apache Kafka ecosystems are capturing developer mindshare from commercial offerings in price-sensitive accounts.
- Database Middleware:Connection pooling, query routing, and data caching layers abstract database complexity for application developers.
- Web Middleware:HTTP servers, reverse proxies, and content delivery integration handle web-tier traffic management and session persistence.
Application server middleware absorbs the bulk of installed capacity; microservices-oriented alternatives are expanding most quickly.
Deployment:
Cost tier stratification separates regulated enterprises requiring data residency controls from cloud-native startups prioritizing operational expenditure treatment.
- Cloud-Based:Fully managed middleware services eliminate infrastructure provisioning overhead through consumption-based pricing. Nordic public sector frameworks mandate operational expenditure treatment, accelerating subscription procurement for integration platform-as-a-service offerings. AWS, Azure, and GCP native services are commoditizing standalone middleware in price-sensitive segments.
- Hybrid:Split deployments maintain sensitive transaction processing on-premises while bursting web-tier workloads to public cloud. EU AI Act and GDPR mandates are fragmenting architectures as French and German healthcare providers keep patient data within sovereign boundaries while leveraging cloud analytics for operational workloads.
- On-Premises:Self-managed installations persist in core banking and defense applications with stringent air-gapping requirements.
- Multi-Cloud:Portability layers prevent vendor lock-in across heterogeneous cloud estates, though operational complexity inflates total cost of ownership.
Hybrid deployments dominate regulated verticals; cloud-based configurations are gaining share fastest among digital-native enterprises.
End User:
Application intensity varies dramatically, with BFSI generating the highest per-account middleware spend while healthcare interoperability gaps create expansion headroom.
- BFSI:Real-time payment systems, open banking APIs, and algorithmic trading platforms demand sub-millisecond latency with audit-grade reliability. US SEC and FTC scrutiny of API security and transaction logging is elevating compliance costs for vendors serving American banks. IBM sustains dominance in mainframe connectivity layers that bridge core banking systems to modern microservices.
- Telecommunications:5G network slicing orchestration requires event-driven middleware managing latency-sensitive partitions across distributed radio access networks. Fujitsu specializes in integration frameworks for operators in Japan and Southeast Asia managing subscriber authentication and billing mediation.
- Healthcare:HIPAA-compliant interoperability for electronic health record integration remains underpenetrated relative to financial services adoption curves.
- Retail:Omnichannel order management and inventory synchronization drive seasonal scaling requirements for middleware infrastructure.
BFSI commands the highest absolute spend; healthcare data fabric expansion offers the steepest growth trajectory.
Solution:
Maturity gradients separate established integration patterns from emerging architectural paradigms reshaping vendor competitive positioning.
- Microservices:Fine-grained service decomposition demands service mesh, container orchestration, and decentralized data management capabilities. Organizations are dismantling monolithic codebases, forcing incumbent vendors to recast licensing models around consumption-based pricing while defending installed bases. Kubernetes and Istio ecosystems capture developer preference over commercial alternatives.
- API Management:Gateway, developer portal, and analytics layers monetize digital interfaces through rate limiting and security policy enforcement. Singapore and Swiss financial services firms pilot converged service mesh and zero-trust stacks for real-time payment orchestration.
- Integration Solutions:Enterprise service buses and extract-transform-load pipelines handle batch-oriented data synchronization between heterogeneous systems.
- Business Process Management:Workflow orchestration and human task management automate long-running transactional processes across organizational boundaries.
Integration solutions retain the largest installed base; microservices architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters concentrate middleware procurement around Stuttgart and Munich, where automotive manufacturers demand high-throughput integration layers for smart factory deployments. EU data sovereignty rules accelerate replacement cycles across European manufacturing hubs.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria drive demand for application server middleware bridging COBOL mainframes to REST APIs. The EU AI Act mandates algorithmic transparency in financial services, forcing Frankfurt banking centers to retrofit audit-ready integration layers. Industrial automation clusters around Stuttgart require specialized frameworks for equipment connectivity.
United States
SEC scrutiny of API security elevates compliance costs for middleware vendors serving Wall Street banks and Chicago trading floors. HIPAA requirements shape healthcare interoperability procurement in Boston and Minneapolis medical technology corridors. Core banking modernization in Charlotte and Dallas sustains IBM's mainframe connectivity dominance.
Singapore
Telecommunications operators deploy event-driven middleware for real-time payment orchestration across Southeast Asian digital banking corridors. The Monetary Authority of Singapore's technology risk management guidelines enforce strict audit trails for financial middleware deployments. Marina Bay financial district pilots converge service mesh and zero-trust security frameworks.
India
The PLI scheme attracts manufacturing investments requiring localized middleware for industrial equipment connectivity in Gujarat and Tamil Nadu. RBI data localization mandates fragment cross-border middleware architectures for Mumbai and Bangalore fintech operators. Telangana's electronics manufacturing clusters generate concentrated procurement for integration platform-as-a-service offerings.
Switzerland
Swissmedic and FINMA requirements shape healthcare and banking middleware procurement in Zurich and Geneva. Zürich financial services firms pilot latency-critical microservices architectures for wealth management platforms. Basel pharmaceutical headquarters demand HIPAA-equivalent interoperability layers for clinical trial data integration.
Middleware Market Vendor Landscape
Top-tier vendors anchor mainframe connectivity and database middleware layers, while cloud-native specialists capture developer mindshare in microservices segments. The market structure stratifies across three tiers: legacy infrastructure incumbents defending installed bases, hyperscaler bundlers commoditizing standalone integration services, and open-source ecosystem players capturing price-sensitive accounts. Strategic archetypes include mainframe bridge specialists, event-streaming platform vendors, and sovereign cloud integration providers. Competitive moves concentrate on consumption-based licensing recasts and service mesh capability acquisitions.
Within the legacy infrastructure tier, IBM and Oracle occupy positions exemplifying entrenched enterprise Java and database middleware dominance. Fujitsu represents the telecommunications-specialist archetype, anchoring integration frameworks for 5G network slicing orchestration. These three vendors collectively illustrate how incumbent players defend margin pools through certification requirements and specialized bridging expertise for regulated verticals.
| Leading Market Players |
|---|
| Amazon Web Services |
| Software AG |
| IBM |
| SAP SE |
| TIBCO Software |
| Oracle |
| Google Cloud |
| Fujitsu |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
Certified engineering labor costs cascade through middleware pricing tiers, with Frankfurt banking centers and Stuttgart automotive clusters absorbing premium rates for mainframe bridging expertise while Nordic public sector frameworks compress margins through mandated operational expenditure treatment.
Pricing Analysis
Short lead-time delivery commands substantial premiums in middleware procurement, particularly for EU AI Act compliance retrofits where audit-ready integration layers face certification bottlenecks. Subscription-based consumption models dominate cloud-adjacent deployments, while perpetual licensing persists in core banking installations requiring air-gapped configurations. Price differentiation hinges on certification grade (ISO 27001, SOC 2) and customization depth for COBOL-era system bridging. Cost compression in container-native segments intensifies as Apache Kafka ecosystems capture developer preference over commercial message queuing. Small and mid-sized fintech operators exhibit highest price sensitivity; regulated BFSI incumbents demonstrate lowest sensitivity due to compliance-driven vendor stickiness.
Supply Chain Analysis
Freight costs for specialized hardware appliances supporting edge middleware deployments have risen alongside semiconductor component volatility, though software-centric delivery models increasingly bypass physical logistics entirely. Engineering talent concentrates in Germany, India, and the United States, with Bangalore and Hyderabad emerging as integration platform-as-a-service development hubs. Intellectual property licensing draws from Oracle database patents, IBM mainframe protocols, and open-source Apache Foundation frameworks. Single-source vulnerability permeates telecommunications middleware where Fujitsu anchors 5G network slicing orchestration for Japanese and Southeast Asian operators. Distribution runs through systems integrators and managed service providers capturing margin pools previously accruing to pure software vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middleware procurement is accelerating through a technology-transition phase as event-driven architectures displace request-response patterns and service mesh capabilities collapse boundaries between networking infrastructure and application layers.
For Market Incumbents: Deepen vertical integration into mainframe connectivity expertise by acquiring specialized COBOL bridging consultancies in Frankfurt and Charlotte banking corridors, while simultaneously recasting licensing models around consumption-based pricing to defend installed bases against open-source substitution from Apache Kafka and Kubernetes ecosystems threatening message queuing revenue pools. For New Entrants and Emerging Players: Capture white-space opportunity in healthcare data fabric expansion, where HIPAA-compliant interoperability layers for electronic health record integration remain underpenetrated relative to financial services adoption curves. Target mid-sized hospital systems in Minneapolis and Boston medical technology corridors with API management solutions bundled with zero-trust security frameworks, leveraging subscription pricing to bypass capital expenditure approval bottlenecks. For Investors and Strategic Acquirers: Accelerating SEC audit queue backlogs for API security certification is the leading indicator that compliance-automation middleware vendors will command acquisition premiums. Position for five-to-ten year viability around service mesh convergence plays, prioritizing targets with pre-certified governance modules addressing EU AI Act algorithmic transparency mandates rather than retrofit-dependent open-source alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Service Mesh Capability Acquisition | Collapsing boundaries between networking infrastructure and application middleware rewards converged stack vendors in Singapore financial services pilots. |
| Consumption-Based Licensing Recast | Subscription models align with Nordic public sector operational expenditure mandates while defending against open-source substitution. |
| Edge Runtime Development | Lightweight middleware deployments at network peripheries address latency-critical IoT and autonomous systems demand in German industrial automation clusters. |
| Pre-Certified Governance Module Launch | Embedded explainability hooks and audit logging accelerate EU AI Act compliance ramps for French and German healthcare providers. |
| Healthcare Data Fabric Expansion | HIPAA-compliant interoperability layers for electronic health record integration capture underpenetrated demand relative to BFSI adoption curves. |
Methodological Framework
Multi-period observation of middleware procurement patterns, certification queue lengths, and open-source adoption rates anchored the trend analysis, supplemented by interviews with CTOs at Frankfurt banking centers, platform engineers at Singapore telecommunications operators, IT procurement officers in Nordic public sector frameworks, and integration specialists serving German automotive manufacturers. Secondary validation drew from SEC filings of publicly traded vendors, hyperscaler capex disclosures revealing cloud infrastructure investment trajectories, EU regulatory filings documenting AI Act implementation timelines, and hospital procurement databases tracking healthcare interoperability spend. Bottom-up segment sizing triangulated against top-down market boundary assessments.
Input-output matrices modeled deployment mode transitions, vertical adoption intensity, and geographic regulatory clustering across the projection horizon. Segmentation dimensions included product type (application server, message oriented middleware, database middleware, web middleware), deployment configuration (cloud-based, hybrid, on-premises, multi-cloud), end-user vertical (BFSI, telecommunications, healthcare, retail), and solution architecture (microservices, API management, integration solutions, business process management). CAGRs were derived from technology substitution curves and replacement cycle acceleration factors. Forecast inputs incorporated EU data sovereignty mandate compliance costs and 5G network slicing orchestration deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to open-source ecosystem maturation, sovereign cloud mandate fragmentation, and hyperscaler bundling intensity. Forecasts reflect assumptions around regulatory implementation timelines and technology transition velocities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Dropshipping Software Solutions Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
EDA Tools Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Patent Management Software Market
Software & Services
India Software Services Export Market
Software & Services
Global Architecture Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
Database Monitoring Software Market
Software & Services
Resonator Design Software Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Web Framework Software Market
Software & Services
Embedded Operating Systems Market
Software & Services
Taxi Booking Software Market