
 Global Equity Management Software Market | 2026-2036
Global Equity Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Equity Management Software Market Foresight
Subscription-based cap table automation is broadening what equity management vendors monetize beyond one-time licensing. Carta leverages its early-mover position to anchor premium pricing for bundled compliance and investor reporting tools. Pulley competes through granular permission controls designed for multi-stakeholder cap tables at growth-stage companies. Eqvista specializes in valuation modeling features that appeal to venture capital firms managing mark-to-market portfolios.
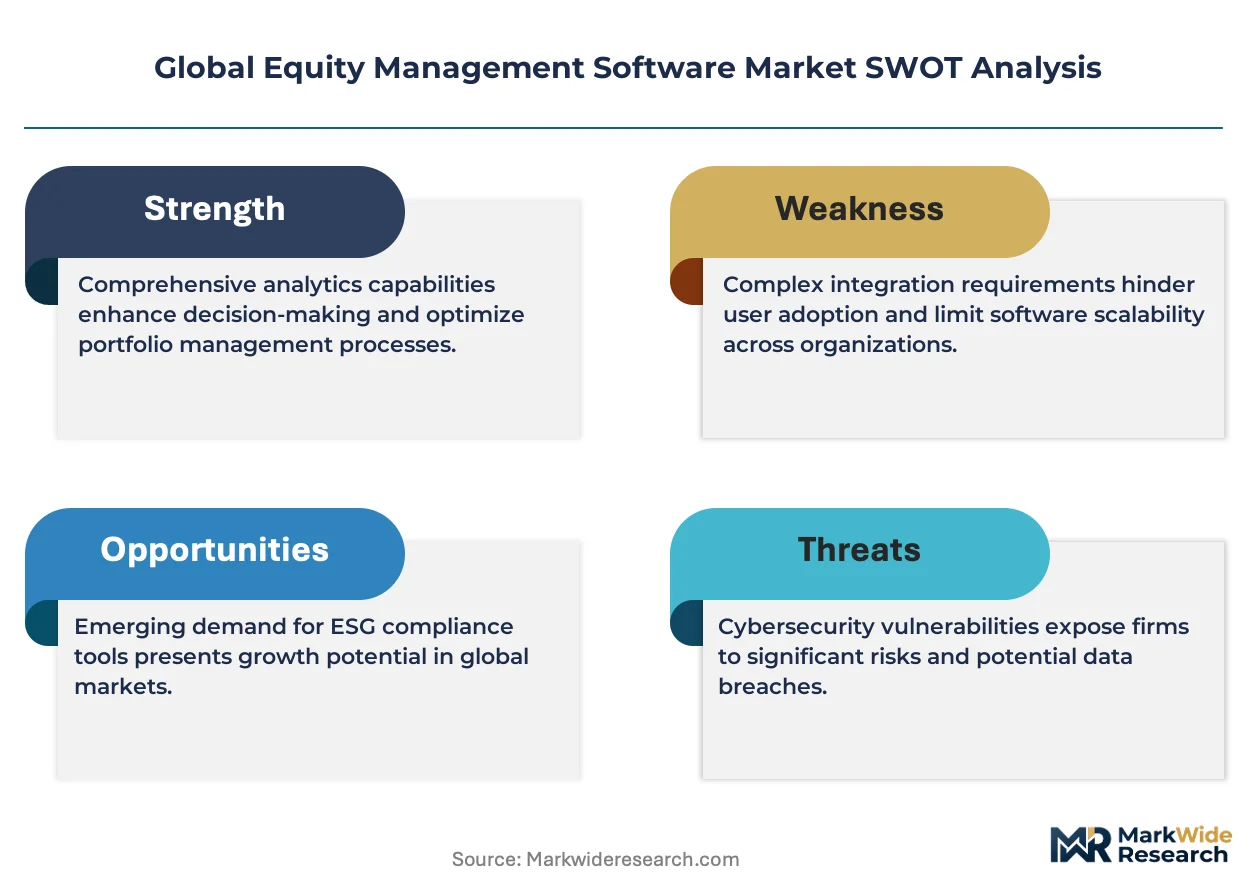
Global equity management software comprises cloud-native and on-premises platforms that track securities issuance, vesting schedules, and ownership dilution through automated ledger updates and audit-trail generation. These systems serve primarily to reduce legal overhead and prevent errors in shareholder recordkeeping for privately held and publicly traded entities. Cloud-based deployment leads volume due to lower implementation friction for startups without dedicated IT infrastructure. Cap table management captures the largest solution-type revenue pool because every funding event requires accurate ownership reconciliation. Compliance tracking represents the fastest-expanding segment as jurisdictional disclosure rules multiply across operating geographies.
The SEC mandates granular equity compensation disclosures that push public and pre-IPO companies toward software with built-in audit trails. GDPR and the EU AI Act shape how European-headquartered platforms store investor biometric data and automate governance decisions. ISO 27001 certification has become a procurement filter for enterprise buyers evaluating vendor security postures. Stakeholders must weigh whether to build compliance depth for regulatory divergence or pursue interoperability standards that simplify cross-border cap table administration.
Market Dynamics
Venture capital portfolio complexity and SEC disclosure mandates are compressing sales cycles for equity management platforms as firms seek auditable systems before next funding rounds.
Growth Catalysts
- Cap table automation:Cloud-native ledger systems reduce legal overhead for startups managing multiple funding events and stakeholder classes.
- SEC disclosure mandates:Enhanced equity compensation reporting requirements push pre-IPO companies toward software with built-in audit trails.
- Startup density concentration:United States venture formation rates create sustained demand for ownership dilution tracking tools.
Market Restraints
- Data migration friction:Historical cap table records in spreadsheet formats resist clean transfer to structured databases.
- Certification bottlenecks:ISO 27001 audit timelines extend enterprise procurement cycles by six to twelve months.
- Specialized talent scarcity:Professionals combining securities law expertise with software implementation skills command premium compensation.
Strategic Opportunities
- Secondary transaction infrastructure:Private company share liquidity platforms require integrated ownership verification systems.
- GDPR compliance modules:European investor biometric data handling creates demand for jurisdiction-specific governance tools.
- AI-assisted valuation modeling:Machine learning convergence with mark-to-market portfolio management appeals to venture capital limited partners.
Industry Challenges
- Multi-jurisdiction disclosure alignment:Reconciling SEC, FCA, and BaFin reporting standards strains product roadmap prioritization.
- Legacy ERP integration:SAP and Oracle financial systems demand custom API development for cap table synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Equity Management Software Market |
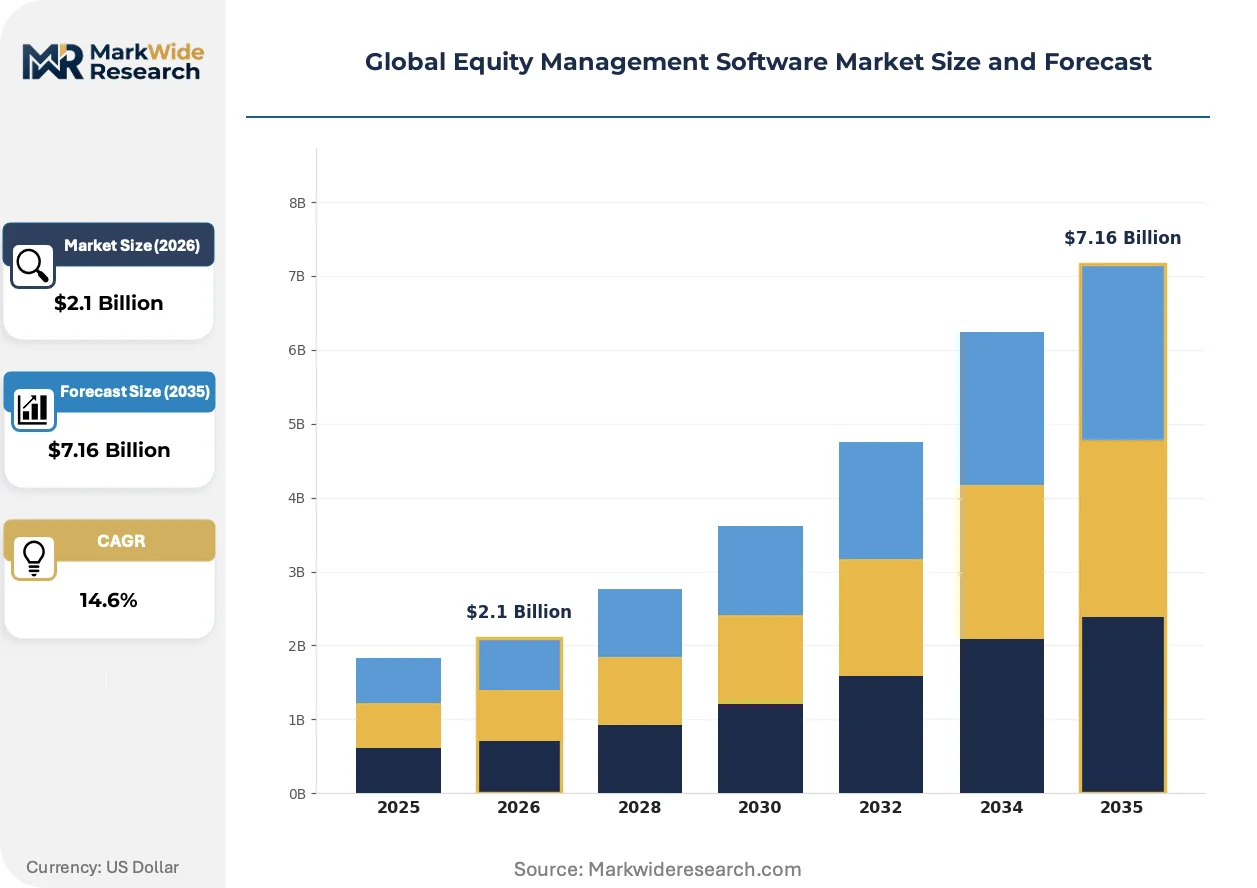
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Cap Table Management, Employee Stock Options, Compliance Tracking, Reporting & Analytics Application: Investor Relations, Shareholder Recordkeeping, Financial Auditing, Corporate Governance End User: Startups, Venture Capital Firms, Private Equity Firms, Public Companies |
| Companies Covered | Eqvista, Certent, Carta, Cake Equity, Pulley, Capdesk, Gust, Shareworks, Ledgy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Equity Management Software Market Shifts & Advancements
Artificial intelligence and blockchain verification are compressing reconciliation timelines while regulatory divergence forces modular compliance architectures.
Smart contract technology is automating vesting schedule execution and option exercise workflows. Growth-stage companies with complex stakeholder bases are adopting these tools at accelerating rates. This automation is eliminating manual escrow interventions and reducing legal review cycles for routine equity events.
The EU AI Act imposes algorithmic transparency requirements on automated governance decisions within equity platforms. European-headquartered vendors must document decision logic for biometric data processing and investor communications. Pre-IPO companies with EU operations are responding by procuring region-specific compliance modules rather than unified global deployments.
Subscription pricing models are displacing perpetual licenses across mid-market buyer segments. Annual recurring revenue structures align vendor incentives with ongoing customer success functions. This shift is most visible in United States startup ecosystems where cash conservation priorities favor operational expenditure treatment.
Global Equity Management Software Market Segmentation
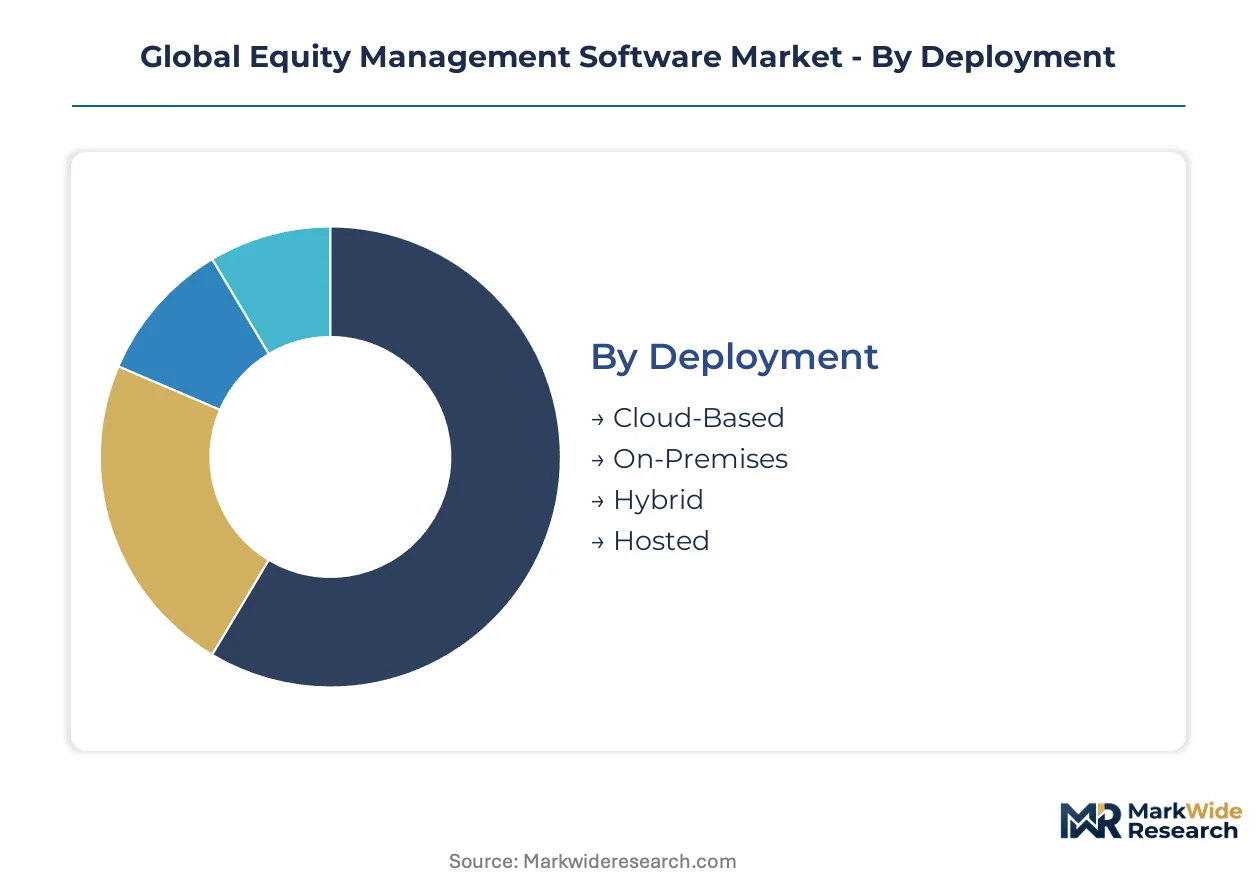
Equity management software segments by deployment architecture, solution capability, application workflow, and buyer organization type. Each axis reveals distinct procurement patterns and technology requirements across startup ecosystems and institutional capital markets.
Deployment:
Cloud-native architectures dominate procurement for organizations lacking dedicated IT infrastructure, while regulated entities evaluate control-tradeoffs across hosting models.
- Cloud-Based:Multi-tenant SaaS platforms deliver automated ledger updates through browser-accessible interfaces without local server maintenance. United States startup ecosystems favor this model for rapid onboarding before funding events, though GDPR data residency rules complicate European deployments.
- On-Premises:Single-tenant installations on customer-controlled servers satisfy financial institutions with proprietary security protocols. German private equity firms specify these deployments to maintain direct custody of investor biometric data under BfDI oversight.
- Hybrid:Split architectures isolate sensitive cap table records on local infrastructure while pushing analytics workloads to cloud environments.
- Hosted:Dedicated single-tenant cloud instances managed by vendors offer middle-ground control without capital expenditure.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
Solution Type:
Functional modules align with organizational maturity — early-stage companies prioritize ownership tracking while pre-IPO entities layer compliance depth.
- Cap Table Management:Automated securities issuance tracking with vesting schedule engines and dilution modeling. Venture capital portfolio companies in California and New York deploy these tools before Series A rounds to prevent spreadsheet errors during rapid ownership changes.
- Compliance Tracking:Jurisdiction-specific disclosure modules with SEC, FCA, and BaFin reporting templates. European-headquartered platforms expand these features fastest under EU AI Act algorithmic transparency mandates.
- Employee Stock Options:Grant administration with exercise workflow automation and tax withholding calculations.
- Reporting & Analytics:Investor dashboard generation with waterfall analysis and scenario modeling tools.
Revenue concentration rests with Cap Table Management. Steepest expansion trajectory belongs to Compliance Tracking.
Application:
Workflow automation targets friction points across capital formation, ongoing stewardship, and regulatory examination cycles.
- Shareholder Recordkeeping:Centralized ownership registers with certificate generation and transfer approval chains. United Kingdom fintech startups adopt these systems to satisfy Companies House filing requirements without legal department expansion.
- Corporate Governance:Board resolution tracking, proxy management, and meeting documentation with audit trails. Public companies preparing for dual-listings in Frankfurt and New York deploy governance modules to reconcile disclosure timelines.
- Investor Relations:Communication portals with document distribution and capital call processing.
- Financial Auditing:Automated data extraction for external auditor review with immutable transaction logs.
Established adoption centers on Shareholder Recordkeeping. Emerging demand clusters around Corporate Governance.
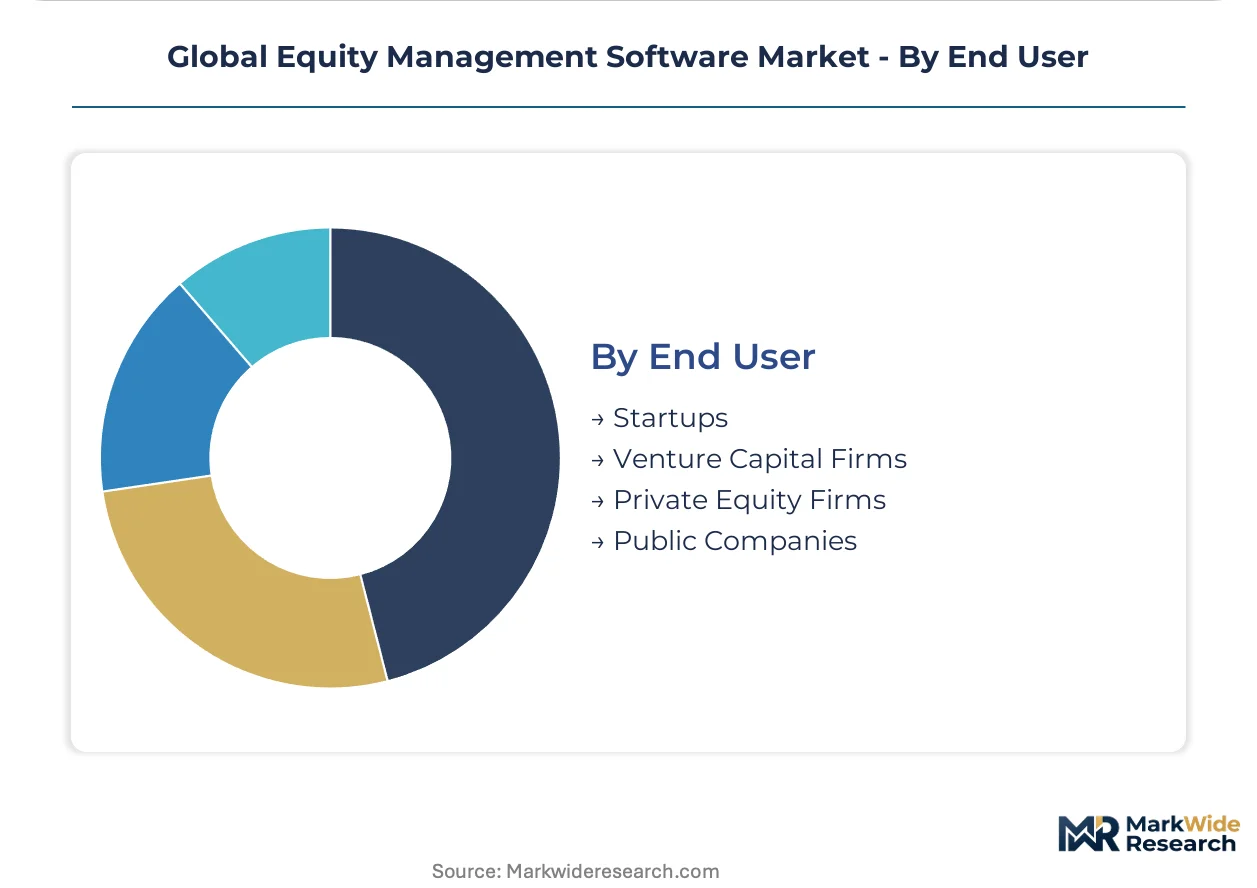
End User:
Buyer sophistication spans bootstrapped founders managing first option grants to institutional limited partners tracking mark-to-market positions.
- Startups:Seed through Series C companies with lean legal teams requiring self-service equity administration. Israeli and Singaporean startup hubs show particular concentration as venture formation rates accelerate in these jurisdictions.
- Venture Capital Firms:Multi-portfolio managers needing standardized cap table visibility across dozens of holdings. Firms with assets under management exceeding $500 million prioritize platforms with API connectivity to portfolio monitoring systems.
- Private Equity Firms:Buyout sponsors managing complex waterfall structures across fund vintages and co-investment vehicles.
- Public Companies:Issuers subject to SOX controls and proxy advisor disclosure standards with dedicated equity administration departments.
Volume leadership belongs to Startups. Procurement value per seat peaks with Public Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the world's densest concentration of equity management software deployment, with venture-backed startups in the Bay Area driving platform adoption rates that outpace other technology corridors.
United States
SEC disclosure mandates and startup formation density create sustained procurement pull. The Sarbanes-Oxley Act and evolving equity compensation rules push pre-IPO companies toward auditable systems. New York and Boston financial districts host the largest installed bases outside California, with fintech clusters in Miami and Austin accelerating adoption.
Germany
BaFin oversight and GDPR data residency requirements shape vendor selection criteria. The BfDI enforces strict biometric data handling protocols for investor records. Munich and Frankfurt private equity firms specify on-premises deployments to maintain direct custody of sensitive cap table information under national supervision.
United Kingdom
FCA disclosure standards and Companies House filing automation drive compliance module demand. The UK GDPR framework imposes algorithmic transparency requirements on automated governance tools. London's venture capital corridor generates concentrated demand for multi-stakeholder cap table management before Series A funding events.
Israel
Venture formation rates in Tel Aviv create outsized demand relative to market size. The Israel Securities Authority mandates granular equity tracking for companies approaching public listings. Herzliya Pituach technology clusters host specialized implementation consultants combining securities law expertise with software deployment skills.
Singapore
Monetary Authority of Singapore guidelines on digital asset governance attract regional headquarters deployments. The Personal Data Protection Act shapes how platforms store investor biometric information across Southeast Asian operations. Raffles Place financial district concentrates procurement decision-making for pan-Asian venture portfolios.
Global Equity Management Software Market Competitive Landscape
Capital-heavy platform infrastructure competes with asset-light specialized modules across the equity management software landscape. Early-mover advantages have consolidated around integrated suites, while niche challengers penetrate through vertical-specific compliance depth. Three archetypes dominate: full-stack incumbents bundling cap table, valuation, and governance tools; point-solution specialists targeting single workflow automation; and regional compliance-first vendors capturing jurisdiction-specific procurement. Strategic moves center on API ecosystem expansion and secondary transaction infrastructure integration.
Within the full-stack tier, Carta and Pulley occupy positions defined by divergent customer segmentation approaches. Eqvista anchors the valuation-specialist archetype, representing vendors that compete through financial modeling depth rather than workflow breadth. These three companies exemplify how competitive positioning stratifies across platform comprehensiveness versus functional precision.
| Leading Market Players |
|---|
| Eqvista |
| Certent |
| Carta |
| Cake Equity |
| Pulley |
| Capdesk |
| Gust |
| Shareworks |
| Ledgy |
| Others |
Supply & Pricing Matrix
Securities law expertise concentrated in San Francisco and New York widens pricing-tier spreads between premium compliance bundles and self-service entry tiers, as labor-cost differentials for specialized implementation talent feed directly into vendor margin structures.
Pricing Analysis
Value-based pricing anchored to audit-trail completeness and regulatory examination outcomes dominates enterprise procurement. Three-tier pricing structure across premium, standard, and economy levels separates SOC 2 Type II-certified platforms with dedicated customer success from stripped-down cap table utilities. Price differentiation rests on ISO 27001 certification status and API integration depth. Pricing pressure stems from open-source ledger alternatives and spreadsheet inertia among seed-stage founders. Venture capital firms show lowest price sensitivity due to portfolio-wide standardization mandates, while bootstrapped startups cluster in economy tiers.
Supply Chain Analysis
Single-source vulnerability sits with cloud infrastructure providers Amazon Web Services, Microsoft Azure, and Google Cloud Platform hosting the majority of multi-tenant SaaS deployments. Software development draws from engineering talent pools in the United States, India, and Israel. Raw material dependencies include open-source database technologies, identity verification APIs, and biometric processing libraries. Supply chain risk centers on regulatory restriction as EU AI Act algorithmic transparency requirements fragment code bases. Distribution runs through direct vendor sales teams, channel partnerships with law firms, and embedded offerings through venture capital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into secondary transaction infrastructure and upstream data sources is reshaping competitive positioning as full-stack vendors seek to capture liquidity event economics beyond subscription fees.
For Market Incumbents: Cement platform stickiness through embedded compliance modules that automate SEC, FCA, and BaFin filing workflows. Deepen API ecosystem partnerships with portfolio monitoring systems to raise switching costs for venture capital firms. Counter specialized valuation-modeling challengers by acquiring mark-to-market analytics capabilities.
For New Entrants and Emerging Players: EU AI Act algorithmic transparency requirements in Germany and France open a window for jurisdiction-specific governance tools that incumbent global platforms struggle to modularize. Target Israeli and Singaporean startup hubs where venture formation rates outpace local vendor presence. Pursue channel partnerships with regional law firms as primary go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors compliance-first specialists with deep securities law expertise over horizontal workflow tools. Long-term viability hinges on regulatory divergence accelerating demand for modular architectures. Monitor ISO 27001 certification timelines as inflection indicator for enterprise procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Transaction Infrastructure Integration | Captures liquidity event economics beyond recurring subscription revenue streams. |
| Regulatory Compliance Module Expansion | Addresses SEC, GDPR, and EU AI Act divergence through jurisdiction-specific tooling. |
| API Ecosystem Partnership Development | Raises switching costs by embedding cap table data into portfolio monitoring systems. |
| Valuation Modeling Capability Acquisition | Appeals to venture capital limited partners tracking mark-to-market positions. |
| Geographic Expansion to Emerging Startup Hubs | Targets Tel Aviv and Singapore where venture formation exceeds local vendor supply. |
Research Methodology
Multi-period observation of venture capital deployment velocity, regulatory filing volumes, and platform adoption rates anchored the trend analysis, supplemented by interviews with equity administration officers at venture capital firms, cap table managers at pre-IPO companies, securities law practitioners, and software procurement leads. Secondary validation drew from SEC disclosure filings, EU regulatory bulletins, startup formation databases, and cloud infrastructure spending reports. Bottom-up triangulation across individual platform deployments reconciled with top-down market sizing from aggregate funding event tracking.
Segment-weighting approaches distributed value estimates across deployment architecture, solution capability, application workflow, and buyer organization type dimensions. CAGRs were derived from regression analysis of historical adoption curves against funding cycle timing and regulatory mandate implementation schedules. Forecast inputs included venture capital dry powder projections, pre-IPO company pipeline estimates, and jurisdictional disclosure rule expansion timelines.
Caveats apply where regulatory delay, funding market contraction, or data migration friction could materially shift the outlook beyond modeled trajectories. Forecasts reflect assumptions about continued startup formation density and sustained enforcement of equity compensation disclosure standards. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Systems Administration Management Tools Market
Software & Services
Job Description Management Software Market
Software & Services
Geomechanics Software and Service Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Customer Advocacy Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Cemetery Software Market
Software & Services
User Interface Software Market
Software & Services
Saas Based HRM Market
Software & Services
Global Process Mining Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Spain Sports Management Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
PAC Programming Software Market
Software & Services
Global Development Tools Software Market