
 BFSI Software Market | 2026-2036
BFSI Software Market Size, Share, and Industry Trends Forecast 2026-2036
BFSI Software Market Analysis
India's fintech corridor is reshaping how core banking platforms scale across emerging economies. Oracle Corporation leverages its database heritage to dominate enterprise-grade installations in North American money-center banks. SAP SE anchors its position through deep ERP integration that spans treasury operations and regulatory reporting. Tata Consultancy Services Limited competes by combining offshore delivery scale with localized compliance expertise across Commonwealth markets.
BFSI software encompasses the specialized applications, middleware, and platforms that enable financial institutions to execute transactions, manage risk, ensure regulatory compliance, and deliver customer-facing services through digital and physical channels. These systems process millions of concurrent operations with sub-second latency requirements while maintaining audit trails that satisfy prudential supervisors. Core Banking solutions occupy the largest installed base, though SaaS deployment models are capturing the fastest expansion as tier-two institutions abandon capital-intensive on-premise refreshes. Fraud Detection within the Application Area dimension commands premium pricing, driven by real-time transaction monitoring mandates and machine-learning model refresh cycles.
The Federal Reserve's operational resilience guidelines, the EU's DORA framework, and India's RBI cybersecurity directives are collectively elevating procurement standards for vendor risk management and business continuity capabilities. Compliance Software solutions are absorbing disproportionate R&D investment as multi-jurisdiction institutions seek unified reporting architectures. Stakeholders must weigh cloud concentration risk against the agility gains of SaaS delivery as regulatory scrutiny of third-party dependencies intensifies.
Market Dynamics
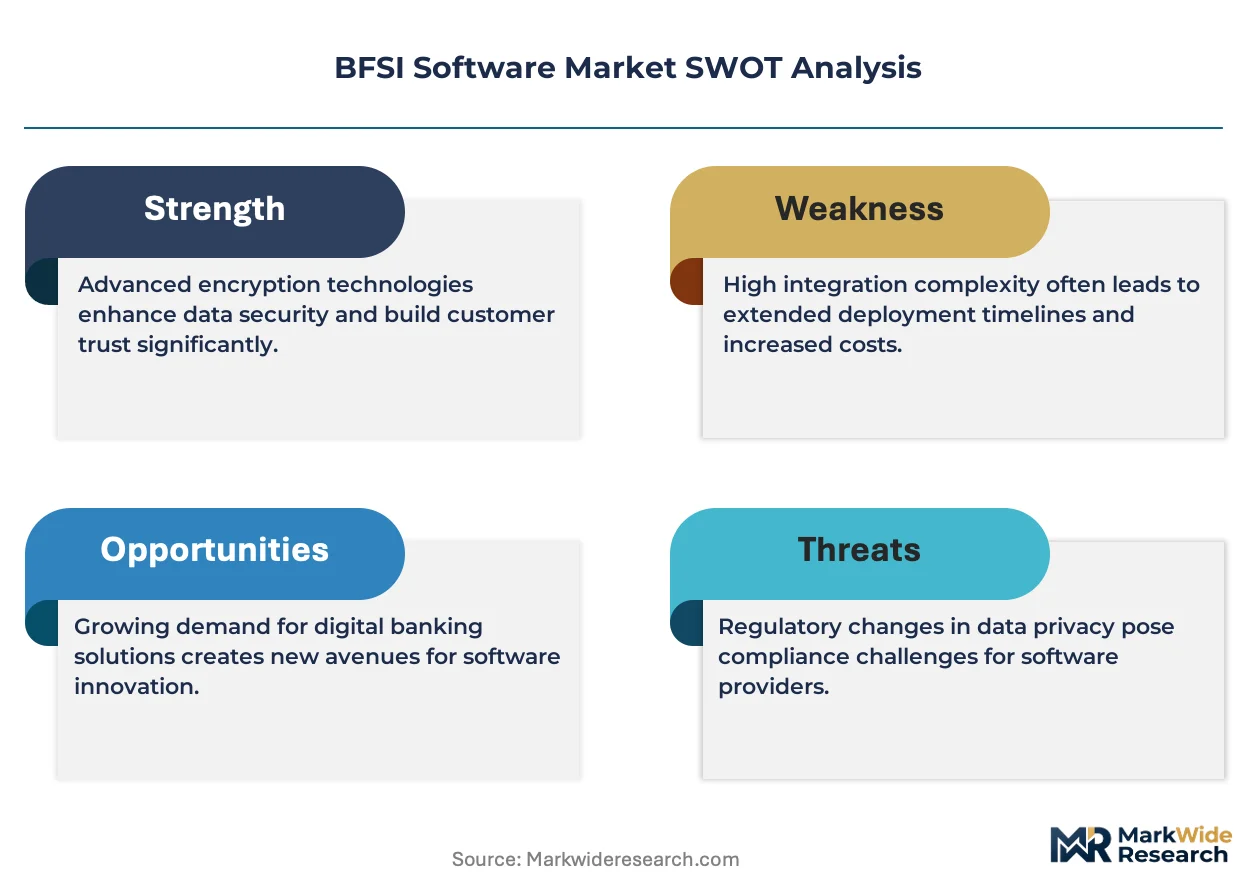
Cloud-native core banking platforms are displacing monolithic legacy stacks as tier-two institutions abandon capital-intensive refresh cycles. The EU's Digital Operational Resilience Act and India's RBI cybersecurity directives are elevating procurement standards for vendor risk management capabilities.
Growth Catalysts
- EU DORA Compliance Mandate:European institutions must upgrade risk management infrastructure by 2025, forcing wholesale replacement of legacy operational resilience tools.
- India's UPI Ecosystem Expansion:The National Payments Corporation of India processes billions of real-time transactions monthly, driving demand for scalable payment middleware.
- Real-Time Fraud Detection:Machine-learning model refresh cycles for transaction monitoring are compressing from quarterly to weekly updates.
Market Restraints
- Cloud Concentration Risk:Regulatory scrutiny of third-party dependencies intensifies as hyperscalers dominate SaaS delivery infrastructure.
- Specialized Talent Scarcity:Shortage of engineers proficient in both legacy COBOL systems and modern container orchestration limits migration velocity.
- Multi-Jurisdiction Reporting Complexity:Institutions operating across the US, EU, and India face conflicting data localization requirements.
Strategic Opportunities
- Embedded Finance Integration:Non-bank platforms in retail and logistics seek white-labeled banking-as-a-service APIs.
- Regulatory Sandbox Participation:RBI's framework allows fintechs to test innovations with relaxed compliance burdens.
- AI-Driven Predictive Analytics:Convergence of natural language processing and graph neural networks enables anticipatory risk scoring.
Industry Challenges
- Core System Migration Complexity:Decades-old transaction processing architectures resist modular decomposition without service disruption.
- Model Governance Overhead:Explainability requirements for algorithmic credit decisions demand dedicated MLOps infrastructure.
- Vendor Lock-In Escalation:Proprietary data formats in SaaS platforms complicate future platform switches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BFSI Software Market |
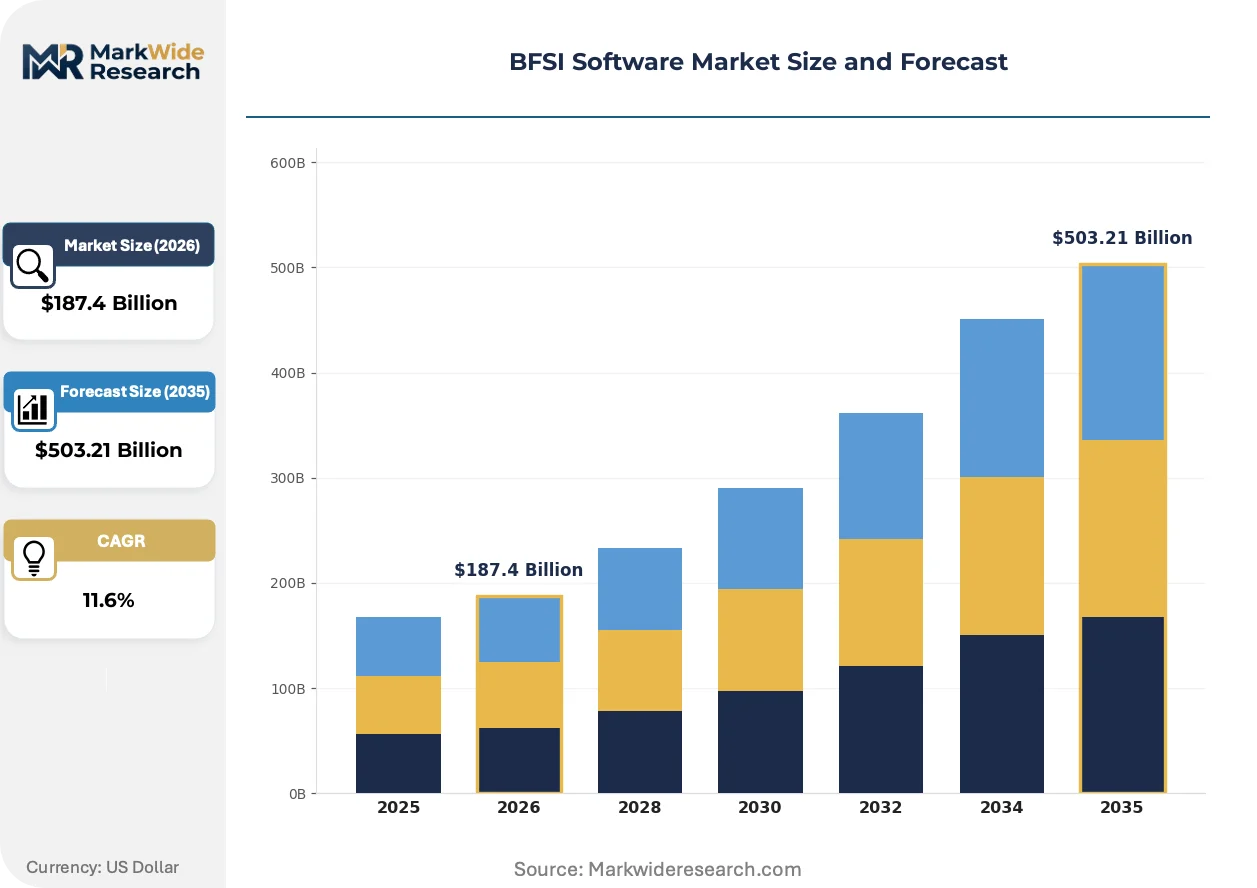
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Core Banking, Mobile Banking, Investment Management, Compliance Software Deployment Model: On-Premise, Cloud, Hybrid, SaaS Customer Type: Retail Customers, Corporate Clients, SMEs, Financial Institutions Application Area: Payment Processing, Risk Management, Fraud Detection, Wealth Management |
| Companies Covered | Oracle Corporation, SAP SE, IBM Corporation, Microsoft Corporation, FIS Global, Fiserv Inc, Finastra International Limited, Temenos Group, Tata Consultancy Services Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BFSI Software Market Emerging Trajectories
Distributed ledger infrastructure and generative AI are reshaping how financial institutions architect trust and automation. These shifts are compressing development cycles while expanding regulatory surface area.
Core banking infrastructure is hybridizing containerized microservices with selective mainframe retention for high-volume batch processing. Tier-two credit unions and regional lenders adopt this architecture fastest, seeking to match money-center bank capabilities without equivalent capital budgets. The structural result is collapsing the traditional vendor tiering that separated enterprise from mid-market solutions.
The EU's Digital Operational Resilience Act mandates granular third-party risk registers and incident reporting thresholds for critical ICT providers. Financial institutions must map sub-contractor chains to the fourth level, forcing procurement departments to renegotiate thousands of existing vendor agreements. Cloud service providers face the steepest compliance burden, with European supervisors conducting joint oversight examinations.
Subscription-based pricing for core banking modules is displacing perpetual license models among institutions under ten billion dollars in assets. Vendors unbundle treasury, lending, and payments components, allowing buyers to scale functional scope with deposit growth. This pattern is most visible in India's cooperative banking sector, where UPI integration requirements accelerate SaaS procurement decisions.
BFSI Software Market Segmentation
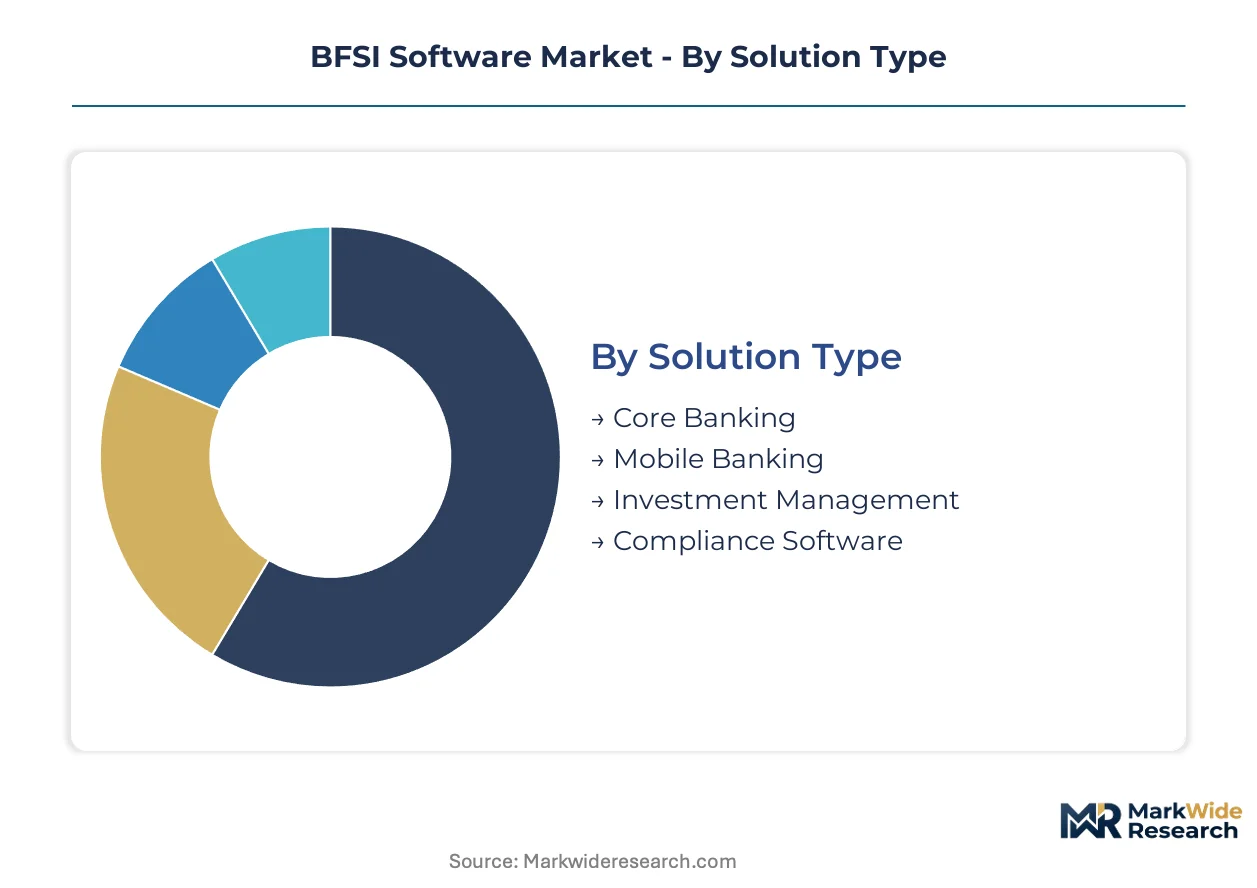
BFSI software procurement patterns diverge sharply by institutional scale and regulatory exposure. Solution architecture, delivery model, and functional priority each create distinct vendor competitive arenas with specialized pricing dynamics.
Solution Type:
Cost tier determines implementation complexity and ongoing operational burden across banking technology stacks.
- Core Banking:Transaction processing engines manage deposit accounts, lending operations, and general ledger functions through centralized databases. Tier-two credit unions in India and cooperative banks across Germany are migrating from legacy mainframe installations to containerized microservices architectures.
- Compliance Software:Regulatory reporting automation and audit trail management systems satisfy multi-jurisdiction supervisory requirements. European institutions facing DORA implementation deadlines are prioritizing unified risk data warehouses over point solutions.
- Mobile Banking:Customer-facing applications enabling remote account access, fund transfers, and digital onboarding.
- Investment Management:Portfolio analytics, order execution, and custody administration platforms serving asset managers and wealth advisors.
Core Banking holds installed capacity. Compliance Software is rotating up the share rankings.
Deployment Model:
Application criticality and data sovereignty requirements shape infrastructure location decisions.
- SaaS:Subscription-delivered modules eliminate capital expenditure cycles and accelerate functional upgrades. Regional lenders under ten billion dollars in assets across India and the United States are adopting SaaS core banking faster than money-center competitors.
- Cloud:Hyperscaler-hosted infrastructure provides elastic compute for payment processing peaks and regulatory batch reporting. EU institutions must map fourth-level sub-contractor chains under DORA, elevating vendor due diligence costs.
- On-Premise:Institution-owned data centers retain sensitive transaction processing within physical perimeter controls.
- Hybrid:Selective mainframe retention for high-volume batch operations combined with cloud-native customer channels.
On-Premise retains mission-critical workloads. SaaS is climbing the fastest among deployment alternatives.
Customer Type:
Volume concentration and service complexity create divergent procurement authority structures.
- Financial Institutions:Banks, credit unions, and insurers with dedicated procurement functions negotiate enterprise license agreements. India's scheduled commercial banks and cooperative banking sector are consolidating vendor relationships under RBI cybersecurity directive compliance programs.
- Corporate Clients:Treasury departments of non-financial enterprises require cash management, trade finance, and liquidity forecasting tools.
- Retail Customers:Individual account holders accessing services through institution-provisioned channels.
- SMEs:Small business operators seeking integrated payment acceptance, payroll, and credit facilities.
Financial Institutions command vendor attention. SMEs are gaining procurement sophistication fastest.
Application Area:
Functional priority reflects regulatory enforcement intensity and direct revenue impact.
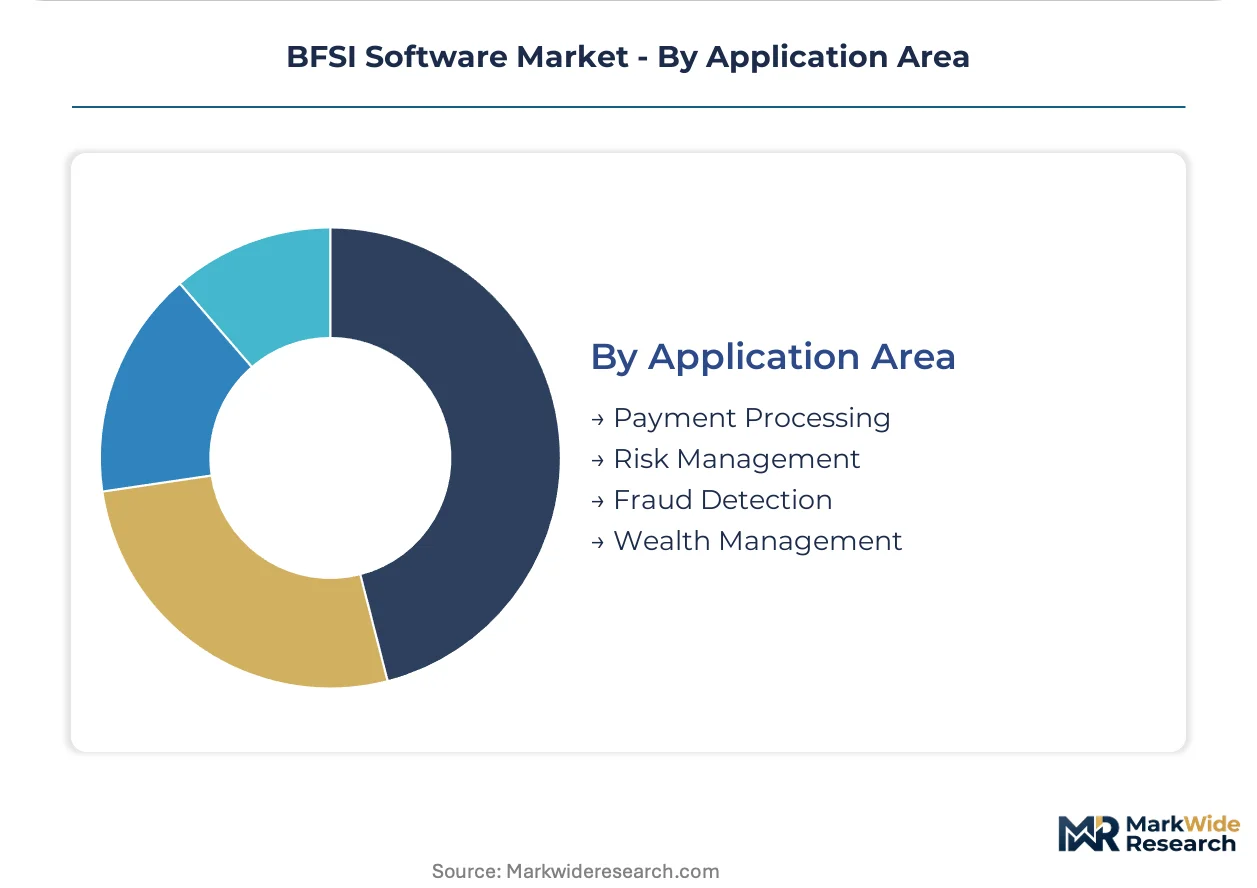
- Fraud Detection:Real-time transaction monitoring systems deploy machine-learning models with weekly refresh cycles to identify anomalous payment patterns. European payment service providers and Indian UPI ecosystem participants face mandatory monitoring thresholds.
- Risk Management:Credit scoring, market risk analytics, and operational resilience dashboards aggregate exposures across asset classes. DORA's third-party risk register requirements are forcing wholesale replacement of legacy operational resilience tools.
- Payment Processing:Clearing, settlement, and cross-border remittance infrastructure handling billions of monthly transactions.
- Wealth Management:Client portfolio construction, tax optimization, and fiduciary reporting for high-net-worth segments.
Payment Processing anchors transaction volumes. Fraud Detection is expanding most quickly on regulatory mandate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI cybersecurity directives and India's UPI ecosystem expansion are establishing the country as the dominant procurement geography for core banking modernization. Software procurement standards across the United States, Germany, and Japan reflect divergent regulatory timelines for operational resilience compliance.
United States
Money-center banks in New York and Chicago are refreshing legacy mainframe installations with hybrid cloud architectures. The Federal Reserve's operational resilience guidelines mandate sub-second recovery capabilities for critical payment systems. Oracle Corporation leverages its database heritage to dominate enterprise-grade installations across these financial centers.
Germany
Cooperative banking networks and regional Landesbanks face compressed DORA implementation deadlines through 2025. The EU's Digital Operational Resilience Act requires fourth-level sub-contractor mapping across vendor chains. Frankfurt's concentration of ECB-supervised institutions is driving unified risk data warehouse procurement.
India
Scheduled commercial banks and cooperative banking sectors are consolidating vendor relationships under RBI cybersecurity directive compliance programs. The National Payments Corporation of India processes billions of real-time UPI transactions monthly. Mumbai and Bengaluru fintech corridors are reshaping how core banking platforms scale across emerging economies.
United Kingdom
Open Banking mandates and PSD2 compliance requirements are accelerating API infrastructure investment among challenger banks. The Financial Conduct Authority's operational resilience rules align with DORA implementation timelines. London's Square Mile concentration of international banks is prioritizing vendor risk management platform upgrades.
Japan
Regional banks facing negative interest rate pressures are adopting SaaS core banking to reduce operational expenditure. METI digital transformation incentives support legacy system modernization initiatives. Tokyo's megabank headquarters are deploying machine-learning fraud detection with weekly model refresh cycles.
BFSI Software Market Vendor Landscape
Enterprise software conglomerates and specialized banking technology vendors split the market into distinct competitive arenas. Consolidation pressures favor players with integrated ERP-to-core-banking data flows. Database heritage providers and offshore delivery specialists represent the dominant strategic archetypes. Competitive moves center on SaaS module unbundling and regulatory sandbox participation partnerships.
Within the enterprise software tier, Oracle Corporation and SAP SE exemplify divergent positioning strategies. Oracle leverages its Redwood Shores database heritage to anchor enterprise-grade installations in North American money-center banks. SAP SE occupies a position defined by deep ERP integration spanning treasury operations and regulatory reporting. Tata Consultancy Services Limited represents the offshore delivery archetype, combining scale with localized compliance expertise across Commonwealth markets.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| Microsoft Corporation |
| FIS Global |
| Fiserv Inc |
| Finastra International Limited |
| Temenos Group |
| Tata Consultancy Services Limited |
| Others |
Supply Flow & Price Mechanics
Bengaluru's software engineering cluster feeds capacity into global BFSI procurement pipelines, concentrating development talent in a geography where labor arbitrage still compresses SaaS delivery costs. This geographic concentration grants Indian-origin vendors pricing flexibility that Western competitors struggle to match without offshore replication.
Pricing Analysis
North American enterprise installations command premiums of 40-60 percent above equivalent deployments in India and Southeast Asia, reflecting compliance certification tiers and data residency guarantees. Subscription-based SaaS modules for core banking now dominate among institutions under ten billion dollars in assets, with pricing stratifying across premium, standard, and economy tiers based on API call volume and regulatory reporting depth. Cost compression in the mid-market tier is intensifying because containerized microservices have collapsed the traditional vendor tiering that separated enterprise from mid-market solutions. Tier-two credit unions exhibit the highest price sensitivity, while money-center banks prioritize vendor risk management capabilities over unit economics.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud providers have restructured vendor working capital requirements, with 90-120 day receivables now standard for SaaS platform components. Software development capacity concentrates in India, Ireland, and Poland, with these jurisdictions anchoring both captive development centers and third-party delivery partnerships. Raw material dependencies center on semiconductor compute instances, open-source middleware libraries, and specialized financial data feeds. Single-source vulnerability runs through hyperscaler infrastructure concentration, as regulatory scrutiny of third-party dependencies intensifies under DORA and RBI cybersecurity directives. Distribution runs through direct enterprise sales organizations supplemented by systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BFSI software markets exhibit defensive moat characteristics rooted in regulatory entrenchment. Switching costs escalate dramatically once institutions embed vendor platforms into audit trail and reporting workflows that satisfy prudential supervisors.
For Market Incumbents: Pre-empt competitive displacement by embedding AI-driven predictive analytics into existing client architectures before challengers achieve standalone traction. Acquire specialized fraud detection boutiques to consolidate machine-learning model governance capabilities. DORA's fourth-level sub-contractor mapping requirements create natural bundling opportunities for integrated risk data warehouses. For New Entrants and Emerging Players: Build out white-labeled banking-as-a-service API offerings targeting retail and logistics platforms seeking embedded finance integration. India's cooperative banking sector presents the most penetrable geography, where UPI compliance mandates accelerate procurement decisions without incumbent relationship entrenchment. Lead with regulatory sandbox participation as proof-of-concept validation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors containerized core banking specialists with demonstrated DORA compliance architectures. Long-term viability hinges on multi-jurisdiction regulatory coverage rather than single-market dominance. Acquisition targets should demonstrate weekly machine-learning model refresh capabilities and unified risk data warehouse deployments. Monitor RBI cybersecurity directive enforcement intensity as inflection indicator for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified ERP-to-core-banking data flows satisfy DORA's risk register mandates across European installations. |
| Regulatory Sandbox Participation | RBI framework partnerships accelerate fintech innovation validation with relaxed compliance burdens. |
| Acquisition of Specialist Firm | Fraud detection boutiques with weekly ML model refresh cycles command premium valuations. |
| Geographic Expansion | Indian cooperative banking sector procurement concentrates vendor relationships under cybersecurity directives. |
| Strategic Partnership | Hyperscaler alliances address cloud concentration risk while maintaining SaaS delivery agility. |
Methodological Framework
Two parallel data streams informed the analysis: structured conversations with CTOs, IT procurement officers, platform engineers, and integration specialists at tier-one and tier-two financial institutions, combined with secondary validation against SEC filings, hyperscaler capex disclosures, regulatory sandbox participant lists, and RBI cybersecurity directive implementation reports. Bottom-up segmentation modeling triangulated against top-down market sizing derived from vendor revenue disclosures and installed base estimates.
Forecast inputs span deployment model, institution asset tier, application area criticality, and regional regulatory intensity across the projection horizon. CAGRs were derived from segment-level growth rate distributions weighted by procurement velocity indicators. Core banking modernization cycles, fraud detection model refresh frequency, and compliance software R&D absorption rates served as industry-specific forecast inputs.
Practitioners should monitor DORA enforcement intensity, RBI cybersecurity directive expansion, and hyperscaler concentration risk regulatory action for early signals of forecast revision. Macroeconomic deviation, regulatory timeline acceleration, or generative AI disruption of development cost structures would prompt reassessment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Bill of Material Management Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Mobile Speech Recognition Software Market
Software & Services
EDA Tools Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Transient Analysis Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Global Church Management Software Market
Software & Services
General Ledger Accounting Software Market
Software & Services
Channel Management Software Market
Software & Services
Account Reconciliation Software Market
Software & Services
Business Activity Monitoring Software (BAM) Market