
 Military Load Carriage System Market | 2026-2036
Military Load Carriage System Market Size, Share, and Industry Trends Forecast 2026-2036
Military Load Carriage System Market Outlook
The EU Green Deal's sustainable procurement criteria is recalibrating material specifications for European defense tenders, pushing suppliers toward recycled nylon and bio-based composites. Mystery Ranch leverages its Bozeman, Montana manufacturing base to sustain domestic production for US military contracts. Crye Precision anchors its position through proprietary laminate fabrics and close integration with US Army Natick Soldier Systems Center. BAE Systems competes across the full spectrum from individual load carriage to integrated soldier systems, extending its reach through platform-level contracts.
A military load carriage system comprises modular platforms—backpacks, vests, pouches, and belts—engineered to distribute operational loads across the musculoskeletal frame while permitting rapid reconfiguration for mission profiles. These systems typically integrate MIL-SPEC webbing, laser-cut laminate construction, and quick-release mechanisms to sustain mobility under loads exceeding 45 kilograms in tactical environments. Backpacks dominate procurement volume due to universal infantry requirement, while Kevlar-reinforced vests command premium positioning through ballistic integration and extended duty cycles. Special Forces application segments exhibit the fastest configuration turnover, driven by mission-specific modularity demands and compressed replacement cycles.
US Army Natick Soldier Research, Development and Engineering Center sets performance benchmarks for load carriage systems, while NATO Standardization Office harmonizes interoperability requirements across allied procurement. The EU's CSRD reporting obligations are pressing defense suppliers to document supply chain emissions, reshaping material sourcing decisions for European contracts. Stakeholders must monitor the divergence between US MIL-STD durability specifications and emerging European sustainability mandates, as this regulatory friction will determine which material platforms achieve cross-Atlantic scale.
Market Dynamics
The US Army's Modular Scalable Vest program and NATO Special Forces procurement cycles are compressing product lifecycles while demanding simultaneous weight reduction and ballistic performance gains. This dual mandate is forcing material science investments and supplier consolidation across the defense industrial base.
Growth Catalysts
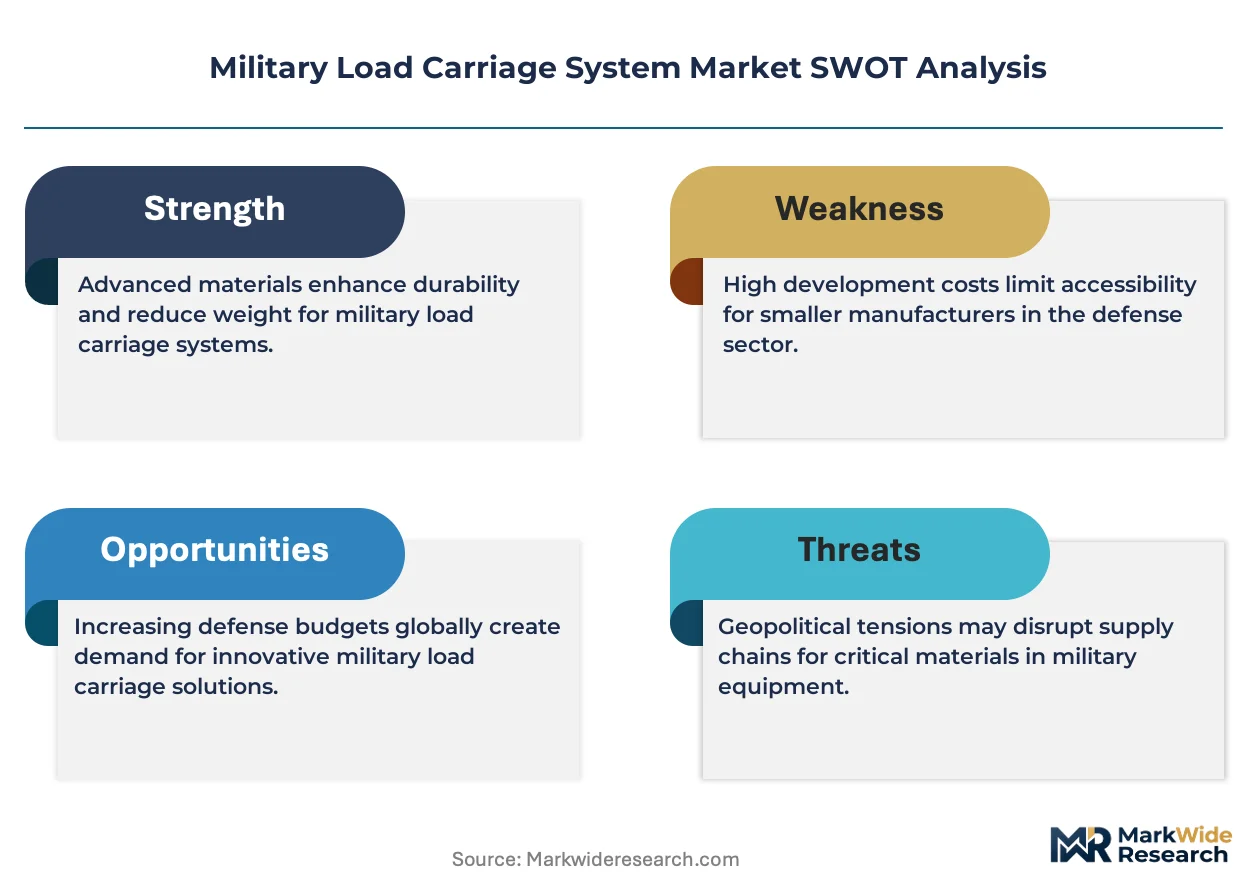
- EU Green Deal sustainable procurement criteria:European defense tenders now specify recycled nylon and bio-based composites, redirecting supplier R&D toward circular material platforms.
- Special Operations Command equipment refresh cycles:US SOCOM's compressed replacement schedules for modular plate carriers sustain demand velocity independent of conventional procurement lulls.
- Laser-cut laminate construction:This manufacturing process reduces material waste and enables rapid pouch reconfiguration, aligning with mission-specific modularity requirements.
Market Restraints
- Kevlar and aramid fiber cost volatility:Petroleum-derived feedstock exposure creates margin pressure for vest manufacturers during energy price spikes.
- US domestic production concentration:Bozeman, Montana and limited alternative sites create geographic supply risk for MIL-SPEC webbing and finished goods.
- REACH chemical registration burdens:European coating and adhesive suppliers face compliance cost barriers that disadvantage smaller material providers.
Strategic Opportunities
- CSRD supply chain emissions documentation:Early compliance with EU corporate sustainability reporting obligations positions vendors for preferred supplier status in European tenders.
- Quick-release mechanism integration:Convergence of mechanical engineering and textile manufacturing creates differentiation for medevac-compatible vest systems.
- Platform-level soldier system contracts:BAE Systems and integrated primes are bundling load carriage with communications and power management, opening channel access for subsystem specialists.
Industry Challenges
- MIL-STD durability certification timelines:US Army Natick testing protocols extend product validation to 18-24 months, constraining innovation cadence.
- Ballistic integration complexity:Seamless incorporation of hard and soft armor plates without compromising load distribution requires cross-functional engineering teams scarce in the labor market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Load Carriage System Market |
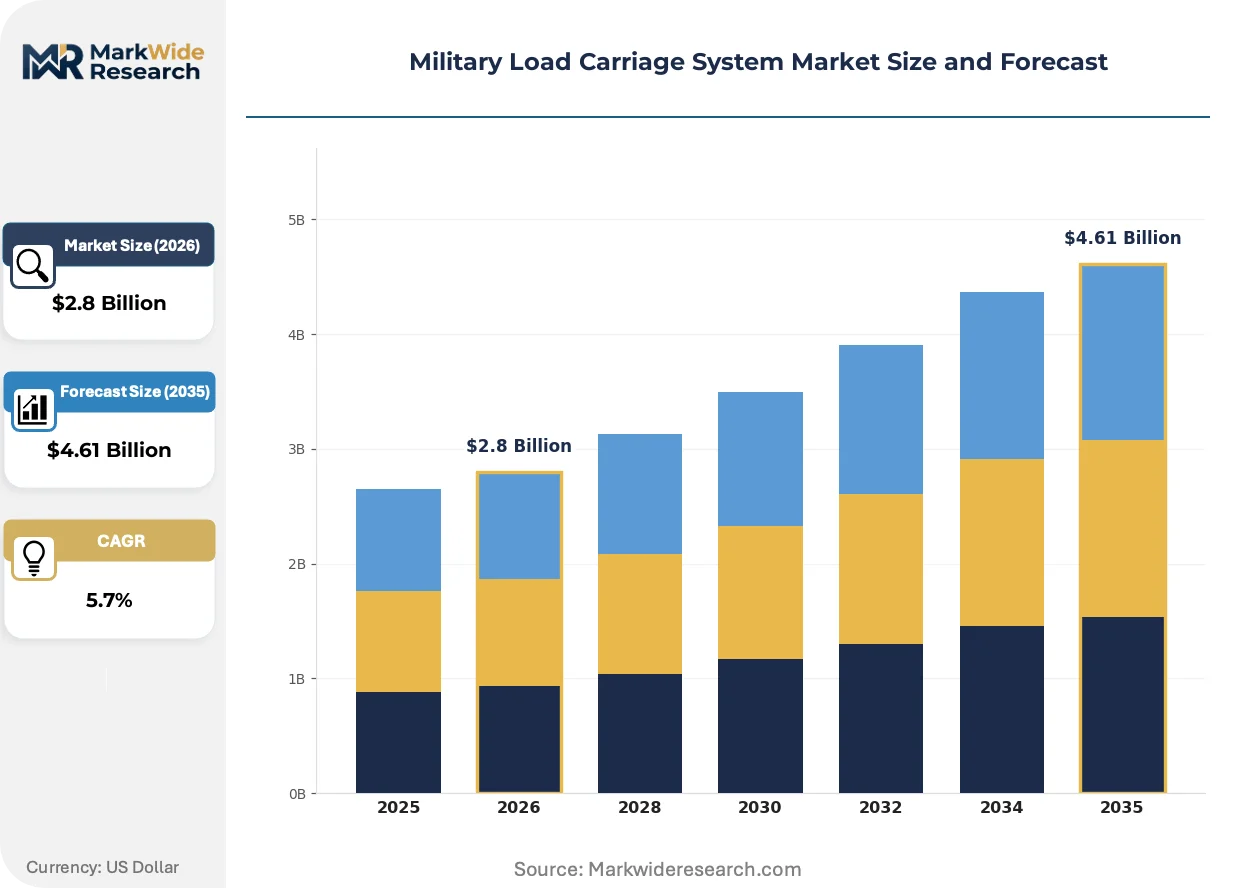
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Vests, Pouches, Belts Material: Nylon, Polyester, Canvas, Kevlar Application: Infantry, Special Forces, Logistics, Medical User Type: Military Personnel, Contractors, Law Enforcement, Civilians |
| Companies Covered | Source Tactical Gear, Mystery Ranch, Safariland Group, Crye Precision, Eagle Industries, BAE Systems, ADS Inc., Ehmke Manufacturing, TYR Tactical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Load Carriage System Market Strategic Shifts
Material substitution and regulatory divergence are fragmenting technical standards while procurement centralization concentrates buying power among fewer defense primes. These forces are reshaping competitive positioning without altering fundamental demand drivers.
Laser-cut laminate fabric construction is overtaking traditional sewn webbing in Special Forces plate carrier programs. US Army Natick Soldier Systems Center has accelerated evaluation of these platforms for airborne and light infantry units. The shift is compressing supplier margins on conventional stitching equipment while rewarding capital investment in CNC cutting and thermal bonding infrastructure.
EU CSRD reporting obligations are forcing defense material suppliers to document Scope 3 emissions from nylon polymerization through finished goods assembly. German and French prime contractors now require tier-two vendors to submit verified carbon footprints as contract preconditions. This regulatory layer disadvantages non-European suppliers lacking established sustainability audit trails.
Outcome-based vest leasing arrangements are displacing outright purchase in select NATO member state procurement. Danish and Norwegian defense ministries now contract for "operational availability" of load carriage systems with vendor-managed inventory and field repair obligations. This model transfers lifecycle cost risk to manufacturers while locking in multi-year sole-source relationships.
Military Load Carriage System Market Segmentation
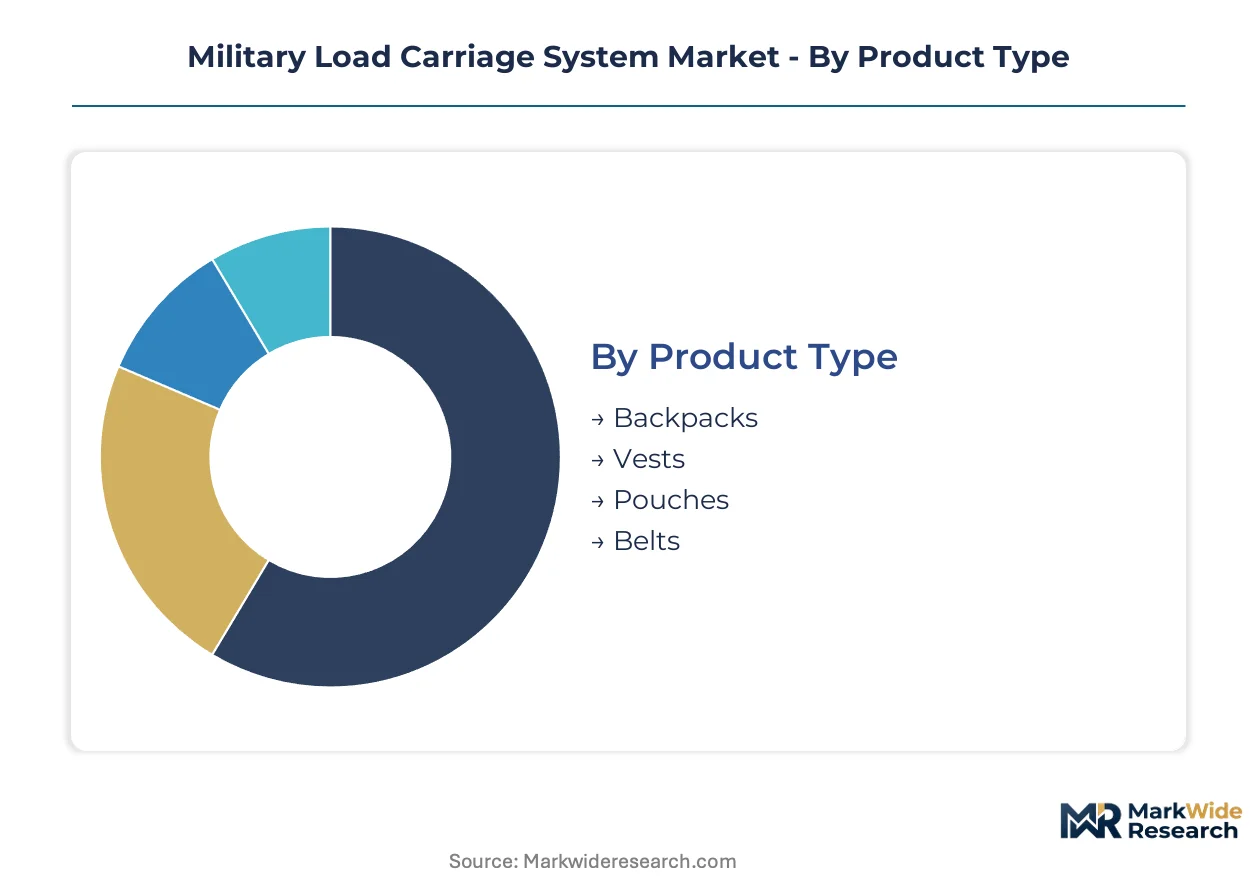
Military load carriage systems fragment across multiple technical and operational dimensions. Procurement patterns diverge sharply between conventional forces requiring standardized configurations and Special Forces demanding rapid mission-specific reconfiguration. Understanding these segment boundaries clarifies where supplier R&D investments concentrate and which material platforms achieve scale.
Product Type:
Customization intensity spans from universal infantry equipment to mission-tailored modular platforms across this category.
- Backpacks:Universal frame-and-harness systems engineered for 45+ kilogram loads with MIL-SPEC webbing and internal frame architecture. Demand concentrates in US Army infantry divisions undergoing equipment refresh cycles, constrained by 18-24 month Natick certification timelines for new designs.
- Vests:Torso-borne platforms integrating plate carriage with load distribution, increasingly constructed via laser-cut laminate methods. Special Forces procurement across NATO militaries is compressing replacement cycles here, driven by airborne compatibility requirements and medevac quick-release mandates.
- Pouches:Modular accessory units for ammunition, medical supplies, and communications equipment.
- Belts:Hip-borne load transfer components with MOLLE attachment interfaces.
Most installed capacity flows through Backpacks. Expansion is steepest in Vests.
Material:
Cost tiers separate petroleum-derived synthetics from emerging bio-based alternatives reshaping European tender specifications.
- Nylon:Dominant polymer for webbing and fabric substrates, specified in US MIL-STD durability protocols. German and French prime contractors now demand verified Scope 3 carbon footprints from tier-two nylon suppliers under CSRD obligations.
- Kevlar:Aramid fiber reinforcement for ballistic-integrated vest panels and abrasion-resistant high-wear zones. Price volatility in petroleum feedstocks creates margin pressure during energy price spikes, constraining smaller vest manufacturers.
- Polyester:Lower-cost synthetic alternative for non-ballistic applications and training equipment.
- Canvas:Legacy cotton-duck material retained for ceremonial and limited field applications.
Procurement volume concentrates in Nylon. Supplier investment is shifting most aggressively toward Kevlar-adjacent composite development.
Application:
End-use maturity separates established infantry programs from emerging integrated soldier system architectures.
- Infantry:Standard-issue load carriage for conventional ground forces, representing the baseline procurement volume across NATO militaries. US Army Modular Scalable Vest program is recalibrating technical requirements toward lighter composite materials here.
- Special Forces:Mission-configurable platforms requiring rapid reconfiguration and compressed replacement cycles. Danish and Norwegian defense ministries are pioneering outcome-based leasing arrangements with vendor-managed inventory in this segment.
- Logistics:Rear-echelon cargo transport systems with reduced mobility requirements.
- Medical:Evacuation-focused configurations with quick-release mechanisms for casualty extraction.
Revenue concentration remains in Infantry. Configuration turnover velocity peaks in Special Forces.
User Type:
Customer risk profiles range from sovereign defense budgets to commercial security contracting with fragmented purchasing authority.
- Military Personnel:Sovereign procurement through centralized defense ministries with multi-year program funding. US Special Operations Command equipment refresh cycles sustain demand velocity independent of conventional procurement lulls.
- Law Enforcement:State and municipal agencies with constrained budgets and simplified ballistic requirements.
- Contractors:Private security firms with commercial purchasing patterns and faster replacement cycles.
- Civilians:Recreational and preparedness markets with minimal regulatory oversight.
Contract volume concentrates with Military Personnel. Margin expansion opportunity sits with Law Enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement specialists cluster around US Army Natick Soldier Systems Center in Massachusetts and NATO Standardization Office in Brussels, anchoring transatlantic demand concentration for military load carriage systems.
United States
Special Operations Command equipment refresh cycles sustain demand velocity independent of conventional procurement lulls. The US Army Modular Scalable Vest program recalibrates technical requirements toward lighter composite materials under MIL-STD durability protocols. Bozeman, Montana hosts Mystery Ranch's domestic manufacturing base for sustained military contract fulfillment.
Germany
Bundeswehr Special Forces procurement programs expand adoption of modular plate carriers with integrated load distribution. The EU Green Deal's sustainable procurement criteria redirects supplier R&D toward recycled nylon and bio-based composites for defense tenders. German prime contractors now require tier-two vendors to submit verified carbon footprints as contract preconditions.
France
Direction Générale de l'Armement oversees specification alignment with NATO interoperability requirements for airborne and light infantry units. REACH chemical registration burdens create compliance cost barriers that disadvantage smaller European coating and adhesive suppliers. The Auvergne-Rhône-Alpes region concentrates textile engineering expertise for laminate fabric development.
United Kingdom
Ministry of Defence procurement centralizes buying power for integrated soldier system architectures bundling load carriage with communications equipment. The UK Defense and Security Equipment International exhibition anchors annual vendor engagement cycles for Special Forces configuration turnover. British Army trials at Warminster Garrison accelerate evaluation of laser-cut laminate construction methods.
Norway
Outcome-based vest leasing arrangements displace outright purchase in Norwegian defense ministry procurement. Forsvaret contracts for operational availability of load carriage systems with vendor-managed inventory and field repair obligations. Oslo-based defense material specialists coordinate Nordic interoperability standards with Swedish and Finnish counterparts.
Military Load Carriage System Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the military load carriage system market. The vendor base concentrates among integrated defense primes, specialized tactical equipment fabricators, and domestic manufacturing specialists serving sovereign procurement channels. Three strategic archetypes dominate: platform-level system integrators bundling multiple soldier subsystems, modular component specialists optimizing rapid reconfiguration, and captive production facilities anchoring MIL-SPEC compliance. Competitive moves center on strategic partnerships with defense research centers and geographic expansion into NATO-aligned procurement programs.
Among US-based fabricators, Mystery Ranch, Crye Precision, and BAE Systems occupy distinct competitive positions. Mystery Ranch exemplifies the domestic manufacturing specialist archetype with its Montana-based production facility. Crye Precision represents the modular component specialist tier through proprietary material platforms and close integration with Army Natick research protocols. BAE Systems anchors the platform-level integrator position across the full spectrum from individual load carriage to integrated soldier systems.
| Leading Market Players |
|---|
| Source Tactical Gear |
| Mystery Ranch |
| Safariland Group |
| Crye Precision |
| Eagle Industries |
| BAE Systems |
| ADS Inc. |
| Ehmke Manufacturing |
| TYR Tactical |
| Others |
Value Chain & Pricing Dynamics
Textile engineering clusters in the Auvergne-Rhône-Alpes region and Bozeman, Montana anchor labor-cost differentials that widen pricing spreads between premium laser-cut laminate vest systems and standard sewn-webbing backpacks. European Union CSRD documentation requirements and US MIL-STD certification timelines compound these cost structures, pushing price stratification across performance tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ballistic-integrated plate carriers from conventional infantry backpacks and training-grade canvas equipment. Price differentiation hinges on Natick certification status and Kevlar reinforcement density, with Special Forces procurement showing lowest price sensitivity due to mission-critical performance mandates. Cost compression in standard-tier nylon webbing intensifies because petroleum feedstock volatility squeezes smaller manufacturers lacking composite material capabilities.
Supply Chain Analysis
Domestic-content mandates under US Berry Amendment provisions and EU Green Deal sustainable procurement criteria are reshaping sourcing patterns for military textiles. Manufacturing concentrates in the United States, Germany, and France, with raw material dependencies spanning petroleum-derived nylon polymerization, aramid fiber production, and laser-cutting equipment fabrication. Single-source vulnerability in MIL-SPEC webbing suppliers creates geographic concentration risk. Distribution runs through defense ministry procurement offices and NATO Standardization Office-coordinated tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU CSRD emissions documentation obligations and US Army Natick certification protocols continuously elevate compliance barriers that favor established suppliers with audit infrastructure.
For Market Incumbents:Acquire laser-cutting and thermal bonding equipment capabilities to defend against laminate construction specialists eroding market share in Special Forces segments. Consolidate tier-two nylon suppliers with verified Scope 3 carbon footprints to preempt EU tender prequalification requirements and secure preferred vendor status with German and French prime contractors.
For New Entrants and Emerging Players:Launch via outcome-based leasing arrangements targeting Nordic defense ministries in Norway and Denmark where vendor-managed inventory models displace conventional procurement. Penetrate the law enforcement segment through simplified ballistic requirements and faster replacement cycles, avoiding 18-24 month Natick certification timelines that gate military access.
For Investors and Strategic Acquirers:Platform-level defense primes are the most active acquirer in this space, bundling load carriage with communications and power management subsystems. Mid-cap modular component specialists with proprietary laminate fabrics and Army Natick research integration represent the optimal acquisition archetype over the coming decade. Monitor divergence between US MIL-STD durability specifications and European sustainability mandates as the inflection signal determining which material platforms achieve cross-Atlantic scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Cut Laminate Manufacturing Scale-Up | Reduces material waste and enables rapid pouch reconfiguration for SOCOM equipment refresh cycles. |
| CSRD Compliance Infrastructure Investment | Positions suppliers for preferred status in German and French defense tenders requiring verified carbon footprints. |
| Quick-Release Mechanism R&D Partnership | Creates differentiation for medevac-compatible vest systems through convergence of mechanical engineering and textile manufacturing. |
| Outcome-Based Leasing Model Deployment | Transfers lifecycle cost risk to manufacturers while locking multi-year sole-source relationships with Nordic defense ministries. |
| Domestic Production Facility Expansion | Sustains Berry Amendment compliance for US military contracts and mitigates geographic supply risk in Montana-based webbing production. |
Study Parameters
Bottom-up Special Forces and infantry procurement modeling reconciled against top-down defense prime production tracking forms the analytical core of this study. Primary interviews with program managers at US Army Natick Soldier Systems Center, procurement officers at NATO Standardization Office, textile engineering directors at laminate fabric specialists, and sustainability compliance leads at German prime contractors combined with secondary validation from US defense budget submissions, EU tender databases, and NATO standardization agreements.
Input-output matrices connect segment-level demand drivers to supplier capacity utilization across the projection horizon. Segmentation dimensions modeled include product type, material platform, application intensity, and user risk profile. CAGRs derive from regression analysis against historical procurement cycles and forward-looking program announcements. Forecast inputs incorporate US SOCOM equipment refresh schedules and EU Green Deal implementation timelines for sustainable procurement criteria.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt defense budget reallocations or accelerated material substitution mandates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Anti-Jamming Equipment Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market