
 Precipitation Hardening Market | 2026-2036
Precipitation Hardening Market Size, Share, and Industry Trends Forecast 2026-2036
Precipitation Hardening Market Analytics
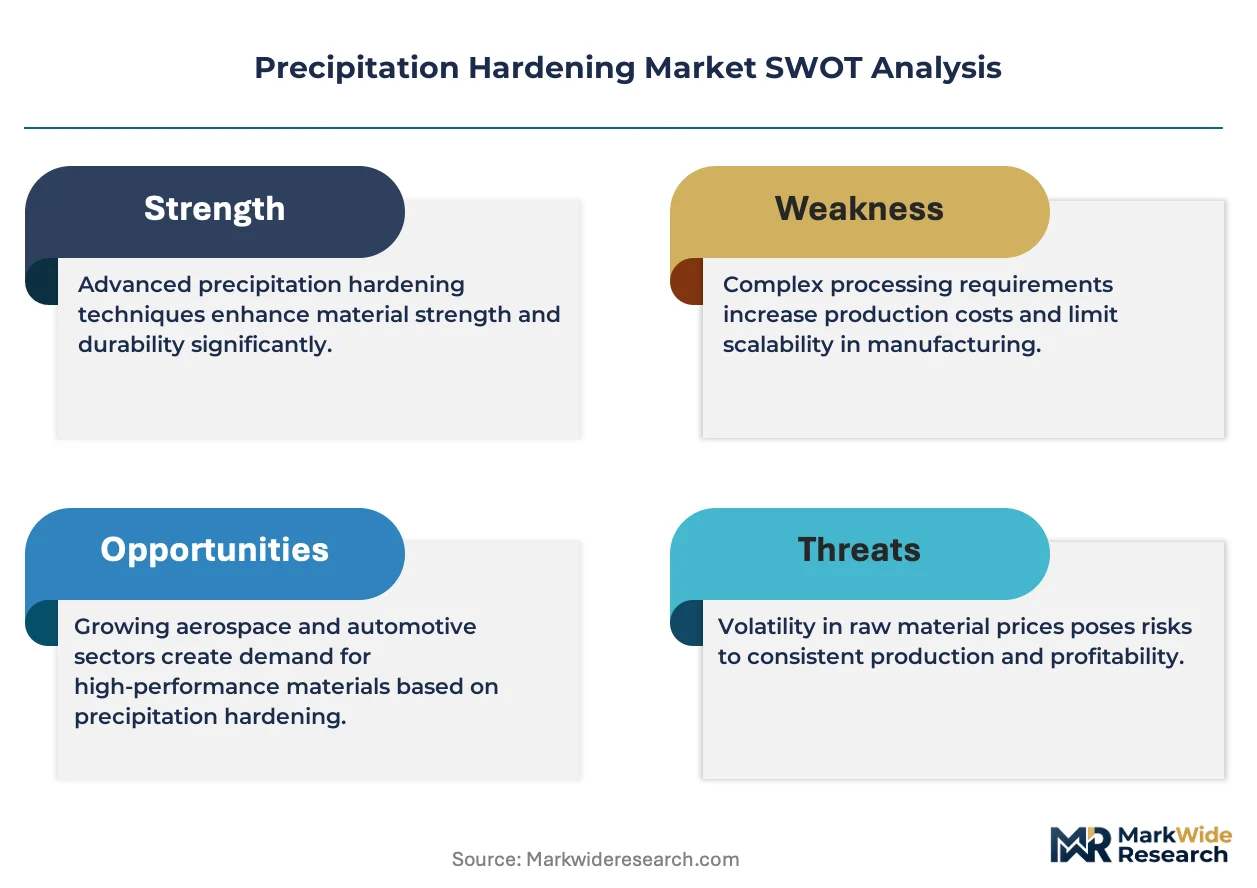
Specialized heat treatment service networks is rewriting how aerospace and defense OEMs source precipitation hardening capacity. Bodycote plc leverages its global furnace footprint to sustain multi-site contracts with tier-one suppliers. Carpenter Technology anchors North American demand through in-house vacuum arc remelting and subsequent aging capabilities. Daido Steel Co., Ltd. competes on precision-controlled aging cycles for nickel superalloy fasteners.
Precipitation hardening strengthens alloys by forming coherent nanoscale precipitates—typically intermetallic compounds like Ni3Al in nickel-base systems or GP zones in aluminum-copper alloys—through controlled thermal aging after solution treatment, achieving yield strengths exceeding 1,200 MPa in peak-aged conditions. Steel alloys dominate volume flows due to broad automotive drivetrain applicability, while titanium alloys command premium positioning in airframe structural brackets where specific strength requirements exclude alternatives. Aerospace applications absorb the highest value share as engine disk and landing gear specifications mandate AMS-certified aging protocols with full thermal history traceability.
FAA airworthiness directives and EASA certification specifications govern heat treatment process validation for flight-critical components, forcing service providers to maintain Nadcap accreditation with continuous furnace uniformity surveys. EPA NESHAP standards for metal finishing operations constrain aging furnace emissions profiles, particularly for nickel alloy processing where hexavalent chromium surface conversion remains prevalent. Stakeholders must monitor evolving AMS specifications for additive-manufactured precipitation hardenable alloys, as powder bed fusion feedstocks demand modified aging responses compared to wrought equivalents.
Market Dynamics
Specialized heat treatment service networks are consolidating around Nadcap-accredited furnace clusters, concentrating qualified capacity within aerospace manufacturing corridors and forcing OEMs into multi-site contractual arrangements to secure aging throughput.
Growth Catalysts
- Aerospace engine specifications:Turbine disk and landing gear mandates for AMS-certified thermal processing sustain demand for vacuum-controlled aging cycles with full traceability documentation.
- REACH substance restrictions:European ECHA regulations on hexavalent chromium surface treatments accelerate substitution toward precipitation-hardenable nickel alloys with native corrosion resistance.
- Automotive lightweighting:Drive train manufacturers specify PH stainless steels for transmission components to replace case-hardened carbon steels in torque-density-critical applications.
Market Restraints
- Nickel price volatility:LME nickel contract swings directly compress margins for nickel-base superalloy aging service providers locked into annual fixed-price contracts.
- Furnace capacity concentration:Germany's Ruhr industrial cluster controls disproportionate European vacuum aging capacity, creating single-point vulnerability for continental supply security.
- Substitution by additive manufacturing:Directed energy deposition of near-net-shape titanium brackets reduces wrought-and-aged component demand in specific airframe applications.
Strategic Opportunities
- India defense localization:Ministry of Defence indigenization mandates for fighter engine components create first-mover advantage for heat treatment service providers establishing Nadcap-accredited facilities near Bangalore aerospace clusters.
- Electrification thermal management:Electric vehicle battery enclosure manufacturers specify precipitation-hardened aluminum alloys for crashworthy tray structures requiring specific strength above 300 MPa.
- ISO 14001 convergence:Environmental management system integration with aging furnace operations opens premium pricing tiers for carbon-accounted thermal processing in European supply chains.
Industry Challenges
- Metallurgical technician scarcity:Qualified furnace operators capable of interpreting TTT diagrams and managing multi-stage aging protocols remain concentrated among retiring workforce cohorts in mature industrial economies.
- Nadcap audit cycle compression:Continuous furnace uniformity survey requirements and 12-month reaccreditation timelines strain quality management resources at mid-cap service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precipitation Hardening Market |
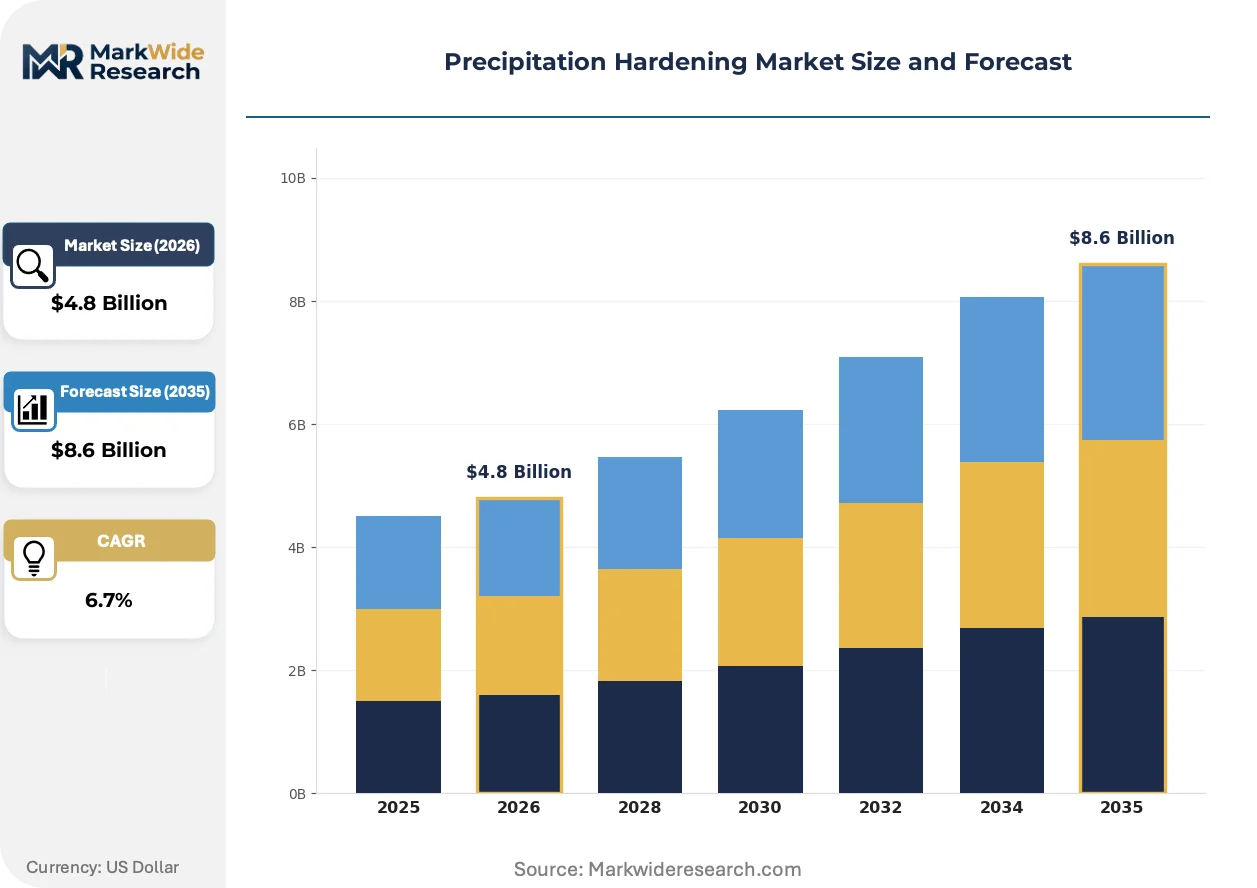
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum Alloys, Nickel Alloys, Titanium Alloys, Steel Alloys Application: Aerospace, Automotive, Marine, Defense Delivery Mode: Direct Supply, Distributor, Online Sales, B2B Sales End User: Manufacturers, Contractors, OEMs, Research Institutions |
| Companies Covered | Bodycote plc, Bluewater Thermal Solutions, Specialty Steel Treating, Inc., Aalberts Surface Technologies, Paulo Heat Treating, Wallwork Heat Treatment Limited, Carpenter Technology, Daido Steel Co., Ltd., Haynes International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precipitation Hardening Market Evolving Landscape
Digital thermal monitoring and predictive aging models are compressing process development cycles, while regulatory pressure on emissions intensifies furnace technology refresh rates across established service networks.
Machine learning-enabled microstructure prediction is hybridizing traditional empirical aging curve development with physics-informed neural networks. Aerospace tier-one suppliers deploy these tools to reduce qualification timelines for new alloy heats from 18 months to under 6 months. This convergence is compressing competitive differentiation formerly anchored in proprietary thermal databases.
EPA NESHAP standards for hazardous air pollutants from metal heat treatment operations mandate regenerative thermal oxidizer retrofits on aging furnaces processing nickel alloys. Equipment suppliers report 24-month order backlogs for compliant furnace systems. Service providers in California and Texas face the steepest compliance costs due to state-level overlay requirements.
Consolidated procurement of heat treatment capacity through multi-year sole-source agreements is displacing spot-market transactions for flight-critical components. Tier-one aerospace suppliers now contract 3-5 year thermal processing commitments with penalty clauses for furnace downtime. This shift concentrates supplier risk with accredited providers in Wichita, Toulouse, and Hamburg manufacturing corridors.
Precipitation Hardening Market Segmentation
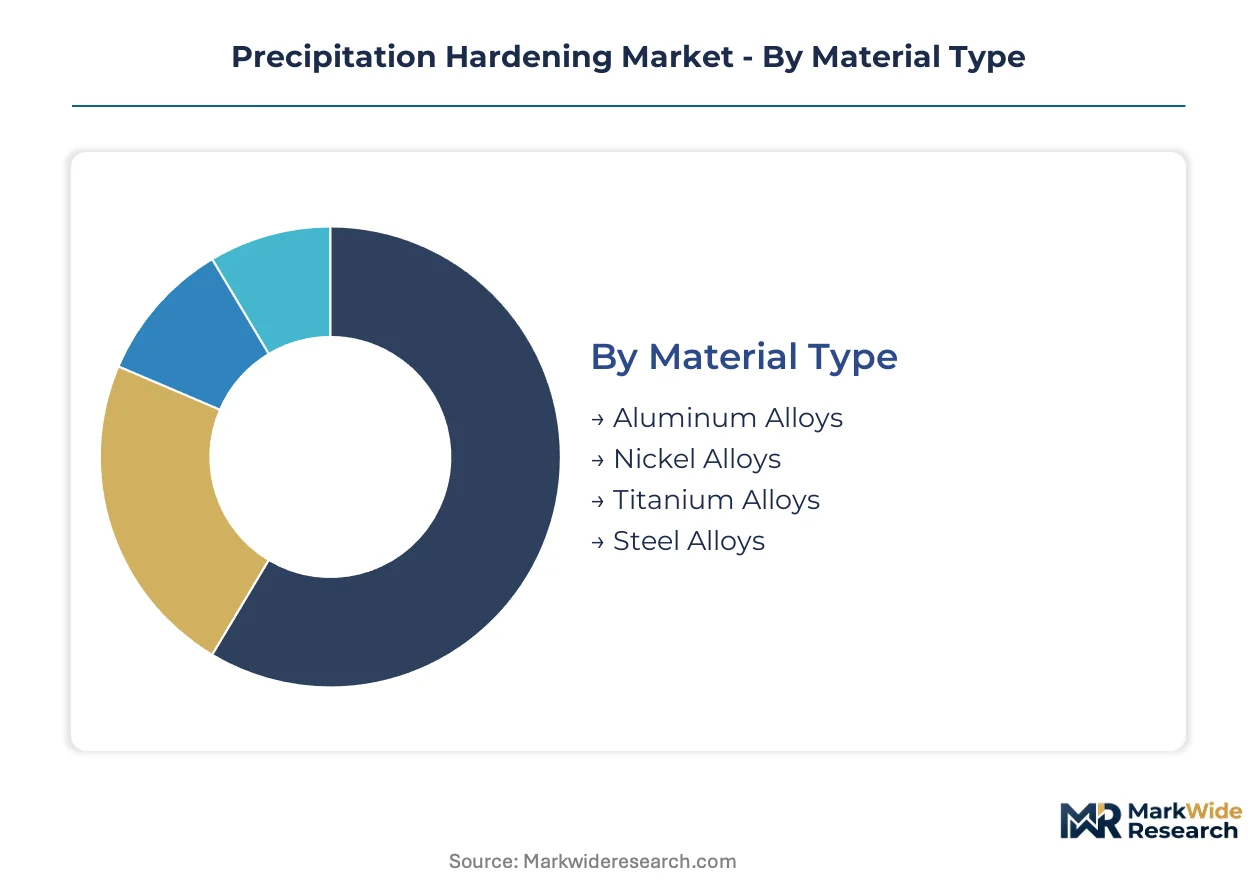
Precipitation hardening service procurement fragments across material specifications, application criticality, and supply chain integration models. Understanding these segment boundaries reveals where pricing power concentrates and where capacity bottlenecks form.
Material Type:
Mature alloys anchor volume flows while emerging formulations capture specification upgrades in next-generation platforms.
- Steel Alloys:PH stainless grades (17-4PH, 15-5PH) deliver yield strengths of 1,100-1,300 MPa through copper and niobium precipitate formation. Automotive drivetrain manufacturers in Stuttgart and Detroit specify these for transmission shafts requiring torque density above 200 Nm/kg. REACH substance restrictions on hexavalent chromium plating accelerate substitution toward native corrosion-resistant PH steels.
- Nickel Alloys:Inconel 718 and Waspaloy achieve gamma-prime (Ni3Al,Ti) strengthening for turbine disk applications above 650°C operating temperatures. Aerospace engine OEMs mandate vacuum-controlled aging cycles with full thermal history traceability per AMS specifications. Nickel price volatility on LME contracts compresses service provider margins locked into annual fixed-rate agreements.
- Aluminum Alloys:7075-T6 and 6061-T6 systems rely on GP zone and metastable precipitate formation for airframe structural efficiency.
- Titanium Alloys:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades serve landing gear and fastener applications where specific strength requirements exclude alternatives.
Steel alloys retain volume leadership; nickel alloys hold the steepest expansion curve.
Application:
Cost tier stratification separates flight-critical specifications from commercial industrial processing.
- Aerospace:Engine disks, landing gear, and structural brackets demand AMS-certified aging protocols with Nadcap-accredited furnace uniformity surveys. FAA airworthiness directives and EASA certification specifications govern process validation for flight-critical components. Tier-one suppliers contract 3-5 year sole-source thermal processing commitments with penalty clauses for furnace downtime.
- Automotive:Transmission components and chassis fasteners specify PH stainless steels to replace case-hardened carbon steels in torque-density-critical applications. Drive train manufacturers in Germany's Ruhr cluster and Michigan's automotive corridor concentrate procurement through qualified heat treatment networks.
- Defense:Fighter engine components and armor systems require ITAR-controlled processing with restricted foreign ownership of aging facilities.
- Marine:Propeller shafts and submarine hull fasteners utilize PH copper-nickel alloys for seawater corrosion resistance.
Aerospace commands premium pricing tiers; automotive scales volume throughput.
Delivery Mode:
Customer type determines channel configuration, with integrated OEMs bypassing intermediaries while fragmented buyers rely on distributor networks.
- B2B Sales:Long-term framework agreements dominate aerospace and automotive procurement, with thermal processing bundled into multi-year component supply contracts.
- Direct Supply:Large OEMs with captive heat treatment capabilities source aging services from Bodycote and Carpenter Technology for overflow capacity.
- Distributor:Mid-tier manufacturers access qualified aging capacity through metal service centers holding Nadcap accreditation.
- Online Sales:Digital platforms facilitate spot-market transactions for non-flight-critical components with standardized AMS specifications.
B2B sales retain contract value concentration; online channels gain share in commoditized specifications.
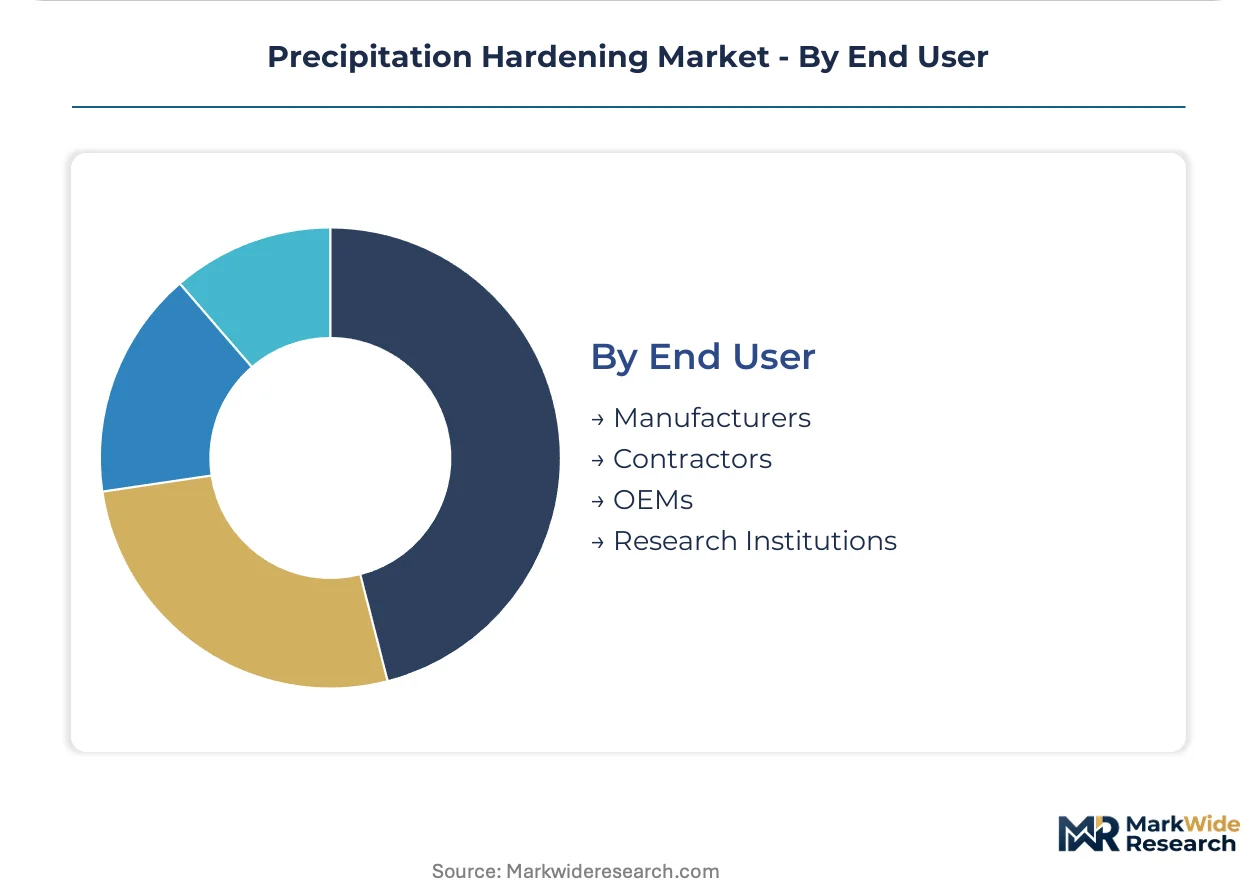
End User:
Supply concentration varies sharply by integration depth, with OEMs controlling specification development while contractors execute processing protocols.
- OEMs:Pratt & Whitney, Rolls-Royce, and Safran dictate aging cycle parameters through proprietary heat treatment specifications exceeding baseline AMS requirements.
- Manufacturers:Tier-two suppliers operate in-house vacuum furnaces for solution treatment while outsourcing precision aging to specialized service networks.
- Contractors:Heat treatment service providers in Wichita, Toulouse, and Hamburg manufacturing corridors consolidate multi-site contractual arrangements.
- Research Institutions:National laboratories and university materials science programs develop modified aging responses for additive-manufactured precipitation hardenable alloys.
OEMs retain specification authority; contractors absorb capacity execution risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial cluster's dense furnace network anchors European vacuum aging capacity, while Wichita's aerospace manufacturing corridor concentrates North American heat treatment infrastructure. These physical assets determine where precipitation hardening service procurement concentrates.
United States
Wichita's aerospace manufacturing corridor hosts dense Nadcap-accredited furnace clusters serving Pratt & Whitney and Spirit AeroSystems engine contracts. EPA NESHAP standards mandate regenerative thermal oxidizer retrofits on aging furnaces processing nickel alloys, with California and Texas facing the steepest state-level overlay requirements. The Pacific Northwest's titanium processing facilities supply Boeing's Everett and Renton assembly lines with AMS-certified structural brackets.
Germany
Stuttgart's automotive drivetrain manufacturers specify PH stainless steels for transmission shafts requiring torque density above 200 Nm/kg. REACH substance restrictions on hexavalent chromium plating accelerate substitution toward native corrosion-resistant precipitation-hardenable alloys. The Ruhr industrial cluster around Dortmund and Essen controls disproportionate European vacuum aging capacity, creating single-point vulnerability for continental supply security.
China
Shenyang's aero-engine manufacturing base drives demand for Inconel 718 turbine disk aging with full thermal history traceability. MIIT industrial standards govern heat treatment process validation for defense-critical components, with state-owned AVIC subsidiaries maintaining captive furnace networks. The Yangtze River Delta's precision fastener manufacturers source aging services for Ti-6Al-4V landing gear brackets serving COMAC C919 production.
India
Bangalore's aerospace cluster attracts heat treatment service providers establishing Nadcap-accredited facilities under Ministry of Defence indigenization mandates for fighter engine components. BIS certification requirements for aerospace-grade alloys align with DGFT import substitution programs targeting foreign dependency reduction. Hindustan Aeronautics Limited's Koraput and Nasik divisions contract overflow aging capacity to emerging specialized service networks.
Japan
Nagoya's automotive and aerospace manufacturing belt demands precision-controlled aging cycles for nickel superalloy fasteners. METI technology roadmaps emphasize domestic heat treatment capability retention for critical supply chain segments. Daido Steel's Nagoya facilities anchor regional precipitation hardening capacity for tier-one Toyota and Subaru component suppliers.
Precipitation Hardening Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with process-specific furnace assets. The market structure consolidates around Nadcap-accredited service networks, with mid-cap providers facing audit cycle compression that favors scale. Three archetypes dominate: global furnace footprint operators, integrated specialty alloy producers with captive aging capacity, and regional precision-aging specialists. Competitive dynamics center on multi-year sole-source contract capture and geographic proximity to aerospace manufacturing corridors.
Among UK-listed service providers, Bodycote plc occupies the global furnace footprint archetype, sustaining multi-site contractual arrangements with tier-one aerospace suppliers. Carpenter Technology represents the integrated specialty alloy producer model, anchoring North American demand through in-house vacuum arc remelting and subsequent aging capabilities. Daido Steel Co., Ltd. exemplifies the regional precision-aging specialist, competing on controlled thermal cycle management for nickel superalloy applications.
| Leading Market Players |
|---|
| Bodycote plc |
| Bluewater Thermal Solutions |
| Specialty Steel Treating, Inc. |
| Aalberts Surface Technologies |
| Paulo Heat Treating |
| Wallwork Heat Treatment Limited |
| Carpenter Technology |
| Daido Steel Co., Ltd. |
| Haynes International |
| Others |
Value Network & Pricing Analysis
Rhine-Alpine Corridor freight costs fluctuate with fuel surcharges and carbon border adjustments, compressing margins for German heat treatment service providers while amplifying price premiums for Nadcap-accredited capacity in aerospace manufacturing clusters.
Pricing Analysis
Volume-discount tiering structures separate multi-year sole-source contracts from spot-market transactions. Three-tier pricing stratifies across AMS-certified premium cycles, Nadcap-accredited standard processing, and non-flight-critical economy aging. Price differentiation hinges on certification grade and furnace uniformity survey documentation. Pricing pressure intensifies as nickel-base superalloy service providers absorb LME contract volatility locked into annual fixed-rate agreements. Automotive drivetrain manufacturers exhibit highest price sensitivity; aerospace engine OEMs prioritize thermal history traceability over unit cost.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day payment terms strain working capital for mid-cap heat treatment providers competing against Bodycote's balance sheet scale. Geographic supply concentration centers on Germany, the United States, and Japan. Raw material dependencies include nickel cathodes, titanium sponge, and specialty alloy feedstocks from vacuum arc remelting operations. Single-source vulnerability persists in vacuum furnace control systems sourced from Austrian and German equipment manufacturers. Distribution runs through Nadcap-accredited service networks with direct OEM contractual relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics is reshaping competitive positioning as digital thermal monitoring systems create interoperability standards that favor furnace fleet operators with unified data architectures.
For Market Incumbents: Build certification moats through accelerated Nadcap accreditation for additive-manufactured alloy aging protocols. Expand vacuum furnace clusters in India's Bangalore aerospace corridor to capture Ministry of Defence indigenization mandates. Deepen backward integration into vacuum arc remelting to secure specialty alloy feedstock margins against nickel price volatility. For New Entrants and Emerging Players: Build out electrification thermal management capacity for electric vehicle battery enclosure manufacturers specifying precipitation-hardened aluminum alloys. Target India's emerging defense-aerospace cluster where Nadcap-accredited capacity scarcity creates first-mover positioning. Deploy ISO 14001-integrated carbon-accounted thermal processing as a premium service tier for European supply chains. For Investors and Strategic Acquirers: Regional precision-aging specialists with proprietary thermal cycle databases represent attractive acquisition targets as machine learning-enabled microstructure prediction commoditizes empirical aging curve development. Long-term viability favors service providers with captive furnace networks in aerospace manufacturing corridors. Monitor AMS specification evolution for powder bed fusion feedstocks as an inflection indicator for modified aging protocol demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Arc Remelting | Carpenter Technology anchors North American specialty alloy supply through captive remelting and aging capabilities. |
| Nadcap Accreditation Expansion | Bodycote plc sustains multi-site aerospace contracts through continuous furnace uniformity survey compliance. |
| Carbon-Accounted Thermal Processing | ISO 14001 convergence opens premium pricing tiers for European supply chain decarbonization mandates. |
| Machine Learning-Enabled Aging Models | Aerospace tier-one suppliers compress qualification timelines from empirical curve development to physics-informed neural networks. |
| India Defense Localization Facilities | Ministry of Defence indigenization mandates create first-mover advantage for accredited capacity near Bangalore clusters. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with heat treatment service executives, aerospace procurement managers, and metallurgical technicians; and secondary validation through AMS specification databases, EPA NESHAP regulatory filings, and SEC disclosures from listed specialty alloy producers. Bottom-up capacity modeling across Nadcap-accredited furnace clusters triangulated against top-down aerospace and automotive production forecasts.
Forecast inputs incorporated material type segmentation by alloy system, application criticality tiers, and supply chain integration depth across the projection horizon. CAGRs derived from historical capacity utilization trends and specification-driven demand elasticity. Industry-specific inputs included LME nickel price volatility coefficients and evolving AMS certification requirements for additive-manufactured feedstocks.
The forecast holds incumbent behavior within observed patterns; aggressive furnace capacity expansion by state-backed Chinese aero-engine subsidiaries would shift outcomes. Macroeconomic deviation, regulatory acceleration of REACH substance restrictions, or breakthroughs in directed energy deposition substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Nitinol Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market