
 Europe Aluminum Casting Market | 2026-2036
Europe Aluminum Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aluminum Casting Market Foresight
OEM supply channels for passenger vehicle powertrain housings is rewriting procurement geography across Central Europe. Constellium leverages its integrated rolling and casting footprint to dominate aerospace-grade output from French and German plants. Rheinmetall Automotive sustains captive foundry relationships with German transmission builders through specialized gravity die capabilities. GF Casting Solutions anchors high-pressure die casting capacity in Austria and Switzerland for premium drivetrain customers.
Europe aluminum casting encompasses molten aluminum alloy poured into shaped molds to produce near-net-shape components, typically using alloys with 7-12% silicon content for improved fluidity and 0.3-0.5% magnesium for tensile strength, serving industries where weight reduction directly improves energy efficiency. Die casting commands the largest share of European output value due to its dimensional precision in high-volume automotive transmission cases and engine blocks. Sand casting retains structural importance for low-volume aerospace prototypes and custom building hardware where tooling amortization would overwhelm unit economics. High pressure die casting leads technology adoption as OEMs specify thinner-walled structural components to offset battery weight in electrified platforms.
The European Green Deal and REACH chemical compliance frameworks mandate lifecycle carbon accounting that favors recycled aluminum feedstock, while ECHA scrutiny of process chemicals shapes foundry investment timelines. CE marking under the EU Machinery Directive governs casting equipment safety and constrains retrofit economics for smaller operators. Stakeholders must monitor how the EU Carbon Border Adjustment Mechanism reshapes scrap aluminum sourcing economics relative to primary metal imports.
Market Dynamics
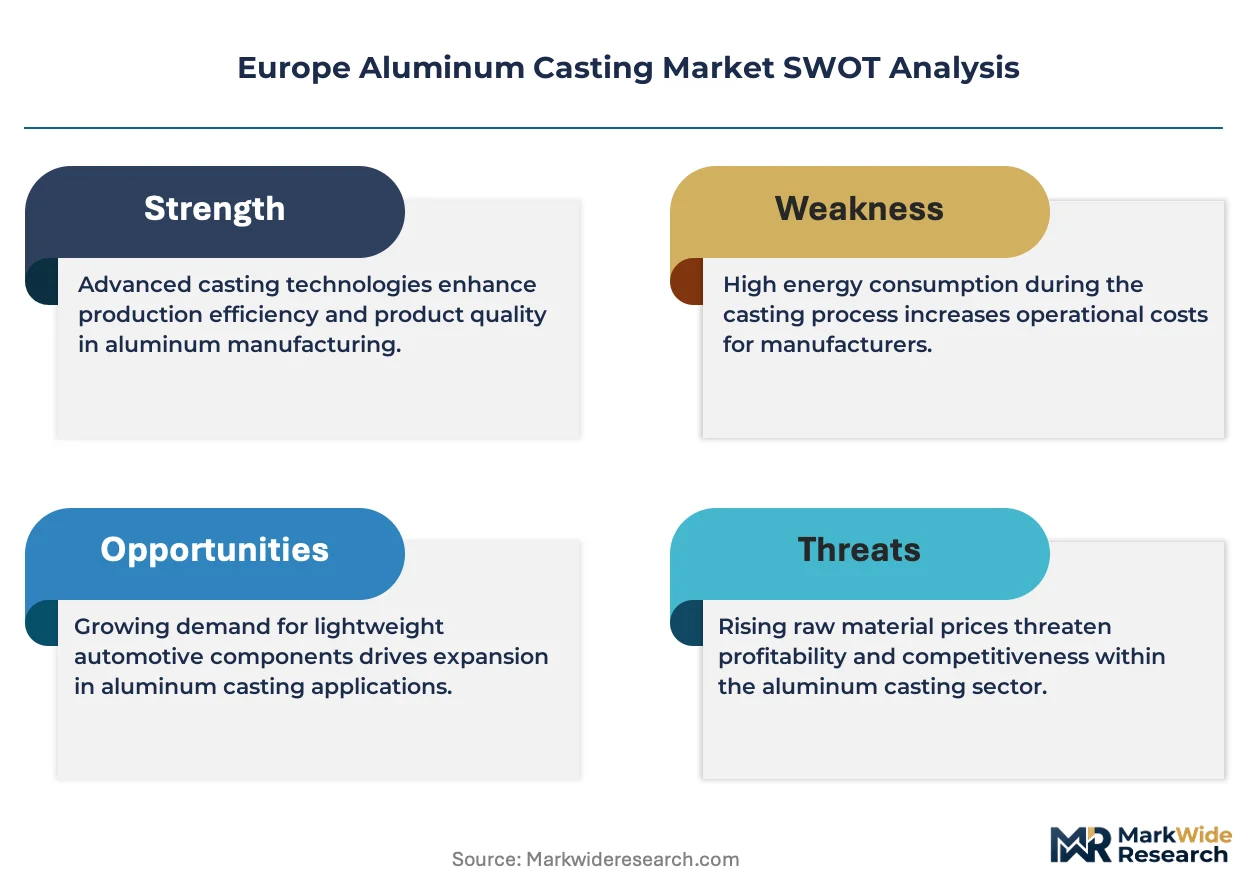
High-pressure die casting is virtualizing traditional gravity and sand casting methods as European automotive OEMs specify thinner-walled structural components to offset battery weight in electrified platforms. The EU Green Deal's lifecycle carbon accounting mandates are simultaneously reshaping feedstock sourcing economics toward recycled aluminum.
Growth Catalysts
- EU Green Deal carbon mandates:Lifecycle accounting requirements favor recycled aluminum feedstock, redirecting foundry procurement toward secondary metal streams and scrap-sourcing infrastructure.
- Powertrain electrification:Battery electric vehicle platforms require lightweight housings for inverters, battery trays, and thermal management modules that high-pressure die casting delivers.
- F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases eliminate competing lightweighting materials in HVAC and thermal systems, expanding aluminum casting's addressable applications.
Market Restraints
- Primary aluminum price volatility:Energy-intensive smelting operations expose European foundries to electricity cost swings that compress margin predictability on fixed-price OEM contracts.
- Scrap supply concentration:Germany, France, and Italy control the majority of Europe's post-consumer aluminum scrap collection and sorting infrastructure, creating sourcing bottlenecks for peripheral markets.
- REACH chemical compliance:ECHA scrutiny of release agents, coatings, and flux additives extends qualification timelines and restricts process chemistry options for smaller foundries.
Strategic Opportunities
- Poland and Czech Republic manufacturing corridors:Underpenetrated high-pressure die casting capacity in Central Europe offers greenfield expansion sites proximate to expanding OEM assembly plants.
- Heat exchanger micro-channel technology:Convergence of additive manufacturing for conformal cooling channels with conventional die casting enables thermal performance gains in electrified powertrains.
- CSRD disclosure requirements:Corporate Sustainability Reporting Directive mandates create competitive differentiation for foundries with verified Scope 3 emissions data and closed-loop recycling certifications.
Industry Challenges
- Die casting simulation expertise:Shortage of engineers proficient in MAGMAsoft and FLOW-3D casting simulation software extends product development cycles and increases tooling rework rates.
- CE marking retrofit costs:EU Machinery Directive safety upgrades for legacy casting equipment strain capital allocation for mid-tier operators with aging machine parks.
- Multi-material joining certification:Aluminum-steel and aluminum-composite hybrid structures require new adhesive bonding and mechanical fastening qualifications that lack standardized test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aluminum Casting Market |
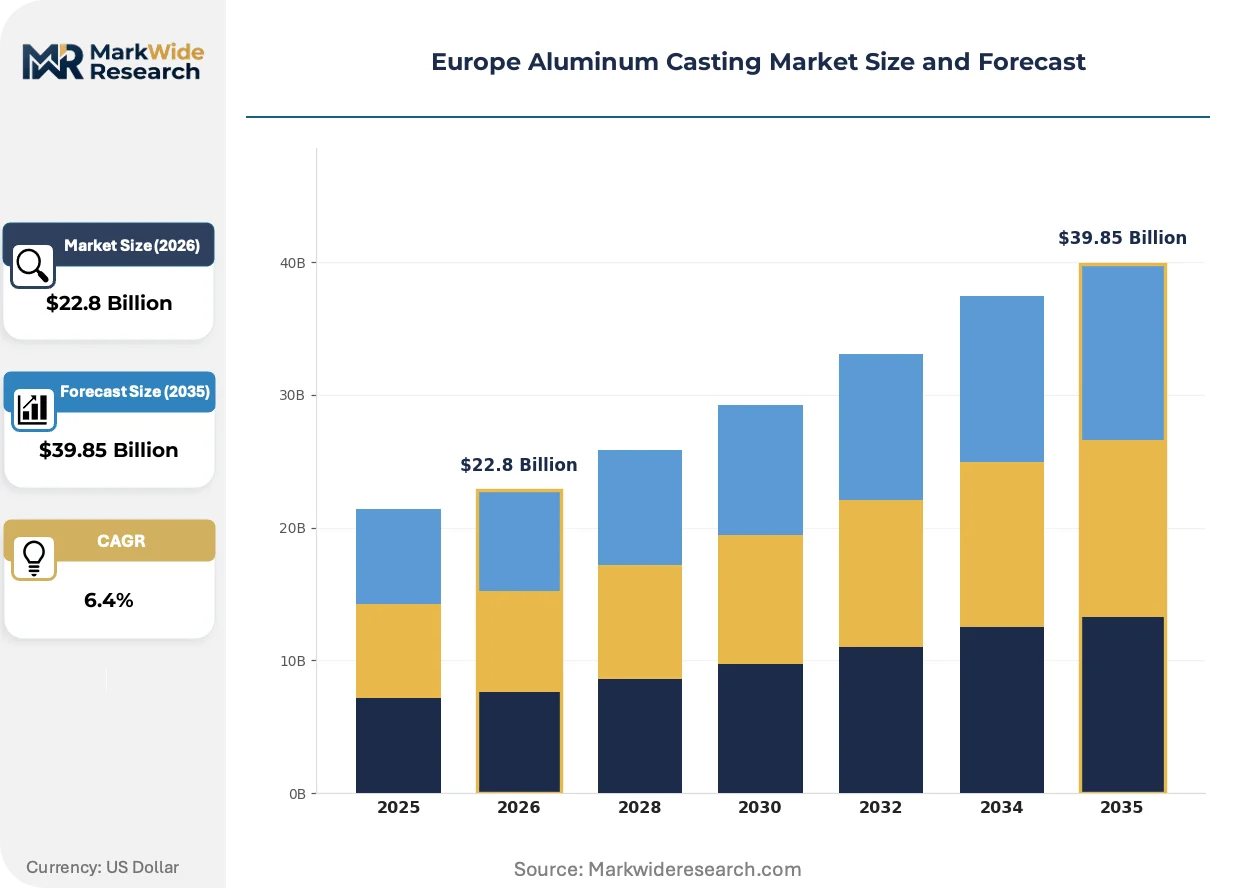
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die Casting, Sand Casting, Permanent Mold Casting, Investment Casting End User: Aerospace, Automotive, Building & Construction, Electrical Technology: High Pressure Die Casting, Low Pressure Die Casting, Gravity Die Casting, Squeeze Casting Application: Structural Components, Engine Parts, Transmission Cases, Decorative Parts |
| Companies Covered | Constellium, Rheinmetall Automotive, GF Casting Solutions, Nemak, Martinrea Honsel, Alcoa Corporation, Gränges AB, RYOBI Aluminium Casting, Endurance Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aluminum Casting Market Shifts & Advancements
Digital twin technology and real-time process monitoring are compressing development cycles for complex castings. Foundries are integrating sensor networks with predictive algorithms to reduce scrap rates and accelerate qualification timelines for automotive programs.
Large structural die casting is virtualizing traditional multi-part assemblies as Tesla's gigacasting approach diffuses through European OEM engineering departments. BMW and Volkswagen have accelerated adoption of 6,000-ton-plus clamping force machines for rear underbody and battery housing production. This consolidation is virtualizing stamped-and-welded component supply chains while demanding new alloy formulations with enhanced crashworthiness.
REACH authorization procedures are tightening control over chromium-based conversion coatings and specific release agents used in gravity die casting. The industrial consequence is accelerated qualification of silane-based and zirconium pretreatment alternatives that maintain corrosion resistance without hexavalent chromium. Italian and Spanish foundries serving building hardware and marine applications face the most compressed substitution timelines.
Automotive OEMs are consolidating supplier bases around foundries offering integrated machining and surface treatment capabilities. Tier-1 purchasing departments now specify single-source accountability for casting-to-finished-component delivery, displacing traditional tier-2 machining specialists. This vertical integration preference is most visible in Germany's automotive corridor where transmission and axle housing contracts increasingly bundle finishing operations.
Europe Aluminum Casting Market Segmentation
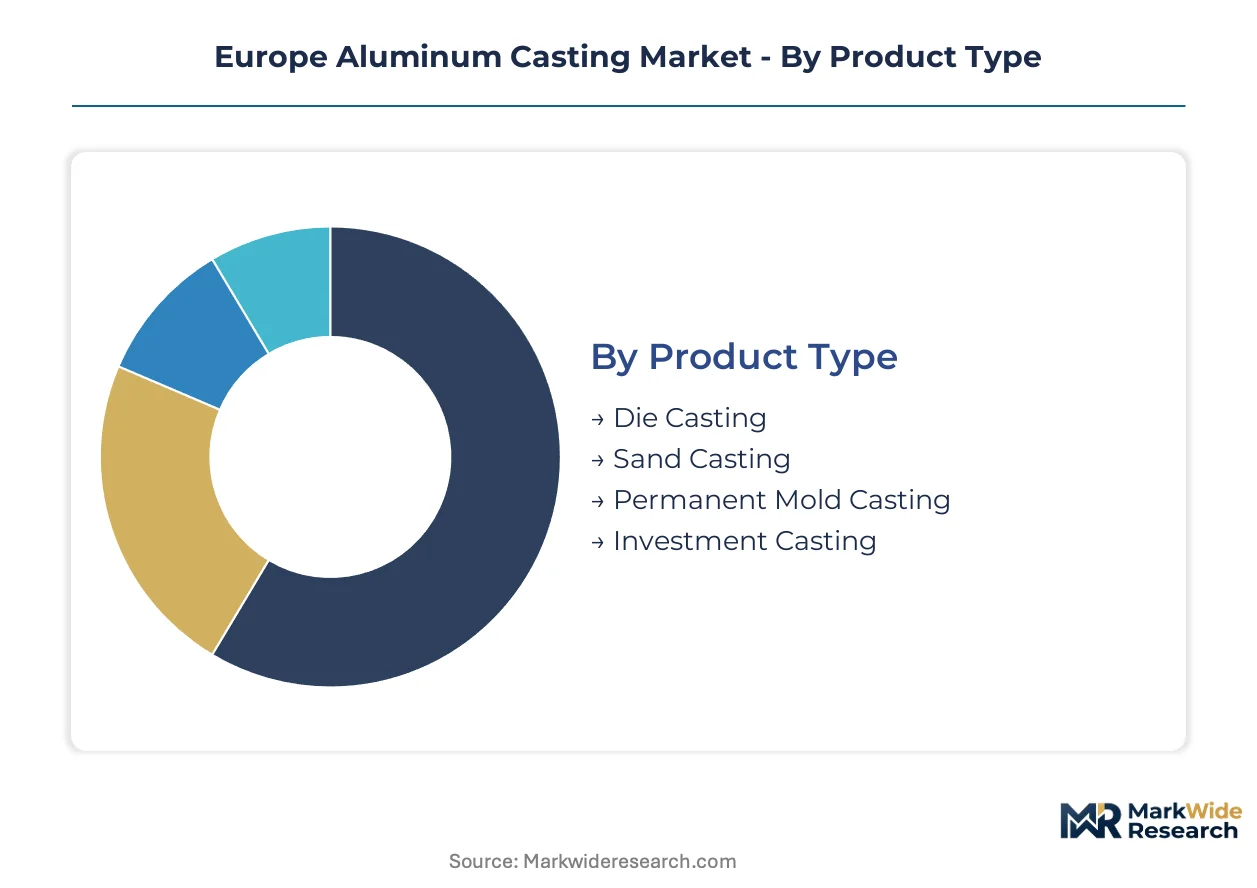
Segmentation in the Europe aluminum casting market reveals how process economics and end-use specifications fragment procurement channels. Understanding these divides explains why German automotive OEMs source differently from French aerospace contractors or Italian building hardware distributors.
Product Type:
Mature high-volume processes dominate automotive procurement, while emerging methods capture specialized aerospace and prototype demand.
- Die Casting:Molten aluminum alloy injected into hardened steel dies under 1,000-4,000 bar pressure achieves dimensional tolerances of ±0.1 mm for transmission cases and engine blocks. German and Czech automotive OEMs concentrate procurement here for electrified powertrain housings where wall thickness below 2 mm offsets battery weight. The EU Green Deal's recycled aluminum mandates favor die casting's closed-loop scrap recovery economics.
- Sand Casting:Bonded silica molds accommodate single-use geometries for low-volume aerospace prototypes and custom architectural hardware. Italian foundries serving marine and building applications retain this method where tooling amortization would overwhelm unit economics on batches below 500 pieces. REACH chemical scrutiny of furan resins and bentonite binders extends qualification timelines for smaller operators.
- Permanent Mold Casting:Reusable metal molds balance surface finish and cost for medium-volume electrical enclosures and industrial components.
- Investment Casting:Ceramic shell processes deliver near-net-shape precision for turbine blades and aerospace structural nodes requiring complex internal passages.
Die casting handles the majority of throughput; investment casting is expanding most quickly on share as aerospace OEMs consolidate supplier bases.
End User:
Cost tier differentiation separates premium-certified aerospace demand from price-sensitive building hardware procurement.
- Automotive:OEM powertrain and structural programs specify high-pressure die cast aluminum for battery trays, inverter housings, and motor end caps. Volkswagen and BMW assembly plants in Germany, Austria, and the Czech Republic drive volume concentration. The F-Gas Regulation phase-down eliminates competing lightweight materials in HVAC thermal management modules.
- Aerospace:Constellium and Aubert & Duval serve Airbus and Safran with aerospace-grade alloys meeting AMS specifications for wing ribs, landing gear components, and engine mounts. French and German plants dominate output due to integrated rolling and casting footprints required for traceability certification.
- Building & Construction:Architectural hardware and marine fittings demand corrosion-resistant finishes with lower mechanical performance thresholds than transportation applications.
- Electrical:Switchgear housings and busbar enclosures prioritize thermal conductivity and electromagnetic shielding over structural load-bearing capacity.
Automotive commands the steepest expansion trajectory; aerospace maintains the highest margin tier through certification barriers.
Technology:
Volume concentration versus margin structure differentiates mass-production methods from specialized precision processes.
- High Pressure Die Casting:Clamping forces exceeding 6,000 tons enable single-piece rear underbody and battery housing castings that virtualize stamped-and-welded assemblies. BMW and Volkswagen engineering departments in Munich and Wolfsburg accelerated adoption following Tesla's gigacasting diffusion. New alloy formulations with enhanced crashworthiness absorb development resources.
- Low Pressure Die Casting:Controlled metal rise from pressurized crucibles produces porosity-free wheels and suspension knuckles for premium vehicle platforms. Austrian and Swiss foundries anchor capacity for drivetrain customers requiring X-ray inspection certification.
- Gravity Die Casting:Rheinmetall Automotive sustains captive foundry relationships with German transmission builders through specialized tooling for clutch housings and valve bodies.
- Squeeze Casting:Solidification under mechanical pressure yields fine microstructures for high-strength structural nodes in hybrid material assemblies.
High pressure die casting captures the dominant share; squeeze casting is gaining share fastest as multi-material joining requirements intensify.
Application:
Customer type segmentation separates OEM direct procurement from tiered supplier channels for finished components.
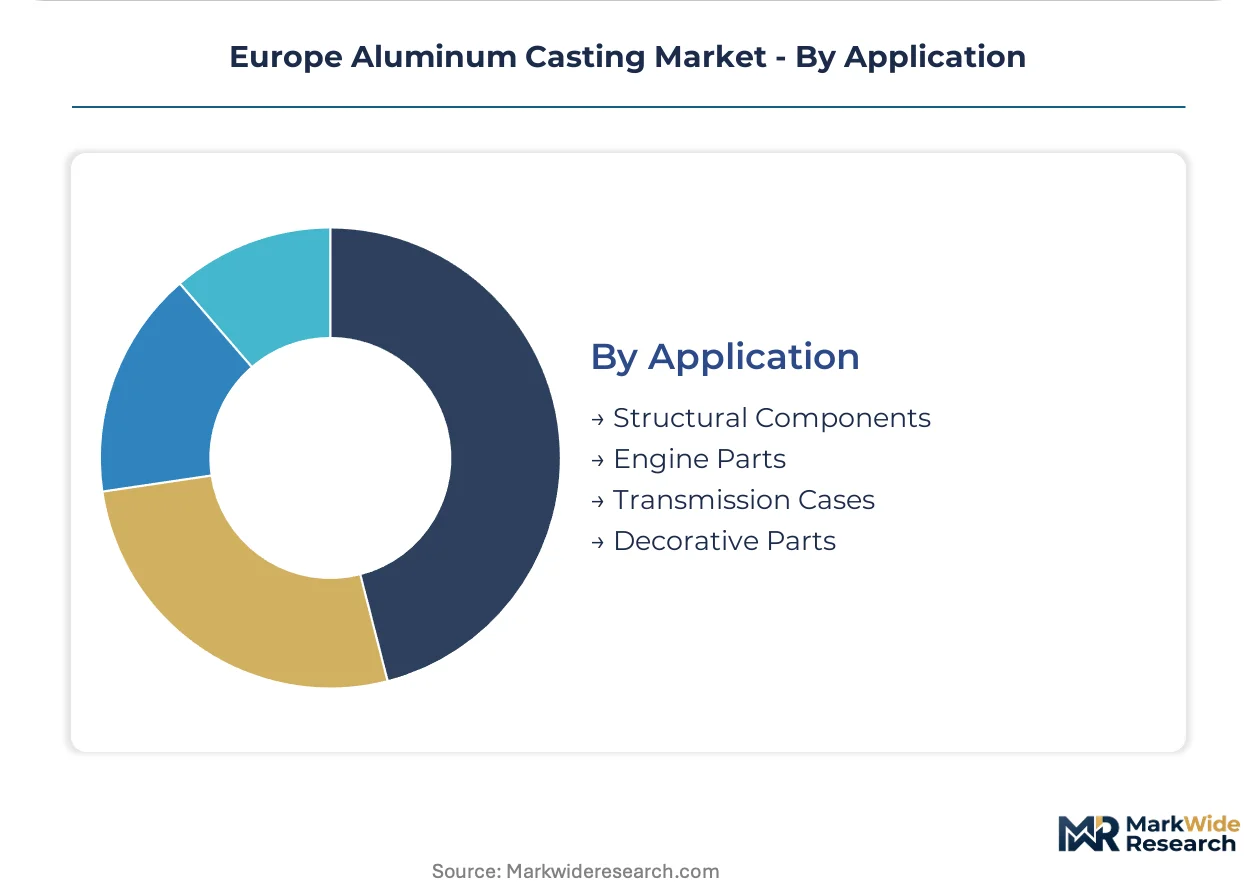
- Structural Components:Large die castings for vehicle underbodies and battery enclosures consolidate multi-part assemblies into single castings. German OEMs specify these for electric platforms where weight reduction directly improves range certification under WLTP testing protocols.
- Engine Parts:Cylinder heads, blocks, and oil pans retain sand and gravity die casting methods for thermal fatigue resistance. Italian and Spanish foundries serve aftermarket and industrial engine rebuilders with shorter qualification cycles than OEM programs.
- Transmission Cases:High-pressure die casting delivers dimensional precision for dual-clutch and electric axle gearbox housings.
- Decorative Parts:Architectural hardware and consumer product castings prioritize surface finish and anodizing compatibility over mechanical properties.
Structural components absorb the majority of new capacity investment; transmission cases face displacement risk as electrification reduces gearbox complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foundries extract 15-20% price premiums over Polish and Czech counterparts for equivalent high-pressure die castings, reflecting certification depth and proximity to BMW and Volkswagen engineering centers. This pricing-power asymmetry shapes investment flows across Central Europe.
Germany
Bavaria and Baden-Württemberg concentrate demand for battery tray and inverter housing castings from BMW, Mercedes-Benz, and Porsche electrification programs. The EU Green Deal's lifecycle carbon accounting mandates favor recycled aluminum feedstock, redirecting foundry procurement toward secondary metal streams. Munich and Stuttgart engineering corridors specify thinner-walled structural components to offset battery weight in electric platforms.
France
Airbus and Safran procurement of wing ribs, landing gear components, and engine mounts drives aerospace-grade alloy demand through Constellium and Aubert & Duval. REACH authorization procedures tighten control over chromium-based conversion coatings, accelerating qualification of silane-based pretreatment alternatives. The Toulouse and Nantes aerospace clusters require integrated rolling and casting footprints for traceability certification.
Italy
Building hardware and marine fittings demand corrosion-resistant finishes with lower mechanical performance thresholds than transportation applications. ECHA scrutiny of furan resins and bentonite binders extends qualification timelines for smaller sand casting operators. The Lombardy and Veneto foundry belts serve architectural and aftermarket engine rebuilders with shorter qualification cycles than OEM programs.
Poland
Underpenetrated high-pressure die casting capacity offers greenfield expansion sites proximate to expanding OEM assembly plants. CE marking under the EU Machinery Directive governs casting equipment safety and constrains retrofit economics for smaller operators. The Silesian and Greater Poland manufacturing corridors attract transmission and axle housing contracts from German tier-1 suppliers.
Czech Republic
Škoda Auto and Hyundai Motor Manufacturing procurement of transmission cases and structural components drives high-pressure die casting adoption. The F-Gas Regulation phase-down eliminates competing lightweight materials in HVAC thermal management modules, expanding aluminum casting's addressable applications. The Mladá Boleslav and Ostrava automotive clusters concentrate supplier relationships with Austrian and Swiss foundry capacity.
Europe Aluminum Casting Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on narrower process expertise. The European aluminum casting market structures around three tiers: multinational rolled-products conglomerates with integrated casting footprints, automotive-focused high-pressure die casting specialists, and regional sand casting operators serving building and marine applications. Consolidation pressure intensifies as OEMs consolidate supplier bases around foundries offering integrated machining and surface treatment capabilities. Dominant competitive moves include captive foundry relationships for transmission builders and greenfield capacity expansion in Central European manufacturing corridors.
Among France and Germany-based integrated producers, Constellium and Rheinmetall Automotive exemplify divergent strategic positions. Constellium occupies the aerospace-grade alloy tier through combined rolling and casting operations. Rheinmetall Automotive sits within the automotive powertrain specialist tier, sustaining captive foundry relationships with German transmission builders. GF Casting Solutions, with Swiss and Austrian operational presence, anchors high-pressure die casting capacity for premium drivetrain customers. These three represent distinct archetypes: rolled-products integrator, automotive captive supplier, and precision die casting specialist.
| Leading Market Players |
|---|
| Constellium |
| Rheinmetall Automotive |
| GF Casting Solutions |
| Nemak |
| Martinrea Honsel |
| Alcoa Corporation |
| Gränges AB |
| RYOBI Aluminium Casting |
| Endurance Technologies |
| Others |
Supply & Pricing Matrix
Bavaria's automotive manufacturing corridor concentrates high-pressure die casting capacity within 150 kilometers of BMW and Munich engineering centers, creating localized pricing power that German foundries exploit to extract 15-20% premiums over Polish and Czech counterparts for equivalent transmission housings and battery trays.
Pricing Analysis
The customization-premium spread between configured-to-order aerospace castings and standard automotive die castings defines European aluminum pricing architecture. Contract-based long-term offtake agreements dominate automotive procurement, with price differentiation driven by certification depth and geographic proximity to OEM engineering centers. Cost compression in Central European standard-grade castings is intensifying because German tier-1 suppliers are consolidating volumes across fewer foundries. Tier-2 machining specialists show highest price sensitivity as OEMs bundle finishing operations into single-source casting contracts.
Supply Chain Analysis
Upstream feedstock dynamics center on Germany, France, and Italy controlling Europe's post-consumer aluminum scrap collection and sorting infrastructure. Secondary aluminum smelters in these markets draw from established scrap-sourcing networks, while peripheral foundries face feedstock bottlenecks. The supply chain rests on primary aluminum ingot, silicon alloying additives, and magnesium strengthening agents. Single-source vulnerability concentrates in German automotive OEM direct procurement channels. Distribution runs through tier-1 supplier consolidation toward captive foundry relationships and integrated machining-to-finished-component delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe aluminum casting sits in early-cycle recovery as automotive electrification programs accelerate procurement of lightweight structural components for battery electric platforms.
For Market Incumbents: Entrench defensive positioning through backward integration into scrap-sourcing infrastructure and captive machining capacity. Rheinmetall Automotive-style foundry relationships with transmission builders provide template for locking out tier-2 competitors. CE marking retrofit requirements for legacy equipment present margin pressure point that scale operators can absorb while mid-tier competitors face capital constraints. For New Entrants and Emerging Players: Poland's Silesian and Greater Poland manufacturing corridors represent the most penetrable entry point for greenfield high-pressure die casting capacity proximate to expanding OEM assembly plants. Czech Republic transmission case contracts from Škoda and Hyundai suppliers offer secondary wedge. Go-to-market angle should emphasize closed-loop recycling certifications that satisfy CSRD disclosure requirements for German automotive procurement departments. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because OEM supplier base rationalization favors foundries with integrated machining and verified Scope 3 emissions data. Target acquisition archetype: mid-cap Central European die casting specialists with underutilized 4,000-ton press capacity and existing relationships with Austrian or Swiss tier-1 suppliers. Signal to watch is BMW and Volkswagen engineering department adoption rates for 6,000-ton-plus gigacasting machines as inflection indicator for structural component demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Sorting | EU Green Deal lifecycle mandates favor foundries controlling secondary metal feedstock streams. |
| High-Pressure Die Casting Capacity Expansion | 6,000-ton press installations in Poland and Czech Republic capture OEM electrification procurement. |
| CSRD-Compliant Emissions Certification | Verified Scope 3 data creates competitive differentiation for German automotive contract bidding. |
| Integrated Machining Capability Addition | Single-source casting-to-finished-component delivery displaces traditional tier-2 machining specialists. |
| Silane-Based Pretreatment Qualification | REACH-compliant alternatives to chromium coatings maintain corrosion resistance for Italian marine applications. |
Research Methodology
Desk research of trade association filings, EU regulatory databases, and automotive production statistics preceded structured interviews with foundry operations directors, OEM platform engineers, tier-1 supplier procurement managers, and scrap metal trading specialists. Secondary validation drew from ECHA chemical authorization records, CE marking compliance directories, and customs data on aluminum alloy trade flows. Bottom-up capacity modeling triangulated against top-down OEM procurement estimates across the analysis window.
Assumptions held fixed include EU Green Deal carbon accounting enforcement timelines and F-Gas Regulation phase-down schedules, while variables tested included primary aluminum price volatility bands and scrap supply concentration scenarios. Segmentation dimensions encompassed process technology, end-use industry, and regional production cluster. CAGRs derived from volume-weighted average of segment growth trajectories, with electrification penetration rates and battery platform adoption curves as key forecast inputs.
Practitioners should monitor ECHA chemical authorization timelines and EU Carbon Border Adjustment Mechanism implementation signals for early indicators of feedstock sourcing economics shifts. Cross-checking against IHS Markit vehicle production databases and OEM electrification program announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Corrosion Resistant Alloys Market
Advanced Alloys
Nitinol Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Chromium Carbide Overlay Plate Market
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Quenched and Tempered Steel Market
Advanced Alloys
Forgings Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market