
 Retail Bubble Tea Kits Market | 2026-2036
Retail Bubble Tea Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Bubble Tea Kits Market Analytics
Modular kit configurations with interchangeable flavor pods and separate tapioca pearl sachets is expanding consumer choice across preparation skill levels. ORBITEL INTERNATIONAL leverages its supply chain scale to dominate bulk retail channels. Buddha Bubbles Boba specializes in premium ingredient sourcing that sustains above-average margins. The Bubble Tea Club competes through direct-to-consumer subscription models that control recurring revenue.
Retail bubble tea kits are pre-packaged assemblies containing tea bases, tapioca pearls, sweeteners, and straws designed for at-home preparation of bubble tea beverages, typically requiring boiling water and five to fifteen minutes of active preparation time. These kits serve the dual purpose of replicating café-style experiences while eliminating per-unit costs of commercial preparation. DIY Kits lead volume shipments among product types as novice consumers seek guided entry points with pre-measured ingredients. Online Retail captures the fastest growth trajectory within distribution channels, driven by algorithmic discovery and influencer-driven unboxing content. Specialty Shops retain margin concentration through curated inventory and staff-assisted selection.
The FDA regulates food-contact substances and labeling claims for imported tea components and tapioca starch products entering the United States. The USDA's National Organic Program shapes premium positioning for kits certified with organic tea bases and non-GMO tapioca. State-level cottage food laws in California and New York create variable thresholds for small-batch kit assemblers selling through farmers markets and local retail. Stakeholders must monitor evolving platform commerce regulations and ingredient provenance disclosure requirements as consumer litigation risk around allergen labeling intensifies.
Market Dynamics
Home beverage preparation has shifted from novelty to habit among millennial and Gen-Z households, creating sustained pull for guided-format kits that reduce trial-and-error waste while delivering café-equivalent outcomes.
Growth Catalysts
- FDA Food-Contact Substance Oversight:Stricter documentation requirements for imported tapioca starch and tea packaging are filtering out non-compliant suppliers, concentrating shelf space among verified assemblers.
- Algorithmic Discovery Engines:TikTok and Instagram recommendation systems surface unboxing and preparation content to novice users, collapsing customer acquisition costs for direct-to-consumer entrants.
- Modular Flavor Pod Systems:Interchangeable tea bases and pearl sachets let households customize sweetness, caffeine levels, and texture without purchasing multiple complete kits.
Market Restraints
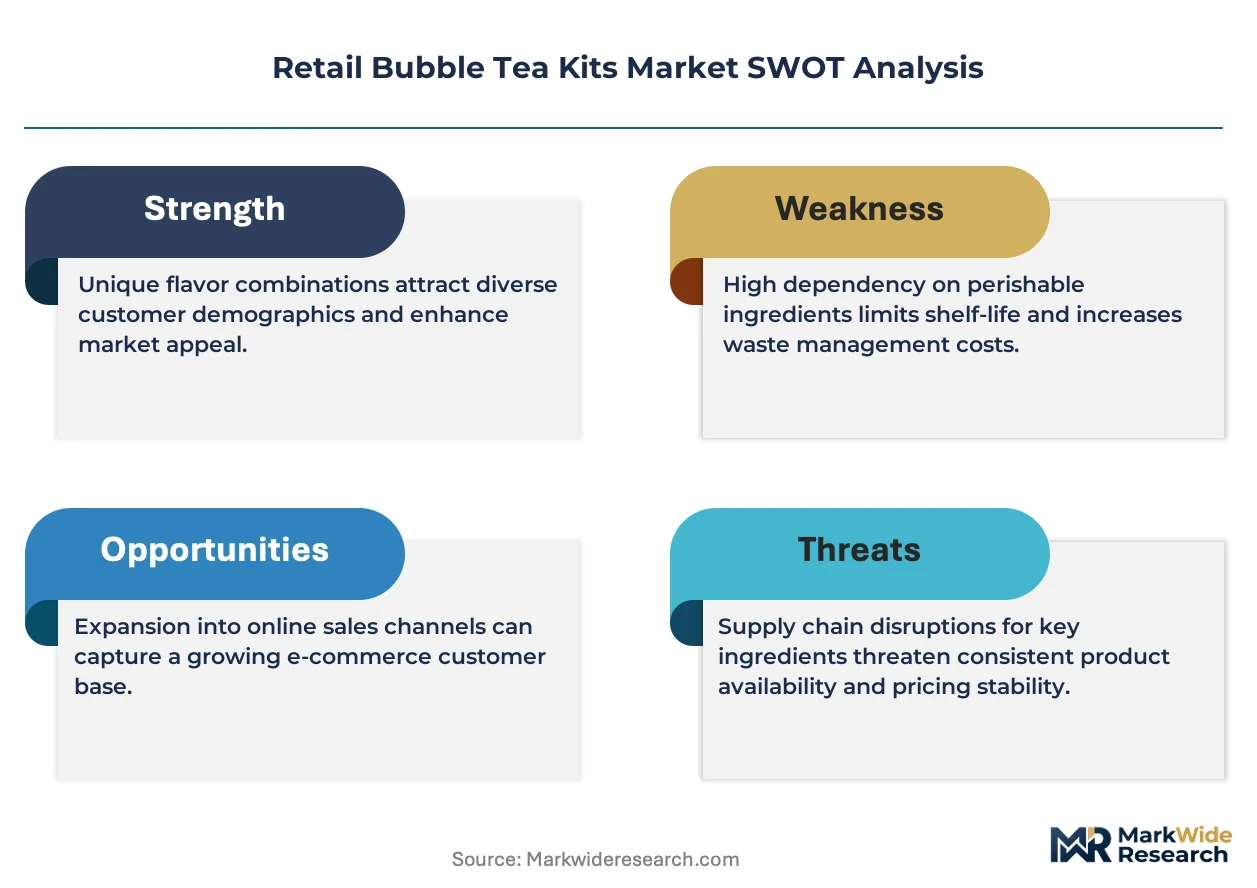
- Cassava Price Volatility:Tapioca pearl input costs fluctuate with Southeast Asian harvest cycles and starch export quotas, compressing margins for kit assemblers locked into fixed retail pricing.
- Single-Origin Supply Concentration:Premium black tea bases depend heavily on Taiwanese and Sri Lankan estates, exposing assemblers to climate disruption and freight rate spikes on the Asia-North America lane.
- Refrigerated Pearl Shelf-Life Constraints:Pre-cooked tapioca degrades within 48 hours of opening, limiting subscription box economics and forcing frequent replenishment cycles that increase logistics costs.
Strategic Opportunities
- USDA Organic Certification Pathway:The National Organic Program creates premium positioning for tea bases and non-GMO tapioca, commanding 30-40% price premiums in specialty retail channels.
- Specialty Shop Channel Expansion:Curated inventory with staff-assisted selection captures margin concentration unavailable through mass retail, particularly in urban markets with established Asian diaspora communities.
- AI-Formulated Flavor Matching:Machine learning systems that correlate consumer preference data with ingredient combinations are converging with small-batch production to enable hyper-localized kit configurations.
Industry Challenges
- Allergen Labeling Litigation Exposure:FDA enforcement actions against mislabeled cassava-derived ingredients are intensifying, requiring assemblers to validate supply chain documentation or face recall liability.
- Cross-Border E-Commerce Platform Compliance:Amazon and Shopify policy changes on food-contact materials documentation create variable thresholds that delay listing approvals and freeze inventory capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Bubble Tea Kits Market |
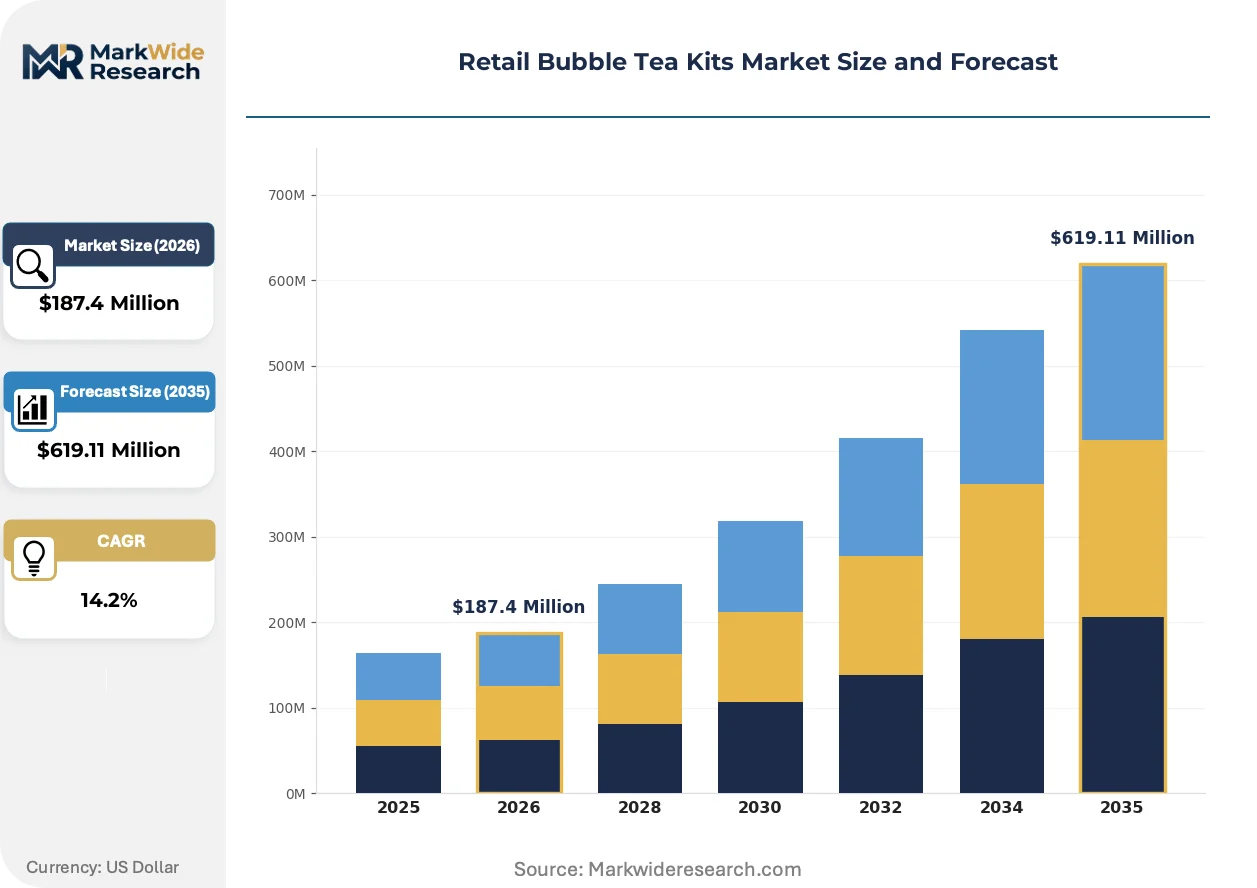
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Kits, Advanced Kits, DIY Kits, Premium Kits Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops Customer Type: Individual Consumers, Cafes, Restaurants, Event Planners Packing Type: Single-Serve Packs, Multi-Packs, Bulk Packages, Gift Sets |
| Companies Covered | ORBITEL INTERNATIONAL, BUBBLE TEA HOUSE COMPANY, Boba Barista, Locca Bubble Tea, Bubble Tea Supply, THE TEASHED, The Bubble Tea Club, Buddha Bubbles Boba, BOBA CHiC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Bubble Tea Kits Market Evolving Landscape
Preparation automation and ingredient transparency are reshaping how households engage with at-home beverage kits, shifting competition from flavor replication to trust architecture and time-to-consume metrics.
Compostable straws and sachets derived from polylactic acid and bamboo fiber are converging with municipal composting infrastructure expansion to eliminate single-use plastic guilt among environmentally conscious purchasers. Premium kit assemblers in California and Washington State have adopted these materials as default specifications. The structural consequence is a bifurcation between sustainability-certified entrants and legacy plastic-dependent brands facing channel exclusion.
The FDA's evolving oversight of imported food-contact packaging materials is compressing supplier qualification timelines while expanding documentation burdens for tapioca starch and tea component importers. Small-batch assemblers without dedicated regulatory affairs functions are outsourcing compliance to third-party certifiers. Direct-to-consumer subscription models bear disproportionate impact, as their just-in-time import patterns offer limited buffer for customs holds.
Social commerce discovery has displaced search-based purchasing for first-time kit buyers, with algorithmic feeds replacing keyword queries as the dominant acquisition channel. Influencer-driven unboxing content on short-form video platforms now determines trial rates among Gen-Z households. This behavioral shift concentrates marketing spend on content creation and creator partnerships rather than traditional retail slotting allowances, with visibility clustering in Los Angeles, New York, and Toronto metropolitan areas.
Retail Bubble Tea Kits Market Segmentation
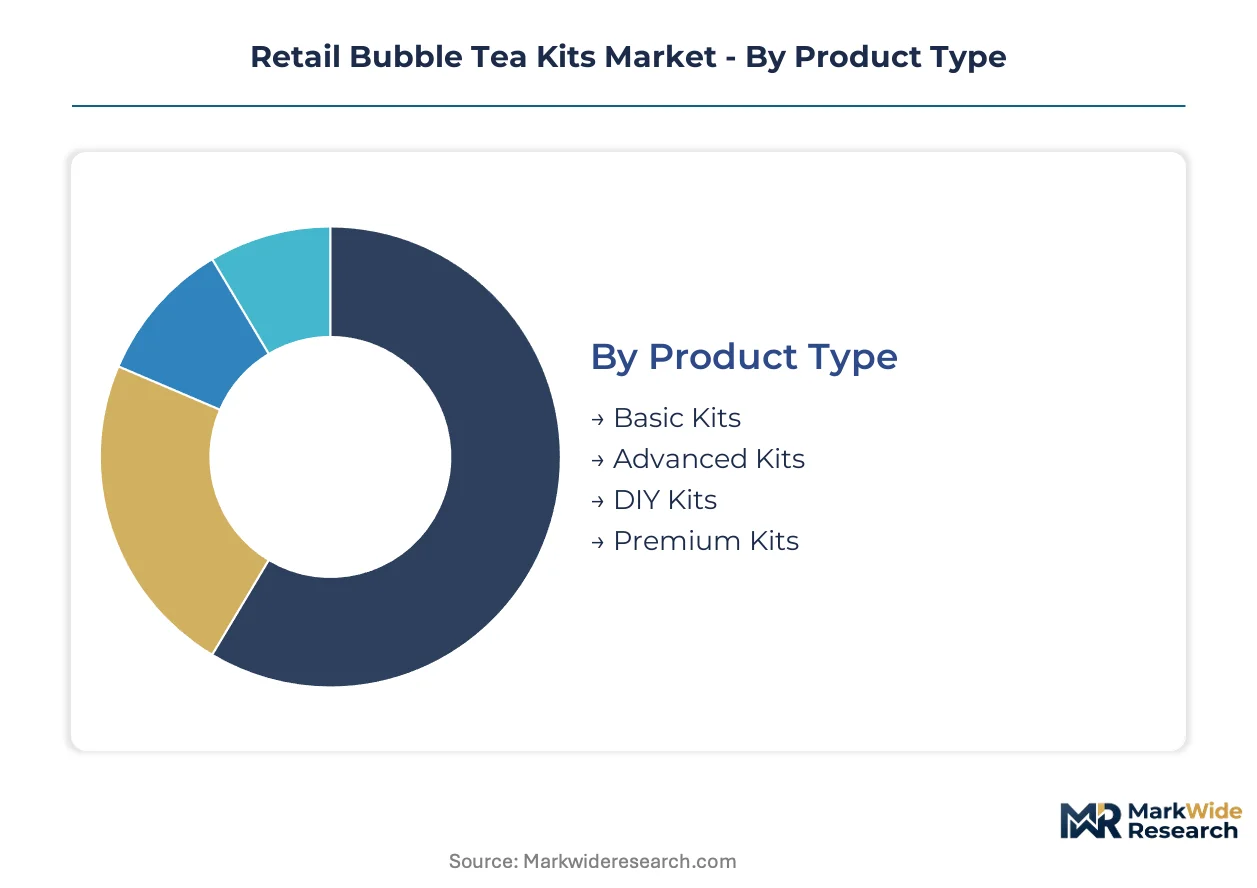
Segmentation in the Retail Bubble Tea Kits Market reveals distinct preparation behaviors and channel preferences that determine kit configuration, packaging economics, and margin architecture. Each dimension captures a different lens on how households and commercial operators translate café-style beverage demand into at-home purchasing decisions.
Product Type:
Purchase decisions pivot on preparation confidence and ingredient control preferences, with households self-selecting into complexity tiers based on prior bubble tea consumption experience and kitchen equipment availability.
- DIY Kits:Pre-measured ingredient assemblies with step-by-step instructions target novice consumers entering the category. Demand concentrates in United States suburban households with limited access to specialty bubble tea cafés, driven by algorithmic discovery on short-form video platforms that collapse trial barriers.
- Premium Kits:Single-origin tea bases and artisanal tapioca pearls command elevated price points through provenance storytelling and extended steeping guidance. Concentration sits in California and New York urban markets with established Asian diaspora communities, where ingredient authenticity overrides cost sensitivity.
- Basic Kits:Standardized black tea and conventional cassava pearl combinations optimize for mass retail shelf efficiency and price accessibility.
- Advanced Kits:Modular flavor pod systems with interchangeable components appeal to repeat purchasers seeking customization without multiple complete kit purchases.
DIY Kits lead on scale; Premium Kits lead on momentum.
Distribution Channel:
Channel selection reflects inventory velocity requirements, customer education needs, and the relative importance of impulse discovery versus planned replenishment in the purchase cycle.
- Online Retail:Direct-to-consumer and marketplace platforms capture algorithmic discovery traffic with unboxing content driving trial. Steepest expansion trajectory among channels as influencer partnerships and subscription models consolidate recurring revenue streams.
- Specialty Shops:Curated inventory with staff-assisted selection commands margin premiums unavailable through mass retail. Concentration in Toronto, Los Angeles, and Vancouver metropolitan areas with high-density Asian consumer bases.
- Supermarkets:Standardized kit configurations with national distribution optimize for household penetration and promotional pricing cycles.
- Convenience Stores:Single-serve impulse formats with minimal preparation time target immediate consumption occasions and travel-related purchases.
Online Retail expands most quickly; Specialty Shops retain margin concentration.
Customer Type:
End-user segmentation distinguishes household consumption patterns from commercial operational requirements, with volume thresholds and preparation consistency demands shaping kit specifications.
- Individual Consumers:Household purchasers seeking café-equivalent experiences without per-unit commercial pricing. Demand concentrates in millennial and Gen-Z demographics across United States metropolitan markets, driven by habit formation around home beverage preparation.
- Cafes:Small commercial operators using kits for menu experimentation or supply chain backup during ingredient shortages. Procurement prioritizes batch consistency and rapid preparation protocols.
- Restaurants:Full-service establishments adding bubble tea as a limited beverage offering without dedicated equipment investment.
- Event Planners:Corporate and private event coordinators sourcing bulk formats for experiential catering with interactive preparation stations.
Individual Consumers anchor volume; Cafes drive commercial segment experimentation.
Packing Type:
Packaging configuration aligns with consumption frequency, storage constraints, and gifting occasions, with format selection directly impacting logistics economics and inventory turnover.
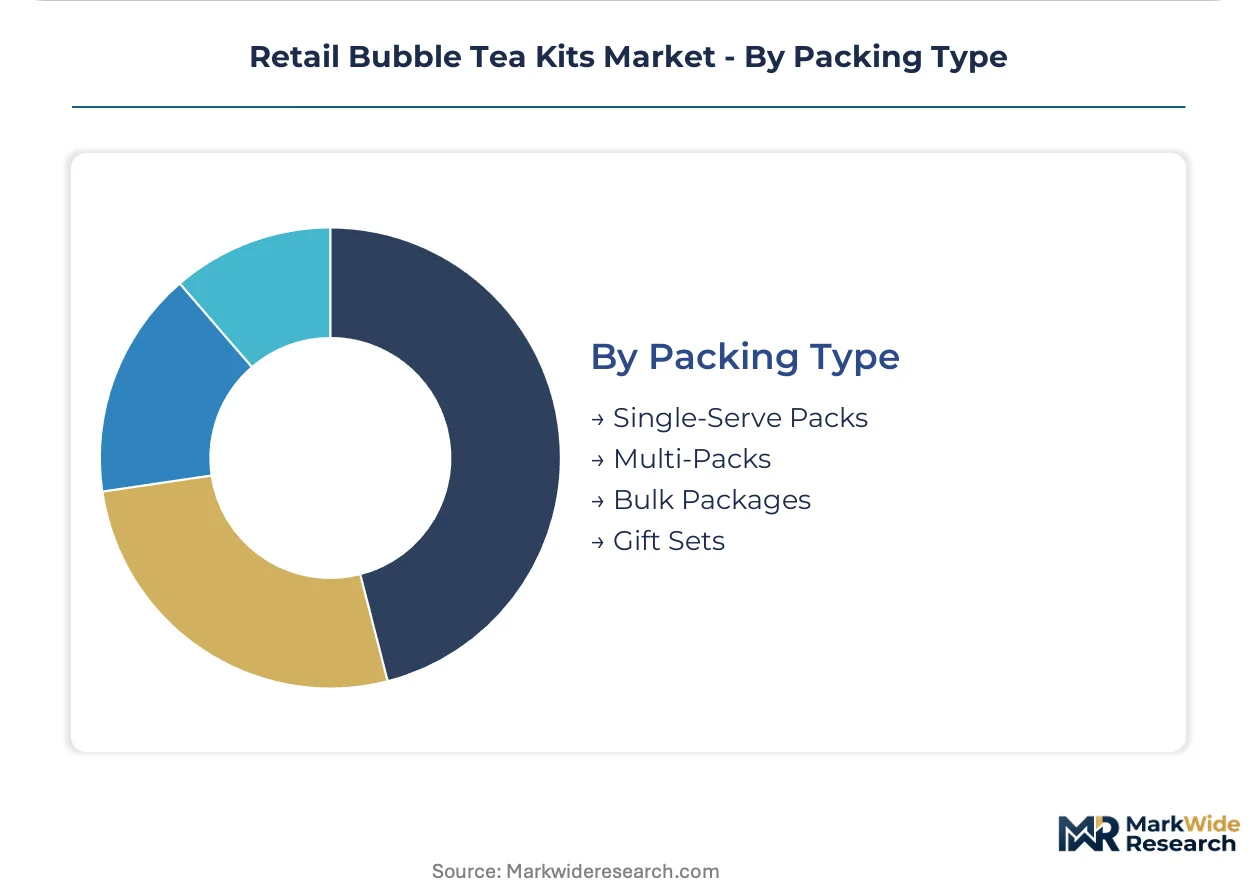
- Multi-Packs:Four-to-six serving configurations balance per-unit cost efficiency with manageable household consumption cycles. Concentration in subscription box models and warehouse club channels.
- Single-Serve Packs:Individual portion formats minimize trial risk and optimize for impulse retail placement and travel consumption.
- Bulk Packages:Commercial-scale quantities with extended shelf-life packaging target cafe and restaurant operators with predictable demand patterns.
- Gift Sets:Curated assortments with premium presentation and accessory inclusion capture seasonal purchasing occasions and experiential gifting demand.
Multi-Packs dominate household replenishment; Gift Sets concentrate margin in seasonal windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bubble tea culture originated in Taiwan during the 1980s before spreading through Asian diaspora communities to North America and Europe. The at-home kit phenomenon emerged first in United States metropolitan markets with established Taiwanese and Chinese populations, then diffused through algorithmic social media exposure to mainstream consumers. Today, demand concentrates in five national markets where ingredient import infrastructure and specialty retail channels have matured.
United States
Asian diaspora communities in California and New York sustain premium kit demand through authenticity-seeking purchasing behavior. The FDA's food-contact substance regulations for imported tapioca starch and tea packaging filter non-compliant suppliers, concentrating shelf space among verified assemblers. Los Angeles and New York metropolitan areas host the densest specialty shop concentrations, where staff-assisted selection commands margin premiums unavailable through mass retail channels.
Canada
Toronto and Vancouver anchor national demand through high-density Asian consumer bases and established bubble tea café culture. Health Canada and the PMRA regulate imported tea components and food-contact materials, creating documentation requirements that favor larger assemblers with dedicated regulatory affairs functions. Subscription box models concentrate in Ontario and British Columbia, where just-in-time import patterns face customs hold risks without compliance buffers.
United Kingdom
London's multicultural food retail landscape supports specialty shop expansion for premium kit configurations with single-origin tea bases. EFSA labeling requirements and post-Brexit import documentation for Southeast Asian tapioca products create variable thresholds that delay market entry for smaller assemblers. The Teashed and similar domestic brands leverage local formulation knowledge to capture urban household demand.
Australia
Sydney and Melbourne metropolitan areas drive consumption through millennial and Gen-Z households habituated to home beverage preparation. The TGA and FSANZ oversee food-contact material safety for imported kit components, with state-level packaging waste regulations in New South Wales and Victoria accelerating compostable straw and sachet adoption. Asian grocery retail chains serve as primary distribution infrastructure.
Germany
Berlin and Munich emerging demand centers reflect broader European mainstream crossover from Asian diaspora consumers to general population trial. ECHA REACH compliance for food-contact substances and the EU Green Deal's packaging sustainability mandates reshape supplier qualification timelines. German consumers demonstrate particular price sensitivity, favoring basic kit configurations over premium provenance positioning.
Retail Bubble Tea Kits Market Competitive Landscape
The competitive structure tilts toward direct-to-consumer specialists and supply-chain-scale bulk retailers rather than consolidated multinational beverage conglomerates. Player mix spans unbranded Amazon marketplace entrants, subscription-native digital brands, and established Asian import distributors pivoting into kit assembly. Three archetypes dominate: algorithmic discovery-optimized DTC natives, regulatory-compliance-scale bulk channel players, and premium ingredient provenance storytellers. Competitive moves concentrate on influencer partnership networks and USDA organic certification acquisition rather than manufacturing capacity expansion.
Within the bulk retail channel archetype, ORBITEL INTERNATIONAL exemplifies supply-chain-scale positioning that dominates mass-market shelf presence. Buddha Bubbles Boba and The Bubble Tea Club occupy contrasting positions on the premium-DTC spectrum, with the former representing artisanal ingredient sourcing credibility and the latter exemplifying subscription-model recurring revenue architecture. These three anchors illustrate how market position derives from channel selection and margin structure rather than manufacturing scale or brand heritage.
| Leading Market Players |
|---|
| ORBITEL INTERNATIONAL |
| BUBBLE TEA HOUSE COMPANY |
| Boba Barista |
| Locca Bubble Tea |
| Bubble Tea Supply |
| THE TEASHED |
| The Bubble Tea Club |
| Buddha Bubbles Boba |
| BOBA CHiC |
| Others |
Value Network & Pricing Analysis
Millennial and Gen-Z procurement preferences for USDA Organic certification and compostable packaging are forcing kit assemblers to absorb premium input costs and pass selective markups through subscription channels rather than mass retail.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and ingredient provenance. Premium tiers command substantial markups through single-origin tea sourcing and non-GMO tapioca validation. Cost compression in economy tiers is intensifying because cassava price volatility and freight rate spikes on the Asia-North America lane squeeze fixed-price retail contracts. Individual consumers in suburban United States markets demonstrate highest price sensitivity, while Asian diaspora communities in California and New York urban centers accept elevated premiums for authenticity signaling.
Supply Chain Analysis
FDA food-contact substance documentation requirements and USDA National Organic Program certification gating are filtering supplier pools and extending qualification timelines for Southeast Asian tapioca starch and Taiwanese tea base importers. Raw material sourcing draws from Thailand and Vietnam for cassava starch, Taiwan and Sri Lanka for premium black tea cultivars, and domestic United States facilities for organic sweetener blending. Single-origin supply concentration exposes assemblers to climate disruption and export quota restrictions. Distribution runs through direct-to-consumer subscription platforms, specialty retail channels in Toronto and Los Angeles, and bulk warehouse club formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Retail Bubble Tea Kits Market reads as a late-cycle quality story where habituated home beverage preparation has shifted procurement priorities toward certified ingredient transparency and preparation consistency over introductory trial pricing.
For Market Incumbents: Lock in supply chain scale advantages by securing multi-year organic certification contracts with Taiwanese tea estates and Thai cassava processors before qualification backlogs intensify. Deepen channel control through exclusive specialty shop partnerships in Vancouver and Sydney metropolitan clusters where staff-assisted selection commands margin premiums unavailable to algorithmic competitors. For New Entrants and Emerging Players: Direct-to-consumer subscription routes offer the most penetrable white-space for recurring revenue capture without mass retail slotting fee barriers. Target health-conscious millennial households in secondary United States metropolitan markets with modular flavor pod systems that reduce trial risk through customization. Deploy influencer partnership networks on short-form video platforms to collapse customer acquisition costs. For Investors and Strategic Acquirers: Asymmetric upside sits with direct-to-consumer specialists possessing validated subscription retention metrics and USDA Organic certification infrastructure. Long-term viability hinges on regulatory compliance scale rather than manufacturing capacity. Watch FDA enforcement actions against mislabeled cassava-derived ingredients as the inflection indicator for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Acquisition | FDA and National Organic Program validation unlocks 30-40% price premiums in specialty retail channels. |
| Direct-to-Consumer Subscription Launch | Recurring revenue architecture reduces customer acquisition cost dependence on volatile algorithmic discovery engines. |
| Compostable Packaging Transition | Polylactic acid and bamboo fiber specifications align with California and Washington State municipal composting infrastructure expansion. |
| Specialty Shop Channel Expansion | Curated inventory placement in Toronto and Los Angeles captures margin concentration unavailable through mass retail. |
| Modular Flavor Pod System Development | Interchangeable components reduce household trial risk while increasing purchase frequency without complete kit replacement. |
Research Methodology
Coverage spans United States, Canada, United Kingdom, Australia, and Germany, with primary inputs from each market informing demand pattern calibration. The analysis combined structured interviews with kit brand managers, specialty shop buyers, regulatory affairs consultants, and supply chain logistics coordinators with secondary validation from FDA import documentation databases, USDA Organic certification registries, Health Canada PMRA filings, and EFSA food-contact material guidance. Nielsen retail audit data and customs import records provided volume triangulation against bottom-up assembler shipment estimates.
Rate-of-change decomposition separated volume expansion from value premium capture across the projection horizon. The analytical framework modeled kit configurations by product complexity tier, distribution channel economics, customer type volume thresholds, and packaging format logistics. CAGRs were derived from segment-level growth trajectory blending. Forecast inputs incorporated cassava starch price volatility indices, social commerce platform algorithmic reach metrics, and municipal composting infrastructure deployment timelines.
Cassava harvest disruption, FDA enforcement acceleration, and cross-border e-commerce platform policy shifts are the dominant revision risks to modeled outcomes. Deviation in FDA food-contact substance documentation requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Catering Food Warmers Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
Global Digital Food Delivery Market
Food Service
Malaysia Food Service Market
Food Service
Instant Grocery Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Tabletop Pizza Oven Market
Food Service
Airport Quick Service Restaurants Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
India Inflight Catering Market
Food Service
Healthy Takeout Market
Food Service
Contract Blending Services Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Bahrain Food Service Market
Food Service
Global Delivery Takeaway Food Market
Food Service
Supermarkets Market