
 Ghana Seeds Market | 2026-2036
Ghana Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Ghana Seeds Market Foresight
Ghana is narrowing its yield gap through domestic seed multiplication programs and improved variety deployment. Corteva Agriscience leverages its breeding networks to supply drought-tolerant maize hybrids to the Northern Region. Syngenta AG anchors its position through vegetable seed portfolios targeting greenhouse operators near Accra. Seed Co Limited dominates open-pollinated variety distribution through rural agro-dealer networks.
Seeds are reproductive units containing embryonic plants encased in protective coats, typically standardized for germination rates exceeding 80 percent and genetic purity thresholds set by national certification protocols. Their commercial purpose centers on transferring improved agronomic traits from breeding programs into field production systems. Cereal seeds command the largest volume share as staple crop security drives government procurement, while vegetable seeds generate premium margins through greenhouse and export-oriented horticulture. The end-user structure tilts toward smallholder farmers who purchase through agricultural cooperatives to access certified seed on credit terms.
Ghana's Plant Protection and Regulatory Services Directorate enforces seed certification standards under the Plants and Fertilizer Act, while the Council for Scientific and Industrial Research coordinates variety release protocols through its Crop Research Institute. These frameworks restrict market access for uncertified seed lots and mandate field inspection cycles that shape breeder-to-farmer delivery timelines. Seed distributors and commercial growers must monitor regulatory enforcement intensity in emerging production zones where informal seed channels still dominate supply.
Market Dynamics
Certified seed procurement is concentrating around drought-tolerant maize hybrids as the Plant Protection and Regulatory Services Directorate tightens field inspection cycles and disqualifies informal seed channels from government subsidy programs.
Growth Catalysts
- Plants and Fertilizer Act enforcement:Mandatory certification protocols are redirecting commercial growers toward registered distributors and eliminating counterfeit seed lots from Ashanti Region supply chains.
- Greenhouse horticulture expansion:Vegetable seed demand from Accra-area greenhouse operators is accelerating hybrid tomato and pepper variety adoption for export-oriented production.
- Domestic seed multiplication programs:The Council for Scientific and Industrial Research is scaling breeder seed production to reduce import dependency for foundation materials.
Market Restraints
- Foundation seed import concentration:Breeder material for hybrid maize relies on external supply networks, exposing distributors to currency volatility and shipping delays.
- Field inspection capacity constraints:Limited personnel at the Plant Protection and Regulatory Services Directorate extend certification timelines, delaying variety release by multiple growing seasons.
- Farmer-saved seed substitution:Smallholders in the Northern Region continue replanting open-pollinated varieties from previous harvests, bypassing certified seed premiums entirely.
Strategic Opportunities
- Agro-dealer credit integration:Rural distribution networks in the Brong-Ahafo Region are piloting input financing tied to harvest repayment, expanding certified seed access beyond cash-purchasing farmers.
- Digital variety verification:Mobile-based seed authentication platforms are enabling real-time certification checks, reducing counterfeit penetration in informal market channels.
- Export corridor alignment:Vegetable seed portfolios optimized for EU phytosanitary standards are capturing greenhouse operator demand near Tema Port logistics infrastructure.
Industry Challenges
- Seed analyst certification backlog:The Crop Research Institute faces extended training pipelines for laboratory personnel capable of conducting germination and purity testing.
- Climate adaptation breeding timelines:Variety development cycles for drought-tolerant traits require multi-season field trials, compressing windows for commercial release before climate patterns shift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghana Seeds Market |
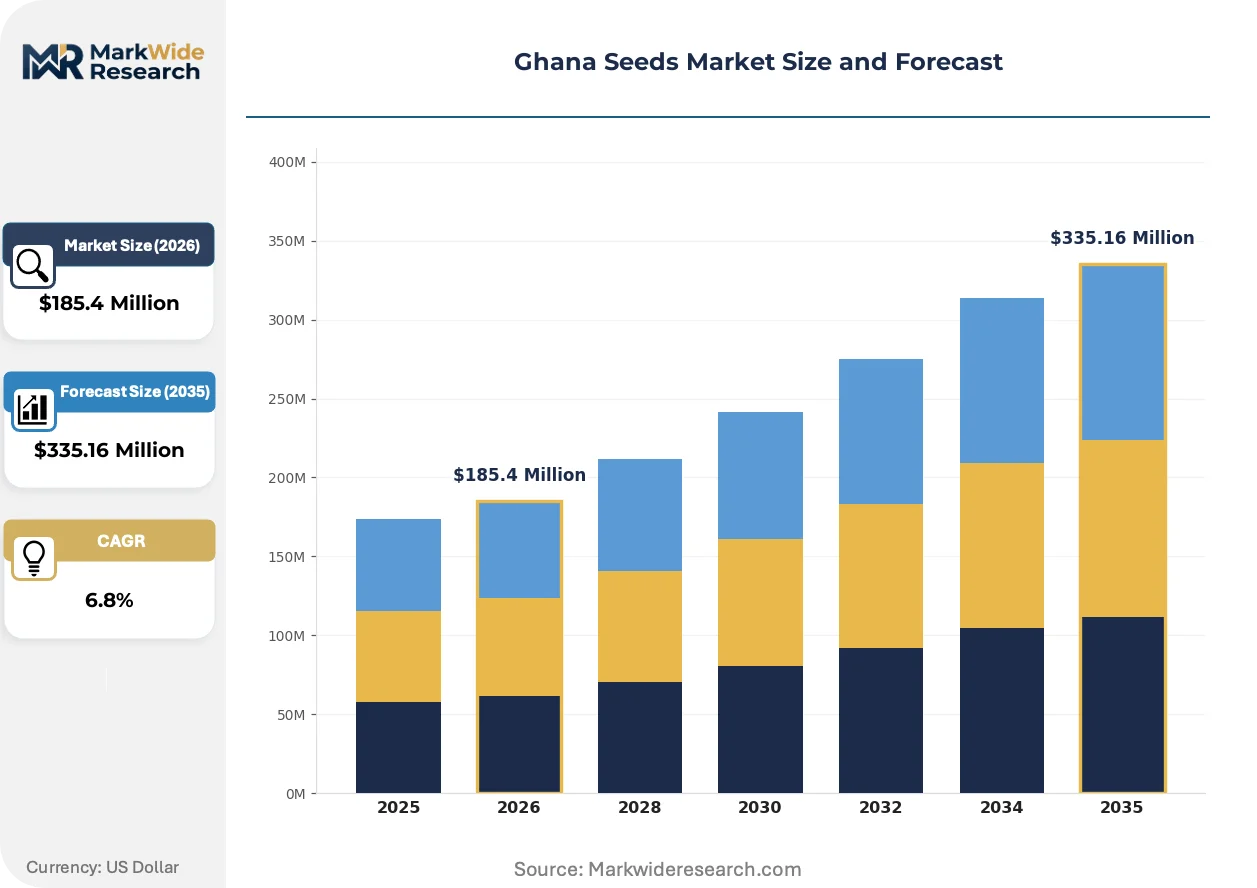
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal Seeds, Legume Seeds, Vegetable Seeds, Oilseed Seeds, Forage Seeds Application: Cereal Cultivation, Pulse Production, Horticulture, Oilseed Farming, Pasture Establishment End User: Smallholder Farmers, Commercial Growers, Agricultural Cooperatives, Research Institutes, Seed Distributors Packaging Type: Bulk Bags, Pouches, Vacuum-Sealed Packs, Jute Sacks, Plastic Containers |
| Companies Covered | Syngenta AG, Corteva Agriscience, Rijk Zwaan Zaadteelt En Zaadhandel BV, RMG Ghana Ltd, Seed Co Limited, M&B Seeds, Groupe Limagrain, East-West Seed, Meridian Seeds and Nurseries Ghana Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghana Seeds Market Shifts & Advancements
Seed technology deployment is pivoting toward climate-resilient genetics and digital traceability systems that compress the breeder-to-farmer verification chain.
Marker-assisted selection is migrating from research station applications to commercial breeding pipelines. Seed Co Limited and Corteva Agriscience are deploying genomic screening to accelerate drought-tolerance trait stacking in maize hybrids. This technology is migrating from experimental programs into routine variety development, collapsing traditional phenotypic selection timelines by half.
The Plant Protection and Regulatory Services Directorate is tightening seed lot traceability requirements under revised Plants and Fertilizer Act implementing regulations. Distributors must now maintain chain-of-custody documentation from breeder seed through certified sale. Smallholder-facing agro-dealers in the Northern Region are responding by consolidating supplier relationships to reduce compliance documentation burden.
Farmer purchasing patterns are fragmenting across input financing modalities. Agricultural cooperatives in the Ashanti Region are displacing cash transactions with harvest-linked credit structures, while commercial greenhouse operators near Accra are negotiating direct breeder contracts for vegetable seed volumes. This bifurcation is most visible in maize seed distribution, where cooperative procurement concentrates in the north and direct commercial sales dominate peri-urban horticulture clusters.
Ghana Seeds Market Segmentation
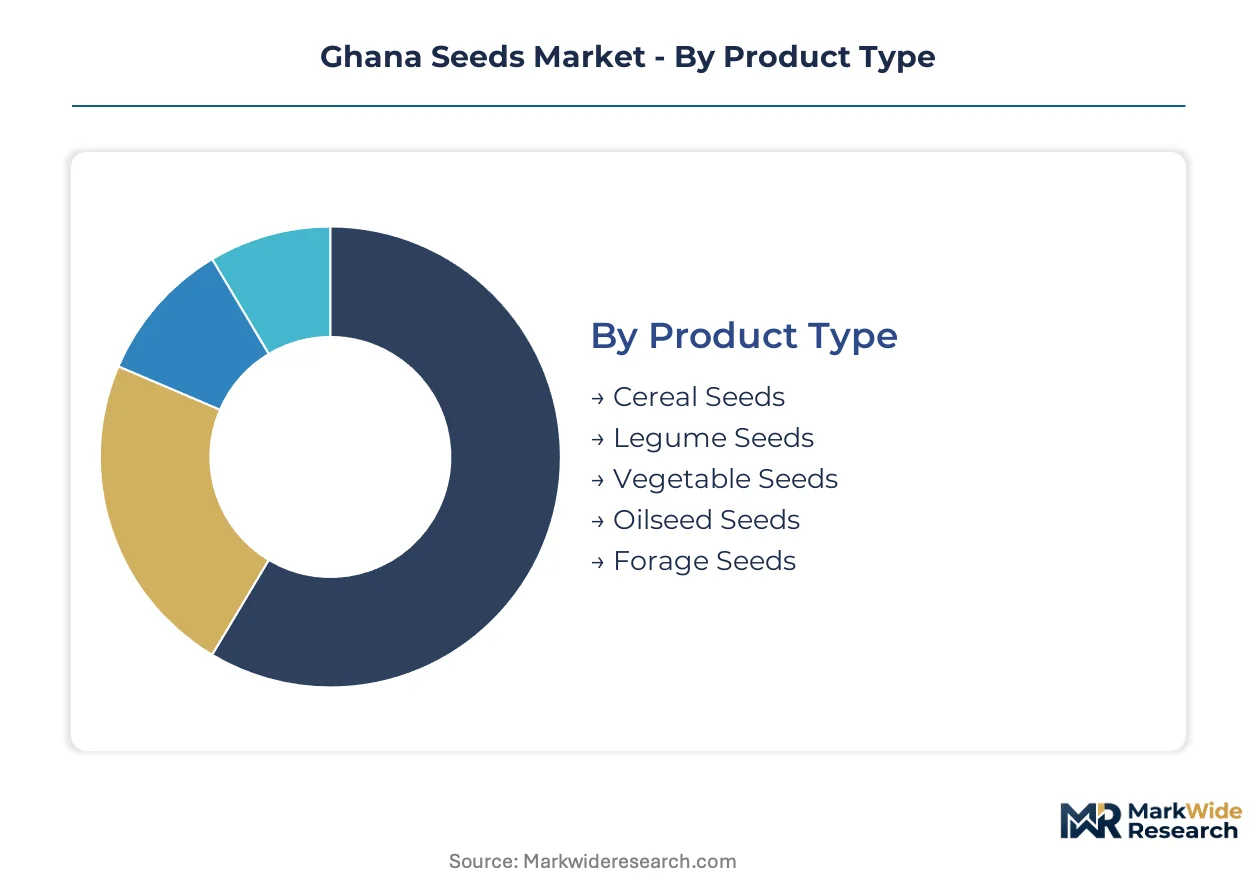
Ghana's seed market segments reflect divergent service intensity requirements across product categories and packaging formats. Certified seed procurement demands vary sharply between smallholder cooperatives requiring credit-linked distribution support and commercial greenhouse operators seeking direct breeder relationships.
Product Type:
After-sales service intensity escalates with genetic complexity and certification tier, driving divergent support models across seed categories.
- Cereal Seeds:Maize and rice hybrids dominate volume flows, with drought-tolerant varieties commanding intensive agronomic support from Corteva Agriscience breeding networks. Demand concentrates in the Northern Region where smallholders rely on cooperative extension services for hybrid management guidance.
- Vegetable Seeds:Hybrid tomato and pepper genetics require greenhouse-specific technical consultation and phytosanitary compliance verification. Accra-area operators near Tema Port logistics infrastructure drive premium pricing through export-oriented production standards.
- Legume Seeds:Cowpea and groundnut open-pollinated varieties circulate through informal channels with minimal distributor support.
- Oilseed Seeds:Soybean and sunflower certified seed adoption remains limited by farmer-saved substitution patterns in the Brong-Ahafo Region.
- Forage Seeds:Pasture establishment materials serve commercial dairy operations with specialized technical advisory requirements.
Cereal seeds hold the largest share; momentum sits with vegetable seeds.
Application:
Cost tier stratification separates subsidized staple crop programs from self-financed horticulture investments.
- Cereal Cultivation:Government procurement channels and Plant Protection and Regulatory Services Directorate certification subsidies shape maize and rice seed distribution economics. The Northern Region's smallholder concentration drives cooperative-aggregated purchasing with harvest-linked repayment structures.
- Horticulture:Greenhouse tomato and pepper production demands hybrid seed with EU phytosanitary alignment and direct breeder technical partnerships. Peri-urban Accra clusters exhibit the steepest expansion trajectory through export corridor development.
- Pulse Production:Cowpea cultivation relies heavily on farmer-saved seed with limited certified variety penetration.
- Oilseed Farming:Soybean seed multiplication programs through the Crop Research Institute aim to reduce import dependency.
- Pasture Establishment:Commercial livestock operations purchase forage seed through specialized distributors with agronomic planning services.
Cereal cultivation absorbs the greatest certified seed volume; horticulture delivers the fastest margin expansion.
End User:
Customer type determines financing modality and distribution channel configuration across rural and peri-urban networks.
- Smallholder Farmers:Individual producers in the Ashanti and Northern regions access certified seed through agricultural cooperatives offering credit terms. Cash constraints perpetuate open-pollinated variety replanting despite yield penalties.
- Commercial Growers:Peri-urban greenhouse operators and mechanized cereal farms negotiate direct contracts with Seed Co Limited and Syngenta AG for volume commitments and technical service packages.
- Agricultural Cooperatives:Aggregating entities manage input financing and extension delivery for member smallholders.
- Research Institutes:The Council for Scientific and Industrial Research coordinates breeder seed production and variety release protocols.
- Seed Distributors:Rural agro-dealer networks in the Brong-Ahafo Region consolidate supplier relationships to manage Plant Protection and Regulatory Services Directorate compliance documentation.
Smallholder farmers represent the largest addressable population; commercial growers command the highest service investment per hectare.
Packaging Type:
Volume scale and seed viability requirements dictate packaging selection across distribution distances and storage conditions.
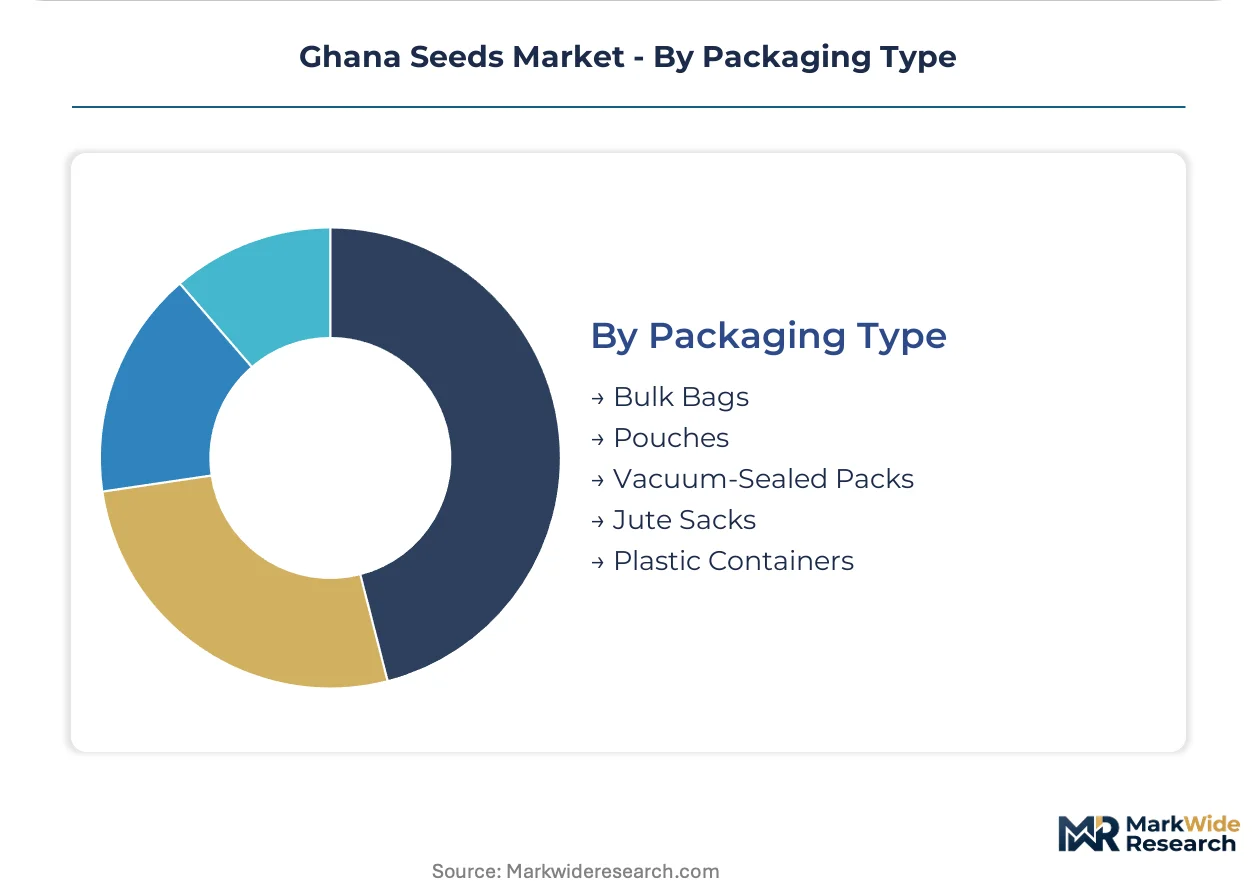
- Bulk Bags:Large-scale commercial cereal operations and cooperative procurement programs utilize woven polypropylene containers for maize hybrid transport from Seed Co Limited distribution centers.
- Vacuum-Sealed Packs:Vegetable seed for greenhouse operators requires moisture barrier protection and germination rate preservation through extended supply chains.
- Pouches:Small-unit retail packaging serves individual smallholder cash purchases through rural agro-dealer networks.
- Jute Sacks:Traditional breathable containers remain common for open-pollinated variety distribution in informal channels.
- Plastic Containers:Reusable rigid packaging supports research institute breeder seed handling and field trial distribution.
Bulk bags capture the greatest tonnage; vacuum-sealed packs are climbing the fastest on horticulture demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Ghana diverge sharply between the cereal-dependent north and the horticulture-focused south. The Northern Region's smallholder maize cultivation operates through cooperative credit structures, while peri-urban greenhouse clusters near Accra and Tema pursue export-grade vegetable seed specifications. This geographic split shapes distributor service models and certification compliance intensity.
Ashanti Region
Maize and rice cooperative networks dominate certified seed procurement through harvest-linked repayment structures. The Plant Protection and Regulatory Services Directorate operates regional field inspection stations that enforce Plants and Fertilizer Act certification timelines. Kumasi-based agro-dealer networks consolidate supplier relationships to manage compliance documentation for smallholder aggregation.
Northern Region
Drought-tolerant maize hybrid demand concentrates among smallholders transitioning from farmer-saved open-pollinated varieties. The Council for Scientific and Industrial Research coordinates breeder seed multiplication programs through Tamale satellite stations. Rural distribution corridors around Tamale and Yendi remain contested between formal certified channels and informal seed recycling networks.
Greater Accra
Greenhouse tomato and pepper operators drive premium vegetable seed specifications aligned with EU phytosanitary export standards. The Tema Port logistics corridor enables direct breeder contracts bypassing traditional distributor tiers. Peri-urban clusters in Tema and Ningo-Prampram exhibit the steepest hybrid adoption rates through mechanized horticulture investment.
Brong-Ahafo Region
Soybean and cowpea seed multiplication programs target import substitution for foundation materials. Agricultural cooperatives in Sunyani and Techiman pilot input financing tied to harvest repayment, expanding certified access beyond cash-constrained smallholders. The Crop Research Institute maintains regional trial stations for variety adaptation testing.
Central Region
Coastal vegetable cultivation and inland cereal production create bifurcated seed demand profiles. Cape Coast greenhouse operators source hybrid varieties through Accra distributor networks, while inland maize growers access certified seed through Brong-Ahafo supply chain extensions. Regional port infrastructure at Tema serves horticulture export consolidation.
Ghana Seeds Market Competitive Landscape
Capability concentration sits with multinational breeding networks; scale advantage sits with domestic distribution specialists. The market structures around three tiers: global agriscience conglomerates controlling proprietary hybrid genetics, regional African seed companies with established varietal portfolios, and domestic distributors managing last-mile compliance documentation. Consolidation pressure operates through variety release protocol bottlenecks rather than acquisition activity. Competitive positioning hinges on breeder-to-farmer timeline compression and Plant Protection and Regulatory Services Directorate certification navigation.
Within the multinational breeding tier, Syngenta AG and Corteva Agriscience occupy positions anchored by drought-tolerance trait portfolios and direct greenhouse operator relationships. Seed Co Limited represents the regional African specialist archetype, with distribution scale concentrated in open-pollinated variety networks. Among domestic distributors, RMG Ghana Ltd and Meridian Seeds and Nurseries Ghana Ltd exemplify the compliance-documentation tier managing field inspection cycle navigation for rural agro-dealer channels.
| Leading Market Players |
|---|
| Syngenta AG |
| Corteva Agriscience |
| Rijk Zwaan Zaadteelt En Zaadhandel BV |
| RMG Ghana Ltd |
| Seed Co Limited |
| M&B Seeds |
| Groupe Limagrain |
| East-West Seed |
| Meridian Seeds and Nurseries Ghana Ltd |
| Others |
Supply & Pricing Matrix
Tamale breeder seed multiplication clusters anchor Ghana's supply architecture, where domestic production capacity constraints translate directly into pricing power for distributors managing certified seed flows. The Northern Region's concentration of foundation material generation allows Seed Co Limited and Corteva Agriscience to command premiums through controlled variety release timelines.
Pricing Analysis
Price spreads between Accra greenhouse operators and Northern Region smallholders exceed threefold for equivalent genetic material. Three-tier pricing structure across premium certified hybrids, standard open-pollinated varieties, and uncertified informal seed governs transactions. Certification grade under the Plants and Fertilizer Act and volume scale through cooperative aggregation serve as the primary differentiation levers. Cost compression in the informal tier is intensifying because farmer-saved seed recycling bypasses distributor margins entirely. Smallholder cooperatives exhibit acute price sensitivity; commercial greenhouse operators demonstrate willingness to pay for phytosanitary documentation and direct breeder technical support.
Supply Chain Analysis
Breeder seed genetics for hybrid maize draw from Corteva Agriscience's South African breeding stations, Syngenta AG's Kenyan research facilities, and Seed Co Limited's Zimbabwean foundation multiplication programs. Parent line imports, laboratory testing reagents, and moisture-barrier packaging materials constitute critical input dependencies. Single-source vulnerability concentrates in foundation seed supply, where currency volatility against the Ghana cedi disrupts landed costs without domestic substitution alternatives. Distribution runs through rural agro-dealer networks in Brong-Ahafo and Ashanti regions, with peri-urban greenhouse operators accessing direct breeder contracts through Tema Port logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghana's seed market rewards players who command breeder-to-farmer timeline compression and navigate Plant Protection and Regulatory Services Directorate certification protocols. The scarcity of laboratory personnel capable of conducting germination and purity testing creates persistent bottlenecks in variety release.
For Market Incumbents: Entrench position through backward integration into foundation seed multiplication within Ghana, reducing import dependency exposure. Secure exclusive distribution arrangements with agricultural cooperatives in the Northern Region to lock out informal seed recycling networks. Invest in digital variety verification platforms to differentiate certified offerings from counterfeit penetration. For New Entrants and Emerging Players: Build out specialized vegetable seed portfolios targeting EU phytosanitary alignment for Accra-area greenhouse operators, where incumbent coverage remains thin. The horticulture segment offers the most penetrable entry point due to premium pricing tolerance and direct contract accessibility. Pursue partnerships with Tema Port logistics providers to compress delivery timelines for time-sensitive hybrid genetics. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-navigation play because certification backlog capacity and variety release protocol expertise compound over time. Target domestic distributors with established Plant Protection and Regulatory Services Directorate relationships and consolidated agro-dealer networks in Brong-Ahafo. Watch field inspection personnel training pipeline expansion as the inflection signal for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Breeder Seed Multiplication | Reduces import dependency for foundation materials under Crop Research Institute coordination. |
| Digital Seed Authentication Platform | Enables real-time certification verification against Plants and Fertilizer Act standards. |
| Agro-Dealer Credit Integration | Expands certified seed access through harvest-linked repayment structures in rural networks. |
| EU Phytosanitary Alignment Program | Captures greenhouse operator demand through export corridor development near Tema Port. |
| Laboratory Personnel Certification | Addresses analyst training backlog constraining germination and purity testing capacity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and agricultural extension reports. Interviews with seed distributors, agricultural cooperative managers, Plant Protection and Regulatory Services Directorate officials, and greenhouse operators informed demand-side validation. Secondary sources included Plants and Fertilizer Act implementing regulations, Crop Research Institute variety release protocols, and Council for Scientific and Industrial Research breeder seed production data. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates.
Forecast inputs span cereal seed adoption rates, vegetable greenhouse expansion trajectories, and certification compliance intensity across the projection horizon. Segmentation dimensions encompass product type, application, end user, and packaging format, with regional regulatory cluster differentiation. CAGRs derive from multi-factor regression incorporating breeder seed availability, field inspection cycle duration, and cooperative financing penetration. Climate adaptation breeding timelines and currency volatility against foundation seed imports constitute key industry-specific forecast variables.
Stress conditions across foundation seed import delays, field inspection capacity constraints, and farmer-saved seed substitution persistence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cooperative credit expansion. Cross-checking against Council for Scientific and Industrial Research breeder seed production disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Ghana Seed Extract Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Africa Vegetable Seed Market
Seeds
Global Forage Seeds Market
Seeds
Myanmar Seed Market
Seeds
Mexico Vegetable Seed Market
Seeds
Asia-Pacific Maize Seed Market
Seeds
Watermelon Seeds Market
Seeds
Guar Market
Seeds
South America Vegetable Seed Market
Seeds
Russia Seed Market
Seeds
Vietnam Seed Market
Seeds
Arnica Montana Market
Seeds
Southeast Asia Seed Market
Seeds
Africa Chia Seeds Market
Seeds
Australia Oilseed Market