
 Global Fabricated Metal Products Market | 2026-2036
Global Fabricated Metal Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fabricated Metal Products Market Foresight
Aftermarket service revenue is reconfiguring margin pools across the fabricated metal products value chain. ArcelorMittal leverages its integrated steel-to-components footprint to capture recurring refurbishment contracts for heavy machinery. Nucor Corporation sustains cost leadership through electric arc furnace flexibility and regional mill proximity to construction end users. Parker-Hannifin Corporation anchors premium positioning in precision machined hydraulic components where replacement cycles generate predictable revenue streams.
Fabricated metal products encompass engineered components and assemblies produced through cutting, bending, welding, machining, and finishing processes applied to raw metal stock, with tolerances often specified to thousandths of an inch for aerospace and medical applications. These products serve as structural and functional inputs across capital-intensive industries where material performance directly determines equipment lifespan and safety margins. Stamped components command mature volume pools in automotive and appliance manufacturing where tooling amortization favors high-run production. Machined parts capture expanding margin contributions from aerospace and defense programs requiring titanium and nickel-alloy precision work. Welded structures dominate infrastructure and shipbuilding procurement where qualification to ISO 3834 and AWS D1.1 standards gates supplier participation.
FDA device regulations and EPA metal finishing effluent rules in the United States constrain surface treatment processes and elevate compliance costs for suppliers serving medical and environmental equipment markets. EMA's Medical Device Regulation in Europe and China's NMPA quality system requirements create divergent certification burdens that fragment supplier qualification portfolios. Stakeholders must monitor how carbon border adjustment mechanisms and evolving scrap metal content mandates reshape raw material sourcing economics and regional cost competitiveness.
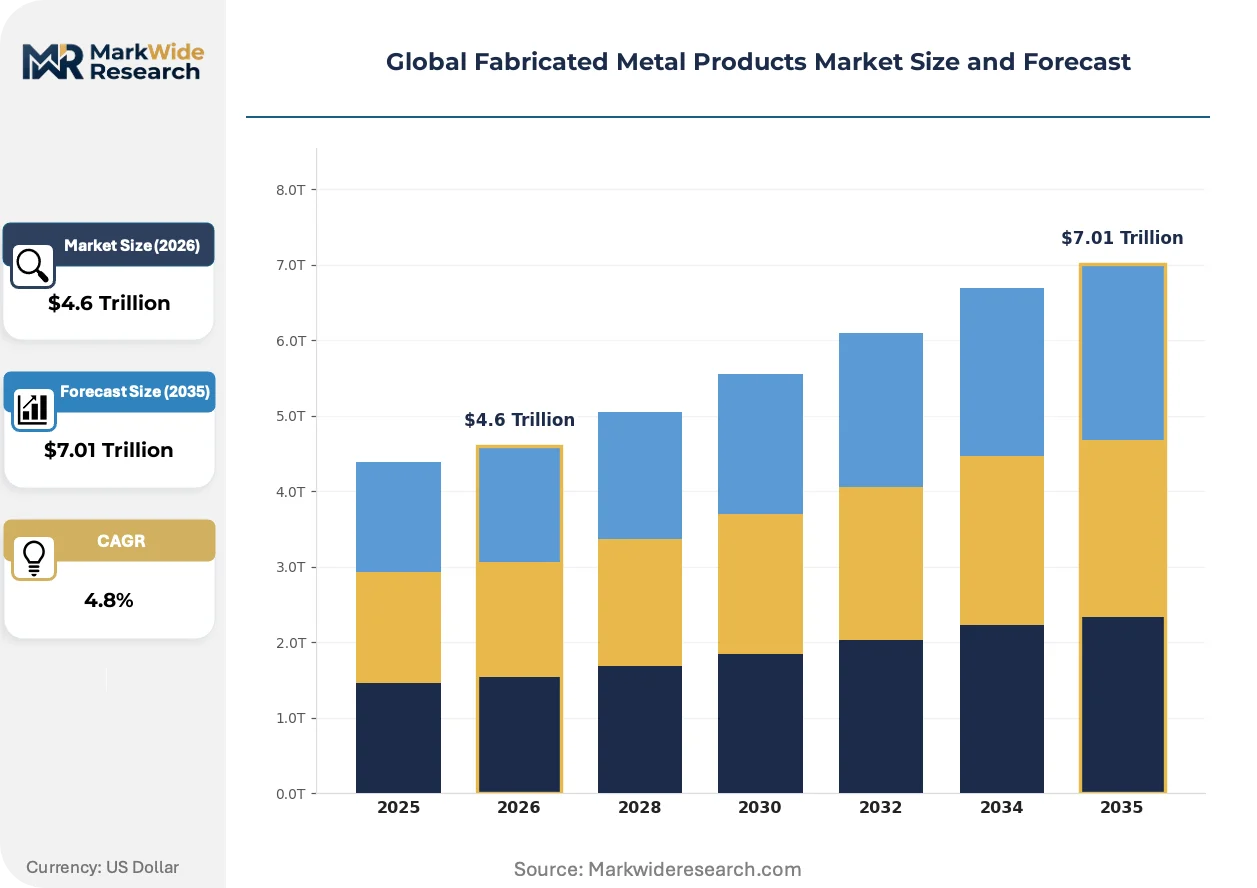
Market Dynamics
Carbon border adjustment mechanisms are reshaping raw material sourcing economics for fabricated metal suppliers, forcing recalculation of regional cost competitiveness as embedded emissions become a priced input across supply chains.
Growth Catalysts
- India's PLI scheme incentives:Precision metalworking investments are concentrating in Gujarat and Tamil Nadu industrial corridors as domestic value-addition mandates strengthen.
- Aerospace titanium procurement:OEMs are expanding machined parts orders for next-generation airframes, tightening tolerance specifications to thousandths of an inch.
- REACH compliance:European material traceability requirements are accelerating supplier qualification investments and favoring integrated producers with captive testing capabilities.
Market Restraints
- Scrap metal volatility:Electric arc furnace operators face margin compression when shredded scrap spreads widen unpredictably against hot-rolled coil benchmarks.
- China's GB standards fragmentation:Divergent provincial enforcement of national quality codes creates compliance friction for exporters serving multiple Chinese industrial zones.
- Polymer composite substitution:Wind turbine blade manufacturers are displacing welded steel towers with carbon fiber reinforced structures in offshore installations above 15MW capacity.
Strategic Opportunities
- Vietnam's industrial parks:Underpenetrated precision machining capacity exists near Haiphong and Bac Ninh as electronics OEMs reshore from China.
- Hydrogen storage vessels:High-pressure tank fabrication for mobility applications represents emerging demand for certified 700-bar welded aluminum-liner assemblies.
- EU Green Deal:Circular economy mandates for recycled content are creating premium pricing tiers for suppliers with verified scrap provenance systems.
Industry Challenges
- Welding engineer scarcity:ISO 3834 and AWS D1.1 certification pipelines cannot replenish retiring qualified inspectors at infrastructure and shipbuilding contractors.
- Multi-standard compliance:Suppliers serving medical device OEMs must simultaneously maintain FDA device regulations, EMA Medical Device Regulation, and China's NMPA quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fabricated Metal Products Market |
| Market Size in 2026 | $4.6 Trillion |
| Market Size in 2035 | $7.01 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stamped Components, Welded Structures, Metal Castings, Machined Parts Material: Carbon Steel, Stainless Steel, Aluminum, Titanium, Copper Application: Construction, Aerospace, Shipbuilding, Electrical Equipment, Heavy Machinery End User: OEM Manufacturers, Aftermarket Suppliers, Infrastructure Developers, Defense Contractors |
| Companies Covered | Howmet Aerospace, China Steel Corporation, ArcelorMittal, BTD Manufacturing, Mayville Engineering Company, Nucor Corporation, Parker-Hannifin Corporation, Carpenter Technology Corporation, Valmont Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fabricated Metal Products Market Shifts & Advancements
Additive manufacturing is converging with subtractive finishing workflows, compressing prototyping-to-production cycles for complex titanium geometries while quality assurance protocols struggle to keep pace with process variability.
Laser powder bed fusion is hybridizing with five-axis CNC machining centers to produce near-net-shape aerospace brackets that retain wrought material properties in critical load-bearing sections. Boeing and Airbus tier-one suppliers in Germany and Japan are adopting these workcells for low-volume, high-mix production runs. The technology is hybridizing traditional forging supply chains by eliminating die costs and reducing titanium buy-to-fly ratios from 20:1 toward 3:1.
REACH authorization requirements for chromium trioxide in surface treatment are forcing conversion to trivalent chrome and plasma electrolytic oxidation processes across European automotive and aerospace finishing operations. Suppliers without conversion coating alternatives are losing qualification status at major OEMs. Medical device manufacturers serving the EU market are most affected, accelerating partnerships with specialized PEO job shops in Switzerland and Poland.
Aftermarket service unbundling is fragmenting traditional component-supply relationships as mining and construction equipment operators separate parts procurement from refurbishment contracts. Independent remanufacturers in Australia and Chile are capturing hydraulic cylinder rebuild volume previously held by OEM distribution networks. This pattern is most visible in copper and iron ore belts where equipment utilization rates justify dedicated on-site machining capabilities.
Global Fabricated Metal Products Market Segmentation
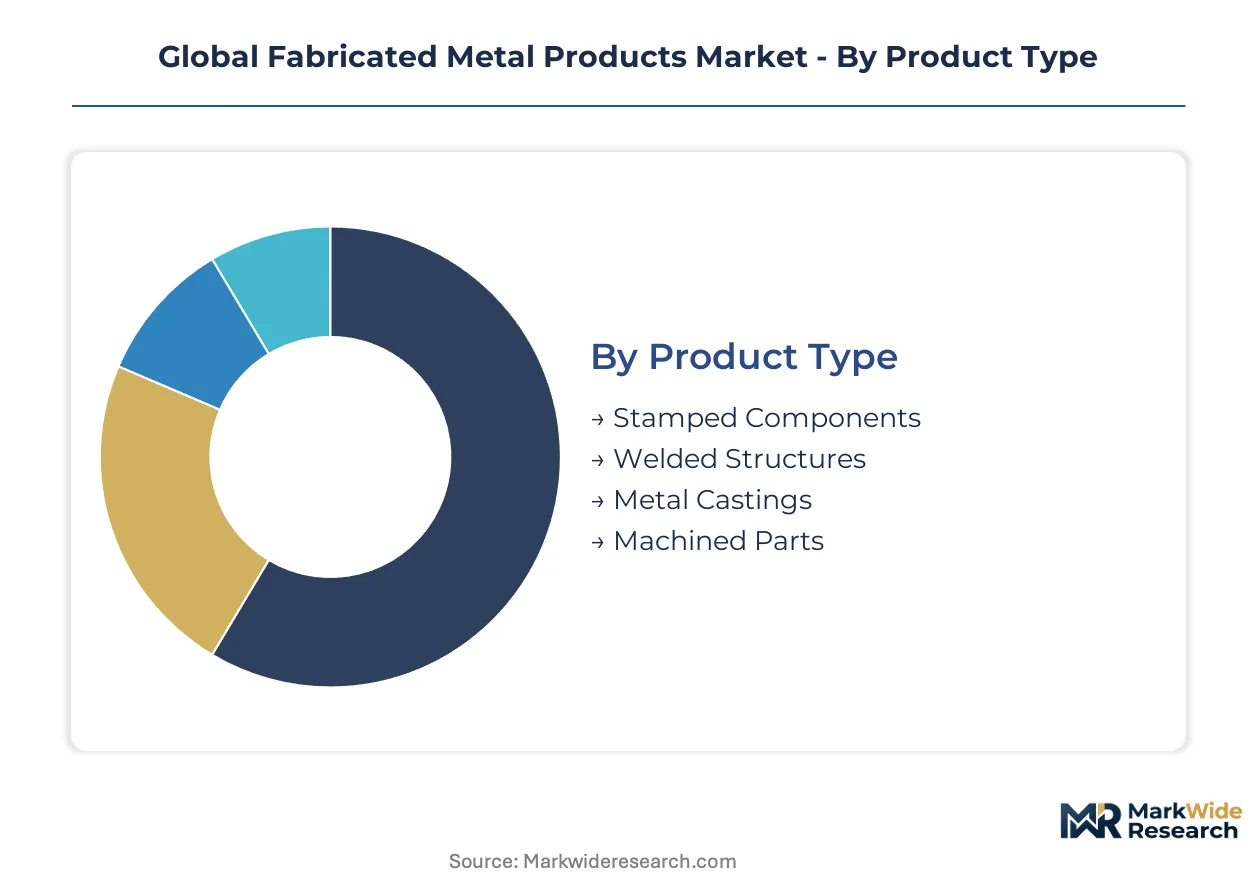
Segmentation in fabricated metal products reveals how process economics and certification requirements fragment supplier capabilities across radically different value pools. Stamped automotive components compete on tooling amortization cycles while aerospace machined parts command premiums through material traceability investments.
Product Type:
Use-case spectrum spans mass-production stampings through mission-critical precision machining, with process selection dictating capital intensity and customer switching costs.
- Stamped Components:High-volume sheet metal forming with progressive die tooling dominates automotive body panels and appliance enclosures. Demand concentrates in Detroit and Stuttgart manufacturing corridors where OEMs amortize die investments across million-unit programs. REACH compliance for surface coatings adds qualification friction for European suppliers.
- Machined Parts:Subtractive manufacturing achieves thousandth-inch tolerances for titanium aerospace brackets and nickel-alloy turbine housings. Boeing and Airbus tier-one suppliers in Germany and Japan are adopting hybrid additive-subtractive workcells for low-volume, high-mix production. Buy-to-fly ratios drive process economics.
- Welded Structures:Fusion-based assembly of plate and structural sections serves infrastructure and shipbuilding where ISO 3834 and AWS D1.1 certification gates supplier participation.
- Metal Castings:Foundry-based production of complex geometries in ferrous and non-ferrous alloys supports pump housings, valve bodies, and transmission cases.
Established volume favors Stamped Components; emerging adoption favors Machined Parts.
Material:
Raw material selection stratifies suppliers by metallurgical capability and emissions accounting requirements.
- Carbon Steel:Dominant tonnage input for construction rebar, structural beams, and automotive stampings where cost minimization overrides corrosion resistance. Electric arc furnace operators in Indiana and North Carolina leverage regional scrap availability for construction-grade output.
- Titanium:Aerospace-grade Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr alloys require vacuum arc remelting and specialized machining centers. Next-generation airframe programs in Seattle and Toulouse are expanding buy-to-fly ratio improvements through near-net-shape forging.
- Stainless Steel:Chromium-nickel grades serve chemical processing, medical devices, and food equipment where ASTM A240 surface finish specifications apply.
- Aluminum:5xxx and 6xxx series extrusions and sheet dominate transportation lightweighting and 700-bar hydrogen storage vessel fabrication.
- Copper:Electrical conductivity grades anchor busbar, winding, and heat exchanger applications with ASTM B152 thickness tolerances.
Carbon Steel retains the largest tonnage position; Titanium climbs the fastest on aerospace procurement expansion.
Application:
End-use diversification exposes suppliers to divergent procurement cycles and qualification protocols.
- Construction:Structural steel fabrication for commercial buildings and bridges follows AISC 360 and Eurocode 3 standards. Nucor Corporation's regional mill network in Texas and Florida captures proximity premiums to Gulf Coast and Southeast building booms.
- Aerospace:Airframe and engine component manufacturing demands AS9100D quality systems and Nadcap accreditation for special processes. India's PLI scheme incentives are concentrating precision metalworking investments in Gujarat and Tamil Nadu industrial corridors for this segment.
- Shipbuilding:Naval and commercial vessel construction requires ABS and DNV classification society approval for welded hull structures.
- Electrical Equipment:Transformer cores, switchgear housings, and busbar systems serve grid infrastructure and industrial power distribution.
- Heavy Machinery:Mining, agriculture, and construction equipment components support aftermarket refurbishment cycles with predictable replacement demand.
Construction maintains the deepest volume base; Aerospace offers the steepest expansion trajectory.
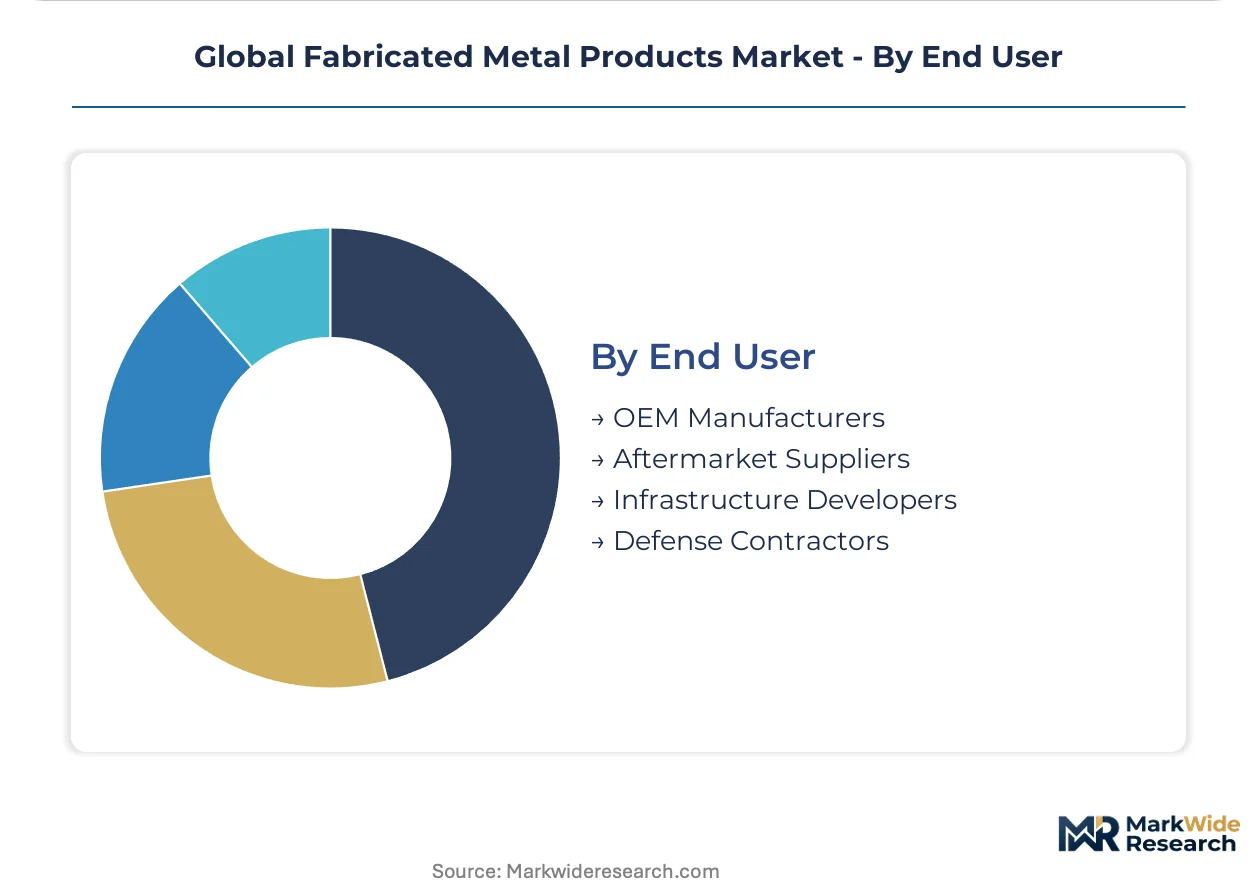
End User:
Customer type determines contract structure, inventory liability, and service revenue attachment.
- OEM Manufacturers:Original equipment producers in automotive, aerospace, and appliance sectors specify components through approved vendor lists with multi-year sourcing agreements. ArcelorMittal leverages integrated steel-to-components footprint to capture recurring refurbishment contracts.
- Aftermarket Suppliers:Independent distributors and remanufacturers in Australia and Chile are capturing hydraulic cylinder rebuild volume previously held by OEM networks. Unbundling of parts procurement from refurbishment contracts fragments traditional supply relationships.
- Infrastructure Developers:Public and private project owners procure fabricated structural elements through design-build and engineer-procure-construct contracts.
- Defense Contractors:Military program suppliers navigate ITAR, DFARS, and country-specific offset requirements with extended qualification timelines.
OEM Manufacturers command the largest contract values; Aftermarket Suppliers gain share fastest on service unbundling trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States favors high-service aftermarket contracts; China prioritizes integrated mill-to-component scale; Germany concentrates on precision-certified aerospace supply; India leverages policy incentives for import substitution; Japan advances hybrid manufacturing workflows.
United States
Construction-grade structural steel and aerospace precision machining dominate divergent demand pools. EPA metal finishing effluent rules constrain surface treatment operations for medical device suppliers. Nucor Corporation's electric arc furnace network in Indiana and North Carolina captures regional scrap proximity advantages for Gulf Coast building booms.
China
Carbon steel fabrication for infrastructure and shipbuilding absorbs dominant tonnage while titanium aerospace work expands. NMPA quality system requirements and divergent provincial GB standards enforcement create compliance friction for exporters. Yangtze River Delta clusters near Shanghai concentrate precision metalworking capacity for electronics OEM reshoring demand.
Germany
REACH authorization requirements for chromium trioxide accelerate conversion to trivalent chrome and plasma electrolytic oxidation across automotive and aerospace finishing. EMA Medical Device Regulation tightens supplier qualification for medical fabricators. Stuttgart and Munich industrial corridors host Boeing and Airbus tier-one suppliers adopting hybrid additive-subtractive workcells.
India
PLI scheme incentives concentrate precision metalworking investments in Gujarat and Tamil Nadu industrial corridors for aerospace and defense import substitution. BIS standards alignment with AS9100D quality systems gates supplier participation at OEMs. Domestic value-addition mandates strengthen as procurement shifts from raw material imports to finished component sourcing.
Japan
Hybrid laser powder bed fusion with five-axis CNC machining advances near-net-shape titanium production for low-volume aerospace brackets. METI industrial policy supports buy-to-fly ratio improvements from 20:1 toward 3:1. Nagoya and Osaka manufacturing clusters integrate traditional forging supply chains with additive manufacturing workflows.
Global Fabricated Metal Products Market Competitive Landscape
Capability concentration sits with precision-certified specialists; scale advantage sits with integrated steel-to-component producers. The market structures around three tiers: global mill operators with downstream fabrication footprints, regional job shops with Nadcap or AS9100D accreditation, and independent remanufacturers capturing unbundled aftermarket contracts. Dominant competitive moves include backward integration into scrap supply and strategic partnerships for hydrogen storage vessel certification.
Among North American fabricators, Howmet Aerospace and Nucor Corporation exemplify divergent archetypes—precision aerospace specialization versus integrated electric arc furnace scale. ArcelorMittal anchors the European-integrated tier with steel-to-components footprint. These three occupy positions spanning certified precision work, regional construction proximity, and integrated mill economics without overlapping strategic territory.
| Leading Market Players |
|---|
| Howmet Aerospace |
| China Steel Corporation |
| ArcelorMittal |
| BTD Manufacturing |
| Mayville Engineering Company |
| Nucor Corporation |
| Parker-Hannifin Corporation |
| Carpenter Technology Corporation |
| Valmont Industries |
| Others |
Supply & Pricing Matrix
Yangtze River Delta clusters near Shanghai concentrate precision metalworking capacity that translates directly into downstream pricing power for aerospace-grade titanium components. Contract structures segment into multi-year offtake agreements for OEM manufacturers, spot-market transactions for construction-grade carbon steel, and project-based procurement for infrastructure welded structures. Long-term offtake agreements dominate aerospace and defense programs where AS9100D certification and material traceability justify premium positioning. Price differentiation separates Nadcap-accredited precision specialists from regional job shops on certification grade and volume scale. Pricing pressure stems from scrap metal volatility compressing electric arc furnace margins. Construction end-users exhibit highest price sensitivity; medical device OEMs show least sensitivity due to regulatory qualification switching costs.
Pricing Analysis
Long-term offtake agreements dominate aerospace and defense programs where AS9100D certification and material traceability justify premium positioning. Price differentiation separates Nadcap-accredited precision specialists from regional job shops on certification grade and volume scale. Pricing pressure stems from scrap metal volatility compressing electric arc furnace margins. Construction end-users exhibit highest price sensitivity; medical device OEMs show least sensitivity due to regulatory qualification switching costs.
Supply Chain Analysis
Extended payment terms from tier-one aerospace OEMs cascade financial strain onto precision machining subcontractors across Germany, Japan, and India. Raw material flows draw from titanium sponge producers in China, nickel-alloy suppliers in the United States, and high-grade scrap processors in Turkey. Single-source vulnerability concentrates in vacuum arc remelting capacity for aerospace-grade titanium. Distribution runs through approved vendor lists at Boeing and Airbus tier-one suppliers rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace procurement expansion for next-generation airframes signals early-cycle penetration growth for precision-certified fabricators. Hydrogen storage vessel certification and India's PLI scheme incentives provide additional adoption tailwinds.
For Market Incumbents: Pre-empt polymer composite substitution in wind turbine towers by securing 700-bar hydrogen storage vessel certification before specialty fabricators scale. ArcelorMittal's integrated steel-to-components model demonstrates how backward integration into scrap supply buffers margin volatility from shredded scrap spread widening. Capacity addition in Gujarat and Tamil Nadu industrial corridors captures PLI scheme benefits while defending against emerging Indian precision metalworking specialists.
For New Entrants and Emerging Players: Vietnam's industrial parks near Haiphong and Bac Ninh represent the most penetrable entry point as electronics OEMs reshore from China. Underqualified welding engineer pipelines in infrastructure and shipbuilding create service gaps for ISO 3834-certified specialists. Hydrogen storage vessel fabrication for mobility applications offers uncrowded positioning before incumbent certification investments mature. Partnership-based go-to-market with German or Japanese tier-one suppliers accelerates aerospace qualification timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid additive-subtractive workcell operators over traditional forging-dependent specialists. Five-to-ten year viability hinges on buy-to-fly ratio improvements from 20:1 toward 3:1 in titanium aerospace brackets. Acquisition targets should display Nadcap accreditation for special processes and established relationships with Boeing or Airbus tier-one suppliers. The signal to watch is REACH authorization enforcement accelerating conversion coating alternatives beyond chromium trioxide.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Manufacturing Workcell Deployment | Boeing and Airbus tier-one suppliers in Germany and Japan compress titanium buy-to-fly ratios through laser powder bed fusion integration. |
| Backward Integration into Scrap Supply | Nucor Corporation's regional mill network captures construction-grade margin stability against shredded scrap volatility. |
| REACH Compliance Conversion Investment | European automotive and aerospace finishing operations pivot to plasma electrolytic oxidation as chromium trioxide authorization tightens. |
| PLI Scheme Capacity Concentration | Gujarat and Tamil Nadu industrial corridors attract precision metalworking investments for aerospace import substitution. |
| Hydrogen Storage Vessel Certification | 700-bar welded aluminum-liner fabrication opens mobility applications before incumbent pressure vessel specialists adapt. |
Research Methodology
Operator-level perspectives from plant engineers at tier-one aerospace suppliers, procurement leads at construction OEMs, aftermarket service heads at mining equipment operators, and welding inspectors at shipbuilding contractors anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, customs and trade data, AS9100D registrar records, and REACH authorization databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the fabricated metal products value chain.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeled by process type, material grade, application end-use, and certification tier. CAGRs derived from historical trajectory analysis adjusted for policy incentive impacts and technology substitution patterns. Forecast inputs incorporated PLI scheme disbursement schedules, aerospace OEM production ramp timelines, and carbon border adjustment mechanism implementation phasing.
Practitioners should monitor scrap metal spread volatility, REACH authorization enforcement actions, and hydrogen infrastructure deployment rates for early signals. Forecasts reflect documented assumptions on policy continuity and technology adoption curves. Macroeconomic contraction, regulatory acceleration, or additive manufacturing breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Antimony Market
Metals & Minerals
Californium Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Rare Earth Elements Market
Metals & Minerals
Gregoryite Market