
 US Lithium Market | 2026-2036
US Lithium Market Size, Share, and Industry Trends Forecast 2026-2036
US Lithium Market Insights
Subscription-based offtake agreements for battery-grade lithium chemicals is consolidating how producers and automakers contract supply. Albemarle Corporation leverages its Silver Peak brine operations and Kings Mountain processing footprint to anchor long-term cathode maker relationships. Piedmont Lithium competes through its Carolina Lithium project and Tennessee lithium hydroxide facility, while American Lithium Corp. differentiates via its Tonopah, Nevada claystone deposit and proprietary acid leach processing method.
Lithium is a soft, silvery-white alkali metal with the lowest density of all solid elements, extracted primarily as spodumene concentrate or brine-derived lithium carbonate and hydroxide for electrochemical applications. Battery-grade lithium hydroxide, with specifications below 20 ppm sodium and 10 ppm calcium, serves as the critical cathode precursor for nickel-rich lithium-ion cells. The Source segment shows hard rock spodumene from Australia and domestic Clayton Valley brine currently dominating feedstock supply, though direct extraction technologies are gaining traction as the fastest-growing Processing Method category. End User demand tilts overwhelmingly toward Automotive, where OEMs are securing decade-long offtake agreements, while Energy Storage represents the emerging margin pool as grid-scale battery deployments accelerate.
The Inflation Reduction Act, administered through Treasury Department guidance, mandates escalating domestic content thresholds for clean vehicle tax credits, directly shaping where lithium extraction and refining capacity must locate. EPA permitting timelines under the National Environmental Policy Act and state-level water rights frameworks in Nevada and North Carolina further constrain project development velocity. Stakeholders must monitor how SEC climate disclosure rules and evolving EPA hazardous waste classifications for lithium processing residues alter project economics and liability structures.
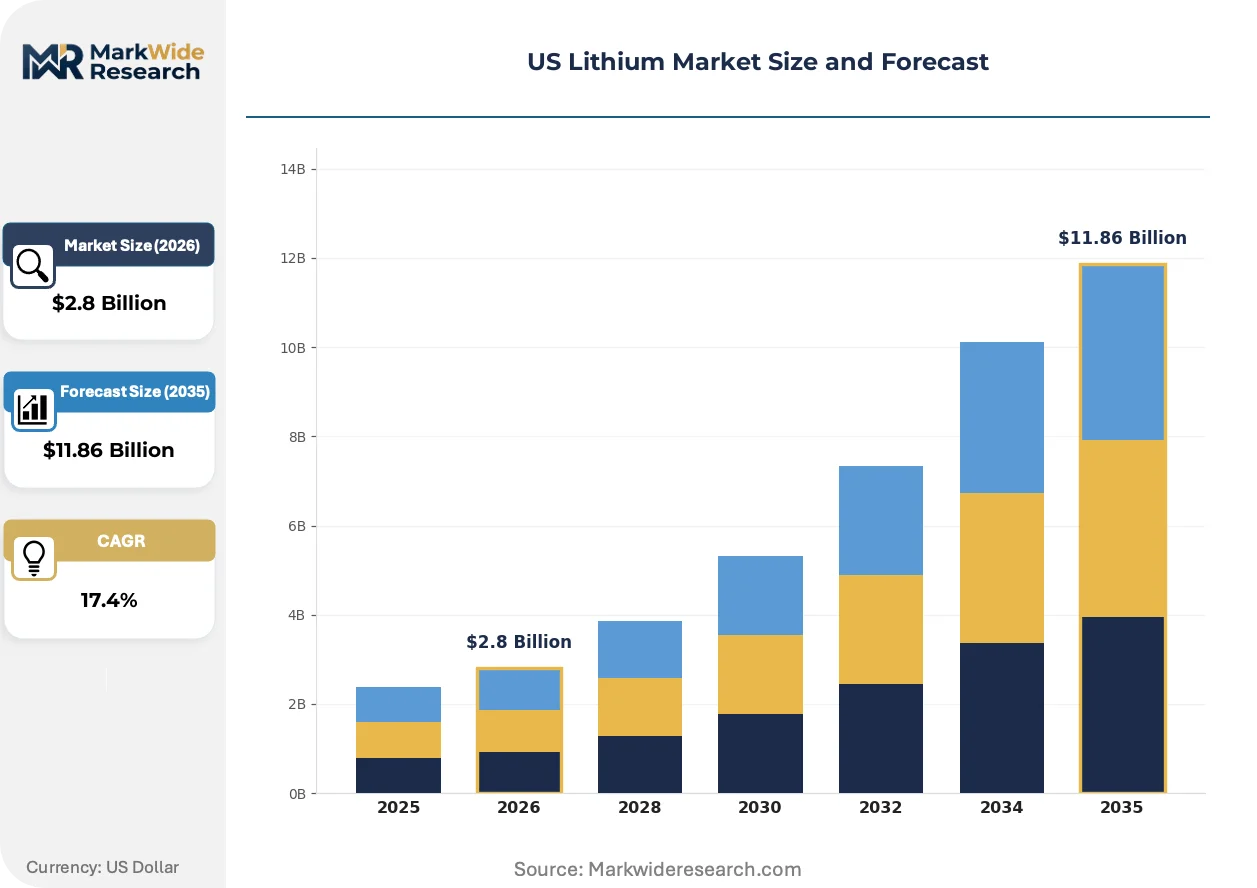
Market Dynamics
The Inflation Reduction Act's domestic content thresholds are compressing project timelines as developers race to qualify battery minerals for clean vehicle tax credits before Treasury Department phase-in deadlines tighten.
Growth Catalysts
- Direct Extraction Technologies:Selective absorption and electrochemical methods are slashing water consumption at brine operations compared to traditional evaporation ponds. Nevada's Clayton Valley operators are piloting these systems to accelerate production ramp.
- Automotive Offtake Structures:Cathode manufacturers are locking decade-long supply contracts with fixed-volume escalators. This de-risks capital deployment for greenfield lithium hydroxide facilities in Tennessee and the Carolinas.
- Grid-Scale Storage Procurement:Utility-scale battery deployments are diversifying demand beyond passenger electric vehicles. Independent power producers are sourcing lithium iron phosphate cells for four-hour duration storage installations.
Market Restraints
- Spodumene Concentrate Dependency:Domestic hydroxide producers rely on Australian hard rock feedstock subject to shipping cost volatility and concentrate offtake competition from Chinese converters.
- EPA Permitting Velocity:National Environmental Policy Act review timelines for Nevada extraction projects routinely extend 24-36 months beyond original schedules, compressing returns on committed capital.
- Claystone Processing Complexity:Nevada's lithium-rich claystone deposits require sulfuric acid leach circuits with higher capex intensity than brine or spodumene alternatives, constraining project finance availability.
Strategic Opportunities
- Carolinas Spodumene Belt:Hard rock deposits in North Carolina offer the only domestically integrated spodumene-to-hydroxide pathway outside Nevada, with existing rail and power infrastructure.
- Recycling Feedstock Integration:Black mass processing from end-of-life batteries is emerging as a secondary lithium source. Tennessee's existing chemical processing corridor positions for this circular supply stream.
- Department of Defense Stockpiling:Strategic mineral reserve mandates under the Defense Production Act are creating offtake guarantees for domestic lithium carbonate and hydroxide production.
Industry Challenges
- Process Engineer Scarcity:Lithium extraction and refining operations require specialized hydrometallurgical expertise that remains concentrated in Australian and Chilean labor markets.
- Water Rights Adjudication:Nevada's prior appropriation framework forces lithium developers into protracted negotiations with agricultural and municipal claimants in arid basins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Lithium Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $11.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source: Hard Rock, Brine, Recycled, Others End User: Electronics, Automotive, Energy Storage, Industrial Application: Batteries, Ceramics, Lubricants, Glass Processing Method: Hydrometallurgical, Pyrometallurgical, Direct Extraction, Others |
| Companies Covered | Albemarle Corporation, SQM S.A., Livent Corporation, American Lithium Corp., Lithium Americas Corp., Piedmont Lithium, Atlas Lithium Corp., Avalon Advanced Materials, Stardust Power Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Lithium Market Trends and Innovations
Direct lithium extraction is compressing the traditional evaporation-to-conversion pathway as developers target faster production cycles and lower water footprints in Nevada's brine basins.
Sorbent-based direct lithium extraction is unifying brine processing steps previously handled through sequential ponds and chemical precipitation. Developers in Clayton Valley are deploying these systems to shrink project timelines from five years to eighteen months. The technology is enabling faster qualification for Inflation Reduction Act domestic content bonuses.
EPA hazardous waste classification proposals for lithium processing residues are tightening disposal liability frameworks. Developers must now engineer zero-liquid discharge systems or secure Class I injection well permits. Nevada operations are responding by integrating solid waste stabilization circuits earlier in project design phases.
Automakers are consolidating cathode chemical procurement through captive offtake structures rather than spot market purchases. This compresses price discovery and transfers volume risk upstream to lithium hydroxide producers. The shift is most visible in Tennessee and the Carolinas, where integrated spodumene-to-hydroxide projects anchor regional supply security commitments from Detroit and European OEMs.
US Lithium Market Segmentation
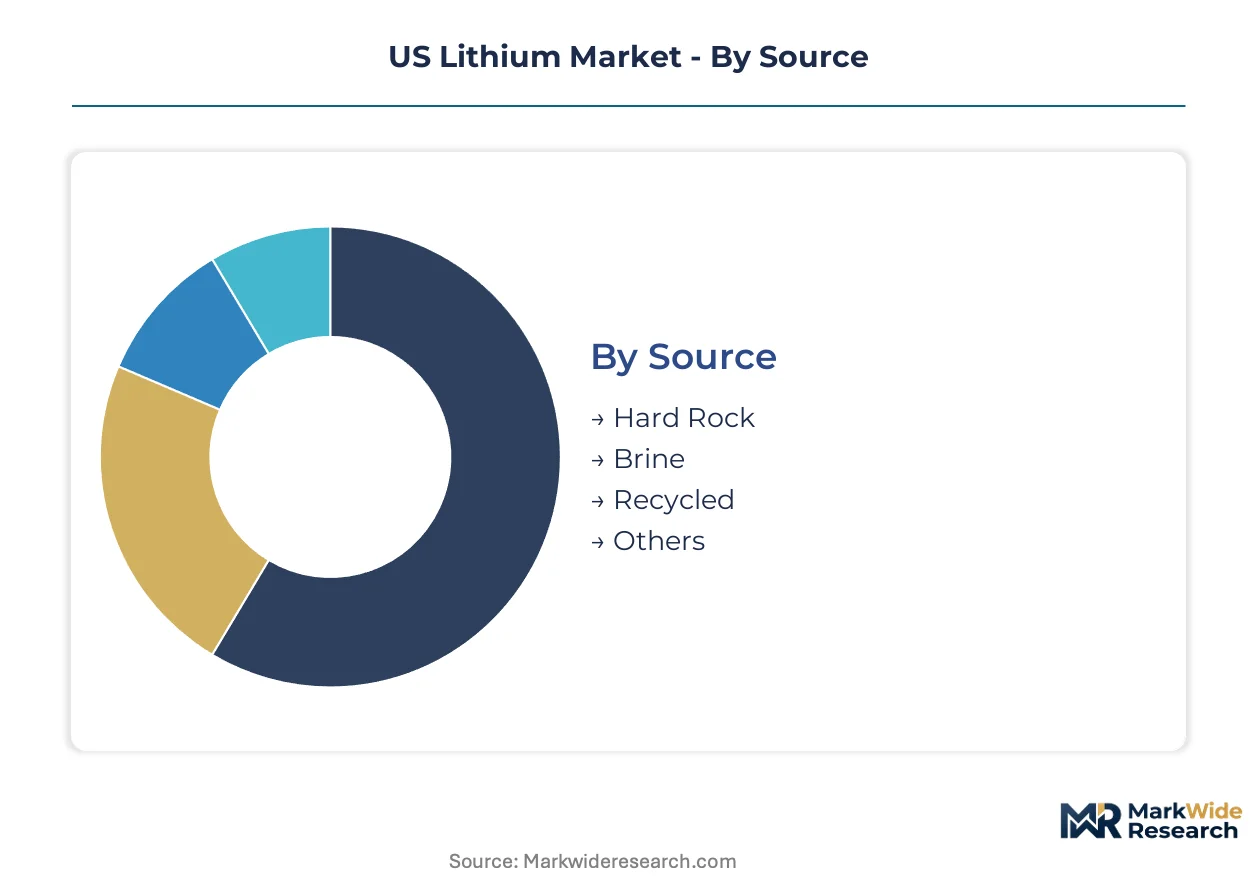
US lithium supply chains stratify sharply across extraction geology and processing chemistry. Each segment carries distinct capital intensity, water consumption profiles, and qualification timelines for Inflation Reduction Act domestic content thresholds.
Source:
Technical specifications and resource geology differentiate feedstock economics across domestic basins.
- Hard Rock:Spodumene concentrate from pegmatite deposits requires crushing, dense media separation, and acid roasting before lithium conversion. North Carolina's Carolina Tin-Spodumene Belt anchors the only integrated hard rock-to-hydroxide pathway outside Nevada, with rail corridors linking Piedmont Lithium's operations to Tennessee conversion facilities.
- Brine:Clayton Valley's lithium-rich groundwater yields through evaporation ponds or emerging direct extraction systems, with sodium and magnesium impurities demanding extensive purification circuits. Water rights adjudication under Nevada's prior appropriation framework constrains expansion velocity for new operators.
- Recycled:Black mass from end-of-life batteries and manufacturing scrap offers secondary lithium carbonate and hydroxide through hydrometallurgical recovery, positioning Tennessee's chemical processing corridor for circular feedstock integration.
- Others:Nevada's lithium-rich claystone deposits at Tonopah and McDermitt Caldera require sulfuric acid leach processing with elevated reagent consumption profiles.
Mature deployment sits with Hard Rock. Newer deployment is concentrated in Brine direct extraction systems.
End User:
Customer procurement structures range from decade-long automotive offtake agreements to spot industrial purchasing.
- Automotive:Detroit and European OEMs are locking fixed-volume escalator contracts with cathode material suppliers, transferring price risk upstream to lithium hydroxide producers. Tennessee and the Carolinas projects anchor these security-of-supply commitments.
- Energy Storage:Independent power producers sourcing lithium iron phosphate cells for four-hour grid-scale battery installations represent the emerging margin pool as utility procurement accelerates.
- Electronics:Consumer device manufacturers consume smaller lithium volumes with higher specification tolerances for cobalt-free cathode formulations.
- Industrial:Glass and ceramics producers purchase technical-grade lithium carbonate through shorter-term contracts with limited price hedging mechanisms.
Procurement concentration is tightening around Automotive. Energy Storage is climbing the fastest as a demand category.
Application:
End-use chemistry dictates lithium compound specification and purity thresholds.
- Batteries:Battery-grade lithium hydroxide with sub-20 ppm sodium and sub-10 ppm calcium serves as the critical precursor for nickel-rich NMC and NCA cathode architectures dominating premium electric vehicle platforms.
- Ceramics:Technical-grade lithium carbonate lowers thermal expansion coefficients in specialty ceramic glazes and heat-resistant cookware.
- Lubricants:Lithium-based grease thickeners derived from technical-grade hydroxide serve high-temperature industrial bearing applications.
- Glass:Lithium carbonate additions improve melt viscosity and thermal shock resistance in specialty glassware and pharmaceutical packaging.
Volume concentration rests with Batteries. Specification evolution is most rapid in Ceramics as manufacturers reformulate for lower-melting-point processes.
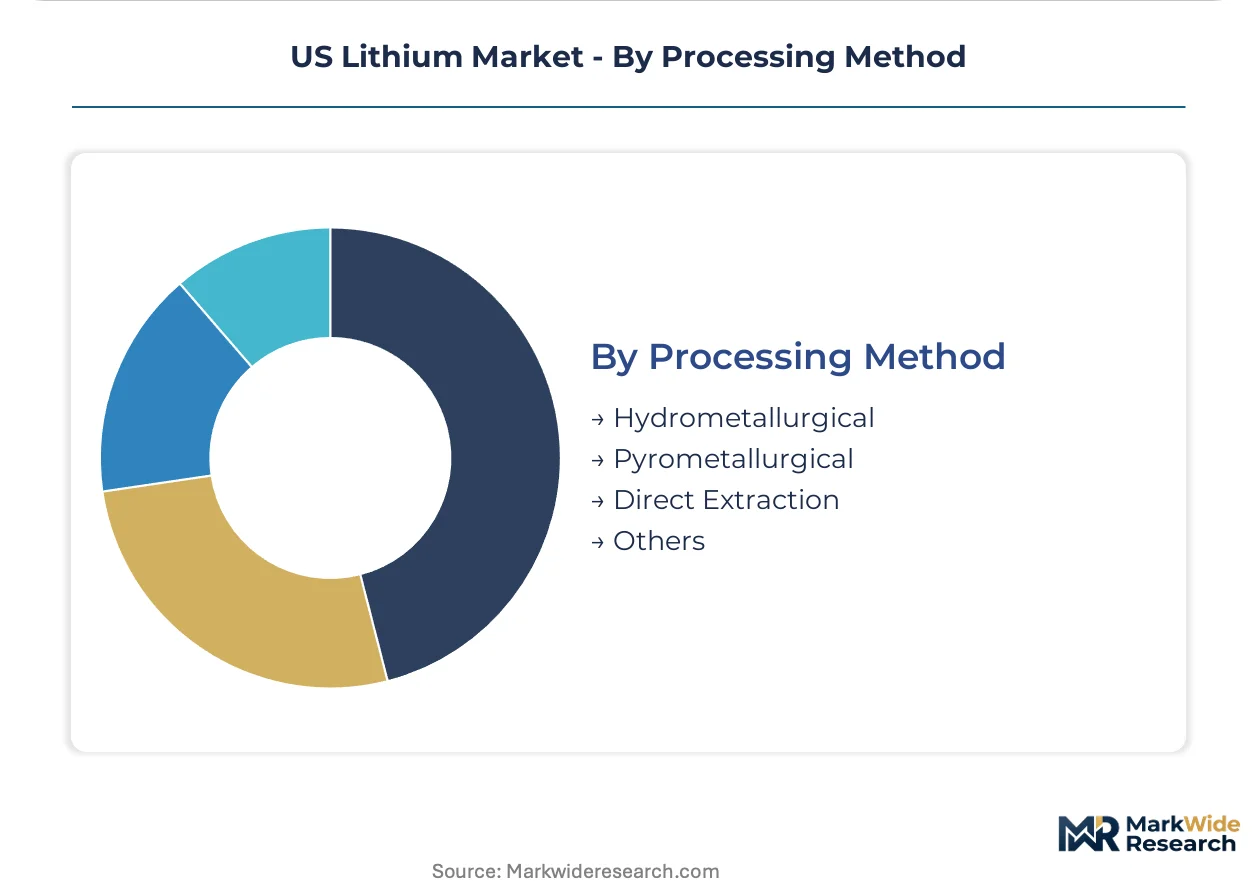
Processing Method:
Technology selection determines water intensity, project timeline, and residue liability exposure.
- Direct Extraction:Selective sorbent and electrochemical systems are compressing brine processing from five-year evaporation cycles to eighteen-month deployment, slashing water consumption in Nevada's arid basins while accelerating IRA qualification timelines.
- Hydrometallurgical:Acid leach and solvent extraction circuits dominate spodumene and claystone processing, with sulfuric acid reagent costs and neutralization residue volumes constraining project finance terms.
- Pyrometallurgical:High-temperature roasting of spodumene concentrate precedes acid digestion, with energy intensity and dust emissions subject to EPA hazardous waste classification proposals.
- Others:Emerging bioleaching and electrochemical membrane approaches remain pre-commercial for domestic deployment.
Operational scale favors Hydrometallurgical installations. Steepest expansion trajectory is occurring in Direct Extraction pilot deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US lithium production capacity lags consumption by a substantial margin, forcing domestic automakers and battery manufacturers to rely on imported spodumene concentrate and processed lithium chemicals. The geographic mismatch between extraction basins in the Mountain West and conversion infrastructure in the Southeast creates logistical complexity for supply chain planners. State-level regulatory frameworks and water rights adjudication further fragment development velocity across domestic basins.
Nevada
Clayton Valley brine operations and Tonopah claystone deposits anchor the nation's largest lithium extraction footprint. EPA permitting under the National Environmental Policy Act extends project timelines for new entrants, while Nevada's prior appropriation water law forces lithium developers into protracted negotiations with agricultural claimants. Silver Peak and McDermitt Caldera host the most advanced project pipelines, with direct extraction pilots accelerating production ramp schedules.
North Carolina
The Carolina Tin-Spodumene Belt offers the only integrated hard rock-to-hydroxide pathway outside Nevada, with Piedmont Lithium's Kings Mountain operations leveraging existing rail corridors. State mining permits under the North Carolina Mining Act of 1971 require comprehensive reclamation bonding, while local zoning disputes in Gaston County have delayed project approvals. The Charlotte-Gastonia metro anchors chemical processing talent pools for hydrometallurgical operations.
Tennessee
The state's existing chemical processing corridor positions for lithium hydroxide conversion from imported spodumene concentrate and emerging recycling feedstocks. Tennessee Valley Authority power rates attract energy-intensive refining operations, while Department of Economic and Community Development incentive packages support greenfield cathode material facilities. The Memphis-Nashville logistics axis enables rail-borne concentrate movement from East Coast ports.
California
Salton Sea geothermal brine deposits represent an emerging lithium extraction frontier tied to renewable energy generation. California Energy Commission grants fund direct extraction pilot programs at geothermal plants, while the state's Low Carbon Fuel Standard creates additional credit revenue streams for carbon-negative lithium production. Imperial County's unemployment rates drive political support for industrial development despite environmental justice concerns.
US Lithium Market Competitive Landscape
Top-tier vendors anchor integrated extraction-to-processing operations, while mid-tier developers compete on project-stage assets and jurisdictional positioning. The market structure concentrates around brine operators with legacy footprints and hard rock specialists with offtake-linked development pipelines. Two strategic archetypes dominate: diversified specialty chemical conglomerates with battery mineral divisions, and pure-play lithium developers with single-asset or regional-cluster strategies. Competitive moves center on captive offtake negotiations with automotive OEMs and strategic partnerships with cathode material manufacturers.
Among North American-anchored operators, Albemarle Corporation and Piedmont Lithium exemplify divergent archetypes. Albemarle represents the integrated multinational model with established brine operations and processing infrastructure. Piedmont Lithium occupies a position as a project-stage developer leveraging domestic spodumene resources. American Lithium Corp. anchors the claystone specialization tier with Nevada-focused assets. These three entities illustrate the competitive spectrum from incumbent scale to developmental optionality.
| Leading Market Players |
|---|
| Albemarle Corporation |
| SQM S.A. |
| Livent Corporation |
| American Lithium Corp. |
| Lithium Americas Corp. |
| Piedmont Lithium |
| Atlas Lithium Corp. |
| Avalon Advanced Materials |
| Stardust Power Inc. |
| Others |
Pricing and Supply Chain Analysis
Sovereign wealth-backed producers and private-equity-rolled-up specialists anchor US lithium supply, concentrating pricing power among integrated operators while compressing margins for project-stage developers dependent on external offtake financing.
Pricing Analysis
Cost-down pressure on battery-grade lithium hydroxide accelerates because automakers are consolidating cathode procurement through decade-long offtake contracts with fixed-volume escalators. Three-tier pricing structure across battery-grade, technical-grade, and industrial-grade specifications separates premium purity thresholds from standard cathode precursors. Pricing pressure stems from Australian spodumene concentrate import dependency and shipping cost volatility. Automotive OEMs exhibit the lowest price sensitivity due to IRA tax credit qualification requirements, while industrial glass and ceramics buyers demonstrate the highest sensitivity with limited hedging mechanisms.
Supply Chain Analysis
Black mass reverse-logistics flows from end-of-life batteries are emerging as secondary lithium carbonate and hydroxide feedstocks, positioning Tennessee's chemical processing corridor for circular supply stream integration. Domestic hydroxide production draws from Australian hard rock concentrate, Chilean brine-derived carbonate, and emerging Nevada claystone deposits. Supply chain risk centers on single-source vulnerability to Chinese converter dominance for spodumene processing. Distribution runs through rail corridors linking East Coast ports to Tennessee conversion facilities and Southeast cathode plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US lithium market sits in a processing-technology transition phase as direct extraction systems displace traditional five-year evaporation cycles, compressing project timelines and water consumption profiles.
For Market Incumbents: Acquire direct extraction technology licenses and pilot-scale assets in Nevada's Clayton Valley to defend against emerging DLE specialists threatening brine economics. Secure captive offtake structures with Detroit OEMs before Treasury Department domestic content thresholds tighten. Backward integration into Tennessee hydroxide conversion capacity anchors regional supply security commitments. For New Entrants and Emerging Players: Begin with North Carolina's Gaston County spodumene belt, where local zoning disputes have delayed incumbent approvals and created regulatory whitespace. Target the grid-scale energy storage segment, where lithium iron phosphate demand from independent power producers remains undercontracted relative to automotive offtake intensity. Pursue Department of Defense stockpiling mandates under Defense Production Act strategic mineral reserve programs as a guaranteed offtake pathway. For Investors and Strategic Acquirers: Distressed-cycle entries favor project-stage developers with EPA permits-in-hand but stalled construction financing in Nevada water rights-constrained basins. Long-term viability hinges on qualification for Inflation Reduction Act domestic content bonuses rather than spot price exposure. Monitor Treasury Department guidance phase-in deadlines as the critical inflection signal for asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Extraction Technology Deployment | Nevada brine operators piloting selective sorbent systems slash water consumption and accelerate IRA qualification timelines. |
| Automotive Offtake Agreement Consolidation | Cathode manufacturers lock decade-long contracts with fixed-volume escalators, transferring price risk upstream to hydroxide producers. |
| Recycling Feedstock Integration | Tennessee's chemical processing corridor positions for black mass recovery from end-of-life batteries as secondary lithium supply. |
| Carolinas Spodumene Belt Development | North Carolina's integrated hard rock-to-hydroxide pathway leverages existing rail infrastructure for Southeast cathode plant supply. |
| Defense Production Act Stockpiling Participation | Strategic mineral reserve mandates create guaranteed offtake for domestic lithium carbonate and hydroxide production. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with lithium extraction engineers, cathode material procurement leads, EPA permitting officers, and utility-scale battery project developers. SEC 10-K disclosures, USGS mineral commodity summaries, and Treasury Department IRA guidance documents provided validation layers. Bottom-up project pipeline assessments triangulated against top-down automotive demand forecasts.
Segment-level modeling operated at source geology, processing chemistry, and end-use application granularity across the projection horizon. Hard rock, brine, claystone, and recycled feedstock categories were modeled separately with distinct capital intensity and timeline assumptions. Hydrometallurgical, pyrometallurgical, and direct extraction processing methods carried differentiated water consumption and residue liability profiles. CAGR derivation incorporated IRA domestic content threshold phase-ins and EPA permitting velocity assumptions.
Permitting delays, water rights adjudication outcomes, and direct extraction technology scale-up failures are the dominant revision risks to supply forecasts. Practitioners should monitor EPA National Environmental Policy Act review timelines and Nevada prior appropriation negotiations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Gemstones Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Selenium Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Cesium Market
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market