
 Global Military IoT Market | 2026-2036
Global Military IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military IoT Market Foresight
The EU AI Act is decoupling autonomous weapons-grade edge computing from conventional defense procurement, forcing suppliers to certify algorithmic transparency before NATO member integration. Lockheed Martin Corporation leverages captive semiconductor foundries to sustain classified chip supply chains. Northrop Grumman Corporation anchors unmanned systems integration with hardened mesh-network protocols. BAE Systems competes through sovereign-British manufacturing of naval IoT sensor suites.
Global Military IoT encompasses networked sensor arrays, edge-computing nodes, and secure communication infrastructure operating in electromagnetic-contested environments, typically hardened to MIL-STD-810 shock specifications and AES-256 encryption standards, enabling real-time battlespace data fusion for command decision acceleration. Smart Sensors and Surveillance Systems dominate current procurement volumes as legacy platform retrofit cycles accelerate, while Command & Control Systems concentrate margin pools due to software-defined architecture upgrade paths. Deployment through Mobile Command Centers is expanding fastest as expeditionary force structures prioritize rapid-reconfigurable network hubs over fixed installations.
The U.S. Department of Defense zero-trust mandate, NATO STANAG interoperability protocols, and the EU Cybersecurity Act collectively reshape product standards by mandating cross-alliance cryptographic compatibility and supply-chain provenance documentation. The U.S. Federal Communications Commission and the UK National Cyber Security Centre enforce spectrum allocation and endpoint-hardening requirements that filter market access for non-compliant vendors. Stakeholders must monitor divergence between U.S. CMMC certification timelines and EU defense-funding conditionality as alliance procurement frameworks negotiate sovereign-cloud exceptions.
Market Dynamics
Defense procurement officers are compressing vendor qualification cycles as electromagnetic-contested environments demand hardened edge nodes with proven NATO STANAG interoperability before contract award.
Growth Catalysts
- U.S. DoD Zero-Trust Mandate:Pentagon acquisition directives now require continuous verification architectures, pulling secure-edge hardware into every networked weapons platform refresh cycle.
- Five Eyes Joint-Command Connectivity:Intelligence-sharing agreements between the United States, United Kingdom, and Australia are standardizing cryptographic modules across allied force structures.
- Legacy Platform Sensor Retrofits:Armored vehicle and maritime hull upgrade programs are embedding IoT arrays without full platform replacement, extending operational lifespans.
Market Restraints
- Classified Semiconductor Supply Concentration:Trusted foundry capacity for radiation-hardened chips concentrates in U.S. Department of Defense-accredited facilities with multi-year order backlogs.
- EU AI Act Algorithmic Transparency Requirements:Autonomous weapons-grade edge computing faces decoupling from conventional defense procurement pending certification of decision-audit trails.
- AES-256 Encryption Export Controls:Wassenaar Arrangement restrictions fragment supply chains as dual-use cryptographic components trigger jurisdiction-specific licensing delays.
Strategic Opportunities
- Australian Sovereign Guided Weapons Enterprise:Canberra's domestic manufacturing push creates demand for battle-networked production facilities with integrated sensor-to-shooter data links.
- Software-Defined Radio Convergence:Cognitive radio protocols merging with tactical IoT mesh networks enable dynamic spectrum allocation in contested electromagnetic environments.
- UK National Cyber Security Centre Endpoint Hardening:British certification schemes for military-grade device integrity are accelerating procurement of UK-manufactured naval sensor suites.
Industry Challenges
- MIL-STD-810 Shock Qualification Timelines:Environmental testing for battlefield-hardened nodes extends product development cycles by 18-24 months versus commercial IoT equivalents.
- Cross-Domain Solution Integration:Air-gapped legacy command systems require custom protocol bridges to ingest real-time sensor feeds without compromising classification boundaries.
- Supply-Chain Provenance Documentation:CMMC and EU defense-funding conditionality demand component-level traceability that many tier-two electronics suppliers cannot yet provide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military IoT Market |
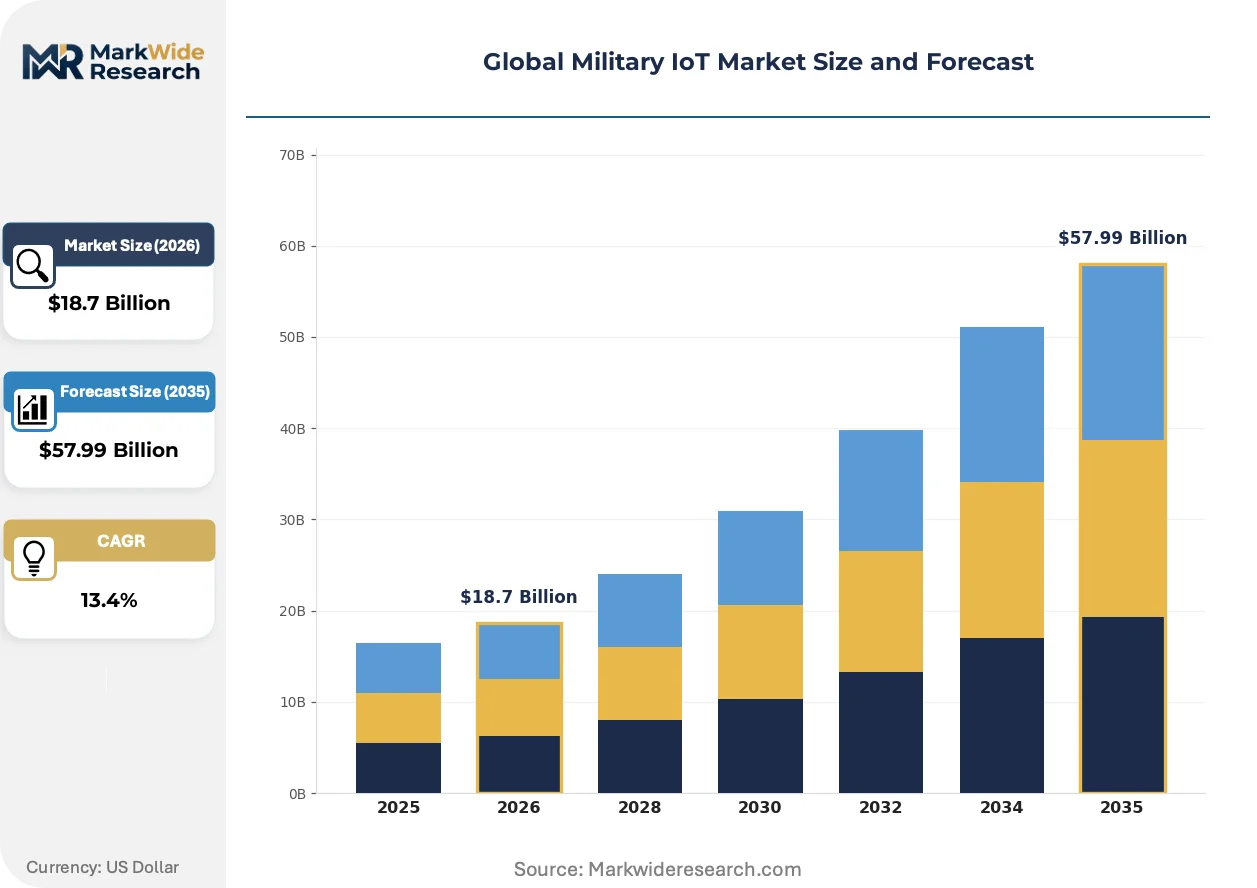
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Communication Devices, Surveillance Systems, Navigation Equipment, Command & Control Systems Application: Reconnaissance, Battlefield Monitoring, Asset Tracking, Personnel Management, Equipment Maintenance Deployment: Onboard Platforms, Portable Units, Fixed Installations, Mobile Command Centers, Remote Outposts End User: Defense Forces, Military Contractors, Intelligence Agencies, Homeland Security, Peacekeeping Organizations |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, Raytheon Technologies Corporation, Honeywell International Inc., Thales Group, L3Harris Technologies Inc., Boeing Company, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military IoT Market Shifts & Advancements
Battlefield data fusion architectures are compressing decision timelines from minutes to seconds, forcing hardware and software roadmaps to synchronize around low-latency edge inference rather than cloud-dependent analytics.
Software-defined mesh networking is expanding into expeditionary force structures as mobile command centers replace fixed installations. U.S. Marine Corps units are field-testing rapidly reconfigurable network hubs that self-heal when nodes are jammed or destroyed. This topology is compressing vendor qualification requirements toward modular, interchangeable radio and computing modules.
The EU AI Act is reshaping autonomous weapons procurement by mandating algorithmic transparency before NATO integration. European defense ministries are now requiring explainable decision trails for target-recognition systems, forcing suppliers to retrofit black-box neural networks with auditable logic layers. This compliance burden falls heaviest on unmanned aerial system integrators serving multinational force commands.
Buyer concentration around joint-program offices is consolidating vendor relationships as Five Eyes allies deepen shared procurement frameworks. Australian, British, and American defense acquisition executives are co-locating technical evaluation teams, replacing bilateral contracts with trilateral equipment certifications. This pooling is most visible in naval IoT sensor suites where sovereign-manufacturing requirements must now satisfy three national security clearances simultaneously.
Global Military IoT Market Segmentation
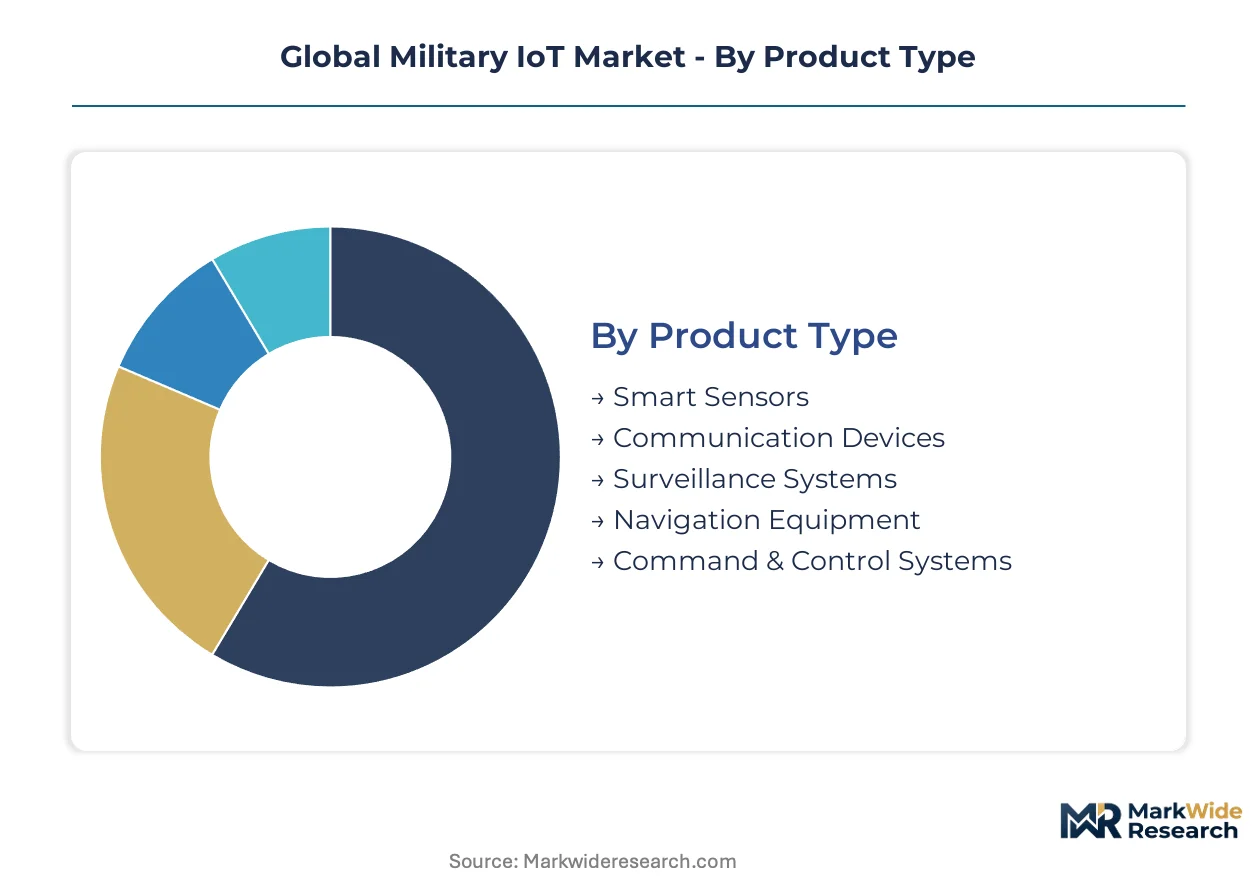
Military IoT procurement diverges sharply across product tiers and deployment contexts, with battlefield-hardened specifications and cryptographic certification requirements fragmenting vendor eligibility. Buyers prioritize NATO STANAG interoperability and zero-trust architecture compliance, creating distinct qualification barriers that reshape competitive dynamics within each segment cluster.
Product Type:
Defense procurement officers differentiate spending by technical maturity and retrofit urgency rather than platform novelty.
- Smart Sensors:Micro-electromechanical systems hardened to MIL-STD-810 shock specifications measure vibration, thermal, and acoustic signatures across armored vehicle hulls. Demand concentrates in the United States and United Kingdom as legacy platform retrofit cycles accelerate without full replacement programs.
- Surveillance Systems:Multi-spectral imaging arrays with edge-computing inference engines enable real-time target recognition in electromagnetic-contested environments. Procurement clusters around Five Eyes joint-command connectivity initiatives, with Australian sovereign manufacturing requirements adding certification complexity.
- Communication Devices:Software-defined radios with AES-256 encryption modules.
- Navigation Equipment:GPS-denied positioning systems using inertial measurement units.
- Command & Control Systems:Software-defined architecture platforms with cross-domain solution integration.
Smart Sensors lead volumes today; Command & Control Systems is gaining share fastest.
Application:
Mission-criticality and decision-timeline compression drive budget allocation across operational scenarios.
- Battlefield Monitoring:Distributed sensor-to-shooter networks fuse ground, aerial, and maritime feeds into unified situational awareness displays. Deployment concentrates in expeditionary force structures prioritizing rapid-reconfigurable network hubs over fixed command posts.
- Reconnaissance:Unmanned aerial and ground platforms with low-latency edge inference capabilities. Demand clusters in intelligence-sharing frameworks between the United States, United Kingdom, and Australia requiring trilateral equipment certifications.
- Asset Tracking:RFID and satellite-linked logistics monitoring for supply convoys.
- Personnel Management:Biometric wearables for health and location monitoring.
- Equipment Maintenance:Predictive analytics engines for platform lifecycle extension.
Battlefield Monitoring dominates current procurement; Reconnaissance shows the steepest expansion trajectory.
Deployment:
Force structure priorities between expeditionary mobility and fixed infrastructure protection determine procurement patterns.
- Mobile Command Centers:Rapidly deployable network hubs with self-healing mesh protocols replace fixed installations in contested electromagnetic environments. U.S. Marine Corps field-testing accelerates modular, interchangeable radio module demand.
- Onboard Platforms:Embedded IoT arrays within armored vehicles, maritime hulls, and aircraft without platform replacement. Procurement concentrates in legacy system upgrade programs extending operational lifespans.
- Portable Units:Dismounted soldier systems with hardened edge computing.
- Fixed Installations:Permanent command infrastructure with air-gapped legacy system integration.
- Remote Outposts:Autonomous power and communication nodes for forward operating bases.
Onboard Platforms anchor current spending; Mobile Command Centers is expanding most quickly.
End User:
Classification clearance levels and sovereign-manufacturing mandates fragment addressable markets.
- Defense Forces:National military services with full-spectrum procurement authority and NATO interoperability requirements. Spending concentrates in the United States, United Kingdom, and Australia under deepening joint-command frameworks.
- Intelligence Agencies:Signals intelligence and human intelligence operations requiring specialized cryptographic modules. Demand clusters around Five Eyes intelligence-sharing agreements standardizing equipment across allied structures.
- Military Contractors:Private sector support services with CMMC certification obligations.
- Homeland Security:Domestic surveillance and critical infrastructure protection agencies.
- Peacekeeping Organizations:Multinational forces with constrained budgets and interoperability needs.
Defense Forces lead volumes today; Intelligence Agencies is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Military IoT procurement originated from Cold War-era sensor networks developed by the United States Department of Defense, with subsequent standardization through NATO STANAG protocols spreading interoperable architectures across allied defense forces.
United States
The Pentagon's zero-trust mandate and CMMC certification timelines drive procurement of secure-edge hardware across every networked weapons platform. The Federal Communications Commission enforces spectrum allocation rules that filter market access for non-compliant vendors. Defense procurement concentrates around Washington D.C. corridor offices co-locating technical evaluation teams with Australian and British counterparts.
United Kingdom
Joint-command connectivity initiatives with Five Eyes allies standardize cryptographic modules across British force structures. The National Cyber Security Centre enforces endpoint-hardening requirements that accelerate procurement of sovereign-manufactured naval sensor suites. BAE Systems anchors sovereign-British manufacturing clusters in Lancashire and Bristol serving trilateral equipment certifications.
Australia
Canberra's Sovereign Guided Weapons Enterprise creates demand for battle-networked production facilities with integrated sensor-to-shooter data links. The country's defense-funding conditionality demands component-level traceability that reshapes supplier qualification cycles. Industrial activity clusters around Adelaide's defense technology precinct and Melbourne's systems integration hubs.
Germany
Rheinmetall and Bundeswehr modernization programs embed IoT arrays in legacy armored vehicle hulls without full platform replacement. EU AI Act algorithmic transparency requirements decouple autonomous weapons-grade edge computing from conventional procurement pending certification. Defense electronics manufacturing concentrates in Bavaria and Baden-Württemberg serving NATO interoperability mandates.
Israel
Israel Defense Forces field-test rapidly reconfigurable network hubs with self-healing mesh protocols in electromagnetic-contested environments. The country's national cybersecurity regulator enforces endpoint integrity standards that filter export-oriented vendor relationships. Tel Aviv and Haifa host specialized clusters in signals intelligence and unmanned systems integration serving intelligence agency procurement.
Global Military IoT Market Competitive Landscape
The competitive structure tilts toward defense-prime conglomerates with captive semiconductor supply chains and sovereign-manufacturing mandates. Tier-one contractors dominate secure-edge hardware procurement through multi-year indefinite-delivery contracts, while mid-tier specialists compete on NATO STANAG interoperability certification speed. Three archetypes prevail: primes with trusted foundry access, sovereign-national champions, and software-defined radio specialists. Consolidation through strategic partnerships and portfolio diversification into mesh-network protocols represents the dominant competitive vector.
Among U.S.-based defense primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the trusted-foundry archetype, occupying positions sustained by Department of Defense-accredited semiconductor facilities. BAE Systems represents the sovereign-national champion model, anchoring British manufacturing requirements while navigating trilateral certification demands across Five Eyes procurement frameworks.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Raytheon Technologies Corporation |
| Honeywell International Inc. |
| Thales Group |
| L3Harris Technologies Inc. |
| Boeing Company |
| General Dynamics Corporation |
| Others |
Supply & Pricing Matrix
The U.S. Department of Defense's zero-trust architecture mandate gates both qualified supply and premium-tier pricing access, as vendors must demonstrate continuous verification capabilities and NATO STANAG interoperability before contract award, compressing procurement cycles for certified hardware while excluding uncertified competitors from margin-rich defense programs.
Pricing Analysis
Three-tier pricing structure across MIL-SPEC certified, STANAG-compliant, and commercial-off-the-shelf levels dominates procurement frameworks, with differentiation driven by cryptographic certification grade and sovereign-manufacturing origin. Cost compression in the commercial-off-the-shelf tier is intensifying because electromagnetic-hardening requirements disqualify standard industrial IoT alternatives. Intelligence agencies exhibit the lowest price sensitivity due to mission-critical classification requirements, while peacekeeping organizations face acute budget constraints.
Supply Chain Analysis
Radiation-hardened semiconductor supply rests on U.S. Department of Defense-accredited foundries, Japanese specialty substrate producers, and Israeli signals-intelligence component specialists. Critical dependencies include gallium nitride substrates, trusted packaging facilities, and AES-256 cryptographic modules. Single-source vulnerability concentrates in classified chip fabrication, where multi-year order backlogs constrain surge capacity. Distribution runs through prime contractor integration facilities rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Military IoT Market functions as a stable compounder, with Five Eyes joint-command connectivity agreements driving steady procurement growth across allied defense modernization cycles.
For Market Incumbents: Anchor market position through captive semiconductor foundry investments that secure classified chip supply chains against multi-year order backlogs. Deepen NATO STANAG interoperability certification speed to outpace sovereign-national champions in trilateral procurement frameworks. Prioritize software-defined radio convergence R&D to capture dynamic spectrum allocation demand from expeditionary force structures.
For New Entrants and Emerging Players: Mid-tier military contractors with CMMC certification gaps represent the most penetrable buyer archetype, as prime vendor consolidation creates supply shortages in rapid-reconfigurable network hub components. Target Australian Sovereign Guided Weapons Enterprise integration opportunities where domestic manufacturing mandates favor new local partnerships. Pursue software-defined mesh networking module specialization as a go-to-market angle, leveraging modular interchangeability requirements from U.S. Marine Corps field-testing programs.
For Investors and Strategic Acquirers: Valuations sit cheapest among software-defined radio specialists lacking trusted foundry access but possessing NATO interoperability certifications. The five-to-ten year viability window favors acquisition targets with proven cross-domain solution integration capabilities and established relationships with joint-program offices. Watch EU AI Act algorithmic transparency enforcement timelines as the critical inflection signal for autonomous weapons-grade edge computing decoupling.
| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Foundry Capacity Expansion | U.S. Department of Defense accreditation secures classified semiconductor supply chains against multi-year order backlogs. |
| Software-Defined Radio Convergence | Cognitive radio protocol integration enables dynamic spectrum allocation in electromagnetic-contested environments. |
| NATO STANAG Interoperability Certification | Cross-alliance cryptographic compatibility unlocks Five Eyes joint-command connectivity procurement pools. |
| Zero-Trust Architecture Compliance | Continuous verification capabilities satisfy Pentagon acquisition directives across weapons platform refresh cycles. |
| Sovereign Manufacturing Partnership | Trilateral equipment certifications with Australian and British defense agencies access premium procurement tiers. |
Research Methodology
Coverage spans the United States, United Kingdom, Australia, Germany, and Israel, with primary inputs from each defense procurement corridor combining interviews with program office acquisition executives, platform engineering directors at prime contractors, signals intelligence technical leads, and semiconductor supply chain managers. Secondary validation draws from U.S. Department of Defense budget justification documents, NATO standardization office publications, EU defense-funding conditionality filings, and customs trade data for dual-use electronic components. Bottom-up segment sizing and top-down macroeconomic triangulation reconcile volume and value estimates.
Granularity-level modeling disaggregates the analysis window by product type, application mission context, deployment mobility class, and end-user classification clearance tier, with additional dimensional depth around cryptographic certification grade and sovereign-manufacturing origin. CAGRs derive from segment-level growth trajectory synthesis applied across the projection horizon. Defense procurement cycle timing and electromagnetic-hardening specification adoption curves inform industry-specific forecast inputs.
Inputs from classified program office briefings were available through the study window; gaps in forward-year defense budget appropriations introduce uncertainty bands around expeditionary force structure equipment forecasts. Assumptions underlying projections reflect current NATO interoperability mandates and zero-trust architecture implementation timelines. A small set of named triggers—EU AI Act enforcement severity, trusted foundry capacity expansion announcements, and Five Eyes procurement framework consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Iiot (Industrial Internet of Things) Technology Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
Enterprise IoT Market
Internet of Things (IoT)
IoT Software Engineering Market