
 ADAS Sensors Market | 2026-2036
ADAS Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
ADAS Sensors Market Analysis
German Tier-1 component manufacturing is restructuring around high-resolution imaging radar and solid-state lidar capacity to serve escalating OEM integration timelines. Robert Bosch GmbH leverages captive semiconductor sourcing through its wafer fabs to secure sensor module supply. Continental AG anchors European camera-system production with dedicated cleanroom assembly lines in Lower Saxony. Denso Corporation competes through thermal management integration, bundling sensor cooling with its powertrain electronics footprint.
ADAS sensors are electromechanical detection devices—encompassing radar emitters, CMOS image sensors, MEMS ultrasonic transducers, and scanning lidar units—that measure proximity, velocity, and object classification to enable automated vehicle intervention. Camera modules dominate unit volume due to their role in lane-keeping and traffic-sign recognition, though lidar commands premium positioning in robotaxi and highway-pilot configurations where centimeter-range accuracy proves essential. Electric vehicle platforms are absorbing sensor suites fastest, as skateboard architectures free frontal surface area previously occupied by internal-combustion hardware, enabling cleaner sensor placement and reduced electromagnetic interference.
NHTSA in the United States mandates automatic emergency braking on all new light vehicles, compelling OEMs to standardize radar and camera fusion across model lineups. The EU General Safety Regulation requires intelligent speed assistance and lane-keeping systems, embedding sensor hardware into type-approval baselines for European sales. Euro NCAP testing protocols reward advanced pedestrian detection, pushing suppliers toward higher-resolution radar and supplemental lidar coverage. Stakeholders must track how software-defined vehicle architectures reshape sensor fusion from discrete hardware modules to centralized compute platforms with raw-data feeds.
Market Dynamics
OEM procurement of radar and camera modules for Level 2+ autonomy is compressing integration timelines and forcing Tier-1 suppliers to restructure manufacturing footprints around high-resolution imaging radar and solid-state lidar capacity.
Growth Catalysts
- EU General Safety Regulation:Mandates intelligent speed assistance and lane-keeping systems, embedding sensor hardware into type-approval baselines for European vehicle sales.
- Electric vehicle platforms:Skateboard architectures free frontal surface area previously occupied by internal-combustion hardware, enabling cleaner sensor placement and reduced electromagnetic interference.
- Highway-pilot configurations:Centimeter-range accuracy requirements in robotaxi and highway-autonomy applications pull premium lidar demand beyond traditional camera-radar fusion.
Market Restraints
- Semiconductor supply concentration:Captive wafer fab access differentiates Tier-1 suppliers, leaving module assemblers exposed to silicon allocation volatility.
- Raw sensor data bandwidth:Software-defined vehicle architectures strain in-vehicle networking infrastructure, delaying centralized compute platform rollouts.
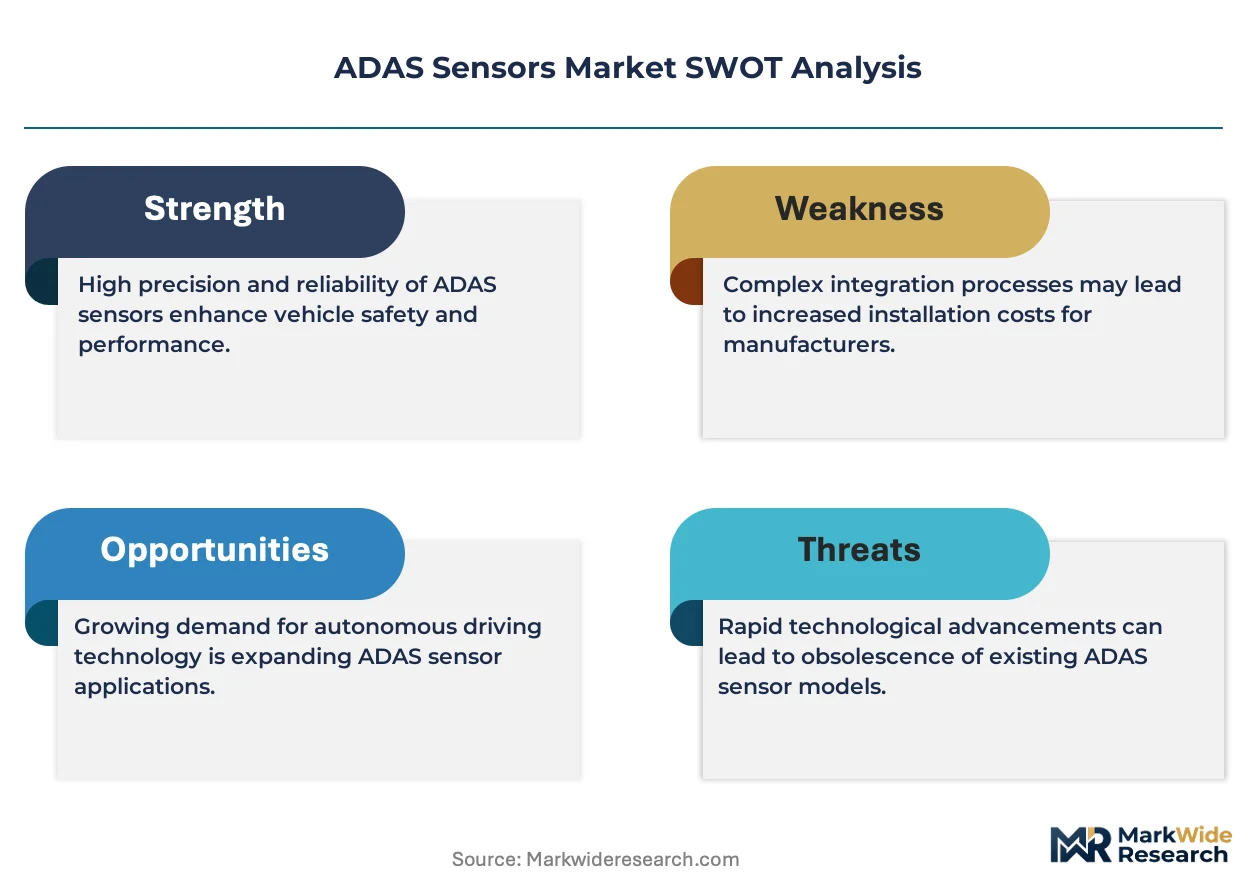
- Technical limitation in adverse weather:Camera and lidar performance degradation in heavy precipitation forces redundant radar coverage, inflating per-vehicle sensor counts and costs.
Strategic Opportunities
- India's PLI scheme for automotive components:Localized sensor module assembly incentives attract Tier-1 investment to serve domestic OEM expansion and export markets.
- Thermal management integration:Bundling sensor cooling with powertrain electronics footprints opens differentiation for suppliers with existing HVAC and battery thermal expertise.
- 4D imaging radar convergence:Elevation-measurement capability narrows the performance gap with entry lidar, creating substitution opportunity in mid-tier autonomy packages.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D validation for sensor fusion algorithms extends development cycles and strains software engineering capacity.
- Legacy vehicle platform integration:Retrofitting centralized compute architectures into existing electrical-electronic architectures requires costly gateway and wiring harness redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ADAS Sensors Market |
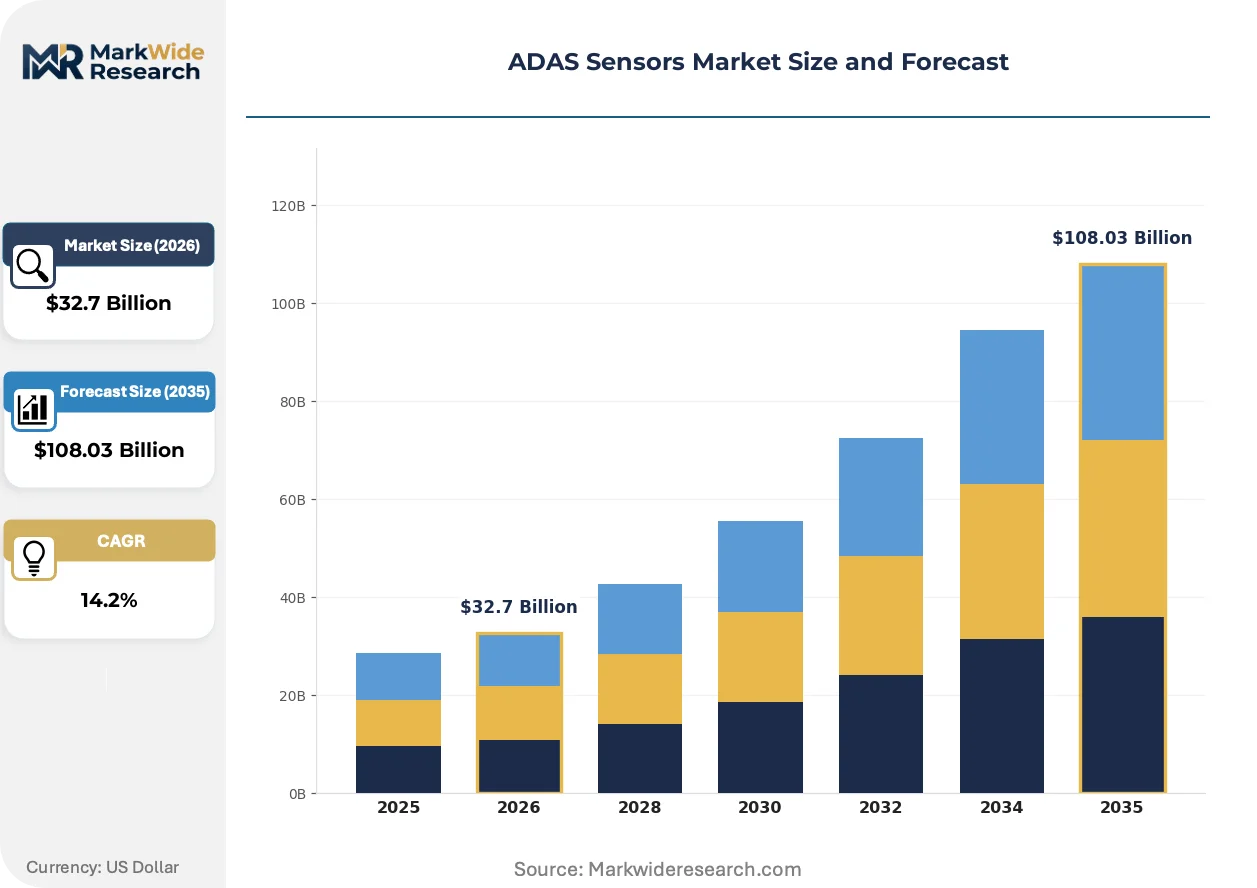
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $108.03 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Radar, Lidar, Camera, Ultrasonic Vehicle Type: Sedan, SUV, Truck, Electric Vehicle Application: Adaptive Cruise Control, Lane Keeping Assist, Collision Avoidance, Parking Assistance End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Magna International, Valeo, ZF Friedrichshafen, Infineon Technologies, NXP Semiconductors, Mobileye, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ADAS Sensors Market Emerging Trajectories
Sensor fusion architectures are migrating from discrete hardware modules feeding distributed electronic control units toward centralized compute platforms ingesting raw data streams, compressing the value capture locus upstream to semiconductor and software layers.
4D imaging radar is consolidating elevation-measurement capability alongside range, velocity, and azimuth detection into single-chip solutions. Tier-1 suppliers are adopting these systems for highway-pilot and urban-autonomy programs to reduce lidar dependency. This consolidation is compressing the price-performance gap between premium radar and entry-level lidar, reshaping tiering strategies across OEM sensor suites.
NHTSA mandates automatic emergency braking on all new light vehicles in the United States, compelling standardization of radar-camera fusion across model lineups. The rule eliminates hardware differentiation at the base trim level, pushing suppliers toward software-enabled feature upgrades. Mid-market OEMs are responding by locking multi-year module supply agreements to secure allocation ahead of compliance deadlines.
Fleet operators and mobility-as-a-service providers are compressing procurement cycles for pre-integrated sensor suites rather than discrete components. This disintermediates traditional distribution channels and forces direct Tier-1 relationships with end-users. The shift is most visible in North American robotaxi deployments, where vehicle-as-a-service contracts bundle sensor hardware, software licenses, and over-the-air update infrastructure into single procurement vehicles.
ADAS Sensors Market Segmentation
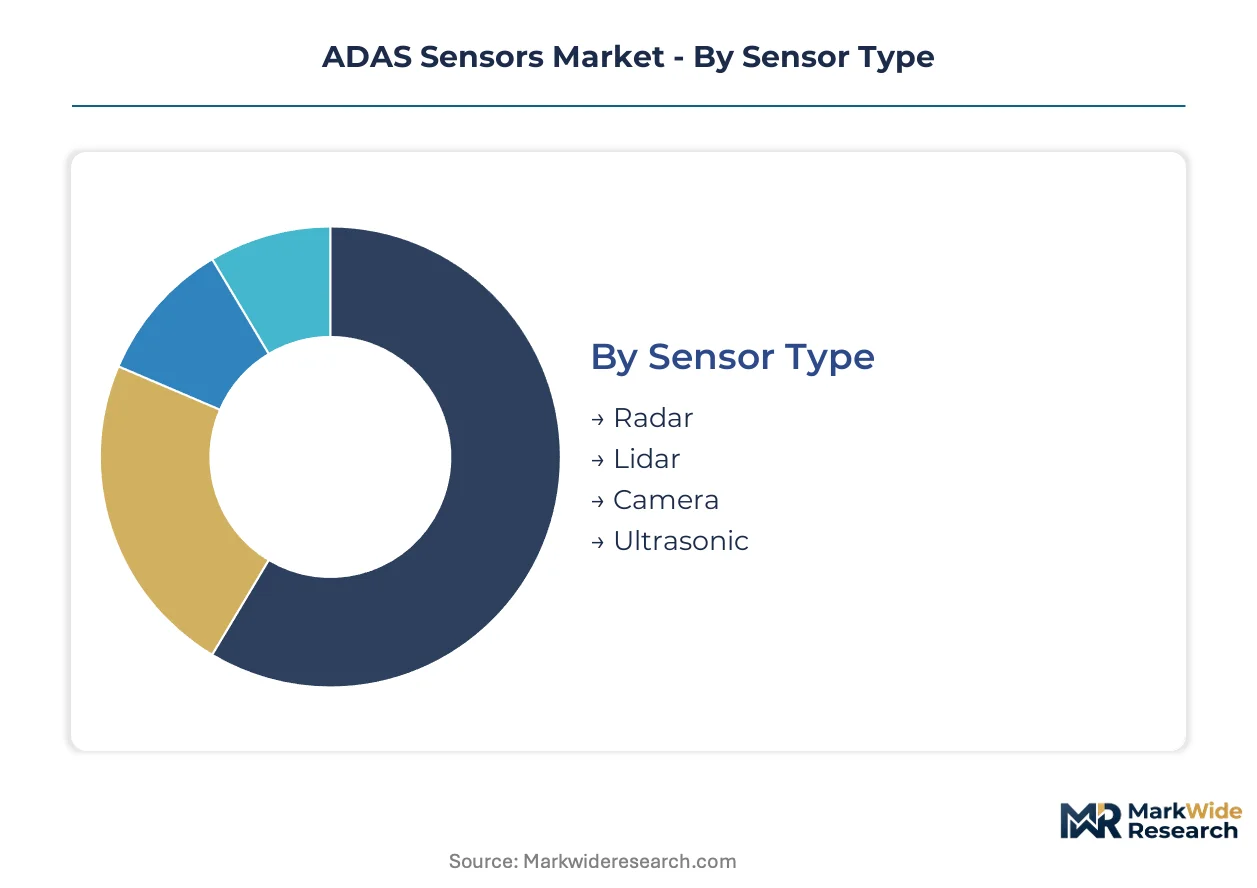
ADAS sensor procurement splits across hardware modality, vehicle architecture, and functional integration depth. OEMs configure sensor suites differently for mass-market compliance versus premium autonomy tiers, creating distinct volume and margin pools within each segment dimension.
Sensor Type:
Standardization dominates radar and ultrasonic modules, while lidar and high-resolution cameras retain customization for premium positioning.
- Radar:77GHz and 79GHz frequency-modulated continuous-wave emitters form the backbone of adaptive cruise and automatic emergency braking. German Tier-1 suppliers anchor European production, with Bosch leveraging captive semiconductor sourcing to secure allocation. Demand concentrates in highway-pilot configurations where long-range detection proves essential.
- Camera:CMOS image sensors with 2-8 megapixel resolution enable lane-keeping and traffic-sign recognition across vehicle classes. Euro NCAP pedestrian-detection protocols push suppliers toward higher dynamic range and low-light performance. Volume leadership stems from mandatory fitment on all new European and US light vehicles.
- Lidar:Solid-state and mechanically scanning units deliver centimeter-range accuracy for robotaxi deployments. Premium positioning limits volume to highway-autonomy and urban-pilot programs.
- Ultrasonic:MEMS transducers handle low-speed parking and proximity detection at lowest per-unit cost. Standardization is complete across OEM lineups.
Leading the category by volume: Camera. Growing fastest: Lidar.
Vehicle Type:
Electric vehicle platforms absorb sensor suites fastest due to packaging advantages, while internal-combustion segments retrofit around legacy electrical architectures.
- Electric Vehicle:Skateboard architectures free frontal surface area for cleaner sensor placement and reduced electromagnetic interference. NHTSA mandates in the United States and EU General Safety Regulation compel standardized radar-camera fusion regardless of powertrain.
- SUV:Higher ride height and larger frontal area accommodate redundant sensor coverage for premium autonomy tiers. North American and Chinese OEMs prioritize this segment for first-wave Level 2+ deployment.
- Sedan:Aerodynamic constraints limit sensor housing dimensions, favoring compact solid-state lidar and integrated camera-radar modules.
- Truck:Commercial vehicle duty cycles demand enhanced thermal management and vibration resistance in sensor modules. Fleet operator procurement concentrates in highway-corridor freight corridors.
Volume concentration: Electric Vehicle. Steepest expansion trajectory: SUV.
Application:
Regulatory mandates standardize collision avoidance and adaptive cruise, while parking assistance and advanced lane-keeping retain feature-differentiation potential.
- Collision Avoidance:Automatic emergency braking mandates from NHTSA embed radar and camera fusion as baseline equipment. Module standardization eliminates hardware differentiation at entry trim levels.
- Adaptive Cruise Control:Stop-and-go functionality in urban traffic requires sensor fusion with predictive algorithms. Highway-pilot configurations pull demand toward 4D imaging radar with elevation measurement.
- Lane Keeping Assist:Camera-dominant systems face performance degradation in adverse weather, forcing supplemental radar coverage and inflating per-vehicle sensor counts.
- Parking Assistance:Ultrasonic and short-range camera fusion handles low-speed maneuvering. Aftermarket retrofit demand concentrates in aging vehicle fleets without factory-fit sensors.
Deepest market penetration: Collision Avoidance. Gaining share fastest: Lane Keeping Assist.
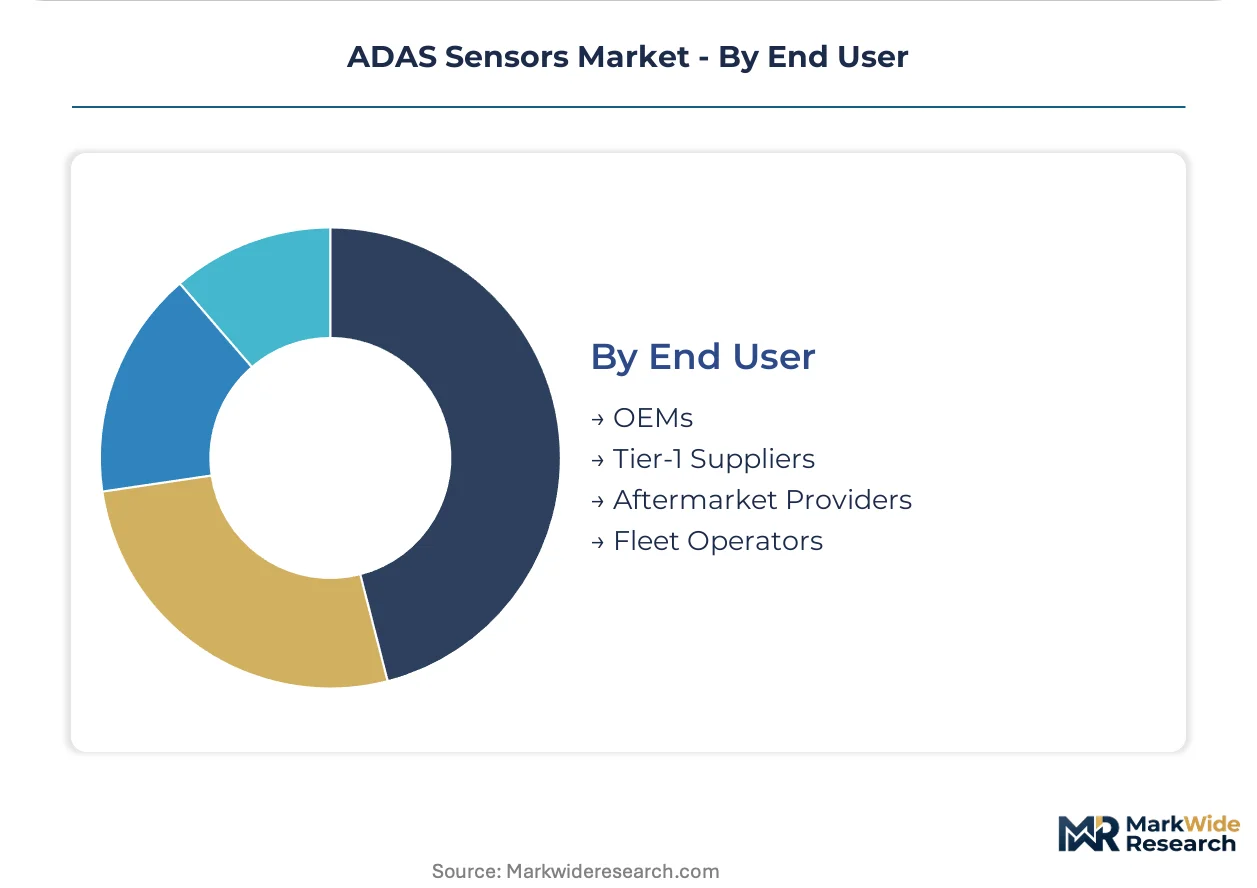
End User:
Procurement authority is shifting from discrete component sourcing toward pre-integrated sensor suite contracts, compressing traditional distribution channels.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz anchor European sensor demand through direct Tier-1 relationships. Multi-year module supply agreements lock allocation ahead of compliance deadlines.
- Tier-1 Suppliers:Bosch, Continental, and ZF manufacture sensor modules for captive OEM fitment and open-market supply. Cleanroom assembly lines in Lower Saxony and Baden-Württemberg anchor European production.
- Fleet Operators:Mobility-as-a-service providers bundle sensor hardware, software licenses, and over-the-air infrastructure into single procurement vehicles. Robotaxi deployments in California and Arizona drive concentrated demand.
- Aftermarket Providers:Retrofit sensor kits serve aging vehicle pools without factory ADAS equipment. Technical limitation in adverse weather and calibration complexity constrain growth.
Controlling largest procurement volume: OEMs. Expanding most quickly: Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German semiconductor fabs in Dresden and Reutlingen supply silicon wafers that anchor European sensor module production. Wafer output from these facilities feeds cleanroom assembly lines across the continent.
United States
NHTSA mandates automatic emergency braking on all new light vehicles, compelling radar-camera fusion standardization. The IRA supports domestic semiconductor fabrication for automotive applications. Detroit anchors Tier-1 supplier engineering centers serving North American OEM compliance timelines.
Germany
Bosch and Continental drive procurement concentration for Level 2+ autonomy modules. The EU General Safety Regulation embeds intelligent speed assistance into type-approval baselines. Lower Saxony hosts dedicated cleanroom assembly lines for European camera-system production.
China
Domestic OEMs accelerate highway-pilot deployments pulling premium lidar demand. MIIT oversees GB standards for vehicle safety system certification. Yangtze River Delta clusters concentrate solid-state lidar manufacturing capacity for robotaxi programs.
Japan
Denso bundles sensor cooling with powertrain electronics leveraging thermal management expertise. METI coordinates automotive semiconductor supply security initiatives. Nagoya anchors Tier-1 supplier integration of MEMS ultrasonic transducers into parking assistance systems.
India
Domestic OEM expansion and export market access drive sensor module assembly localization. The PLI scheme for automotive components attracts Tier-1 manufacturing investment. Tamil Nadu and Gujarat host emerging cleanroom facilities serving ASEAN re-export demand.
ADAS Sensors Market Vendor Landscape
Global majors compete with regional champions across semiconductor supply and module assembly capacity. The supplier base organizes into captive fab operators, module integrators with cleanroom assets, and semiconductor specialists licensing sensor fusion algorithms. Consolidation concentrates around German and Japanese Tier-1 manufacturers with backward integration into silicon sourcing. Dominant competitive moves include multi-year supply agreement lock-ins ahead of regulatory deadlines and thermal management bundling to differentiate module offerings.
Among German-based Tier-1 suppliers, Robert Bosch GmbH and Continental AG exemplify the captive semiconductor archetype through wafer fab ownership. Denso Corporation represents the thermal integration specialist model, leveraging powertrain electronics footprints for sensor cooling. These three anchors demonstrate how geographic clustering around semiconductor fabrication and cleanroom assembly shapes competitive positioning in European and Asian supply chains.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Magna International |
| Valeo |
| ZF Friedrichshafen |
| Infineon Technologies |
| NXP Semiconductors |
| Mobileye |
| Others |
Supply Flow & Price Mechanics
4D imaging radar convergence into single-chip solutions is compressing unit economics while concentrating procurement leverage among captive semiconductor operators. This technology transition simultaneously deflates per-sensor costs and locks module assemblers into allocation-dependent pricing tiers.
Pricing Analysis
Service bundling separates warranty-backed calibration packages from bare-module transactions, with OEMs absorbing integration risk for premium positioning. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 26262 ASIL certification grades and volume commitment scale. Cost compression in entry-level radar-camera fusion intensifies because NHTSA mandates eliminate hardware differentiation at base trim. Fleet operators exhibit lowest price sensitivity due to bundled software-license procurement, while aftermarket retrofit channels face acute margin pressure from calibration complexity.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese wafer fab output feeding European cleanroom assembly. Geographic concentration centers on Germany, Japan, and Taiwan for semiconductor fabrication and module integration. Raw material dependencies span silicon wafers, CMOS image sensors, and rare-earth magnetics for MEMS transducers. Tariff exposure on Chinese-sourced lidar components threatens cost predictability for robotaxi programs. Distribution runs through direct Tier-1 contracts with OEM platform engineers, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from semiconductor allocation volatility is forcing module assemblers without captive fab access toward exit or acquisition.
For Market Incumbents: Anchor backward integration into wafer fabrication or secure multi-year allocation agreements with foundry partners to defend against 4D imaging radar substitution. Lock cleanroom capacity expansion in Lower Saxony and Tamil Nadu ahead of EU General Safety Regulation compliance deadlines. Prioritize thermal management bundling to differentiate from pure-play sensor module competitors. For New Entrants and Emerging Players: Begin with India's PLI scheme localized assembly incentives to capture ASEAN re-export demand without competing for German Tier-1 relationships. Target aftermarket parking assistance retrofit channels where calibration complexity has deterred incumbent investment. Pursue direct fleet operator contracts bypassing OEM procurement gatekeepers. For Investors and Strategic Acquirers: Exit pathways concentrate in captive-fab Tier-1 acquisition by semiconductor majors seeking automotive vertical integration. Long-term viability favors suppliers with in-house silicon sourcing and software-defined vehicle architecture alignment. Watch 4D imaging radar substitution rates in mid-tier autonomy packages as inflection indicator for lidar demand destruction.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Wafer Fab Investment | Bosch's Dresden facility secures sensor module allocation against semiconductor volatility. |
| Cleanroom Assembly Localization | Tamil Nadu facilities serve India's PLI scheme and ASEAN export demand. |
| Thermal Management Bundling | Denso leverages powertrain electronics footprints for sensor cooling integration. |
| 4D Imaging Radar Adoption | Elevation-measurement capability narrows performance gap with entry lidar systems. |
| Fleet Operator Direct Contracts | Robotaxi deployments in California bundle hardware, software, and OTA infrastructure. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operator technology officers. NHTSA rulemaking dockets, EU type-approval databases, MIIT GB standard releases, and semiconductor trade flow statistics provided validation layers. Bottom-up sensor unit shipment estimates triangulated against top-down OEM production forecasts across vehicle architecture segments.
Data-stream reconciliation between vehicle production databases, IHS Markit registration statistics, and supplier revenue disclosures shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass sensor modality, vehicle propulsion architecture, content per vehicle tier, OEM premium-mass-market positioning, and regional production cluster. CAGRs derived from slope analysis of historical penetration curves adjusted for regulatory mandate phase-in schedules and technology substitution elasticities.
Regulatory delay, technology substitution acceleration, and semiconductor supply disruption are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on mandate compliance timelines and sensor fusion architecture migration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Microsensor Market