
 Europe Conveyors Market | 2026-2036
Europe Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Conveyors Market Foresight
German conveyor manufacturers is rebalancing capacity toward modular automated systems as labor costs across Central Europe climb. SSI Schaefer AG leverages its intralogistics integration depth to anchor large-scale warehousing projects. Daifuku Co. Ltd. competes through technology leadership in sortation and distribution center automation. Vanderlande Industries B.V. specializes in airport baggage handling and parcel sortation, occupying a defensible niche with high engineering barriers.
Europe conveyors are mechanical handling devices engineered to move bulk materials or discrete units along predetermined paths, typically employing belts, rollers, chains, or buckets with load capacities ranging from light parcel handling to heavy industrial tonnage per hour. Their primary purpose is eliminating manual transport, reducing cycle times, and enabling continuous flow in manufacturing and distribution environments. Belt conveyors dominate food processing applications where sanitary stainless steel construction and washdown compatibility command premium positioning. Automated technology segments are expanding fastest as warehouses adopt AS/RS integration and real-time control systems. Roller conveyors remain mature in automotive assembly, where standardized pallet dimensions and predictable throughput favor proven mechanical designs.
The EU Machinery Directive, CE marking requirements, and REACH chemical safety standards govern conveyor design, mandating emergency stop systems, guarding, and material traceability for belts and lubricants. EMA and national regulators like Germany's KBA indirectly shape demand through pharmaceutical and automotive quality protocols that require validated material handling equipment. Stakeholders must monitor how the EU AI Act and evolving cybersecurity standards for smart conveyors will alter software architecture and supplier liability frameworks.
Market Dynamics
Automation investments across Central European manufacturing corridors are compressing deployment timelines for modular conveyor systems, while CE marking and EU Machinery Directive compliance costs filter smaller fabricators from tender processes.
Growth Catalysts
- EU Machinery Directive safety mandates:Emergency stop integration and documented risk assessments are forcing facility upgrades across automotive assembly plants in Bavaria.
- E-commerce fulfillment density:Parcel sortation throughput requirements are accelerating belt conveyor replacements in Polish and Czech distribution hubs.
- Stainless steel sanitary construction:Food processors in Denmark and the Netherlands are specifying washdown-compatible belt systems for dairy and meat handling lines.
Market Restraints
- Steel and aluminum input volatility:Roller conveyor fabricators face margin compression from energy-intensive metal pricing swings.
- German supplier concentration:Critical drive component sourcing clusters around Baden-Württemberg engineering networks, creating single-region exposure.
- REACH chemical compliance:Belt polymer formulations and lubricant traceability requirements extend qualification cycles for new material introductions.
Strategic Opportunities
- Portugal and Spain warehousing expansion:Underpenetrated Iberian logistics markets offer first-mover positioning for AS/RS-integrated conveyor installations.
- EU AI Act smart conveyor provisions:Cybersecurity and algorithmic transparency standards create service attach opportunities for software-enabled maintenance contracts.
- Pharmaceutical cold chain convergence:Temperature-monitored belt systems are penetrating vaccine distribution networks in Belgium and Ireland.
Industry Challenges
- Mechatronics technician scarcity:Servo drive programming and PLC integration skills are bottlenecking deployment velocity in Eastern European manufacturing zones.
- Legacy mechanical retrofit complexity:Pneumatic roller systems in mature automotive plants resist seamless integration with Ethernet/IP control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Conveyors Market |
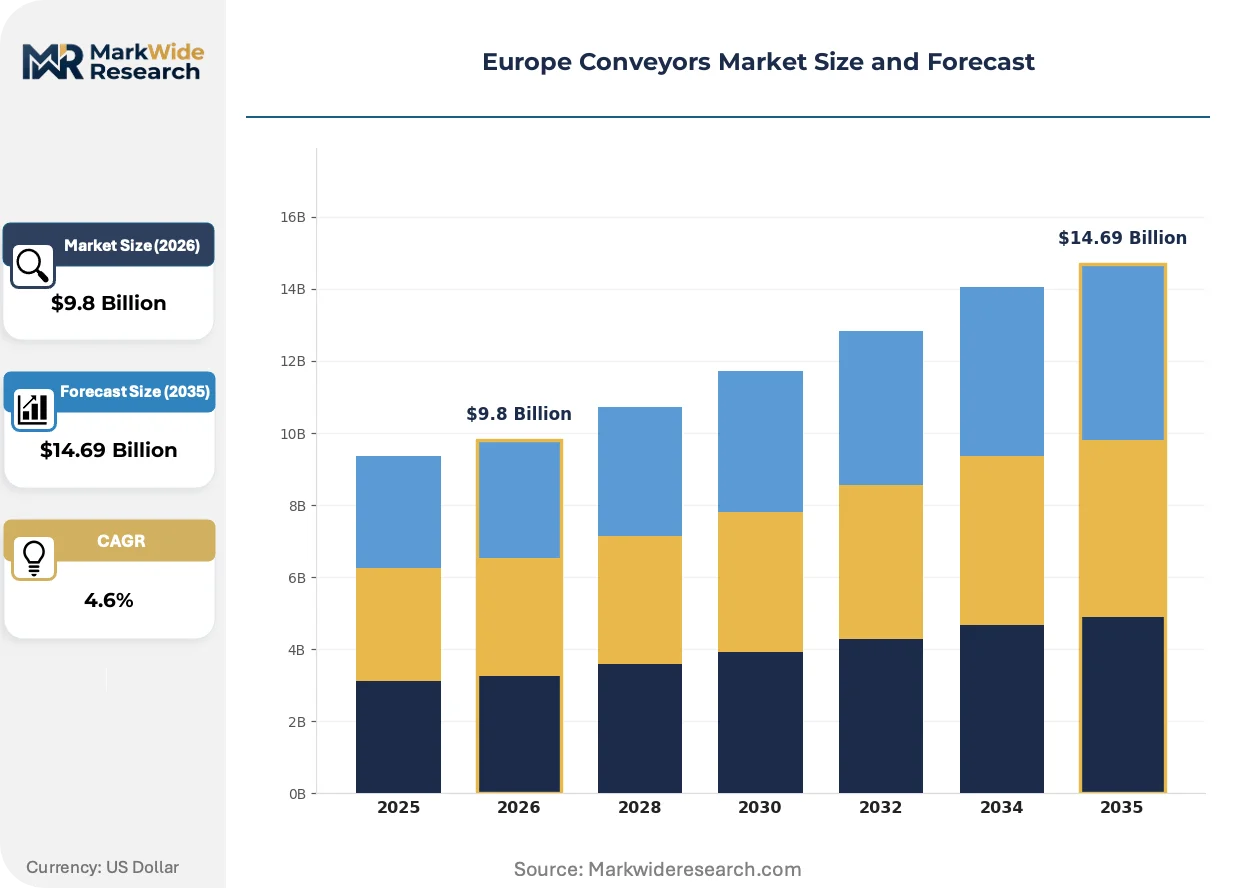
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Conveyor, Roller Conveyor, Chain Conveyor, Bucket Conveyor Application: Manufacturing, Warehousing, Food Processing, Packaging End User: Automotive, Retail, Aerospace, Pharmaceuticals Technology: Automated, Manual, Hybrid, Smart |
| Companies Covered | SSI Schaefer AG, Daifuku Co. Ltd., Dematic GmbH, Vanderlande Industries B.V., KNAPP AG, Swisslog AG, Beumer Group GmbH and Co. KG, Mecalux S.A., Interroll Holding AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Conveyors Market Shifts & Advancements
Digital thread technologies are redefining conveyor lifecycle economics, compressing the boundary between mechanical hardware and software-defined control planes across European industrial facilities.
Edge computing nodes embedded at drive motor terminals are integrating vibration analytics and thermal monitoring into predictive maintenance workflows. Automotive manufacturers in Stuttgart and Wolfsburg are deploying these systems at scale. The technology is integrating formerly siloed operational data into centralized MES platforms, collapsing response latency for fault detection.
REACH chemical safety standards are tightening material disclosure requirements for belt polymers and synthetic lubricants used in food-contact applications. Compound suppliers must now document full substance inventories through the supply chain. Food processing equipment builders in northern Italy and Denmark are reformulating specifications to preempt registration bottlenecks.
After-sales service unbundling is fragmenting traditional full-service contracts into discrete software subscriptions and on-demand technical interventions. Third-party maintenance aggregators are capturing mid-market warehousing accounts in France and Poland. This shift is most pronounced among e-commerce fulfillment operators with standardized roller conveyor footprints and limited in-house technical staff.
Europe Conveyors Market Segmentation
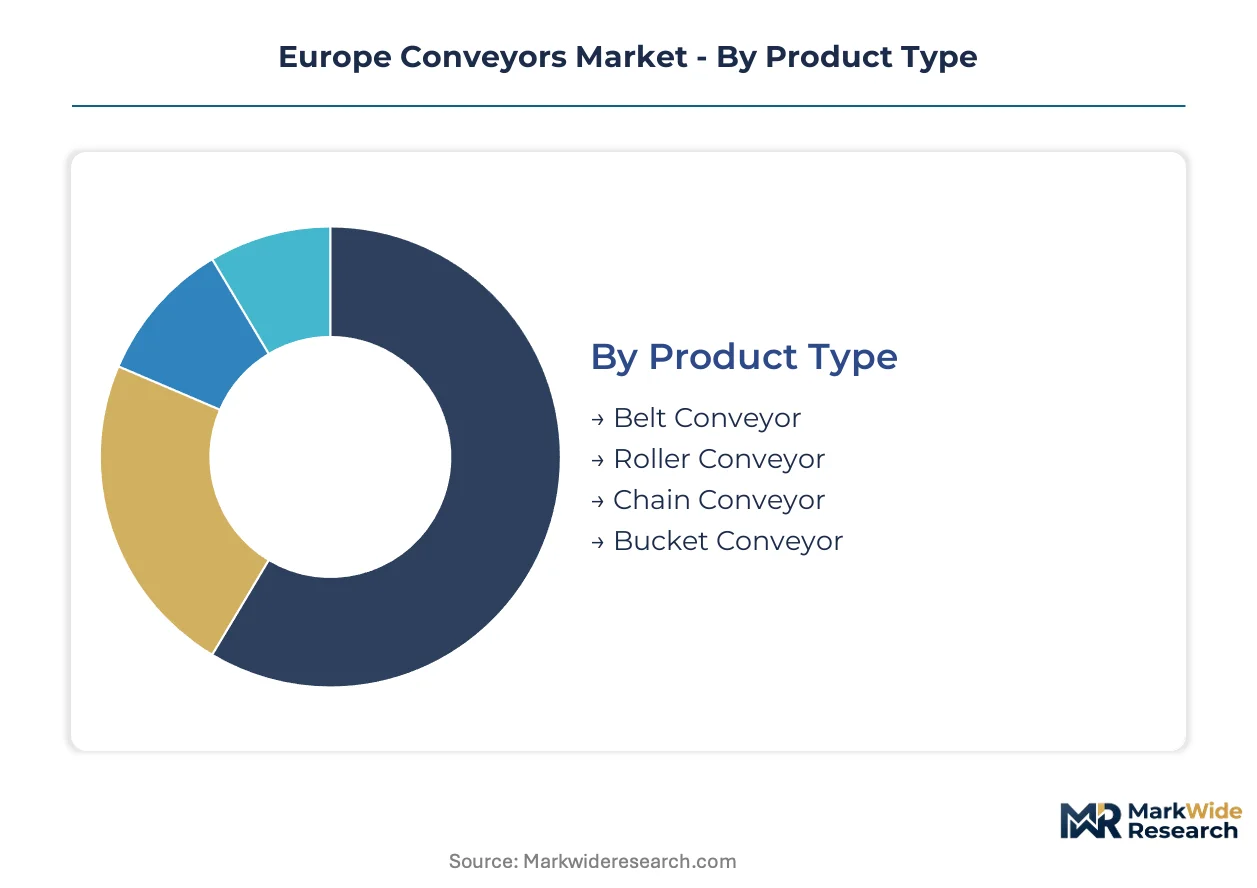
Conveyor procurement decisions across Europe cluster around certification burdens and integration complexity. Each segmentation dimension carries distinct compliance obligations under the EU Machinery Directive and CE marking frameworks.
Product Type:
Belt conveyors demand REACH-compliant polymer formulations and stainless steel sanitary grades for food-contact approvals. Roller systems face lighter material disclosure requirements but heavier mechanical safety documentation.
- Belt Conveyor:Fabric or modular plastic belts with load ratings from light parcel handling to heavy bulk tonnage. Danish dairy processors and Dutch meat packers are specifying washdown-compatible stainless steel constructions to satisfy EFSA hygiene protocols. CE marking for these systems requires documented risk assessments for pinch points and emergency stop integration.
- Roller Conveyor:Gravity or powered roller beds designed for standardized pallet dimensions and predictable throughput. Automotive assembly plants in Bavaria and Baden-Württemberg dominate demand as OEMs compress cycle times through mechanized pallet transfer. The segment carries lighter material compliance burdens but intensive mechanical guarding requirements.
- Chain Conveyor:Heavy-duty linked chains for abrasive or high-temperature materials.
- Bucket Conveyor:Vertical lifting systems for granular bulk handling in agricultural and mineral processing.
Leading the category by volume: Roller Conveyor. Growing fastest: Belt Conveyor.
Application:
Cost tier stratification separates capital-intensive automated installations from standardized mechanical replacements. Food processing commands premium pricing for sanitary construction and chemical traceability.
- Manufacturing:Continuous flow systems integrated with production line pacing and quality checkpoints. German automotive corridors in Stuttgart and Wolfsburg anchor demand as OEMs expand automated material handling to offset Central European labor cost inflation.
- Warehousing:High-throughput sortation and distribution center automation. Polish and Czech e-commerce hubs are accelerating belt conveyor replacements to match parcel density growth. These installations prioritize speed over sanitary certification, compressing qualification cycles.
- Food Processing:Stainless steel construction with washdown compatibility for dairy, meat, and beverage handling. EFSA and national regulators in Denmark and the Netherlands mandate full material traceability for belt polymers and lubricants, extending procurement timelines.
- Packaging:End-of-line accumulation and palletizing systems with standardized footprints.
Dominating procurement value: Manufacturing. Expanding most quickly: Warehousing.
End User:
Customer type determines service attachment rates and software integration depth. Pharmaceutical buyers demand validated equipment with audit trails; retail operators prioritize rapid deployment and modular scalability.
- Automotive:Precision-timed conveyor networks synchronized with assembly sequencing. BMW, Volkswagen, and Mercedes-Benz suppliers in Bavaria and Baden-Württemberg are upgrading legacy pneumatic roller systems to Ethernet/IP architectures. KBA quality protocols indirectly shape equipment specifications through tier-one supplier mandates.
- Retail:Seasonal volume flexibility and rapid reconfiguration for promotional cycles. French and Polish e-commerce fulfillment operators are unbundling after-sales service into discrete software subscriptions and on-demand technical interventions.
- Aerospace:Specialized handling for large components with strict dimensional tolerances.
- Pharmaceuticals:Validated material handling with temperature monitoring and batch traceability. EMA quality protocols require documented equipment qualification, creating sticky supplier relationships and extended contract terms.
Commanding highest equipment value per meter: Automotive. Steepest expansion trajectory: Pharmaceuticals.
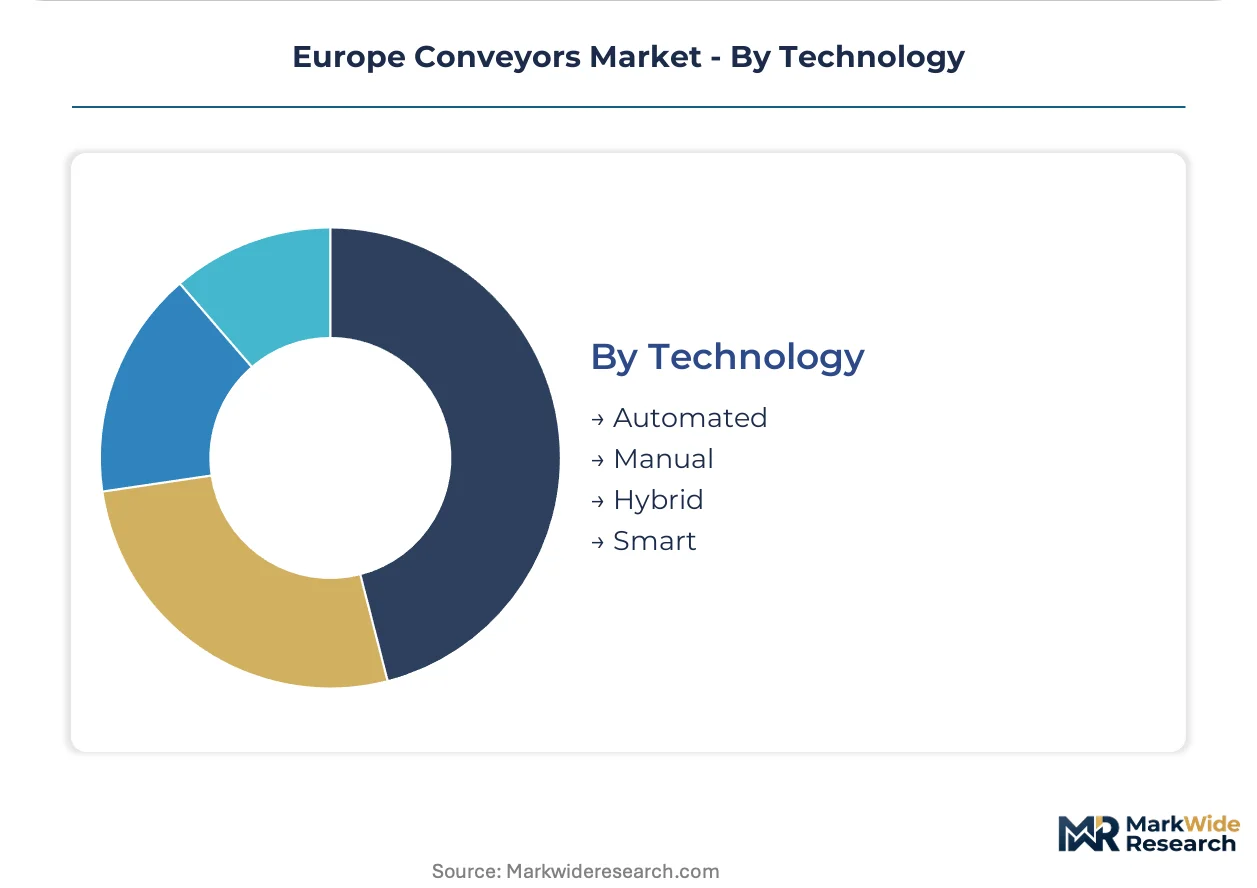
Technology:
Maturity gradients separate established mechanical designs from emerging software-defined control planes. Smart systems face emerging EU AI Act compliance obligations for algorithmic transparency and cybersecurity.
- Automated:AS/RS-integrated conveyor networks with real-time control and predictive maintenance capabilities. Edge computing nodes at drive motor terminals are penetrating Stuttgart and Wolfsburg automotive plants, collapsing fault detection latency through vibration analytics and thermal monitoring.
- Manual:Gravity or basic powered systems without centralized control. These systems face margin compression but persist in low-throughput applications and temporary installations where capital constraints outweigh efficiency gains.
- Hybrid:Mechanical conveyors with retrofitted sensor packages and partial automation.
- Smart:Software-defined control planes with AI-driven optimization and autonomous rerouting. The EU AI Act's cybersecurity and algorithmic transparency standards are creating service attach opportunities for software-enabled maintenance contracts, particularly in Belgian and Irish pharmaceutical distribution networks.
Installed base leader: Automated. Gaining share fastest: Smart.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and aluminum feedstock corridors across the Ruhr and Saarland anchor conveyor fabrication capacity, while finished system integration clusters in southern German engineering belts.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are retrofitting legacy pneumatic roller systems with Ethernet/IP control architectures. KBA quality protocols cascade through tier-one supplier networks, mandating validated material handling equipment. Bavarian and Baden-Württemberg manufacturing corridors concentrate demand for precision-timed conveyor networks synchronized with assembly sequencing.
Poland
E-commerce fulfillment operators are accelerating belt conveyor replacements to match parcel density growth in Warsaw and Łódź distribution hubs. CE marking requirements filter smaller fabricators from tender processes, consolidating procurement around integrated system suppliers. The country's central European logistics positioning attracts AS/RS-integrated warehouse investments.
France
After-sales service unbundling is fragmenting traditional full-service contracts into discrete software subscriptions among mid-market warehousing accounts. ANSM pharmaceutical quality protocols in the Île-de-France region require validated equipment with audit trails for vaccine distribution networks. Paris Basin logistics operators prioritize rapid deployment and modular scalability.
Netherlands
Food processors in Rotterdam and Utrecht are specifying washdown-compatible stainless steel belt systems for dairy and meat handling lines. EFSA hygiene protocols mandate full material traceability for belt polymers and lubricants, extending procurement timelines. The country's port-centric logistics infrastructure drives demand for high-throughput sortation systems.
Italy
Northern Italian equipment builders in Lombardy and Emilia-Romagna are reformulating belt polymer specifications to preempt REACH registration bottlenecks. The national pharmaceutical regulator shapes demand through quality protocols requiring documented equipment qualification. Food processing automation investments cluster around Parma and Bologna manufacturing belts.
Europe Conveyors Market Competitive Landscape
Global majors compete with regional champions across integration depth and compliance certification tiers. The vendor base stratifies between full-system integrators with intralogistics breadth and specialized fabricators focused on discrete conveyor subsystems. Three archetypes dominate: diversified engineering conglomerates with captive automation divisions, pure-play conveyor specialists with deep vertical expertise, and logistics technology providers expanding into material handling hardware. Competitive moves center on strategic partnerships for AS/RS integration and geographic expansion into underpenetrated Iberian warehousing markets.
Among German-based engineering groups, SSI Schaefer AG and Dematic GmbH exemplify the full-system integrator archetype with intralogistics integration depth. Daifuku Co. Ltd. represents the technology-led specialist position competing through sortation and distribution center automation capabilities. Vanderlande Industries B.V. occupies a defensible niche position with high engineering barriers in airport baggage handling and parcel sortation applications.
| Leading Market Players |
|---|
| SSI Schaefer AG |
| Daifuku Co. Ltd. |
| Dematic GmbH |
| Vanderlande Industries B.V. |
| KNAPP AG |
| Swisslog AG |
| Beumer Group GmbH and Co. KG |
| Mecalux S.A. |
| Interroll Holding AG |
| Others |
Supply & Pricing Matrix
Mechatronics technician clusters in Baden-Württemberg and Bavaria anchor the premium-to-economy pricing spread across European conveyor procurement. Labor-cost differentials between these German engineering belts and Polish assembly zones compress margins on standardized roller systems while sustaining premium positioning for AS/RS-integrated installations.
Pricing Analysis
Warranty and service-bundling unbundling now separates premium system integrators from mid-market fabricators. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking depth and after-sales attachment rates. Price differentiation hinges on certification grade and software integration depth. Cost compression in economy-tier roller conveyors is intensifying because third-party maintenance aggregators capture price-sensitive warehousing accounts in France and Poland. E-commerce fulfillment operators exhibit highest price sensitivity; pharmaceutical buyers with EMA validation requirements show lowest.
Supply Chain Analysis
Freight cost volatility from Asian component sourcing compresses margins on servo drive and PLC imports. Supply concentration rests on Germany for precision mechanical components, China for motor drives and control electronics, and Italy for specialty belt polymers. Raw material dependencies span steel and aluminum from Ruhr-Saarland corridors, polymer compounds from northern Italy, and electronic controllers from East Asian manufacturing zones. Single-source vulnerability around Baden-Württemberg engineering networks for critical drive components creates regional exposure. Distribution runs through direct OEM relationships for automated systems and third-party maintenance aggregators for standardized mechanical replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
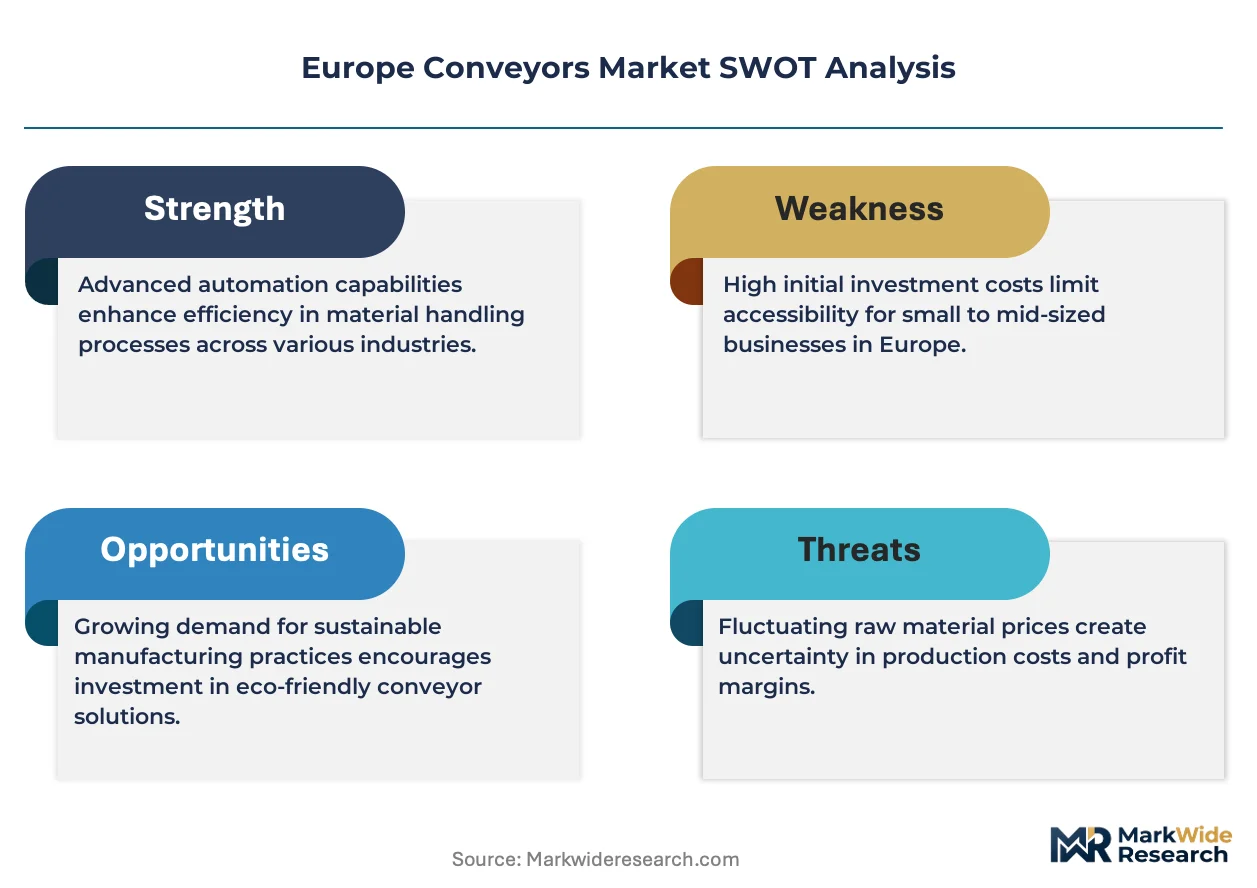
The Europe Conveyors Market functions as a cost-of-compliance arena where EU Machinery Directive documentation burdens filter smaller fabricators from tender processes. CE marking and REACH traceability requirements erect barrier-to-entry moats favoring integrated system suppliers with captive certification capabilities.
For Market Incumbents: Deploy predictive maintenance software attach rates to defend against third-party maintenance aggregator encroachment in French and Polish warehousing accounts. Backward integration into edge computing node manufacturing secures supply continuity for Stuttgart and Wolfsburg automotive retrofit programs. Consolidate position in pharmaceutical cold chain networks before temperature-monitoring belt specifications harden into EMA mandates.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Iberian warehousing markets offers first-mover positioning for AS/RS-integrated conveyor installations with localized service partnerships. Target underpenetrated Portugal and Spain distribution hubs where CE marking requirements have not yet consolidated procurement around incumbent integrators. Pursue modular subscription pricing to match French e-commerce operator preference for unbundled after-sales contracts.
For Investors and Strategic Acquirers: Re-rating potential sits with smart conveyor specialists given EU AI Act cybersecurity and algorithmic transparency standards creating service attach opportunities. Acquisition focus should center on software-defined control plane developers with pharmaceutical network penetration in Belgium and Ireland. Watch for inflection when EMA cold chain specifications mandate temperature-monitoring belt systems across vaccine distribution networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Computing Hardware | Captures predictive maintenance value pool from Stuttgart automotive retrofit demand. |
| CE Marking Certification Investment | Filters smaller fabricators from Bavarian automotive tender processes under EU Machinery Directive. |
| Pharmaceutical Cold Chain Partnership | Positions for EMA temperature-monitoring mandates in Belgian vaccine distribution networks. |
| Iberian Warehousing Geographic Expansion | Exploits underpenetrated Portugal and Spain logistics markets before incumbent consolidation. |
| Software-Defined Maintenance Contract Launch | Matches French e-commerce operator preference for unbundled service subscriptions. |
Research Methodology
Multi-period observation of CE marking compliance timelines and AS/RS integration adoption rates anchored the trend analysis, supplemented by interviews with plant engineers at German automotive OEMs, procurement leads at Polish e-commerce fulfillment operators, aftermarket service heads at French warehousing accounts, and regulatory affairs specialists at Danish food processors. Secondary validation drew from EU Machinery Directive implementation guidance, EMA pharmaceutical quality protocol documents, EFSA hygiene standard updates, and customs trade data for steel and aluminum feedstock flows. Bottom-up project pipeline tracking triangulated against top-down manufacturing investment surveys.
Input-output matrices mapped conveyor system demand across product type, application, end user, and technology dimensions over the projection horizon. Modeled segmentation captured belt, roller, chain, and bucket conveyor categories; manufacturing, warehousing, food processing, and packaging applications; automotive, retail, aerospace, and pharmaceutical end users; plus automated, manual, hybrid, and smart technology tiers. CAGRs were derived from regression analysis against industrial automation capex cycles and e-commerce fulfillment density metrics. Forecast inputs included servo drive cost trajectories and REACH chemical registration timelines affecting belt polymer qualification cycles.
Underlying measurement precision varies by segment; automated and smart conveyor categories carry tighter precision than manual systems given disclosed OEM procurement data. Forecasts reflect assumptions about EU AI Act implementation timelines and Central European labor cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Industrial Pulley Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Rotary Breaker Market
Material Handling Equipment
Loader Bucket Attachments Market