
 Eye Tracking Systems Market | 2026-2036
Eye Tracking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Tracking Systems Market Analysis
Healthcare diagnostics is pivoting toward non-invasive neurological and ophthalmological screening, pulling eye tracking hardware into clinical workflows at accelerating velocity. Tobii AB leverages its research-grade platform dominance to anchor European academic and corporate demand. Seeing Machines Ltd. specializes in drowsiness-detection systems for automotive and aviation safety, sustaining its position in performance-critical environments. Smart Eye AB competes through AI-driven multimodal sensing that extends gaze data into emotional-state inference for human-computer interaction deployments.
Eye tracking systems measure oculomotor behavior through corneal reflection mapping, pupil-center computation, and infrared illumination to capture gaze position, fixation duration, and saccade velocity with sub-degree accuracy. These systems serve industrial and commercial purposes spanning usability engineering, cognitive-load assessment, driver-fatigue monitoring, and immersive-interface control. Hardware segments dominate current revenue as sensor miniaturization and embedded processing reduce unit costs, while software layers capture expanding margin pools through analytics subscriptions and cloud-based experiment management. Video-based technology leads deployment volume due to its non-contact operation and compatibility with standard cameras, though wearable devices are gaining traction in mobile and augmented-reality contexts where head-mounted form factors prove essential.
FDA scrutiny of diagnostic-device claims shapes product development timelines for healthcare-facing vendors, while EMA's Medical Device Regulation imposes clinical-evidence thresholds that filter market entrants in Europe. ISO 9241-9 ergonomic standards and IEC 60601-1 safety requirements further constrain hardware design for medical and workplace applications. Stakeholders must monitor evolving CE marking pathways under the EU AI Act as gaze-analysis algorithms face emerging transparency and bias-audit obligations that will reshape competitive qualification.
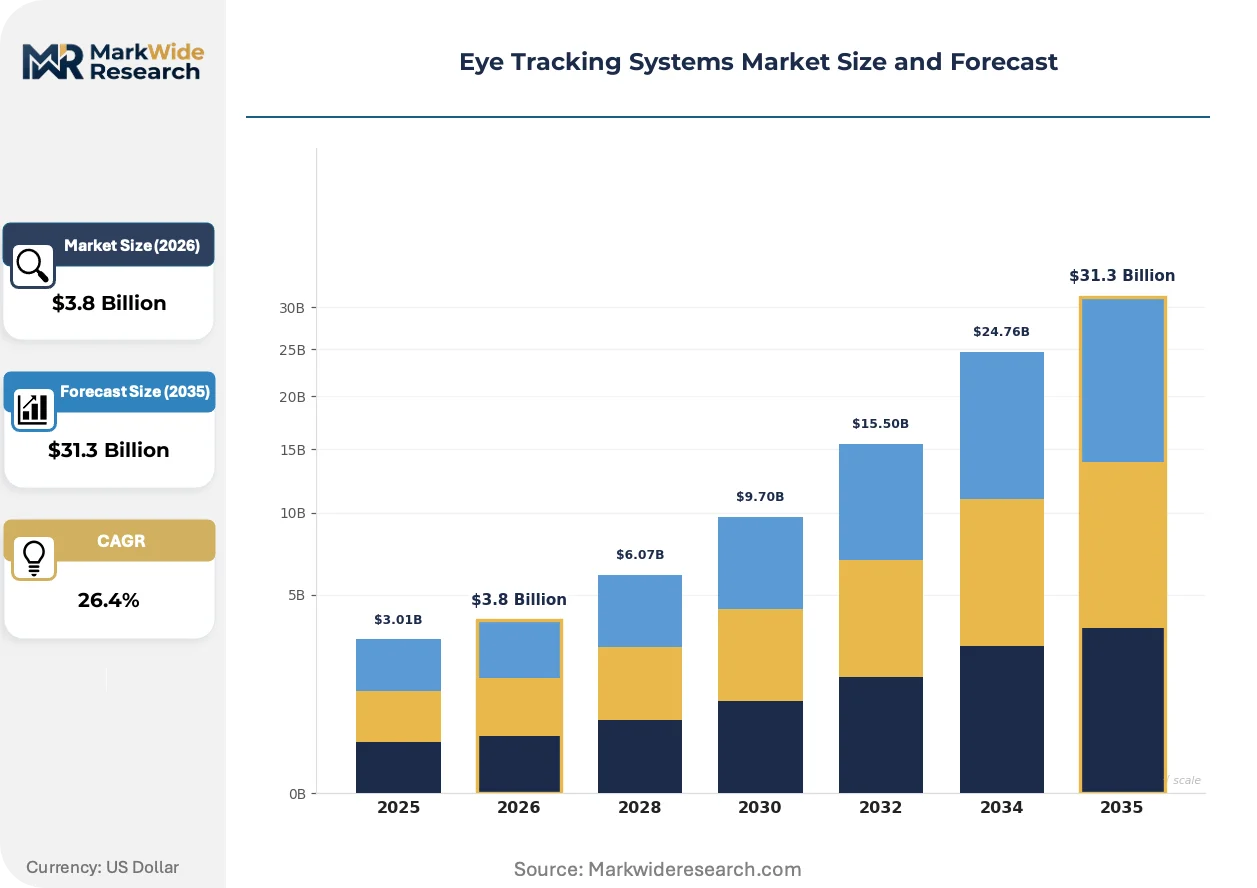
Market Dynamics
Clinical validation requirements under FDA and EMA frameworks are compressing product development timelines while simultaneously expanding addressable demand for diagnostic-grade eye tracking hardware in neurological and ophthalmological screening workflows.
Growth Catalysts
- MDR Compliance Thresholds:EMA's Medical Device Regulation imposes clinical-evidence requirements that filter weaker competitors, concentrating market share among vendors with robust validation data and accelerating hospital procurement of certified systems.
- Automotive Safety Mandates:Driver-monitoring regulations from NHTSA and Euro NCAP protocols are embedding gaze-tracking sensors into production vehicle lines, creating captive demand for automotive-grade hardware modules.
- Remote Research Infrastructure:Academic laboratories in the United States, Germany, and Japan are deploying cloud-managed eye tracking platforms to sustain distributed experimental protocols, sustaining hardware refresh cycles.
Market Restraints
- Specialized Optics Supply Concentration:High-precision infrared illuminators and miniature CMOS sensors concentrate among Taiwanese and South Korean component suppliers, exposing hardware vendors to single-source risks and input cost volatility.
- FDA Diagnostic Claims Scrutiny:The agency's 510(k) and De Novo pathway requirements for neurological screening devices extend validation timelines by 18-36 months, constraining revenue recognition for healthcare-facing product lines.
- Video-Based Substitution Pressure:Standard webcam-based gaze estimation using machine learning is displacing dedicated hardware in low-accuracy consumer applications, compressing addressable volume in the economy tier.
Strategic Opportunities
- Underpenetrated Indian Clinical Market:CDSCO's emerging framework for software-as-medical-device classification creates first-mover positioning for diagnostic eye tracking in neurology departments across tier-1 hospital networks.
- Wearable AR Integration:Convergence of micro-electromechanical systems and waveguide optics is enabling gaze-controlled interfaces in head-mounted displays for industrial maintenance and surgical navigation applications.
- EU AI Act Transparency Mandates:Emerging bias-audit and explainability requirements for biometric analysis algorithms will favor vendors with documented training-data provenance, creating qualification barriers for under-resourced competitors.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time pupil tracking at sub-degree accuracy requires specialized expertise in infrared signal processing and embedded computer vision, constraining vendor scaling.
- Legacy EMR Integration Complexity:Hospital IT departments face extended deployment timelines when connecting gaze-based diagnostic outputs to existing electronic medical record architectures, delaying clinical adoption.
- ISO 13485 Certification Burden:Medical device quality management system audits impose recurring compliance costs and documentation overhead that disproportionately strain mid-cap hardware vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Tracking Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $31.3 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Integration Tools, Accessories Technology: Video-based, Electrooculography, Optical, Wearable Devices Application: Market Research, Healthcare, Human-Computer Interaction, Gaming End User: Academics, Corporations, Healthcare Professionals, Research Institutions |
| Companies Covered | Tobii AB, Seeing Machines Ltd., Smart Eye AB, SR Research Ltd., EyeTech Digital Systems Inc., EyeTracking Inc., LC Technologies Inc., iMotions A/S, Ergoneers GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Tracking Systems Market Emerging Trajectories
Edge computing architectures and on-device inference are redistributing processing loads away from centralized servers, enabling real-time gaze analysis in latency-sensitive automotive and clinical environments without network dependency.
Event-based vision sensors utilizing asynchronous pixel-level intensity change detection are decentralizing eye tracking hardware from laboratory workstations into mobile and wearable form factors. Automotive tier-1 suppliers in Germany and Japan are integrating these neuromorphic chips into driver-monitoring systems for production vehicles launching 2026-2027. The technology is compressing power consumption and data bandwidth requirements, enabling always-on gaze tracking without thermal management constraints.
EMA's Medical Device Regulation and the EU AI Act are converging to impose dual clinical-evidence and algorithmic-transparency obligations on diagnostic eye tracking systems. Hardware vendors must now maintain technical documentation spanning biocompatibility testing, electromagnetic compatibility, and training-data audit trails. European hospital procurement committees are prioritizing vendors with pre-established notified body relationships, accelerating consolidation among established players.
Research institutions are unbundling hardware ownership from experimental service access, subscribing to cloud-managed eye tracking platforms with per-study pricing rather than capital equipment procurement. This consumption-pattern shift is visible across United States academic medical centers and Max Planck Institute facilities, compressing vendor sales cycles while expanding recurring software revenue pools and reducing customer switching costs.
Eye Tracking Systems Market Segmentation
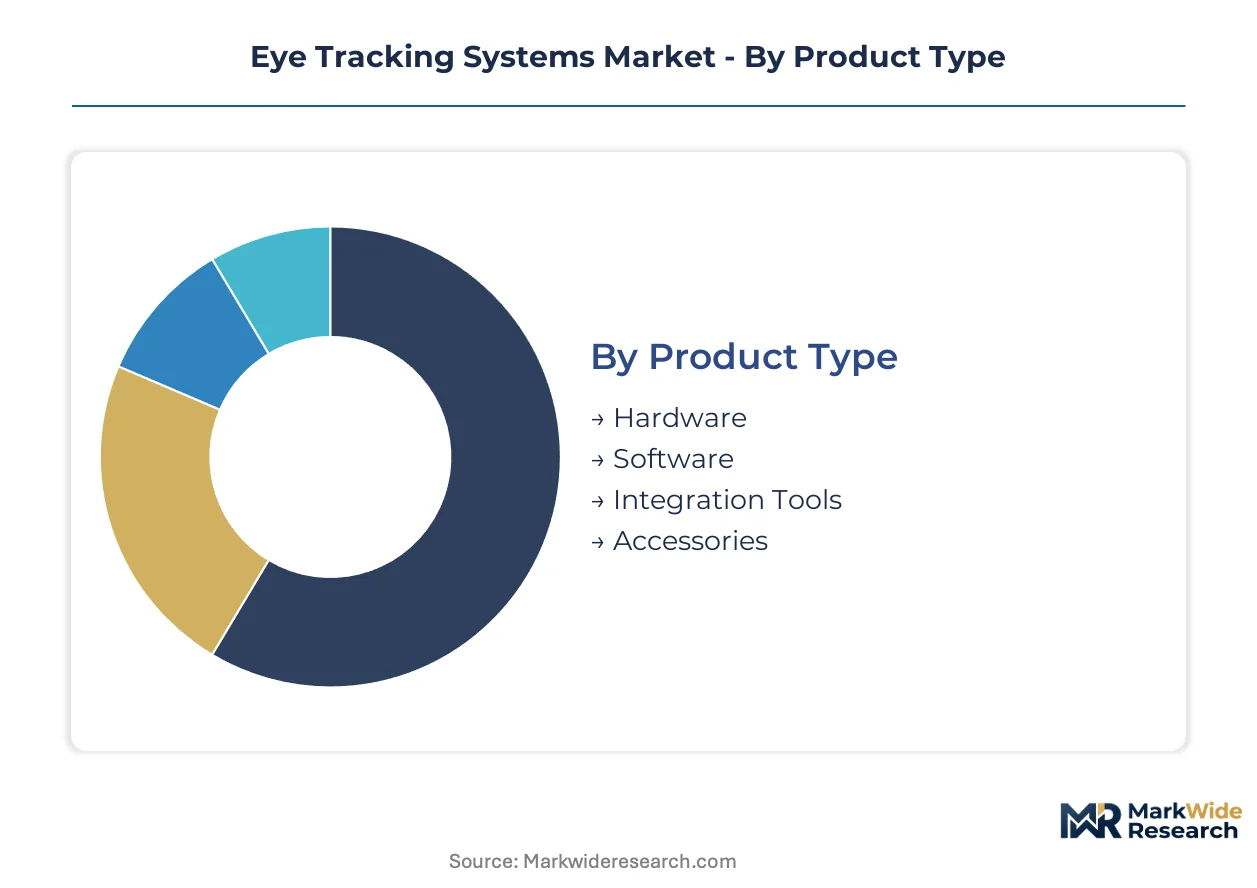
Segmentation in eye tracking systems reflects divergent technical requirements across precision tiers, from sub-degree clinical diagnostics to consumer-grade gaze estimation. Hardware configurations, sensing modalities, and end-user workflows each impose distinct cost structures and validation thresholds that reshape vendor positioning.
Product Type:
Supply concentration in infrared illuminators and miniature CMOS sensors disproportionately shapes hardware economics, while software layers capture expanding margin pools through recurring analytics subscriptions.
- Hardware:Sensor miniaturization and embedded processing are compressing unit costs for corneal reflection cameras and pupil-center computation modules. Demand concentrates in automotive production lines across Germany and Japan where NHTSA and Euro NCAP driver-monitoring mandates require certified gaze-tracking modules.
- Software:Cloud-based experiment management platforms and gaze-data analytics engines enable per-study pricing models that unbundle capital ownership from research access. Academic medical centers in the United States are migrating toward subscription consumption, expanding recurring revenue pools for platform vendors.
- Integration Tools:API middleware and SDK packages bridge proprietary hardware with third-party experimental frameworks.
- Accessories:Calibration targets, mounting rigs, and specialized lenses extend system functionality in laboratory deployments.
Hardware absorbs the bulk of installed capacity; software is expanding most quickly as research institutions shift from capital procurement to consumption-based access models.
Technology:
Cost tier differentiation separates high-precision clinical systems from economy-grade consumer applications, with video-based platforms dominating deployment volume due to standard camera compatibility.
- Video-based:Non-contact operation using infrared illumination and corneal reflection mapping achieves sub-degree accuracy without physical attachment. Healthcare diagnostics in the United States and Germany leverage these systems for FDA and EMA-validated neurological screening workflows.
- Electrooculography:Skin-electrode measurement of corneo-retinal potential changes enables gaze tracking in extreme motion environments where camera stability fails. Aviation safety applications and high-G research protocols in Japan utilize these systems for pilot drowsiness monitoring.
- Optical:Direct retinal imaging and pupil tracking through specialized lens systems serve precision ophthalmology.
- Wearable Devices:Head-mounted form factors integrating micro-electromechanical systems and waveguide optics enable gaze-controlled interfaces in augmented reality and surgical navigation contexts.
Video-based technology commands the largest installed base; wearable devices are climbing the fastest as MEMS convergence enables mobile and AR integration.
Application:
Volume concentration in healthcare diagnostics is accelerating as FDA and EMA clinical validation requirements tighten, filtering market entrants toward certified vendors.
- Healthcare:Non-invasive neurological and ophthalmological screening applications leverage gaze position, fixation duration, and saccade velocity metrics for early disease detection. Hospital procurement committees in Germany prioritize vendors with pre-established EMA notified body relationships under MDR compliance thresholds.
- Human-Computer Interaction:Cognitive-load assessment and emotional-state inference through AI-driven multimodal sensing extend gaze data into adaptive interface design. Corporate usability engineering teams in Japan deploy these systems for product development workflows.
- Market Research:Attention heat mapping and advertisement effectiveness measurement serve consumer behavior analysis.
- Gaming:Immersive interface control and foveated rendering optimization reduce computational loads in virtual reality environments.
Healthcare captures the dominant share of high-value deployments; human-computer interaction is gaining share fastest as AI inference extends gaze utility beyond raw measurement.
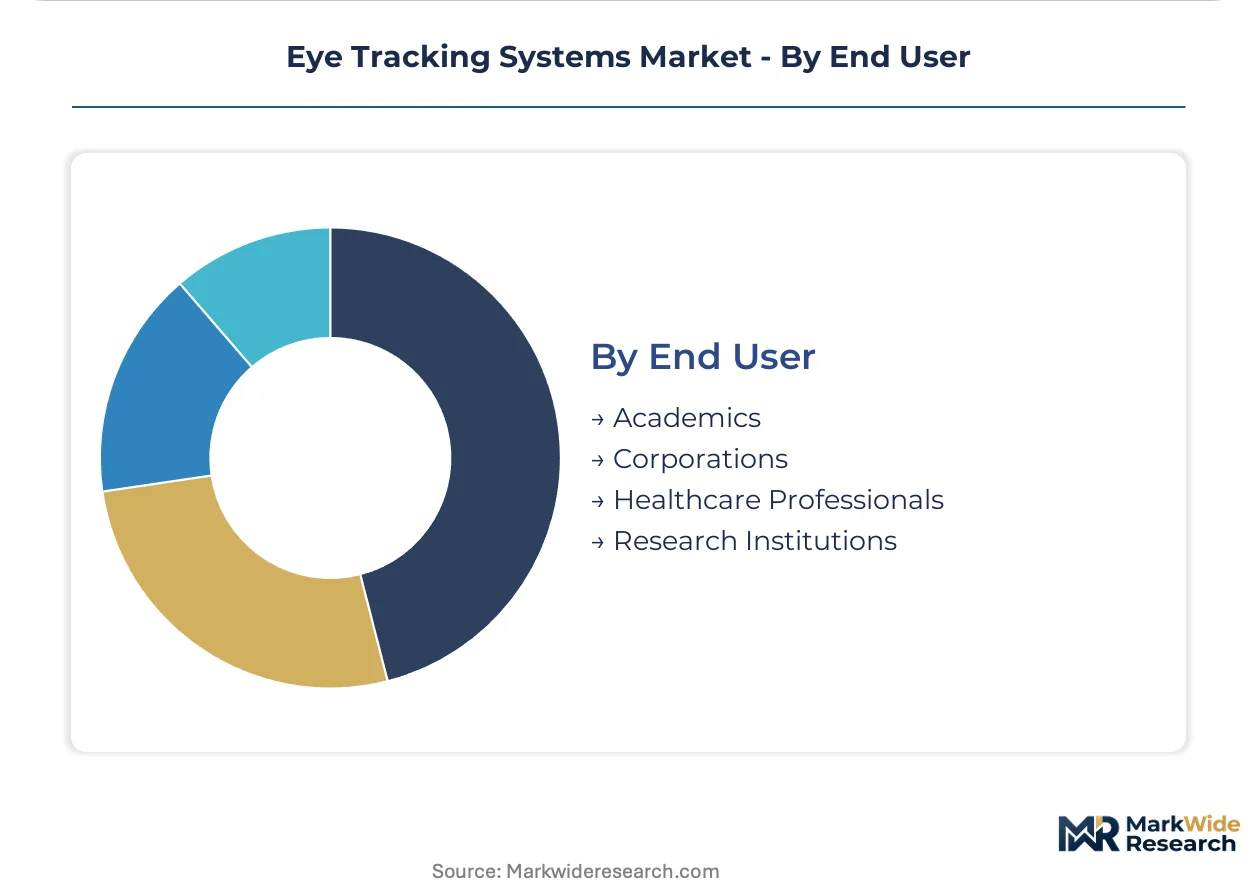
End User:
Customer type segmentation reflects divergent procurement authority, with research institutions driving hardware refresh cycles and healthcare professionals imposing clinical-evidence thresholds that elongate sales timelines.
- Research Institutions:Max Planck Institute facilities and United States academic medical centers sustain distributed experimental protocols through cloud-managed platform deployments. These organizations prioritize vendors offering per-study pricing and remote calibration capabilities.
- Healthcare Professionals:Neurology departments and ophthalmology clinics require ISO 13485 quality management certification and documented training-data provenance for diagnostic claims. EMA's Medical Device Regulation and emerging EU AI Act transparency mandates are concentrating procurement among established players with robust validation archives.
- Academics:Individual laboratory principal investigators balance equipment cost against experimental flexibility.
- Corporations:Automotive tier-1 suppliers and aviation manufacturers integrate gaze tracking into safety-critical production systems.
Research institutions represent the largest installed base; healthcare professionals are expanding fastest as reimbursement pathways for ocular-motor assessment tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate infrared illuminator manufacturing, drawing Taiwanese CMOS sensor suppliers into clustered supply networks that feed automotive and healthcare hardware assembly lines.
United States
Academic medical centers in Boston and the San Francisco Bay Area sustain distributed experimental protocols through cloud-managed platform deployments. FDA 510(k) pathway requirements for neurological screening devices compress product development timelines while expanding certified-system procurement. The Research Triangle Park cluster in North Carolina anchors usability engineering and human-computer interaction research facilities.
Germany
Automotive tier-1 suppliers in Stuttgart and Munich integrate gaze-tracking modules into production vehicle lines under Euro NCAP driver-monitoring protocols. EMA Medical Device Regulation imposes clinical-evidence thresholds that filter hospital procurement toward established notified body relationships. The Max Planck Institute network sustains research-grade hardware refresh cycles across Bavaria and Baden-Württemberg.
Japan
Aviation safety manufacturers in Nagoya and Tokyo deploy electrooculography systems for pilot drowsiness monitoring in high-G research environments. METI industrial standards shape embedded firmware development for automotive and clinical applications. The Kansai region around Osaka concentrates MEMS foundry capacity for wearable device integration.
India
Tier-1 hospital networks in Mumbai and Delhi-NCR pilot diagnostic eye tracking systems under CDSCO's emerging software-as-medical-device classification framework. BIS certification requirements for electronic medical devices create qualification barriers for imported hardware. The Bengaluru technology corridor hosts usability engineering teams serving multinational corporate research contracts.
South Korea
Display panel manufacturers in Gyeonggi Province supply waveguide optics for augmented reality head-mounted displays. MFDS medical device regulations align with international standards to accelerate export-oriented production. The Daegu-Gyeongbuk region specializes in miniature CMOS sensor fabrication for mobile eye tracking applications.
Eye Tracking Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with research-grade hardware consolidating around validated platform vendors while automotive safety modules fragment across tier-1 supplier networks. The vendor base separates into three strategic archetypes: research-platform incumbents with established academic relationships, automotive-integrated module suppliers, and AI-driven multimodal sensing specialists. Dominant competitive moves include strategic partnerships with automotive OEMs for driver-monitoring certification and technology licensing agreements that extend gaze-analysis algorithms into third-party software stacks.
Within the research-platform tier, Tobii AB and SR Research Ltd. exemplify vendors sustaining European and North American academic demand through per-study pricing models. Seeing Machines Ltd. occupies a position in performance-critical safety environments, while Smart Eye AB anchors AI-driven expansion into emotional-state inference applications. These named entities represent distinct competitive vectors without exhausting the full vendor landscape.
| Leading Market Players |
|---|
| Tobii AB |
| Seeing Machines Ltd. |
| Smart Eye AB |
| SR Research Ltd. |
| EyeTech Digital Systems Inc. |
| EyeTracking Inc. |
| LC Technologies Inc. |
| iMotions A/S |
| Ergoneers GmbH |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA-cleared diagnostic systems and uncertified research hardware manifests in pricing premiums of 40-60% for clinical-validated units, while supply chain configurations concentrate infrared illuminator and CMOS sensor procurement among Taiwanese and South Korean component vendors who command allocation priority from hardware assemblers in Germany and Japan.
Pricing Analysis
Short lead-time premiums for automotive-grade gaze-tracking modules sustain elevated pricing for Tier 1 suppliers under Euro NCAP and NHTSA procurement deadlines, while spot inventory of research-grade hardware trades at discounts. Three-tier pricing structure across premium clinical-diagnostic, standard research-grade, and economy webcam-estimation levels separates certified FDA/EMA systems from academic hardware and consumer software. Cost compression in the economy tier intensifies as machine-learning gaze estimation displaces dedicated sensors. Academic medical centers exhibit highest price sensitivity due to capital budget constraints, while automotive OEMs demonstrate lowest sensitivity given safety-mandate compliance requirements.
Supply Chain Analysis
Refurbishment flows for research-grade eye tracking hardware extend asset lifecycles in United States academic laboratories, creating secondary supply channels that moderate new equipment demand. Component sourcing concentrates in Taiwan, South Korea, and Japan for infrared illuminators, miniature CMOS sensors, and MEMS foundry capacity. Hardware assembly draws from precision optics suppliers in Germany and automotive electronics integrators in Japan. Single-source vulnerability for high-precision infrared emitters exposes vendors to allocation disruptions. Distribution runs through direct OEM relationships for automotive modules, specialized scientific distributors for research hardware, and cloud platform subscriptions for software analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in embedded firmware talent and specialized infrared optics prop pricing power for qualified vendors, compressing margins for under-resourced competitors unable to secure component allocation.
For Market Incumbents: Acquire embedded computer vision engineering teams to secure firmware development capacity against talent scarcity constraining competitor scaling. Consolidate notified body relationships under EMA MDR and EU AI Act frameworks to accelerate hospital procurement cycles. Defensive positioning requires backward integration into infrared illuminator supply through long-term offtake agreements with Taiwanese component vendors, mitigating single-source exposure from substitute technologies entering through standard webcam-based estimation. For New Entrants and Emerging Players: Tier-1 hospital networks in India offer penetrable entry points under CDSCO's emerging software-as-medical-device classification, where established vendor presence remains limited. Cloud-managed per-study pricing models reduce customer switching costs and compress capital barriers for academic laboratory adoption. Channel partnerships with scientific equipment distributors in Germany and Japan provide go-to-market infrastructure without direct sales force investment. For Investors and Strategic Acquirers: Re-rating potential sits with AI-driven multimodal sensing specialists given automotive safety mandate expansion and healthcare diagnostic validation requirements accelerating certified-system procurement. Long-term viability over the next decade hinges on demonstrated training-data provenance and algorithmic transparency documentation under emerging regulatory frameworks. Acquisition targets should exhibit established notified body relationships and embedded firmware expertise. Monitor CDSCO classification finalization and EU AI Act implementation timelines as inflection indicators for geographic expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Notified Body Certification | Accelerates hospital procurement under MDR compliance thresholds in Germany. |
| Automotive Tier 1 Partnership | Secures captive demand through Euro NCAP driver-monitoring mandate integration. |
| Cloud Platform Subscription Launch | Captures recurring revenue from United States academic medical center migration. |
| Infrared Component Supply Agreement | Reduces single-source vulnerability from Taiwanese illuminator concentration. |
| Embedded Firmware Talent Acquisition | Addresses capability scarcity constraining real-time pupil tracking accuracy. |
Methodological Framework
Multi-period observation of FDA 510(k) submission timelines, EMA notified body certification cycles, and automotive safety mandate implementation anchored the trend analysis, supplemented by interviews with biomedical engineers at academic medical centers, procurement managers at German automotive Tier 1 suppliers, regulatory affairs specialists navigating MDR compliance, and cloud platform product directors. Secondary validation drew from FDA device classification databases, EMA Medical Device Regulation guidance documents, Euro NCAP assessment protocols, and hospital procurement records. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across hardware configurations, software deployment models, technology modalities, application verticals, and end-user archetypes structured the analytical framework across the analysis window. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory inflection points. Industry-specific forecast inputs included CDSCO software-as-medical-device classification progression and MEMS foundry capacity expansion in Japan's Kansai region.
Several conditions sit outside the modeled scope, including specific FDA De Novo pathway outcomes for novel neurological screening claims and geopolitical disruptions affecting Taiwanese component supply. Forecasts reflect assumptions regarding reimbursement pathway maturation for ocular-motor assessment tools. Practitioners should monitor EU AI Act bias-audit requirement finalization and NHTSA driver-monitoring rulemaking for early signals of competitive qualification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Industrial Controllers Market