
 North America LED Packaging Market | 2026-2036
North America LED Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America LED Packaging Market Analytics
Chip-scale packaging and flip-chip architectures is tilting LED module assembly toward higher thermal density configurations with reduced phosphor volumes. Wolfspeed leverages its silicon carbide substrate expertise to anchor premium power LED supply chains for electric vehicle headlamp modules. Lumileds Holding sustains R&D intensity in chip-on-board arrays for high-bay industrial fixtures. Acuity Brands Lighting dominates specification-grade channel control through its vertical distribution network across US commercial building projects.
LED packaging encompasses the encapsulation, phosphor deposition, and optical lensing of semiconductor dies into functional emitters, typically operating at correlated color temperatures between 2700K and 6500K with luminous efficacy targets exceeding 150 lumens per watt for ENERGY STAR qualification. The technology serves to protect fragile gallium nitride junctions while extracting and directing photons into usable beam patterns for illumination and display applications. Surface Mount Device formats lead volume shipments due to compatibility with automated pick-and-place electronics assembly, while MicroLED technology commands development investment as next-generation display manufacturers chase pixel densities above 2000 ppi for augmented reality headsets. Chip-on-Board configurations retain margin pools in horticultural and medical applications where spectral tuning justifies premium pricing.
The US Department of Energy solid-state lighting program and California Energy Commission Title 20 appliance standards jointly dictate minimum efficacy thresholds and flicker requirements that reshape product qualification costs for market entry. NHTSA Federal Motor Vehicle Safety Standard 108 governs automotive forward lighting color boundaries and intensity minimums that packaging houses must meet for OEM qualification. Stakeholders must monitor how the EPA ENERGY STAR specification revision cycle and emerging state-level right-to-repair lighting mandates alter design-for-longevity requirements against cost minimization pressures.
Market Dynamics
Automotive electrification corridors in Detroit and Tennessee are pulling high-power LED packaging capacity toward thermal-dense flip-chip architectures, compressing legacy SMD supply lines and rewiring qualification timelines for Tier 1 lamp suppliers.
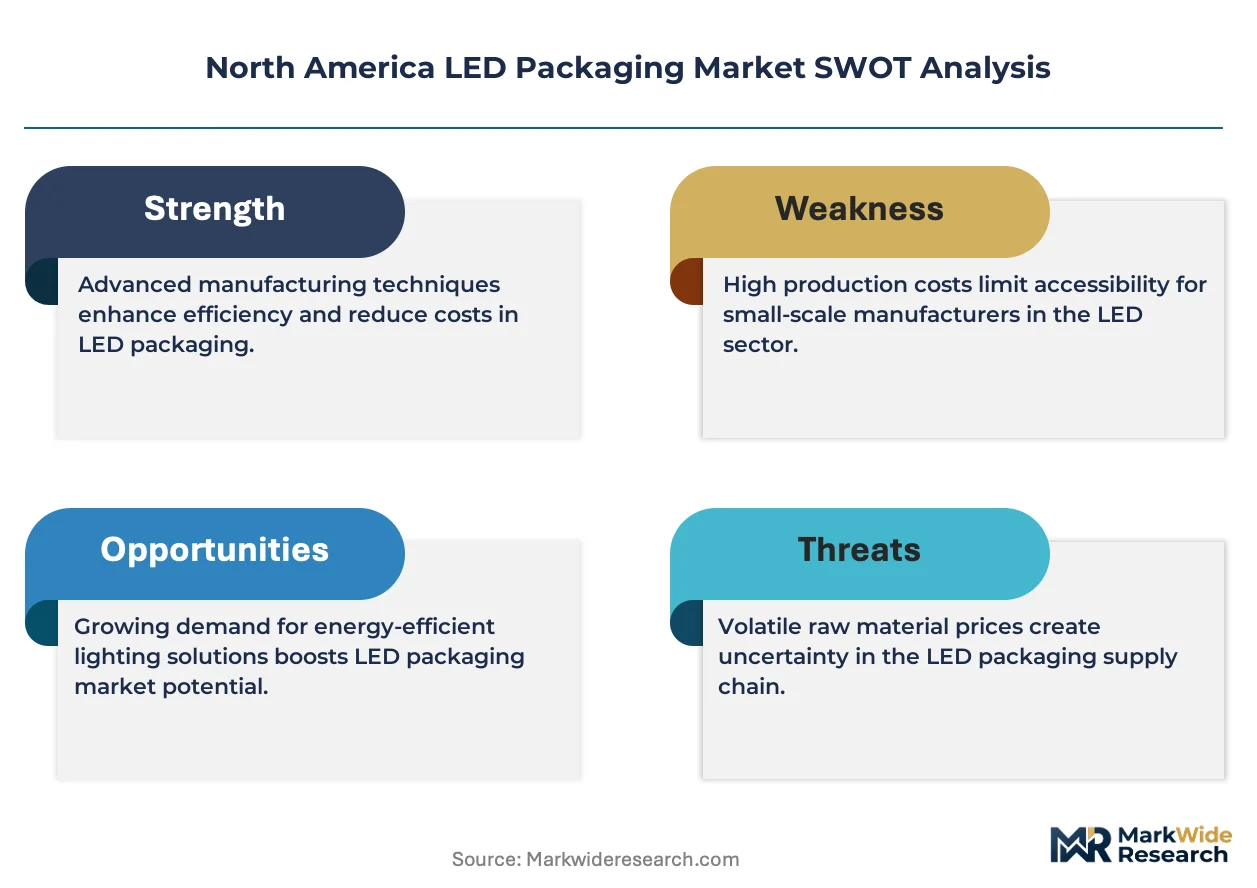
Growth Catalysts
- EPA ENERGY STAR efficacy mandates:Minimum luminous efficacy thresholds above 150 lumens per watt force lumen depreciation redesigns, opening specification-grade sockets for advanced phosphor-converted white emitters in US commercial retrofit projects.
- Mexico Baja California cluster expansion:Electronics assembly concentration near Tijuana attracts chip-on-board packaging investment for horticultural spectral tuning modules serving controlled-environment agriculture across California and Arizona.
- Flip-chip thermal architecture penetration:Silicon carbide substrate integration enables 200°C junction temperature operation, qualifying packaged emitters for electric vehicle headlamp modules under NHTSA Federal Motor Vehicle Safety Standard 108.
Market Restraints
- Gallium nitride wafer supply concentration:Substrate fabrication concentrates among limited merchant suppliers, exposing packaging houses to input cost volatility and allocation rationing during power semiconductor demand spikes.
- California Title 20 flicker compliance:Percent flicker limits below 30 percent at 100 Hz impose optical testing burdens that extend product development cycles and raise entry costs for mid-tier packaging operations.
- MicroLED display substitution threat:Direct-view microemitter arrays for augmented reality headsets bypass traditional packaging value steps, threatening phosphor-converted white emitter demand in premium display backlighting.
Strategic Opportunities
- Texas-Mexico cross-border manufacturing:Maquiladora duty advantages and USMCA rules of origin enable tariff-efficient packaging operations serving automotive OEMs across the southern US manufacturing belt.
- IRA clean energy manufacturing tax credits:Domestic content bonuses for US-assembled solid-state lighting accelerate reshoring investment in chip-scale packaging lines for federal building retrofit programs.
- Horticultural spectral convergence:Far-red and UV-A emitter integration with white packages creates tunable growth-light systems commanding premium positioning in vertical farming installations across Illinois and New York.
Industry Challenges
- Thermal simulation talent scarcity:Finite element modeling expertise for junction temperature prediction remains concentrated among semiconductor packaging veterans, constraining new entrant product qualification speed.
- Automotive PPAP timeline compression:Production part approval process documentation for NHTSA-compliant forward lighting squeezes development schedules, requiring parallel thermal and optical validation tracks.
- Legacy fluorescent socket retrofit integration:Ballast-compatible LED tube packaging must reconcile disparate US regional electrical codes, fragmenting SKU proliferation and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America LED Packaging Market |
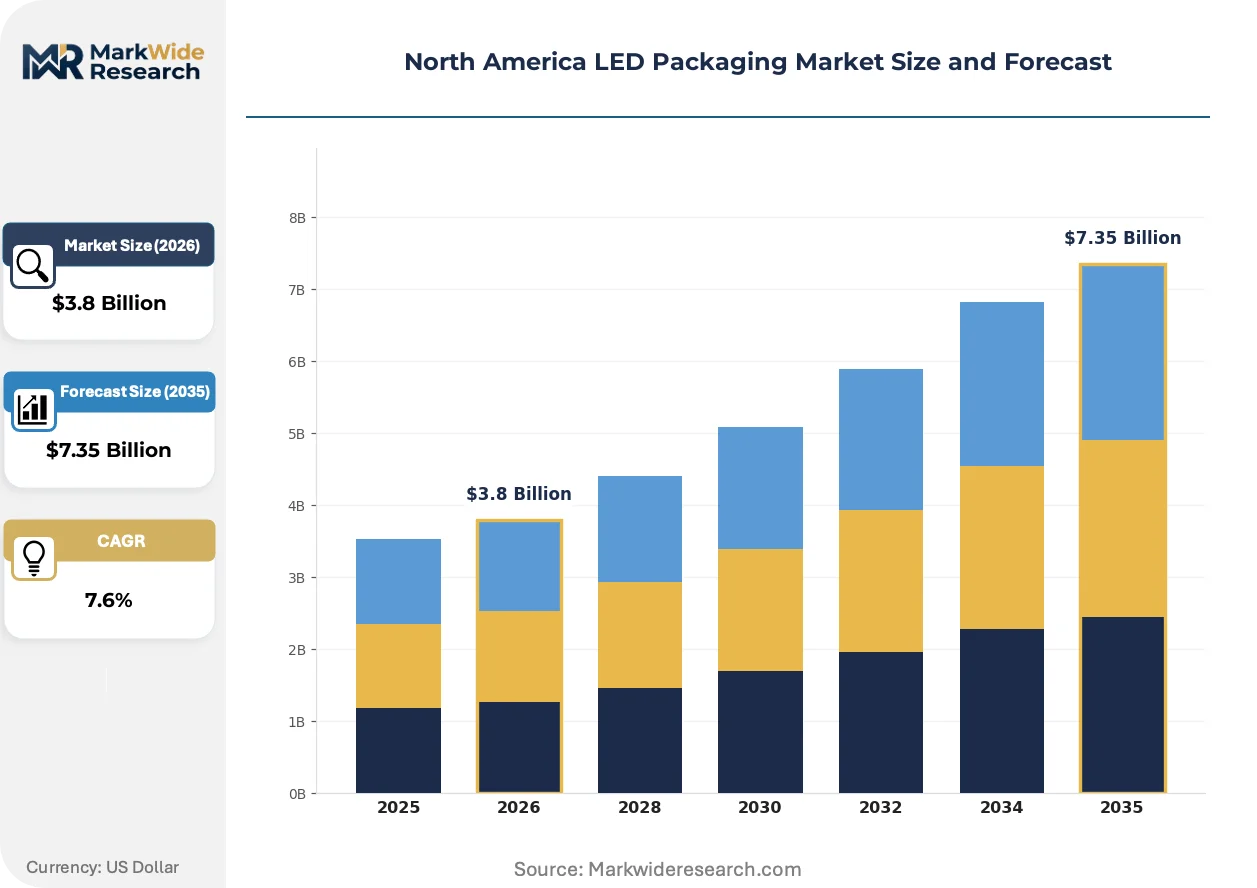
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chip-on-Board, Surface Mount Device, Dual In-Line Package, Through-Hole Package Technology: Organic LED, Quantum Dot LED, MicroLED, Conventional LED Application: Automotive Lighting, Residential Lighting, Outdoor Displays, Backlighting End User: Manufacturers, Retailers, Distributors, Wholesalers |
| Companies Covered | Acuity Brands Lighting, Wolfspeed, General Electric, Hubbell, LSI Industries, Lumileds Holding, Cree, OSRAM, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America LED Packaging Market Evolving Landscape
Packaging architectures are compressing thermal paths and virtualizing optical functions, while regulatory tightening and procurement rationalization reshape how specification-grade emitters reach end-use markets across the continent.
Chip-on-board arrays with direct phosphor deposition onto gallium nitride dies eliminate intermediate substrate layers, cutting thermal resistance by half. Automotive forward lighting engineers in Michigan and Tennessee specify these configurations for electric vehicle headlamp modules operating at 85°C ambient. The technology is virtualizing the discrete LED component supply chain by merging die attach, wire bond, and lensing into single-process manufacturing cells.
California Energy Commission Title 20 appliance standards now mandate minimum efficacy and flicker performance for general service lamps sold in the state. Packaging houses must redesign phosphor systems and driver compatibility to maintain market access, with testing documentation burdens falling heaviest on mid-volume suppliers serving multi-state distribution. Compliance cost concentration is pushing smaller California lighting assemblers toward private-label sourcing from qualified Tier 1 packaging partners.
Building owners and facility managers now bundle LED retrofit procurement with energy-as-a-service contracts, transferring specification authority from distributor sales teams to financed performance guarantees. This channel compression bypasses traditional specification-grade stocking distributors in favor of direct OEM-account relationships. The shift concentrates most visibly in Texas and Florida commercial real estate markets where property management platforms standardize lighting specifications across portfolio-wide rollouts.
North America LED Packaging Market Segmentation
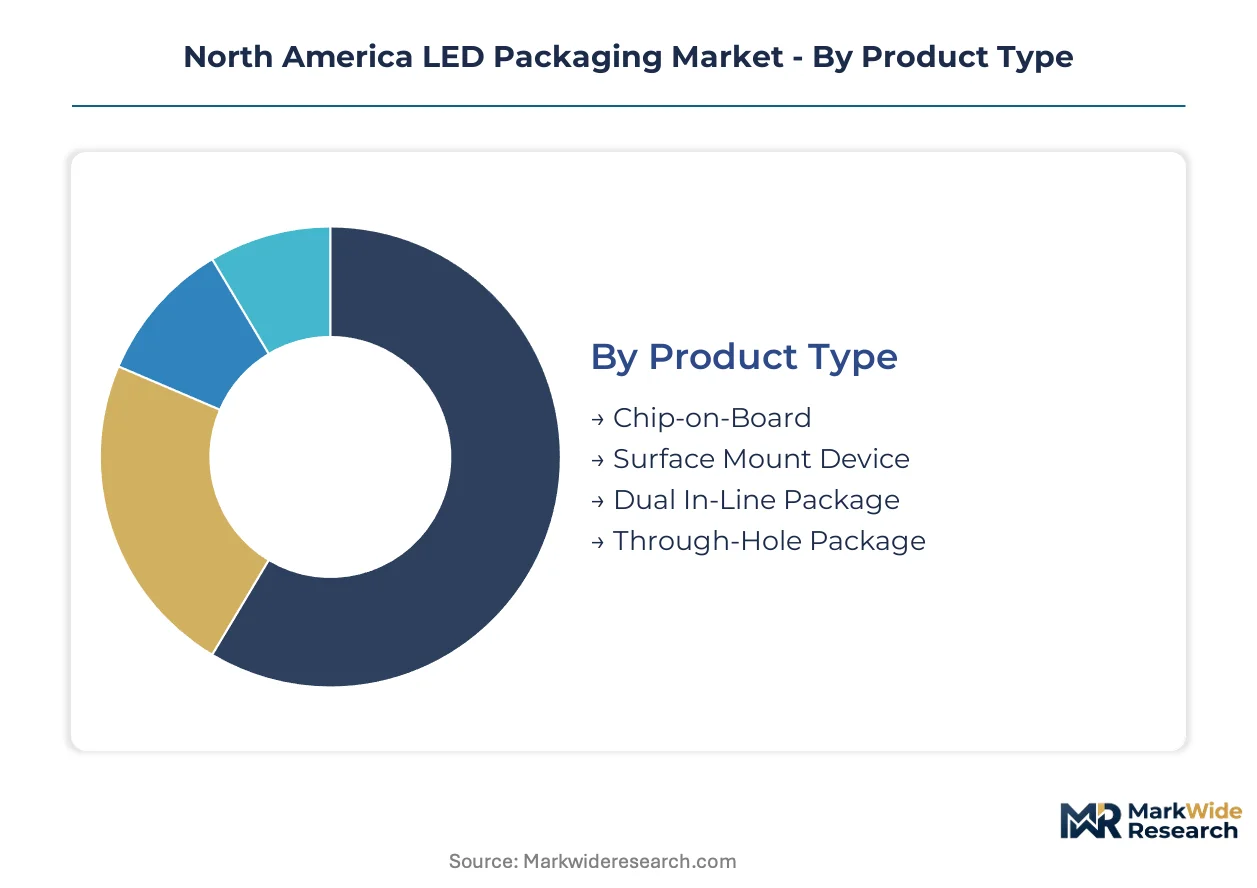
LED packaging segmentation in North America reflects divergent thermal density requirements and qualification timelines across automotive, horticultural, and display end-uses. Understanding product format and technology splits reveals where capital equipment investments concentrate and which customer channels command premium positioning.
Product Type:
Cycle times vary dramatically: Surface Mount Device formats turn inventory monthly through high-volume electronics assembly, while Chip-on-Board configurations require custom thermal validation extending procurement lead times to twelve weeks or longer.
- Chip-on-Board:Direct phosphor deposition onto gallium nitride dies eliminates intermediate substrates, halving thermal resistance for electric vehicle headlamp modules operating at 85°C ambient in Michigan and Tennessee corridors. Horticultural spectral tuning in California and Arizona controlled-environment agriculture justifies premium positioning despite longer qualification cycles.
- Surface Mount Device:Pick-and-place compatibility drives volume dominance across consumer electronics and retrofit lamp assembly. Mexico's Baja California cluster near Tijuana anchors SMD capacity serving US commercial building retrofit programs under EPA ENERGY STAR efficacy mandates.
- Dual In-Line Package:Legacy through-hole compatibility persists in industrial control panel indicator applications with minimal redesign investment.
- Through-Hole Package:Manual assembly suitability retains niche positioning in outdoor signage and architectural accent lighting requiring discrete component replacement.
Surface Mount Device anchors the volume base while Chip-on-Board gains share at the steepest rate.
Technology:
Cost tiers stratify sharply: Conventional LED phosphor-converted emitters compete on lumen-per-dollar metrics, while MicroLED development commands capital allocation chasing augmented reality display premiums.
- MicroLED:Direct-view microemitter arrays bypass traditional packaging value steps entirely, threatening phosphor-converted demand in premium display backlighting while opening entirely new pixel-density frontiers above 2000 ppi for headset manufacturers.
- Conventional LED:Phosphor-converted white emitters with efficacy targets exceeding 150 lumens per watt dominate ENERGY STAR qualification for US federal building retrofit programs. Wolfspeed silicon carbide substrate integration enables 200°C junction temperature operation for automotive forward lighting under NHTSA Federal Motor Vehicle Safety Standard 108.
- Organic LED:Thin-film deposition constraints limit packaging house participation, with panel manufacturing concentrated among integrated display producers.
- Quantum Dot LED:Narrow emission bandwidths enable precise color gamut control for high-end display backlighting, though thermal stability challenges constrain automotive adoption.
Conventional LED commands installed base economics while MicroLED expands most quickly through display capital allocation.
Application:
Customer procurement patterns diverge: automotive lighting demands PPAP documentation and NHTSA compliance, while residential retrofit flows through distributor stocking programs with minimal technical specification.
- Automotive Lighting:Electric vehicle electrification corridors in Detroit and Tennessee pull high-power packaging capacity toward thermal-dense flip-chip architectures. NHTSA Federal Motor Vehicle Safety Standard 108 color boundaries and intensity minimums compress qualification timelines for Tier 1 lamp suppliers.
- Residential Lighting:California Energy Commission Title 20 appliance standards mandate minimum efficacy and flicker performance, with testing documentation burdens falling heaviest on mid-volume suppliers serving multi-state distribution.
- Outdoor Displays:Environmental sealing requirements drive hermetic packaging specifications for digital signage across Texas and Florida commercial real estate markets.
- Backlighting:Display manufacturer consolidation concentrates procurement authority among direct OEM-account relationships, bypassing traditional specification-grade distributors.
Residential Lighting anchors the volume base while Automotive Lighting gains share at the steepest rate.
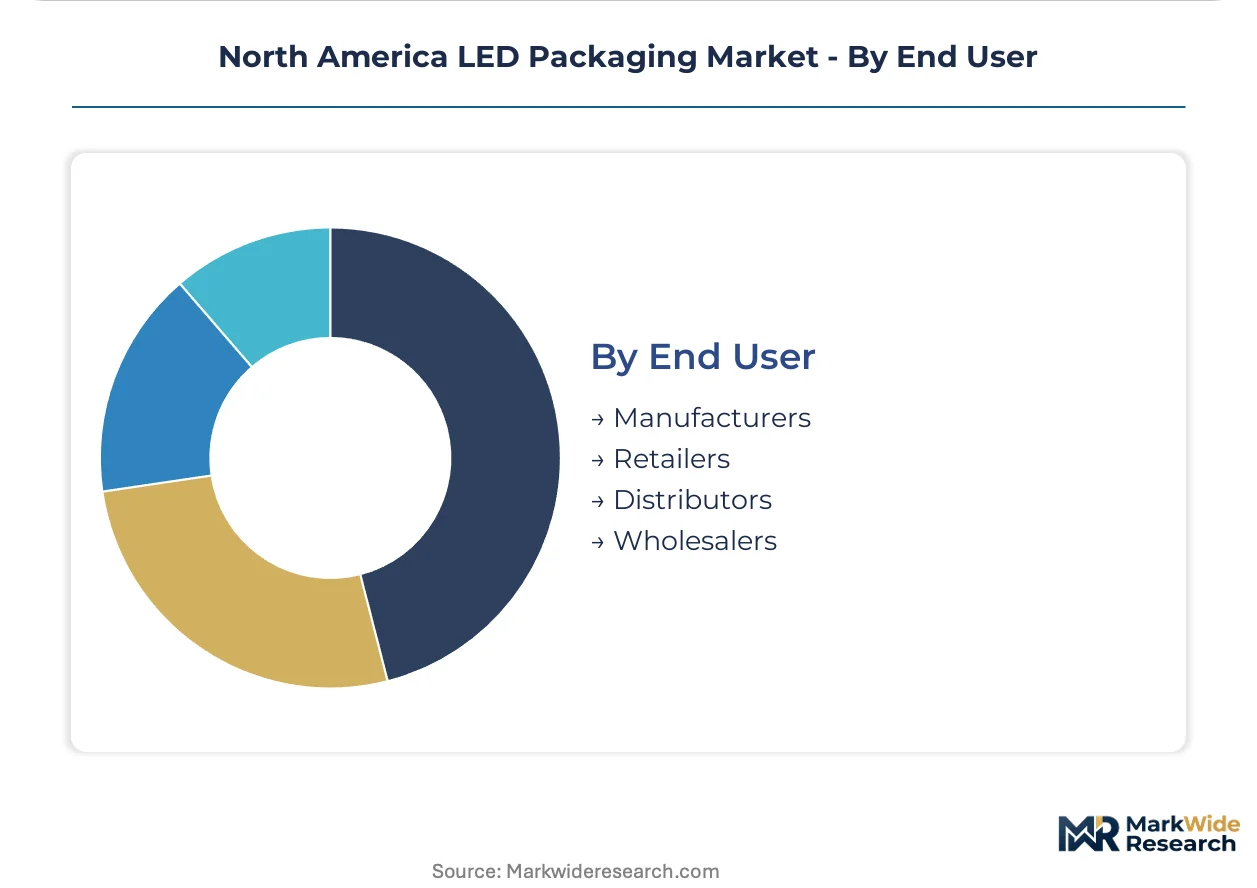
End User:
Margin capture concentrates upstream: Manufacturers retain phosphor formulation IP and thermal design value, while downstream distributors compete on logistics velocity and SKU breadth.
- Manufacturers:Vertical integration into die attach, wire bond, and lensing operations captures margin pools in specification-grade commercial and automotive channels. Acuity Brands Lighting dominates US commercial building projects through direct OEM-account relationships.
- Distributors:Channel compression from energy-as-a-service contracts transfers specification authority to financed performance guarantees, squeezing traditional stocking distributor roles.
- Retailers:Private-label sourcing from qualified Tier 1 packaging partners enables California lighting assemblers to manage Title 20 compliance costs without internal testing infrastructure.
- Wholesalers:Fragmented regional electrical codes for ballast-compatible LED tube packaging force SKU proliferation and inventory carrying cost concentration.
Manufacturers anchor the volume base while Distributors face the steepest share compression from channel restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration varies sharply across the continent: automotive OEMs cluster near Detroit and Tennessee manufacturing corridors, commercial building owners dominate retrofit procurement in Texas and Florida, and horticultural operators drive spectral-tuning demand across California and Arizona controlled-environment agriculture.
United States
EPA ENERGY STAR efficacy mandates above 150 lumens per watt force lumen depreciation redesigns for commercial retrofit projects. The US Department of Energy solid-state lighting program dictates minimum performance thresholds that reshape product qualification costs. Michigan and Tennessee automotive electrification corridors pull high-power packaging capacity toward thermal-dense flip-chip architectures for electric vehicle headlamp modules.
Canada
Building owners in Ontario and British Columbia bundle LED retrofit procurement with energy-as-a-service contracts, transferring specification authority from distributors to financed performance guarantees. Health Canada and PMRA environmental standards influence packaging material selection for horticultural applications. The Pacific Northwest cluster near Vancouver attracts chip-on-board investment for controlled-environment agriculture serving export markets.
Mexico
Electronics assembly concentration in Baja California near Tijuana anchors surface-mount-device capacity serving US commercial building retrofit programs. USMCA rules of origin enable tariff-efficient packaging operations for automotive OEMs across the southern US manufacturing belt. The maquiladora duty advantages accelerate cross-border manufacturing integration for federal building retrofit supply chains.
California
California Energy Commission Title 20 appliance standards mandate minimum efficacy and flicker performance below 30 percent at 100 Hz, imposing optical testing burdens on mid-volume suppliers. The state's controlled-environment agriculture sector commands premium spectral-tuning modules with far-red and UV-A emitter integration. Silicon Valley adjacent development labs drive MicroLED pixel-density research for augmented reality headset applications.
Texas
Commercial real estate property management platforms in Dallas and Houston standardize lighting specifications across portfolio-wide rollouts, compressing traditional distributor channels. The state's independent electrical grid operator ERCOT influences building automation integration requirements for LED control systems. Cross-border manufacturing integration with Mexican maquiladora operations creates duty-advantaged supply routes for automotive Tier 1 suppliers.
North America LED Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification-grade and volume-driven segments. The market structure tilts toward consolidation in automotive and commercial building channels where qualification timelines and regulatory compliance create entry barriers. Three archetypes dominate: silicon carbide substrate specialists, chip-on-board spectral-tuning developers, and vertically integrated lighting OEMs. Competitive moves concentrate on backward integration into die attach and wire bond operations, plus direct OEM-account relationships that bypass traditional distribution.
Among US-based players, Acuity Brands Lighting occupies a position exemplifying channel-control through vertical distribution networks, while Wolfspeed represents the substrate-technology archetype leveraging silicon carbide expertise. Lumileds Holding sits within the R&D-intensive tier focused on chip-on-board arrays. These three anchors illustrate how competitive positioning stratifies across thermal architecture specialization, spectral-tuning capability, and specification-grade channel access.
| Leading Market Players |
|---|
| Acuity Brands Lighting |
| Wolfspeed |
| General Electric |
| Hubbell |
| LSI Industries |
| Lumileds Holding |
| Cree |
| OSRAM |
| Eaton |
| Others |
Value Network & Pricing Analysis
Overcapacity in Mexico's Baja California surface-mount-device assembly cluster is compressing contract margins for mid-tier packaging houses serving US commercial retrofit channels, while automotive flip-chip capacity in Michigan and Tennessee commands premium pricing through thermal-architecture scarcity and NHTSA qualification barriers.
Pricing Analysis
Cost-plus contracts indexed to gallium nitride wafer spot markets dominate raw material pass-through arrangements for chip-scale packaging operations. Three-tier pricing structure across premium, standard, and economy levels separates NHTSA-qualified automotive emitters from commercial retrofit grades and consumer electronics commodity volumes. Pricing pressure stems from SMD commoditization in Mexico assembly corridors, squeezing mid-tier suppliers lacking thermal-design differentiation. Residential retrofit distributors exhibit highest price sensitivity, while automotive Tier 1 procurement teams prioritize junction-temperature reliability over unit cost.
Supply Chain Analysis
Upstream gallium nitride substrate fabrication concentrates in the United States, Japan, and Germany, with merchant wafer supply resting on Wolfspeed's silicon carbide integration and limited qualified alternatives. Phosphor deposition materials, ceramic submounts, and thermal interface compounds anchor bill-of-materials volatility. Single-source vulnerability in qualified gallium nitride epitaxy exposes packaging houses to allocation rationing during power semiconductor demand spikes. Distribution runs through vertically integrated lighting OEMs with direct OEM-account relationships, bypassing traditional specification-grade stocking distributors in Texas and Florida commercial real estate channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory compliance tiers—California Title 20 flicker mandates, NHTSA automotive qualification, and federal ENERGY STAR efficacy thresholds—creates defendable niche positions for specialists mastering discrete certification pathways rather than competing as generalists.
For Market Incumbents: Pre-empt MicroLED display substitution threats by accelerating chip-on-board spectral-tuning development for horticultural and medical applications where phosphor-converted emitters retain irreplaceable value. Consolidate backward integration into die attach and wire bond operations to capture margin pools escaping to substrate suppliers. Defend automotive channel position through parallel thermal-optical validation tracks that compress PPAP timelines below competitor reach. For New Entrants and Emerging Players: Mid-market commercial buildings in Texas and Florida represent the most penetrable entry point, where property management platform standardization bypasses incumbent distributor relationships and rewards direct OEM engagement. Horticultural spectral-tuning modules for California and Arizona controlled-environment agriculture offer premium positioning with lower NHTSA qualification barriers. Go-to-market execution should anchor on energy-as-a-service contract bundling that transfers specification authority from traditional sales channels to financed performance guarantees. For Investors and Strategic Acquirers: Capital is best deployed toward chip-on-board spectral-tuning developers with captive phosphor formulation IP and validated thermal architectures for electric vehicle headlamp modules. Long-term viability hinges on regulatory compliance differentiation rather than scale economies in SMD commodity assembly. Watch for EPA ENERGY STAR specification revision cycles as inflection indicators that reshape qualification cost structures and consolidate mid-tier supplier exits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Die Attach Operations | Captures margin pools from substrate suppliers while accelerating NHTSA qualification timelines for automotive Tier 1 contracts. |
| Spectral-Tuning Module Development | Opens premium positioning in California and Arizona controlled-environment agriculture through far-red and UV-A emitter integration. |
| Direct OEM-Account Relationship Expansion | Bypasses distributor channel compression in Texas and Florida commercial real estate markets where property management platforms standardize specifications. |
| Thermal Simulation Talent Acquisition | Addresses finite element modeling scarcity that constrains new entrant qualification speed in flip-chip automotive architectures. |
| Cross-Border Maquiladora Capacity Expansion | Leverages USMCA rules of origin for tariff-efficient automotive packaging serving southern US manufacturing corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA ENERGY STAR certification databases, NHTSA Federal Motor Vehicle Safety Standard 108 compliance filings, and US Department of Energy solid-state lighting program technical reports. Primary interviews engaged packaging engineering directors, automotive Tier 1 procurement managers, commercial lighting specification agents, and horticultural facility operators across Michigan, Tennessee, California, and Texas. Bottom-up triangulation across die attach equipment utilization rates and top-down validation through lighting fixture shipment data anchored volume estimates.
Forecast inputs span product type segmentation across chip-on-board, surface-mount-device, and dual in-line formats; technology splits between conventional phosphor-converted and MicroLED architectures; and application channels from automotive forward lighting through residential retrofit. CAGRs derive from regression analysis of historical efficacy improvement curves and regulatory mandate implementation schedules. Industry-specific inputs include gallium nitride wafer supply elasticity and NHTSA qualification timeline compression trends.
Practitioners should monitor gallium nitride substrate allocation rationing, California Title 20 flicker compliance test burden evolution, and MicroLED display capital allocation shifts for early signals of forecast revision. Cross-checking against US Department of Energy solid-state lighting program shipment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Europe Outdoor LED Lighting Market
LED
Architectural LED Products Market
LED
Saudi Arabia LED Lights Market
LED
China Outdoor LED Lighting Market
LED
LED Tester Market
LED
Africa LED Lighting Market
LED
France Indoor LED Lighting Market
LED
Small Pitch LED Display Market
LED
LED High Bay Drivers Market
LED
LED Phosphor Materials Market
LED
Mini LED Display Market
LED
Middle East LED Lighting Market
LED
North America Micro-LED Display Market
LED
Led Video Walls Market
LED
Asia Pacific LED Lighting Market
LED
UV-C LED Market