
 Burglar Alarm Systems Market | 2026-2036
Burglar Alarm Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Burglar Alarm Systems Market Intelligence
Multi-source component procurement is rebalancing toward vertically integrated supply chains as chipset shortages exposed vulnerabilities in alarm panel manufacturing. Honeywell International leverages captive semiconductor sourcing to sustain production continuity across North American and Asian assembly plants. Bosch differentiates through in-house sensor fabrication that anchors its premium motion-detection portfolio. ADT competes on brand strength and installer network density rather than hardware ownership, positioning itself as a service-first platform.
Burglar alarm systems are integrated electronic security installations comprising control panels, detection sensors, communication modules, and audible or silent alerting mechanisms designed to detect unauthorized entry and initiate response protocols. These systems employ hardwired or radio-frequency communication topologies with detection thresholds typically calibrated between 15 and 35 kilograms of force for vibration sensors and coverage cones spanning 90 to 110 degrees for passive infrared detectors. Wireless systems lead volume shipments due to reduced installation labor and retrofit compatibility in aging building stock, while monitored systems command superior recurring revenue margins through central station contracts. DIY installation is expanding fastest among residential end users seeking subscription flexibility without truck-roll dependency, though professional installation retains structural importance in commercial and government verticals where liability certification and insurance underwriting require documented compliance.
Underwriters Laboratories certification and EN 50131 European security grading standards shape product design thresholds and market access conditions across developed economies. The FCC regulates radio-frequency emissions from wireless alarm transmitters in the United States, while GDPR and the EU AI Act constrain biometric analytics and cloud-stored event data in European deployments. Stakeholders must monitor evolving insurance industry requirements for smart verification protocols, as carriers progressively tie premium reductions to alarm systems capable of delivering video-confirmed dispatch data rather than conventional sensor-triggered alerts alone.
Market Dynamics
Smart home platform convergence is compressing hardware margins while elevating software and recurring service revenue as the primary value capture mechanism in residential security.
Growth Catalysts
- EU AI Act compliance mandates:Biometric analytics restrictions in European deployments are accelerating demand for privacy-preserving edge-computing alarm hubs that process data locally rather than in cloud environments.
- Insurance underwriting evolution:Carriers in Germany and the United Kingdom now mandate video-verified dispatch protocols for premium discounts, forcing upgrades from legacy sensor-only systems.
- Retrofit building stock:Wireless radio-frequency topologies enable penetration of aging residential structures across France and Italy without invasive wiring, expanding addressable installation bases.
Market Restraints
- Semiconductor supply concentration:Alarm panel manufacturing remains exposed to foundry capacity constraints in Taiwan and South Korea, creating 16-24 week lead time volatility for control unit chipsets.
- GDPR data localization costs:European cloud storage mandates for event footage require redundant regional data centers, adding 12-18% to platform operating overhead.
- DIY substitution pressure:Self-install camera systems from consumer electronics channels erode professional monitoring attachment rates in price-sensitive residential segments.
Strategic Opportunities
- Eastern European security infrastructure:Poland and Romania exhibit alarm penetration below 15% of households versus 45%+ in Germany, presenting greenfield installation growth.
- Cellular IoT communication modules:5G RedCap and LTE-M standards enable battery-powered outdoor sensors without Wi-Fi dependency, opening detached structure monitoring applications.
- France's MaPrimeRénov subsidy scheme:Energy-efficiency-linked home improvement credits now cover connected security upgrades, reducing homeowner acquisition costs by 20-30%.
Industry Challenges
- EN 50131 Grade 2/3 certification timelines:European security grading approvals require 8-14 months of third-party testing, delaying product launches and compressing technology refresh cycles.
- Legacy hardwired system integration:Commercial retrofit projects demand protocol bridges between 1980s-1990s installed bases and modern IP platforms, inflating engineering complexity and project risk.
- Central station operator staffing:Monitored service growth outpaces trained dispatcher availability in the United Kingdom and Germany, constraining service expansion capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burglar Alarm Systems Market |
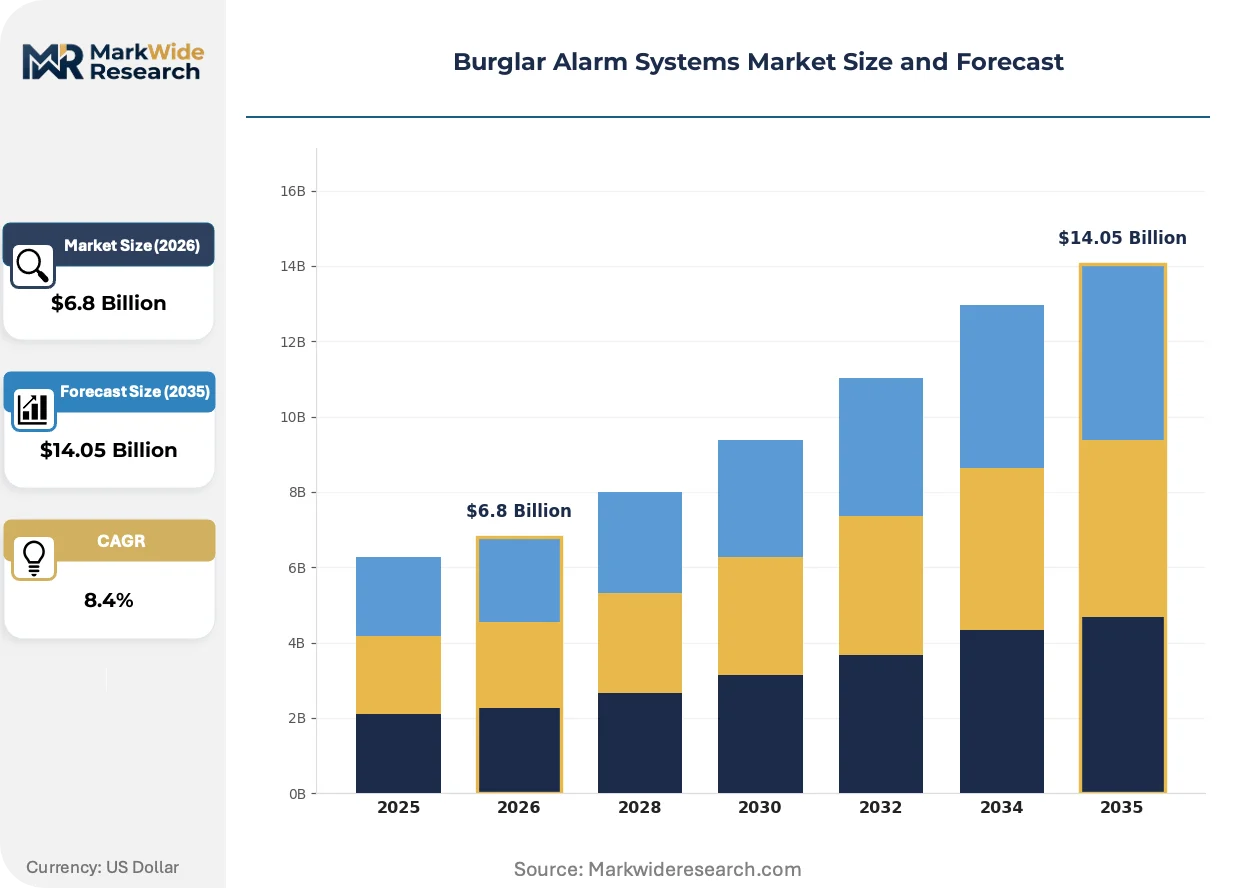
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Systems, Wireless Systems, Monitored Systems, Unmonitored Systems Technology: IP Cameras, Motion Sensors, Smart Detectors, Sound Alarms End User: Residential, Commercial, Government, Industrial Installation: Professional, DIY, Retrofit, Integrated Solutions |
| Companies Covered | Honeywell International, ADT, Johnson Controls, Bosch, ASSA ABLOY, Hangzhou Hikvision Digital Technology, Napco Security Technologies, Securitas AB, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burglar Alarm Systems Market Strategic Shifts & Innovations
Edge artificial intelligence and matter protocol standardization are converging to redefine how alarm systems authenticate threats and interoperate with broader smart home ecosystems.
On-device neural processing units in passive infrared and dual-technology sensors are rewriting false-alarm economics. Commercial integrators in Germany and the Netherlands are deploying these chips to filter pet movement and environmental triggers before transmission. This compression of cloud dependency is reducing central station dispatch costs while accelerating insurer acceptance of sensor-only verification.
The EU AI Act's risk-classification framework for biometric identification systems is restructuring product roadmaps. Manufacturers serving France, Italy, and Spain must now segregate facial recognition capabilities into standalone modules subject to conformity assessments. This regulatory friction is pushing development resources toward behavioral analytics based on gait and thermal signatures rather than stored biometric templates.
Subscription unbundling is fragmenting the residential buyer journey. German and Austrian consumers increasingly purchase hardware through retail channels before activating monitoring services through competing software platforms. This channel disintermediation is eroding traditional installer-captured lifetime value while rewarding brands with direct-to-consumer configuration tools and transparent month-to-month pricing.
Burglar Alarm Systems Market Segmentation
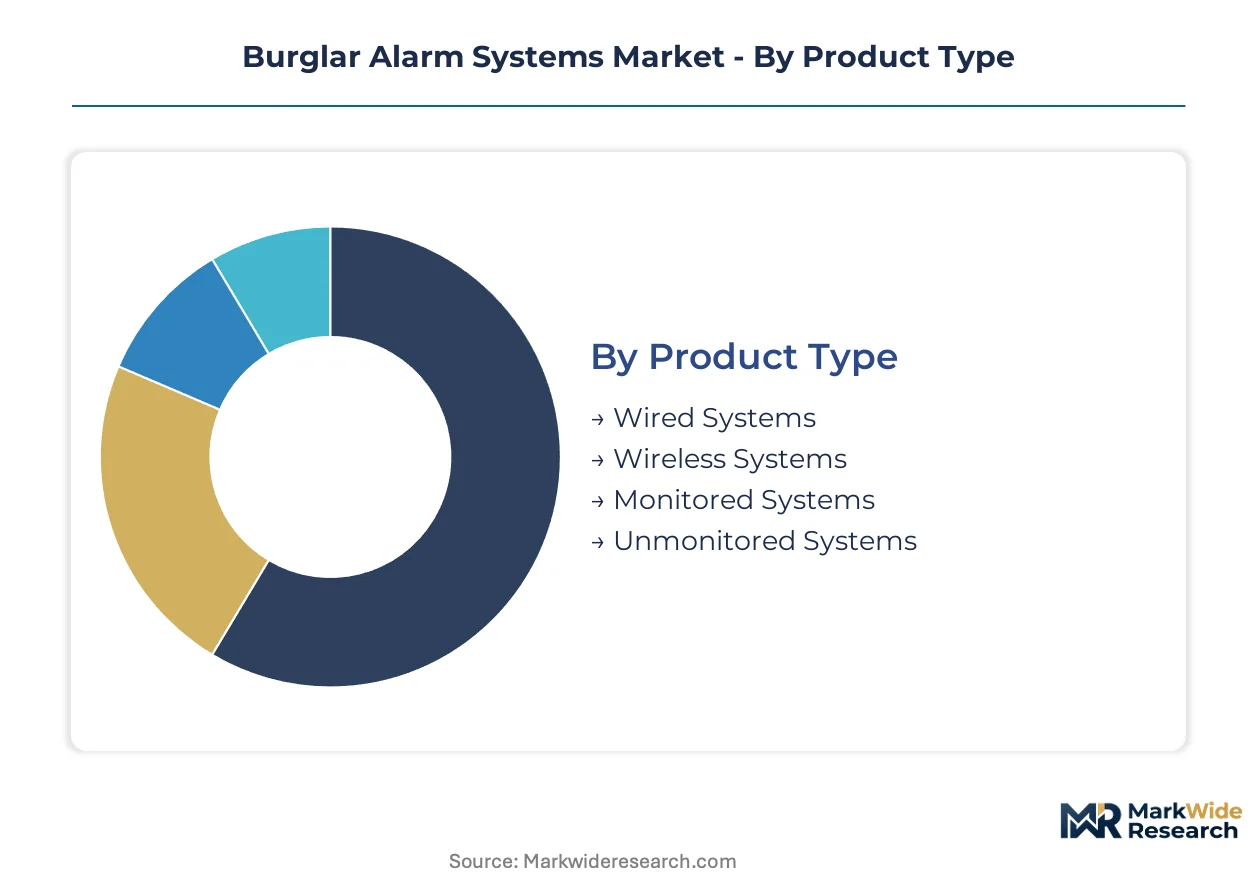
Segmentation in the burglar alarm systems market reveals distinct capital requirements, technology maturity curves, and customer acquisition economics across product architectures and deployment modes. Understanding these divisions illuminates where manufacturers must concentrate R&D investment versus where service platforms capture recurring revenue.
Product Type:
Capital intensity varies sharply across product architectures, with monitored and wireless systems demanding sustained platform investment while wired alternatives require heavier upfront manufacturing tooling.
- Wireless Systems:Radio-frequency mesh networks eliminate conduit installation, reducing truck-roll labor by 60-70% in retrofit applications across aging German and French housing stock. Battery-powered sensor nodes with 5-10 year lifespans concentrate demand in residential renovations where invasive wiring is impractical.
- Monitored Systems:Central station contracts generate 18-24 month payback periods on subscriber acquisition costs, with cellular and broadband communication modules enabling verified dispatch protocols that satisfy insurer requirements in the United Kingdom and Germany. This segment anchors recurring revenue models for service-first platforms.
- Wired Systems:Hardwired control panels with dedicated power and signaling infrastructure dominate new commercial construction in Poland and Romania where electrical contractors integrate security during build-out.
- Unmonitored Systems:Local audible and visual alerts without central station linkage serve price-sensitive residential segments and detached agricultural structures in Eastern European markets.
Monitored systems absorb the bulk of installed capacity; wireless systems are expanding most quickly.
Technology:
Technology segments stratify by processing location—edge versus cloud—with direct implications for GDPR compliance costs and false-alarm reduction economics.
- Smart Detectors:Multi-sensor fusion devices combining passive infrared, microwave, and acoustic signatures with on-device neural processing filter environmental noise before transmission. German integrators deploy these for pet-immune detection in apartment complexes where false dispatches incur municipal penalties.
- IP Cameras:Video verification capabilities satisfy evolving insurance underwriting standards, with edge storage and local analytics reducing cloud dependency to meet EU AI Act biometric processing restrictions.
- Motion Sensors:Passive infrared and dual-technology detectors remain volume leaders in basic perimeter protection, with 90-110 degree coverage cones standardizing across residential and small commercial deployments.
- Sound Alarms:Decibel-rated audible deterrents and silent panic triggers complete layered protection schemes, with integration into smart home ecosystems via Matter protocol standardization.
Smart detectors command the steepest expansion trajectory; motion sensors retain the largest installed base.
End User:
End user segments diverge by procurement authority, certification requirements, and sensitivity to total cost of ownership versus upfront capital expenditure.
- Residential:Homeowner-driven purchases through retail and direct-to-consumer channels emphasize smartphone integration and subscription flexibility, with DIY installation penetration climbing fastest in German and Austrian markets.
- Commercial:Property managers and security directors mandate EN 50131 Grade 2/3 certification, professional installation documentation, and insurance-compliant verification protocols, concentrating demand in United Kingdom retail and office verticals.
- Government:Municipal and national security procurement requires extended warranty terms, domestic content preferences, and compliance with classified facility standards, limiting vendor pools in France and Italy.
- Industrial:Manufacturing and logistics facilities integrate alarm systems with access control and process safety networks, with harsh environment ratings driving sensor specification in Eastern European automotive plants.
Commercial deployments absorb dominant procurement volume; residential channels are climbing the fastest.
Installation:
Installation mode determines margin capture location—hardware sale versus ongoing service—and shapes customer lifetime value calculations.
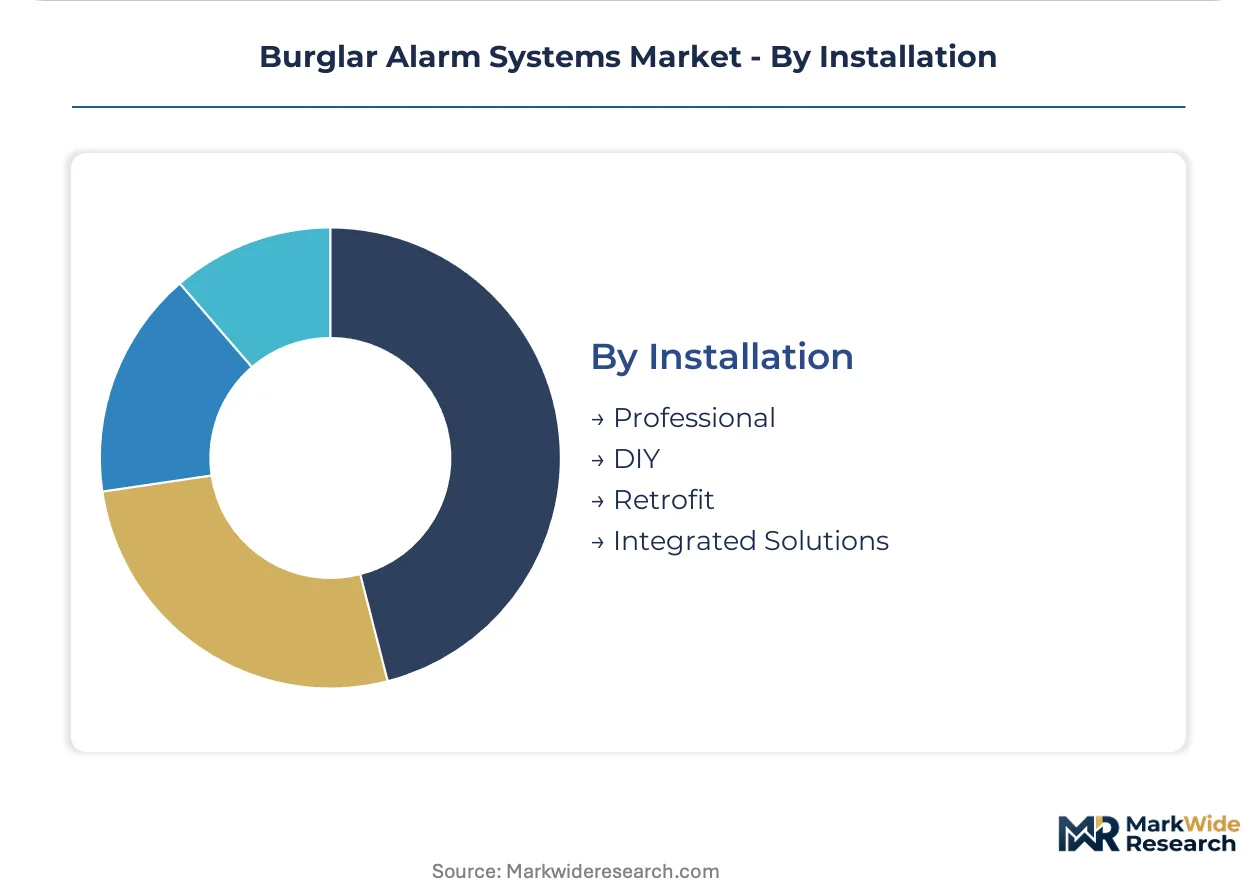
- DIY:Self-configuration tools and peel-and-stick sensors eliminate installer dependency, with month-to-month monitoring subscriptions attracting German consumers who resist long-term contracts. This mode fragments traditional installer-captured value.
- Professional:Certified technician deployment satisfies liability and insurance requirements in commercial and government verticals, with documentation of EN 50131 compliance mandatory for premium discounts.
- Retrofit:Wireless topologies enable penetration of 1960s-1980s building stock across France and Italy without structural modification, expanding addressable bases beyond new construction cycles.
- Integrated Solutions:Single-vendor platforms combining intrusion detection, fire alarm, access control, and video management concentrate in United Kingdom healthcare and education estates seeking unified command interfaces.
Professional installation retains structural importance in commercial verticals; DIY modes are gaining share fastest in residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, the United Kingdom, and France as these markets lead the European security infrastructure upgrade cycle. Residential smart home adoption and insurance-mandated video verification protocols are reshaping procurement patterns across these core economies.
Germany
Homeowners drive demand for DIY wireless systems with flexible subscription terms, while commercial property managers enforce EN 50131 Grade 2/3 certification for insurance compliance. The EU AI Act restricts biometric cloud processing, pushing Hamburg and Munich integrators toward edge-computing alarm hubs. Bavaria's industrial corridor anchors manufacturing of premium motion-detection sensors for export markets.
United Kingdom
Carriers now mandate video-verified dispatch for premium discounts, accelerating replacement of legacy sensor-only installations. GDPR data localization requirements inflate platform operating costs for cloud-stored event footage. Greater London concentrates central station operator capacity, though staffing shortages constrain service expansion in Manchester and Birmingham clusters.
France
The MaPrimeRénov subsidy scheme reduces homeowner acquisition costs by covering connected security upgrades alongside energy-efficiency renovations. CNIL guidance on biometric analytics complicates facial recognition deployments in smart detectors. The Île-de-France region hosts system integrators serving both residential retrofit and government procurement verticals.
Poland
Alarm penetration below 15% of households creates greenfield growth opportunity as wireless topologies bypass invasive wiring in aging building stock. National infrastructure investment programs stimulate commercial construction in Warsaw and Kraków. Local distributors increasingly partner with German manufacturers for EN 50131-certified product supply.
Italy
Retrofit wireless systems penetrate 1960s-1980s residential structures across Rome and Milan without structural modification. Insurance industry adoption of video verification lags northern European benchmarks, preserving demand for basic monitored systems. Northern industrial districts integrate alarm networks with factory access control and process safety systems.
Burglar Alarm Systems Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers seek to bridge hardware capabilities with software platform reach. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive semiconductor supply, specialized security platforms competing on installer network density, and consumer electronics entrants leveraging retail channel access. Two archetypes command attention: vertically integrated sensor fabricators and service-first monitoring platforms. M&A activity and technology licensing agreements represent the primary competitive vectors as firms address EU AI Act compliance requirements.
Among diversified industrial conglomerates, Honeywell International and Johnson Controls occupy positions anchored by upstream control over critical component supply. Bosch exemplifies the in-house fabrication archetype through its premium motion-detection portfolio. ADT represents the service-first platform model, competing on brand strength and installer network density rather than hardware ownership. These three anchors illustrate how competitive positioning splits between manufacturing control and recurring revenue capture.
| Leading Market Players |
|---|
| Honeywell International |
| ADT |
| Johnson Controls |
| Bosch |
| ASSA ABLOY |
| Hangzhou Hikvision Digital Technology |
| Napco Security Technologies |
| Securitas AB |
| Siemens |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up monitoring platforms anchor pricing discipline through recurring revenue models that buffer hardware margin compression, while their consolidated central station networks concentrate buyer power over sensor suppliers in Germany and the United Kingdom.
Pricing Analysis
Volume concentration in wireless DIY systems compresses hardware margins to 15-25% while monitored service contracts sustain 60-70% gross margins through recurring billing. Three-tier pricing structure across EN 50131 Grade 3 certified, Grade 2 compliant, and uncertified economy systems differentiates procurement in commercial verticals. Pricing pressure stems from cellular IoT module cost inflation tied to semiconductor foundry constraints. Residential DIY buyers exhibit highest price sensitivity, while government and healthcare verticals accept premium pricing for documented compliance.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for control panel chipsets, where foundry capacity constraints create procurement bottlenecks. Alarm panel manufacturing draws from Chinese PCB fabrication, German sensor component supply, and Malaysian final assembly. Tariff exposure on Chinese electronics imports threatens cost structures for North American market entrants. Distribution runs through installer networks in commercial verticals, direct-to-consumer retail in residential segments, and systems integrators for government procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry constraints prop pricing power for manufacturers with captive chip supply, transforming procurement urgency into margin defense for vertically integrated incumbents.
For Market Incumbents: Anticipate DIY substitution pressure from consumer electronics channels by accelerating edge-AI sensor development that differentiates professional-grade verification. Secure EN 50131 certification pipelines to maintain insurance-linked pricing premiums. Consolidate installer network density in United Kingdom commercial corridors where central station staffing shortages constrain competitor expansion.
For New Entrants and Emerging Players: Eastern European property managers in Poland and Romania present underserved buyer archetypes with sub-15% alarm penetration and greenfield wireless retrofit demand. Target cellular IoT outdoor sensor applications for detached agricultural and industrial structures bypassing Wi-Fi dependency. Pursue white-label partnerships with German distributors seeking EN 50131-certified product supply.
For Investors and Strategic Acquirers: France's MaPrimeRénov subsidy expansion is the leading indicator that connected security will embed into energy-efficiency renovation financing, extending hardware replacement cycles. Monitor service-first platforms with dense installer networks as acquisition targets. Watch for EU AI Act enforcement actions against cloud-dependent biometric systems as signals of edge-computing valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Sensor Development | On-device neural processing reduces GDPR cloud costs while satisfying EU AI Act biometric restrictions. |
| EN 50131 Certification Investment | Grade 2/3 approvals unlock insurance-mandated commercial procurement in Germany and United Kingdom. |
| Cellular IoT Module Integration | 5G RedCap and LTE-M standards enable battery-powered outdoor sensors without Wi-Fi infrastructure. |
| Installer Network Expansion | Dense technician coverage satisfies liability documentation requirements in healthcare and government verticals. |
| Strategic Partnership with Distributors | Polish and Romanian channel alliances accelerate penetration of underpenetrated Eastern European markets. |
Research Approach
Trade association filings, customs import records, and central station operator regulatory disclosures formed the secondary backbone, supplemented by primary interviews with security systems integrators, central station operations directors, EN 50131 certification body assessors, and insurance underwriting specialists. Bottom-up shipment data from control panel and sensor manufacturers combined with top-down spending estimates from property management and government procurement databases. Triangulation across these sources validated segment-level volume and pricing assumptions.
Historical trendline analysis of wireless versus wired installation ratios, monitored versus unmonitored system attachment rates, and DIY penetration curves established baseline growth patterns across the projection horizon. The analytical framework modeled product type, technology, end user, and installation mode segments with regional regulatory cluster differentiation. CAGRs derived from weighted average of technology diffusion rates and replacement cycle assumptions, incorporating cellular IoT module adoption curves and edge-AI sensor deployment timelines as industry-specific inputs.
Revisions become necessary when semiconductor foundry capacity constraints ease, EU AI Act enforcement actions accelerate, or insurance underwriting standards shift beyond video verification. Forecasts reflect documented assumptions about subsidy program continuity, certification timeline stability, and central station labor availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Home Security Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Full Body Scanner Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Global Traveler Security Services Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Maritime Security Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Seaport Security Management Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Threat Detection Systems Market