
 Workwear Accessories Market | 2026-2036
Workwear Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Workwear Accessories Market Analytics
OSHA's updated personal protective equipment enforcement is hardening demand for certified workwear accessories across hazardous occupations. 3M Company leverages its respiratory and hearing protection integration to sustain cross-selling momentum in industrial channels. Honeywell International Inc. anchors its position through advanced materials science applied to cut-resistant gloves and thermal barriers. Ansell Limited specializes in chemical-resistant hand protection, competing on specification depth for pharmaceutical and laboratory end-users.
Workwear accessories encompass supplementary protective and functional items—belts, gloves, headgear, and footwear—engineered with technical specifications such as ANSI cut-level ratings, arc-flash thermal protection values, and slip-resistant outsole coefficients to shield workers from occupational hazards. These products serve primary industrial and commercial purposes across construction, manufacturing, agriculture, and hospitality settings where physical risk exposure demands standardized protective coverage. Gloves dominate product-type revenue pools due to universal mandate coverage and frequent replacement cycles, while headgear captures accelerated growth from electrical utility and oil-and-gas sector specification upgrades. Leather and advanced synthetic materials command premium positioning as cotton-basic segments face margin compression from commoditization.
FDA oversight of medical-grade protective textiles, EPA guidelines on chemical permeation testing, and OSHA's 29 CFR 1910 standards collectively shape product certification requirements and market access barriers for workwear accessory manufacturers. Compliance documentation demands are intensifying as procurement officers at corporations and government agencies require traceable conformity assessment records. Stakeholders must monitor evolving state-level occupational safety amendments and federal infrastructure procurement clauses that embed domestic content preferences into contractor purchasing decisions.
Market Dynamics
OSHA's 29 CFR 1910 enforcement tightening is compressing replacement cycles for certified protective equipment while redirecting contractor purchasing toward traceable supply chains. This regulatory pressure is restructuring procurement relationships between industrial end-users and domestic manufacturers.
Growth Catalysts
- Flame-Resistant Nylon Blends:Electrical utilities and oil-and-gas operators are mandating arc-flash rated headgear and gloves, pulling material innovation toward performance-grade textile suppliers.
- Federal Infrastructure Spending:United States transportation and energy project awards are elevating contractor purchasing volumes for ANSI-compliant protective accessories.
- OSHA Workplace Safety Mandates:Compliance timeline acceleration across construction and manufacturing is hardening demand for certified respiratory and hearing protection integration.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic fiber production costs fluctuate with crude oil derivatives, compressing margins for advanced material suppliers.
- Domestic Content Procurement Clauses:Federal infrastructure awards embed Buy America preferences that constrain sourcing flexibility for multinational contractors.
- Cotton-Basic Commoditization:Standard cotton glove segments face margin erosion as low-cost imports flood distribution channels.
Strategic Opportunities
- Smart PPE Convergence:Wearable sensor integration with traditional protective equipment opens specification upgrades for connected workforce platforms.
- Rental and Leasing Channels:Industrial laundries and safety service providers are capturing recurring revenue through managed glove and garment programs.
- State-Level Occupational Safety Amendments:California and Texas are implementing supplemental PPE requirements beyond federal baselines, creating premium tier demand.
Industry Challenges
- Conformity Assessment Documentation:Procurement officers now require traceable third-party certification records, extending sales cycles and compliance costs.
- Technical Textile Talent Scarcity:Performance-grade material engineering expertise concentrates among a narrow supplier base, constraining innovation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workwear Accessories Market |
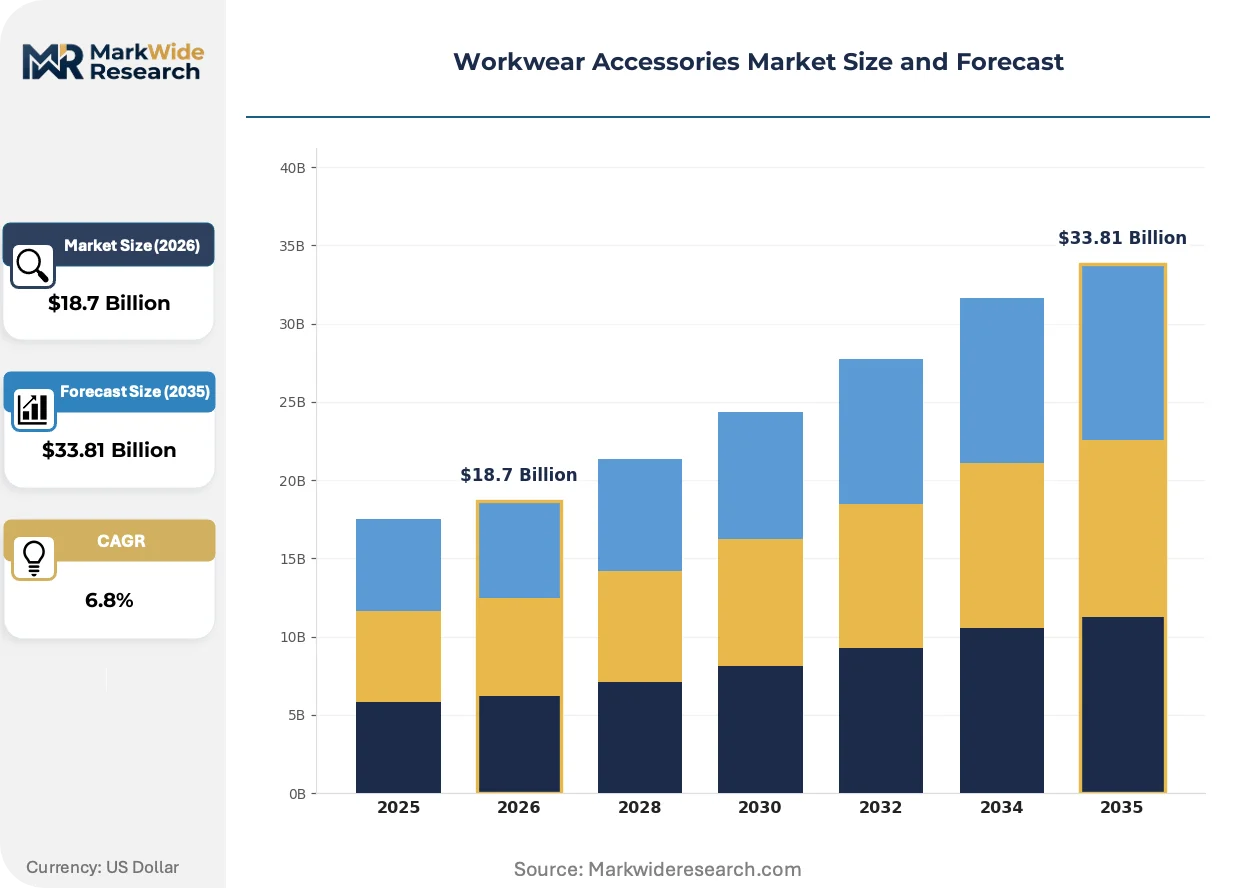
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belts, Gloves, Headgear, Footwear Material: Cotton, Polyester, Leather, Nylon Application: Construction, Manufacturing, Agriculture, Hospitality Customer Type: Small Businesses, Corporations, Government, Contractors |
| Companies Covered | 3M Company, Honeywell International Inc., Ansell Limited, DuPont de Nemours, Inc., MSA Safety Incorporated, Kimberly-Clark Professional, Lakeland Industries, Inc., Delta Plus Group, Portwest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workwear Accessories Market Evolving Landscape
Technical textile advancement and procurement digitization are restructuring how protective accessories are specified, sourced, and deployed across hazardous occupations. Three intersecting developments are compressing traditional supply relationships.
Aerogel-infused thermal barrier fabrics are absorbing market share from conventional insulated gloves in high-heat industrial applications. Steel foundries and aluminum smelters are adopting these materials for their superior heat-to-weight ratios. This absorption is compressing demand for bulkier leather-palm alternatives and enabling slimmer hand-protection designs that improve dexterity.
OSHA's updated personal protective equipment enforcement is mandating documented hazard assessments before procurement authorization. Industrial safety managers must now maintain conformity assessment records for every SKU deployed. Construction and electrical utility sectors are responding by consolidating vendor relationships toward full-line suppliers capable of integrated respiratory, hearing, and hand protection.
Managed safety programs are displacing transactional spot purchasing for high-turnover consumables like cut-resistant gloves. Industrial laundries and regional safety distributors are capturing volume through scheduled replenishment contracts with usage tracking. This shift is most visible among Fortune 500 manufacturing facilities in the Midwest and Southeast where procurement centralization has advanced furthest.
Workwear Accessories Market Segmentation
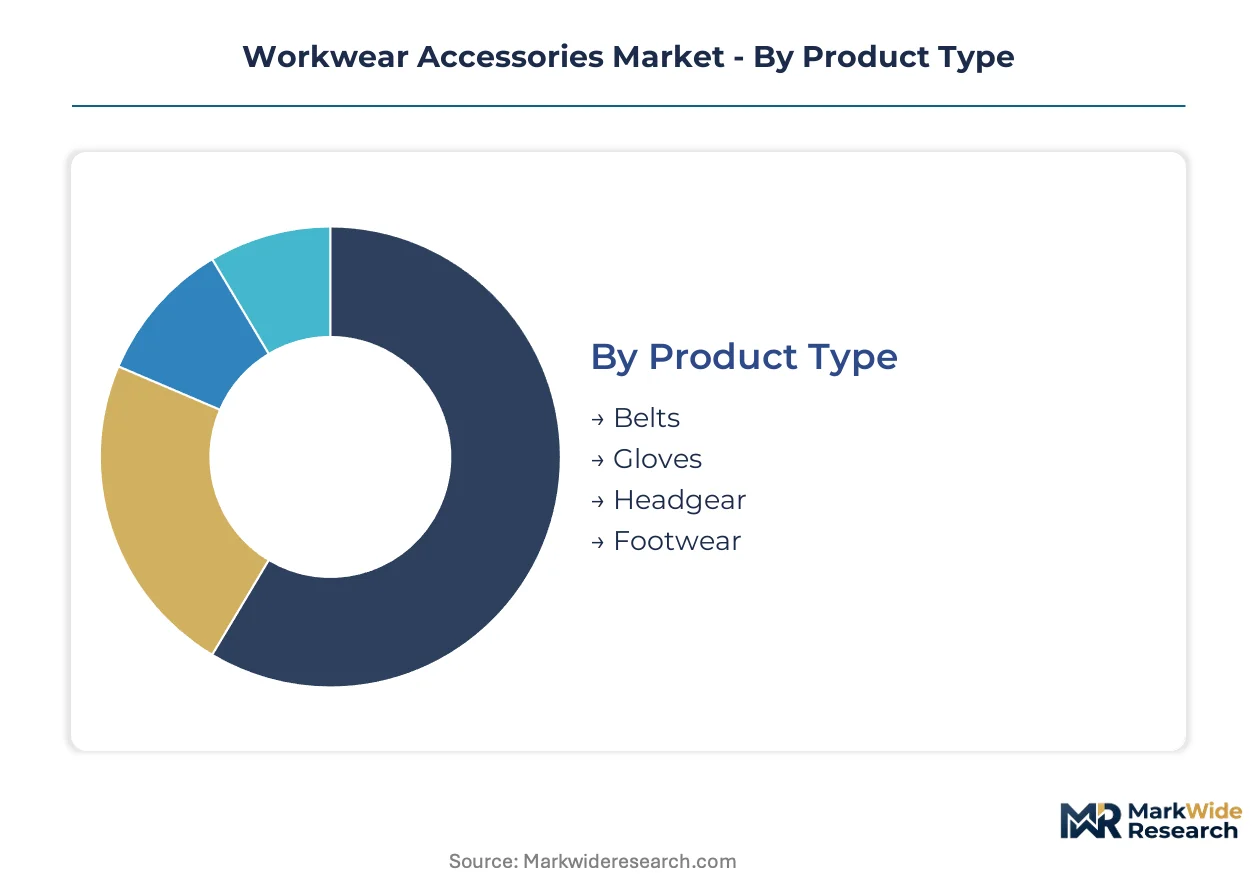
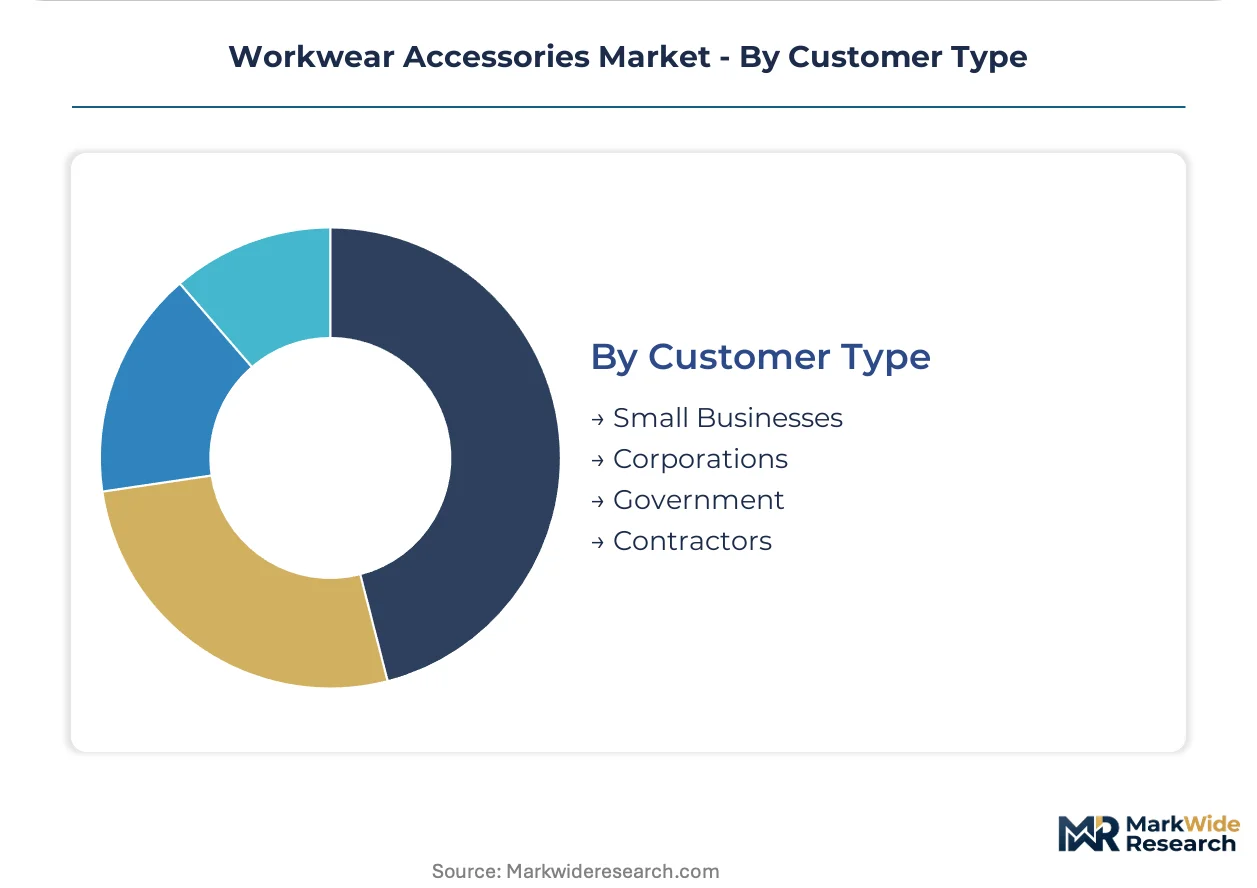
Workwear accessories procurement varies sharply across buyer categories and use environments. Specification requirements, replacement cycles, and compliance burdens differ enough that manufacturers organize product development and channel strategy around distinct segment profiles.
Product Type:
Buyer specifications center on hazard exposure severity and replacement frequency when selecting accessory categories.
- Gloves:Engineered with ANSI cut-level ratings and chemical permeation barriers, these consumables dominate procurement volumes due to universal OSHA mandate coverage and frequent replacement cycles. Demand concentrates in manufacturing and electrical utilities where arc-flash and cut hazards drive specification upgrades toward performance-grade materials.
- Headgear:Hard hats and protective helmets incorporate impact resistance and electrical insulation ratings per 29 CFR 1910.135. Construction sector procurement is accelerating as federal infrastructure awards elevate contractor purchasing volumes for ANSI-compliant head protection.
- Belts:Tool belts and safety harnesses feature load-bearing webbing and quick-release buckles for fall protection compliance. Logging and roofing contractors drive specialized demand for high-visibility and flame-resistant variants.
- Footwear:Safety boots integrate slip-resistant outsoles, composite toe caps, and puncture-resistant midsoles per ASTM standards. Warehouse and distribution centers prioritize ergonomic cushioning for prolonged standing applications.
Gloves lead on scale; headgear leads on momentum.
Material:
Cost-performance tradeoffs and regulatory compliance requirements shape raw material selection across end-use applications.
- Leather:Full-grain and split leather deliver abrasion resistance and thermal protection for welding and foundry operations. Premium positioning persists despite synthetic competition where dexterity and washability matter less than durability.
- Nylon:Flame-resistant nylon blends with arc-flash thermal protection values redirect electrical utility and oil-and-gas procurement toward performance-grade textile suppliers. Technical innovation in fiber engineering is compressing demand for heavier alternatives.
- Cotton:Basic knit gloves face margin erosion from low-cost import competition in general material handling and light assembly tasks. Commoditization pressures concentrate sourcing decisions on unit cost alone.
- Polyester:Synthetic blends offer moisture-wicking and high-visibility color retention for outdoor and high-heat environments. Agriculture and landscaping contractors favor polyester-based accessories for extended wear comfort.
Leather maintains premium positioning; nylon gains share fastest.
Application:
Industry-specific hazard profiles determine certification requirements and procurement centralization patterns.
- Construction:Multi-hazard exposure drives integrated respiratory, hearing, and hand protection procurement. OSHA enforcement tightening compresses replacement cycles and redirects purchasing toward full-line suppliers with documented conformity assessment capabilities.
- Manufacturing:Assembly line automation and chemical processing create divergent demand for cut-resistant gloves versus chemical barriers. Fortune 500 facilities in the Midwest and Southeast are consolidating vendor relationships through managed safety programs.
- Agriculture:Seasonal labor patterns and outdoor exposure prioritize weather-resistant materials and high-visibility features. Smaller operational scale sustains spot purchasing through regional distributors.
- Hospitality:Food service and housekeeping applications emphasize disposable and launderable options with basic protection ratings. Price sensitivity dominates procurement decisions in this fragmented customer base.
Construction commands the largest procurement volumes; manufacturing shows the steepest consolidation trajectory.
Customer Type:
Procurement sophistication and compliance documentation requirements vary dramatically across buyer scale and organizational structure.
- Corporations:Centralized procurement functions at Fortune 500 manufacturers mandate traceable third-party certification records and consolidated vendor relationships. Managed glove and garment programs through industrial laundries are displacing transactional spot purchasing.
- Contractors:Federal infrastructure award recipients face domestic content procurement clauses that constrain sourcing flexibility. Buy America preferences embed compliance complexity into protective equipment selection.
- Government:Municipal and federal agency purchasing follows strict competitive bidding protocols with emphasis on domestic manufacturing verification. Extended sales cycles accompany multi-layer approval requirements.
- Small Businesses:Independent tradespeople and local service providers rely on retail and regional distributor channels with limited specification expertise. Price sensitivity and immediate availability drive purchasing behavior.
Corporations lead on contract value; contractors show the most rapid specification upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The workwear accessories industry traces its modern scaling to early industrial safety movements in the United States and Germany, where standardized protective equipment first gained regulatory backing in mining and steel production. OSHA's establishment in 1970 and subsequent European harmonization through CE marking created the compliance frameworks that now govern procurement across industrialized economies.
United States
Federal infrastructure spending and tightening OSHA enforcement drive contractor purchasing volumes for ANSI-compliant headgear and gloves. The 29 CFR 1910 standards mandate documented conformity assessments, compressing replacement cycles. Houston's oil-and-gas sector and Chicago's manufacturing corridor anchor concentrated demand for arc-flash rated accessories.
Germany
Automotive precision manufacturing and chemical processing sustain premium demand for cut-resistant and chemical-barrier hand protection. REACH compliance and DGUV regulations enforce strict permeation testing documentation. The Ruhr industrial region and Bavarian automotive clusters concentrate procurement through managed safety programs with full-line suppliers.
China
Construction sector expansion and manufacturing export compliance pull demand for both domestic-grade and export-certified protective equipment. GB standards alignment with international norms accelerates specification upgrading. The Yangtze River Delta and Pearl River Delta manufacturing belts generate volume demand for synthetic material gloves and basic head protection.
India
Infrastructure buildout and industrial safety consciousness expansion create dual-tier demand for premium certified and cost-optimized protective accessories. BIS certification requirements and state-level factory safety amendments tighten compliance timelines. Gujarat's petrochemical corridor and Maharashtra's automotive manufacturing zones drive specification-grade procurement growth.
Japan
Aging workforce demographics and construction labor shortages elevate automation-compatible protective equipment demand. METI industrial safety guidelines and JIS standards enforce rigorous product certification. The Kanto region's dense manufacturing base and Osaka's machinery sector concentrate advanced material glove adoption.
Workwear Accessories Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and material performance tiers, creating a stratified competitive structure. The market consolidates around full-line safety suppliers capable of integrated respiratory, hearing, and hand protection documentation. Three archetypes dominate: diversified industrial conglomerates with cross-selling platforms, specialized hand protection manufacturers with chemical-barrier expertise, and regional fabricators serving price-sensitive spot purchasing. M&A activity targets conformity assessment capabilities and geographic expansion into infrastructure-heavy markets.
Within the diversified conglomerate tier, 3M Company and Honeywell International Inc. occupy positions defined by respiratory and hearing protection integration with accessory lines. Ansell Limited exemplifies the specialized chemical-resistant hand protection archetype, competing on specification depth for pharmaceutical and laboratory end-users. These three anchors represent contrasting strategic postures: cross-selling platform breadth versus vertical specialization in barrier technologies.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Ansell Limited |
| DuPont de Nemours, Inc. |
| MSA Safety Incorporated |
| Kimberly-Clark Professional |
| Lakeland Industries, Inc. |
| Delta Plus Group |
| Portwest |
| Others |
Value Network & Pricing Analysis
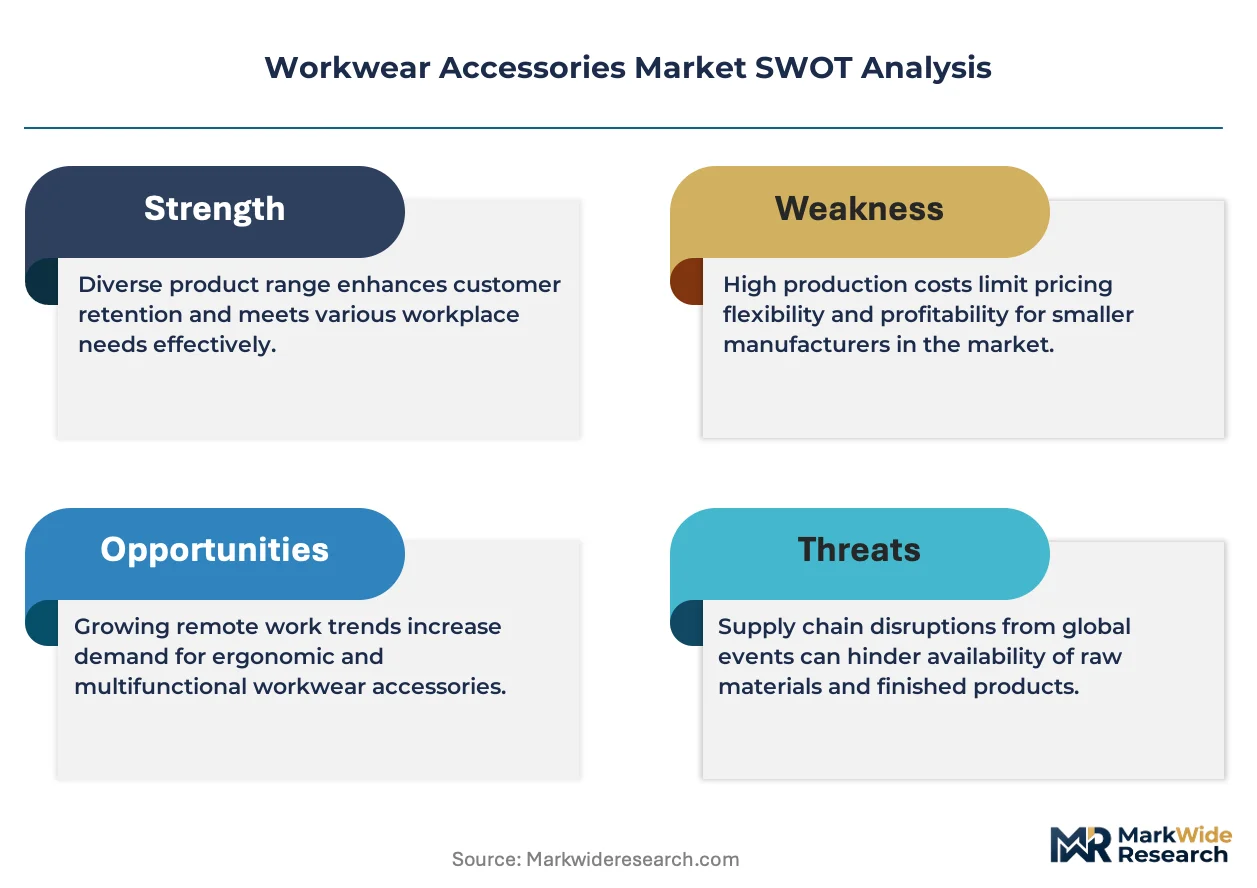
Petrochemical feedstock volatility cascades through synthetic fiber production costs into three distinct pricing tiers for ANSI-certified gloves and arc-flash rated headgear, with performance-grade nylon blends commanding premium positioning against cotton-basic imports facing margin compression from spot-market sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates flame-resistant nylon blends with arc-flash thermal protection values from basic cotton knits and disposable synthetics. Price differentiation hinges on certification depth—OSHA 29 CFR 1910 compliance documentation versus uncertified imports—and volume scale through managed safety program contracts. Pricing pressure stems from low-cost Asian imports flooding general material handling segments, compressing margins for commodity-grade cotton gloves. Small independent contractors exhibit highest price sensitivity, while Fortune 500 manufacturers prioritize traceable conformity assessment over unit cost.
Supply Chain Analysis
Buy America procurement clauses embedded in federal infrastructure awards are reshaping sourcing patterns for domestic manufacturers serving contractor channels. Raw material supply concentrates in China for synthetic fiber precursors, Vietnam for cut-resistant yarn processing, and the United States for technical textile finishing and certification. Component dependencies span petrochemical derivatives for nylon blends, chromium-tanned leather for welding applications, and copper-threaded fabrics for electrical conductivity. Single-source vulnerability concentrates in performance-grade fiber engineering expertise. Distribution runs through industrial laundries and regional safety distributors capturing recurring revenue via managed replenishment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The workwear accessories market functions as a geographic-arbitrage play where OSHA enforcement timelines in the United States outpace regulatory development in India, creating premium-tier demand displacement toward early-compliance suppliers.
For Market Incumbents: Deploy conformity assessment documentation capabilities as a competitive moat against emerging spot-purchasing platforms. Expand technical textile engineering capacity in domestic facilities to satisfy Buy America procurement clauses. Consolidate vendor relationships with electrical utilities and oil-and-gas operators before arc-flash specification upgrades peak. Threat substitution from smart PPE sensor integration demands pre-emptive R&D investment in connected workforce compatibility. For New Entrants and Emerging Players: The premium-economy price gap in chemical-resistant hand protection for pharmaceutical and laboratory end-users offers white-space entry. Target state-level occupational safety amendments in California and Texas where supplemental PPE requirements exceed federal baselines. Agricultural seasonal labor markets remain underpenetrated for weather-resistant high-visibility accessories. Go-to-market through industrial laundry partnerships enables recurring revenue capture without direct sales force buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where conformity assessment capabilities concentrate among narrow supplier bases while procurement officers mandate traceable third-party certification records. Long-term viability favors full-line safety suppliers with integrated respiratory, hearing, and hand protection documentation. Acquisition target archetype: regional fabricators with established industrial laundry relationships and untapped arc-flash certification capacity. Signal to watch: federal infrastructure award acceleration triggering contractor purchasing volume spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Textile Production | Captive supply of flame-resistant nylon blends insulates margin from petrochemical volatility. |
| Smart PPE Sensor Platform Development | Wearable integration with traditional protective equipment opens specification upgrades for connected workforce deployments. |
| Managed Safety Program Expansion | Industrial laundry partnerships displace transactional spot purchasing with scheduled replenishment contracts. |
| Arc-Flash Certification Investment | OSHA electrical utility mandates compress replacement cycles for thermal barrier gloves and headgear. |
| Geographic Manufacturing Footprint Diversification | Domestic content compliance satisfies federal infrastructure procurement clauses constraining multinational contractors. |
Research Methodology
Bottom-up construction and manufacturing demand modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with safety procurement officers at Fortune 500 manufacturers, industrial laundry operations directors, federal contracting compliance managers, and technical textile R&D leads combined with secondary validation from OSHA enforcement databases, ANSI certification registries, federal infrastructure award disclosures, and customs import records. Triangulation between end-user consumption patterns and domestic production capacity estimates anchors volume projections.
Input-output matrices map petrochemical feedstock costs through synthetic fiber production into finished accessory pricing tiers across the projection horizon. Segmentation dimensions include product type, material grade, application hazard profile, and customer procurement sophistication. CAGRs derive from regression analysis of historical replacement cycle compression against regulatory enforcement intensity. Industry-specific forecast inputs incorporate OSHA 29 CFR 1910 compliance timeline acceleration and federal infrastructure spending authorization trajectories.
Caveats apply where petrochemical price volatility, trade policy shifts, or smart PPE technology disruption could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure appropriation levels. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
Uniforms and Workwears Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Welding Curtains Market