
 Activated Partial Thromboplastin Test Market | 2026-2036
Activated Partial Thromboplastin Test Market Size, Share, and Industry Trends Forecast 2026-2036
Activated Partial Thromboplastin Test Market Outlook
The EU Green Deal's healthcare sustainability targets is rebalancing procurement criteria for diagnostic consumables across European hospital networks. Siemens Healthineers leverages its installed base of coagulation analyzers to sustain recurring reagent revenue streams. Abbott anchors its competitive position through integrated point-of-care testing platforms that reduce laboratory turnaround times.
An activated partial thromboplastin test measures the intrinsic and common coagulation pathways using phospholipid reagents, calcium chloride, and patient plasma to detect clotting time in seconds, primarily screening for heparin therapy monitoring and bleeding disorder diagnosis. Reagents capture the largest margin pool due to recurring consumption tied to analyzer installed bases, while optical detection technology leads instrument shipments because of throughput advantages in high-volume hospital laboratories. Test kits for near-patient settings represent the fastest-growing product format as decentralized diagnostic models expand.
The FDA's Class II device controls and the EU MDR's post-market surveillance requirements shape product registration timelines and clinical evidence burdens for manufacturers entering either market. ISO 15189 accreditation standards for medical laboratories drive analyzer precision specifications and quality control protocol standardization. Stakeholders must monitor evolving hemostasis guideline updates from clinical societies to anticipate shifts in testing frequency and panel configuration demands.
Market Dynamics
The Activated Partial Thromboplastin Test Market is restructuring around decentralized diagnostic models that compress laboratory turnaround times while elevating point-of-care precision requirements. This shift is fragmenting traditional hospital-centric procurement patterns and forcing reagent manufacturers to engineer platform-agnostic consumables.
Growth Catalysts
- Heparin Therapy Monitoring Protocols:Anticoagulation management standards from clinical hematology societies are mandating more frequent aPTT testing for hospitalized patients on unfractionated heparin, driving test volume expansion in acute care settings.
- EU MDR Quality Mandates:The Medical Device Regulation's tightened post-market surveillance requirements are accelerating analyzer replacement cycles as laboratories upgrade to compliant instrumentation.
- Aging Demographics in Developed Economies:Japan's super-aged population and Germany's expanding chronic disease burden are elevating coagulation disorder screening frequency in outpatient clinics.
Market Restraints
- Phospholipid Reagent Supply Concentration:Specialized lipid sourcing for high-sensitivity reagents concentrates among a limited supplier base in Switzerland and Germany, creating input vulnerability.
- Optical Detection Component Lead Times:Precision photometric modules for coagulation analyzers face extended procurement cycles from specialized Japanese and German component manufacturers.
- Direct Oral Anticoagulant Substitution:DOAC therapies requiring less intensive monitoring than heparin are compressing routine aPTT test utilization in certain therapeutic segments.
Strategic Opportunities
- Near-Patient Test Kit Expansion:Cardiology clinics and ambulatory surgical centers in the United States are adopting cartridge-based aPTT systems that bypass central laboratory workflows.
- ISO 15189 Accreditation Tailwinds:Medical laboratory quality standardization in France and Italy is creating replacement demand for analyzers with embedded quality control protocols.
- AI-Assisted Result Interpretation:Integration of machine learning algorithms with coagulation analyzers is enabling pattern recognition for rare bleeding disorders that manual review misses.
Industry Challenges
- Multiplex Assay Development Expertise:Engineering reagents that simultaneously detect lupus anticoagulant and standard aPTT requires rare hybridization of immunoassay and coagulation chemistry skill sets.
- Legacy Analyzer Integration Complexity:Hospital laboratories in Germany and Japan face technical friction connecting new reagent formats to decade-old installed analyzer bases without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Activated Partial Thromboplastin Test Market |
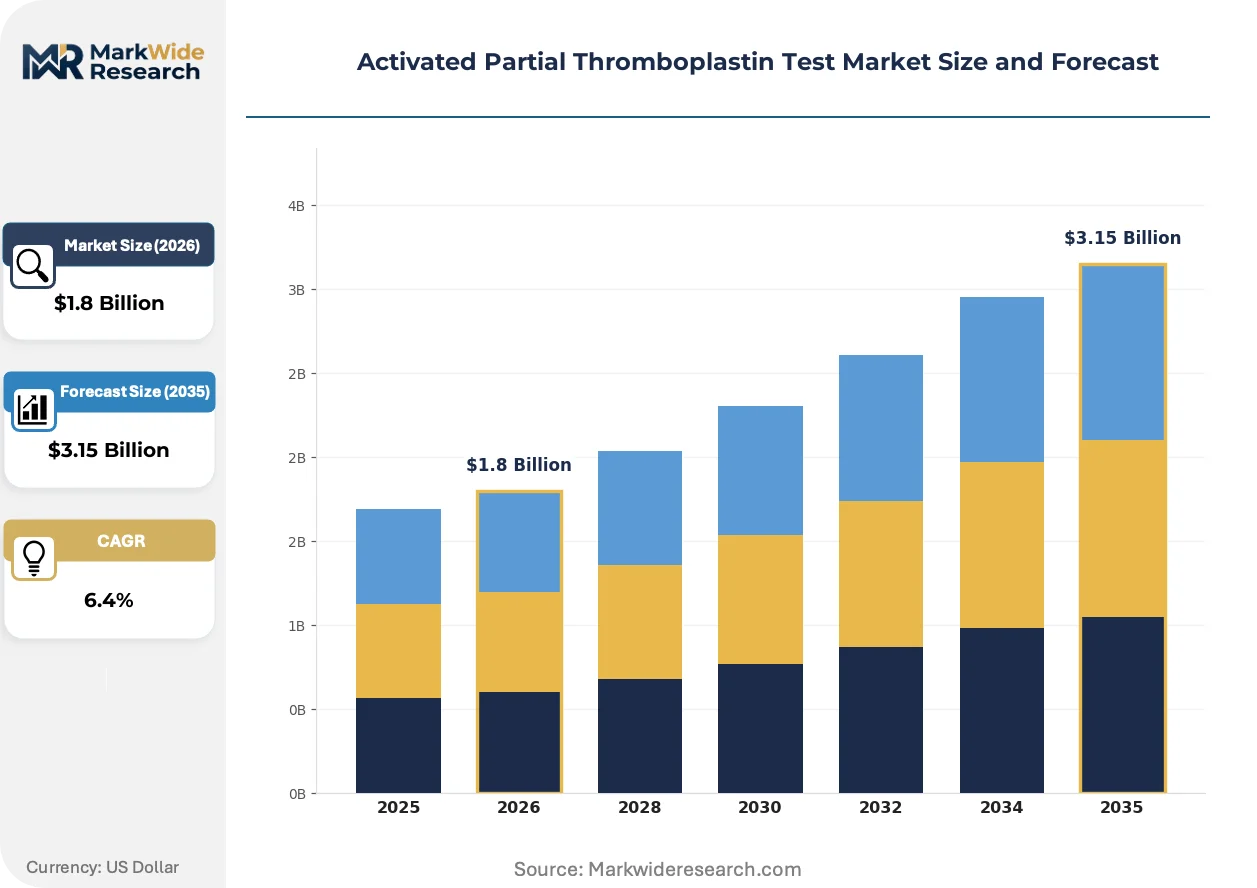
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Analyzers, Test Kits, Software End User: Hospitals, Diagnostic Laboratories, Blood Banks, Research Institutes Technology: Optical Detection, Mechanical Detection, Electrochemical Detection, Colorimetric Methods Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Abbott, Siemens Healthineers, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Bio-Rad Laboratories, Sysmex Corporation, Danaher, bioMérieux, Instrumentation Laboratory (Werfen), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activated Partial Thromboplastin Test Market Strategic Shifts
Diagnostic platform architecture is fragmenting as manufacturers engineer flexible instrument footprints that accommodate both high-throughput hospital laboratories and constrained point-of-care environments. This technical divergence is compressing traditional product lifecycle assumptions.
Microfluidic cartridge technology is modularizing coagulation testing by embedding reagent reservoirs, reaction chambers, and optical detection paths into disposable single-use units. Community hospitals and urgent care networks are adopting these systems at accelerating pace to bypass central laboratory bottlenecks. The technology is modularizing supply chain relationships as reagent and instrument purchasing decisions collapse into single consumable contracts.
The EU MDR's post-market surveillance requirements are extending clinical evidence obligations for in vitro diagnostic devices across the full product lifecycle. Manufacturers must now maintain active safety monitoring systems that feed into periodic safety update reports. High-volume reagent producers serving German and French hospital networks are restructuring quality management systems to accommodate this continuous compliance burden.
Consolidated purchasing by multi-hospital health systems is compressing vendor negotiation cycles and unbundling traditional reagent-instrument bundled contracts. Group purchasing organizations in the United States are extracting standalone pricing for consumables independent of analyzer placement agreements. This behavioral shift is most visible in California and Texas health systems where procurement centralization has advanced furthest.
Activated Partial Thromboplastin Test Market Segmentation
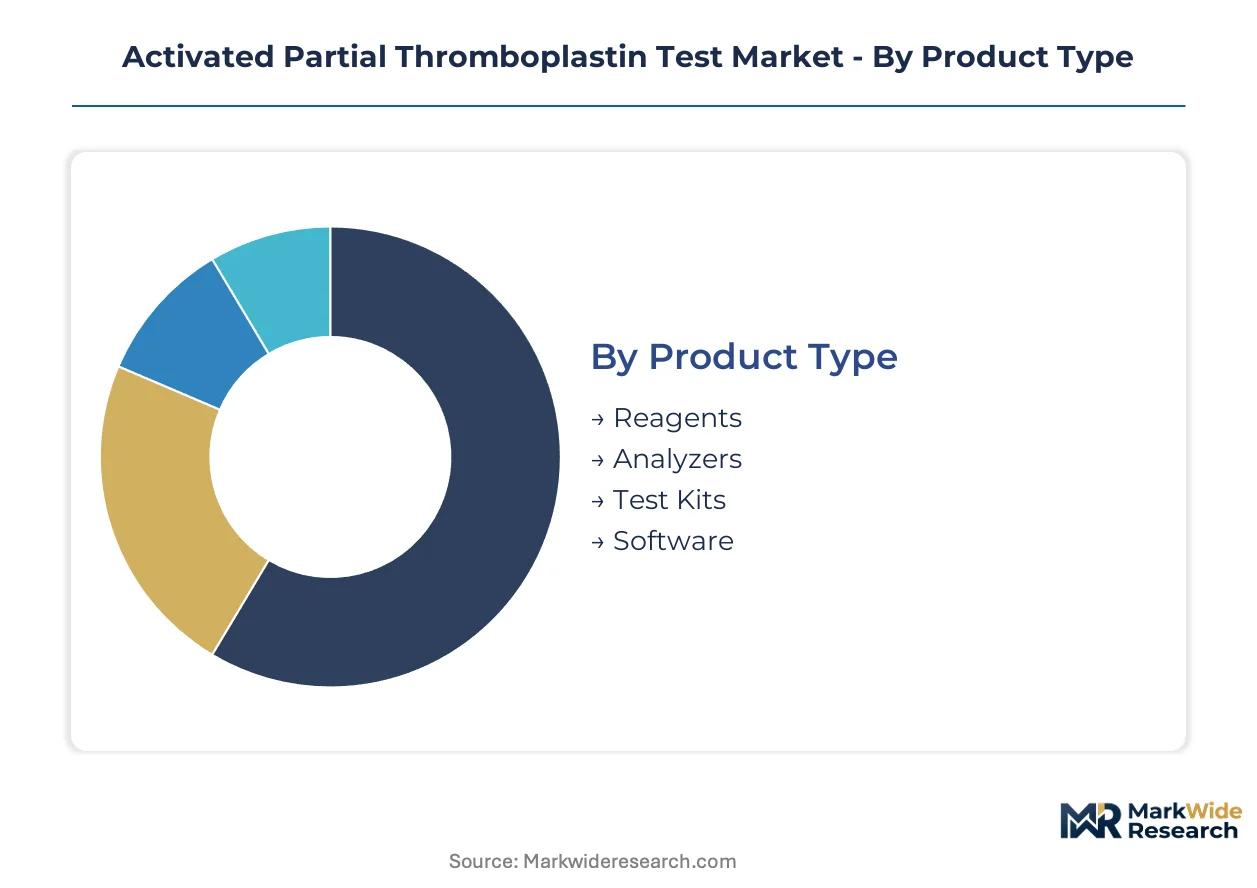
Segmentation in the aPTT market reveals how procurement decisions fragment across clinical settings and technical specifications. Reagent consumption patterns diverge sharply from capital equipment purchasing cycles, while point-of-care adoption is rewriting traditional channel economics.
Product Type:
Technical specifications determine margin structure and purchasing frequency across consumable and capital categories.
- Reagents:Phospholipid formulations combined with calcium chloride and activators constitute the recurring revenue foundation. German and Swiss hospital networks concentrate demand here due to high-throughput analyzer installed bases and strict EU MDR quality mandates.
- Analyzers:Optical detection systems with photometric modules dominate instrument shipments. Japanese component sourcing creates procurement lead time vulnerability for laboratories in the United States and Germany upgrading to compliant platforms.
- Test Kits:Cartridge-based near-patient formats are expanding most quickly in cardiology clinics and ambulatory surgical centers.
- Software:Embedded quality control protocols and AI-assisted result interpretation modules attach to analyzer sales.
Mature deployment sits with reagents. Newer deployment is concentrated in test kits.
End User:
Volume scale and testing frequency separate centralized laboratories from distributed care settings.
- Hospitals:Acute care settings in the United States and Japan drive the highest test volumes through heparin therapy monitoring protocols. Unfractionated heparin administration in surgical and ICU departments mandates frequent aPTT testing with turnaround time pressures.
- Diagnostic Laboratories:Independent and hospital-affiliated labs in Germany and France pursue ISO 15189 accreditation, forcing analyzer replacement cycles. Centralized processing captures economies in high-volume coagulation panels.
- Blood Banks:Donor screening and component therapy validation create specialized demand for high-precision reagent formulations.
- Research Institutes:Rare bleeding disorder studies and hemostasis research consume specialized reagent grades outside routine clinical specifications.
High-volume testing concentrates in hospitals. Decentralized expansion is concentrated in diagnostic laboratories.
Technology:
Detection methodology determines throughput capacity, maintenance burden, and result precision specifications.
- Optical Detection:Photometric clot detection using light scatter or turbidimetry delivers throughput advantages for high-volume hospital laboratories. German and Japanese manufacturers dominate precision module supply.
- Mechanical Detection:Viscosity-based measurement using steel ball or cup-and-ball mechanisms offers simplicity for point-of-care environments. Blood banks and smaller clinics favor these systems for robustness.
- Electrochemical Detection:Impedance-based approaches are emerging in portable cartridge formats for near-patient testing.
- Colorimetric Methods:Visual endpoint detection persists in resource-constrained settings and educational applications.
Established laboratory infrastructure relies on optical detection. Portable and distributed deployment is concentrated in mechanical and electrochemical formats.
Distribution Channel:
Channel selection reflects capital intensity, technical support requirements, and procurement centralization trends.
- Direct Sales:Analyzer manufacturers deploy field service engineers for installation and maintenance in large hospital networks. Multi-hospital health systems in California and Texas negotiate consolidated purchasing agreements directly with vendors.
- Distributors:Regional medical supply distributors manage reagent logistics for mid-sized laboratories across Germany and France. Cold chain requirements for phospholipid formulations favor established distribution infrastructure.
- Online Retail:E-procurement platforms capture standardized consumable orders from smaller clinics and research institutes.
- Wholesalers:Bulk purchasing intermediaries serve blood banks and government health systems with predictable volume contracts.
Complex system sales run through direct channels. High-velocity consumable replenishment is concentrated in distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors North American hemostasis diagnostics development, with Massachusetts General Hospital and Brigham and Women's Hospital driving clinical validation protocols for novel coagulation assays.
United States
Acute care hospitals in Texas and California execute the highest unfractionated heparin monitoring volumes through centralized laboratory networks. FDA Class II device controls mandate clinical evidence packages for analyzer modifications, extending registration timelines for manufacturers seeking 510(k) clearance. The Texas Medical Center in Houston coordinates multi-site procurement for reagent standardization across its affiliated institutions.
Germany
Diagnostic laboratories in Bavaria and North Rhine-Westphalia pursue ISO 15189 accreditation with intensified quality control protocols for coagulation panels. The EU MDR's post-market surveillance requirements accelerate analyzer replacement cycles as facilities upgrade to compliant instrumentation. The Munich metropolitan cluster concentrates reagent manufacturing operations serving Central European hospital networks.
Japan
Super-aged demographic profiles in Tokyo and Osaka elevate chronic coagulation disorder screening frequency in outpatient hematology clinics. PMDA regulatory frameworks enforce stringent precision specifications for optical detection modules used in clinical analyzers. The Kansai region's precision manufacturing base supplies photometric components to domestic and export markets.
Switzerland
Specialized phospholipid reagent production concentrates in Basel and Zurich, creating supply vulnerability for high-sensitivity formulations. Swissmedic quality mandates align with EU MDR standards for in vitro diagnostic device certification. The Basel pharmaceutical-industrial complex integrates hemostasis research with diagnostic reagent development pipelines.
France
Public hospital networks in Île-de-France standardize coagulation testing protocols under national healthcare efficiency programs. ANSM post-market surveillance requirements mirror EU MDR clinical evidence obligations for device manufacturers. The Paris-Saclay research cluster advances microfluidic cartridge technology for near-patient testing applications.
Activated Partial Thromboplastin Test Market Competitive Environment
Premium-margin players sit above commodity-margin players across reagent formulation sophistication and analyzer detection precision. The market structure consolidates around integrated diagnostic platform vendors with captive installed bases and standalone reagent specialists serving multi-vendor laboratories. Three archetypes dominate: full-system integrators bundling instrumentation with consumable contracts, component specialists supplying precision optical modules, and platform-agnostic reagent houses engineering cross-compatible formulations. Competitive moves concentrate on strategic partnerships for microfluidic cartridge development and geographic expansion through distributor network acquisition.
Within the full-system integrator tier, Abbott and Siemens Healthineers occupy positions defined by installed analyzer footprints and recurring reant revenue streams. Sysmex Corporation represents the precision-component archetype with Japanese-origin photometric module supply. F. Hoffmann-La Roche Ltd sits within the platform-agnostic reagent specialist category, exemplifying Swiss-based formulation expertise that serves multi-vendor laboratory environments without captive instrumentation ties.
| Leading Market Players |
|---|
| Abbott |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| Danaher |
| bioMérieux |
| Instrumentation Laboratory (Werfen) |
| Others |
Value Chain & Pricing Dynamics
Consolidated purchasing by multi-hospital health systems in the United States is compressing vendor negotiation cycles and unbundling traditional reagent-instrument bundled contracts, forcing manufacturers to engineer platform-agnostic consumables and accept standalone pricing for consumables independent of analyzer placement agreements.
Pricing Analysis
Throughput-based pricing anchors analyzer contracts, with laboratories paying premium rates for optical detection systems that deliver higher sample-per-hour capacity and embedded quality control protocols. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15189-accredited laboratories from mid-tier hospitals and resource-constrained clinics. Cost compression in economy-tier reagents is intensifying because group purchasing organizations extract volume discounts. Blood banks and research institutes exhibit highest price sensitivity due to predictable volume contracts and alternative sourcing options.
Supply Chain Analysis
EU MDR local-content-equivalence requirements for post-market surveillance documentation are reshaping sourcing decisions, pushing manufacturers toward European-based quality management system investments. Phospholipid reagent formulation concentrates in Switzerland and Germany, while precision photometric modules for optical detection systems draw from Japanese component manufacturers. Single-source vulnerability sits with specialized lipid suppliers in Basel and Zurich. Distribution runs through regional medical supply distributors managing cold chain logistics for temperature-sensitive reagent formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized phospholipid reagent production concentrates among a limited supplier base in Switzerland and Germany, creating input scarcity that props pricing power for manufacturers with secured supply relationships.
For Market Incumbents: Extend platform-agnostic reagent compatibility to capture laboratories running decade-old analyzer bases without full replacement cycles. Secure backward integration into phospholipid sourcing through long-term contracts with Swiss lipid suppliers. Invest in AI-assisted result interpretation modules to differentiate analyzer offerings as direct oral anticoagulant substitution compresses routine test utilization. For New Entrants and Emerging Players: Enter via cartridge-based near-patient test kits for cardiology clinics and ambulatory surgical centers in the United States, where decentralized diagnostic models expand fastest. Target ISO 15189 accreditation tailwinds in France and Italy by offering analyzers with embedded quality control protocols at price points below full-system integrators. Pursue strategic partnerships with microfluidic technology developers to bypass capital-intensive optical detection module development. For Investors and Strategic Acquirers: The window for entry favors platform-agnostic reagent specialists with cross-compatible formulation expertise and established distributor relationships in German hospital networks. Long-term viability hinges on regulatory compliance capabilities under EU MDR post-market surveillance requirements and FDA Class II device controls. Watch for inflection signals in group purchasing organization consolidation patterns across California and Texas health systems.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Cartridge Development | Community hospitals bypass central laboratory bottlenecks through disposable single-use test units. |
| ISO 15189 Accreditation Alignment | French and Italian laboratories replace aging analyzers with quality-control-embedded instrumentation. |
| AI-Assisted Result Interpretation Integration | Machine learning algorithms enable pattern recognition for rare bleeding disorders manual review misses. |
| Platform-Agnostic Reagent Engineering | Reagent manufacturers serve multi-vendor laboratories without captive analyzer installed bases. |
| Distributor Network Acquisition | Cold chain infrastructure for phospholipid formulations accelerates geographic expansion into mid-sized European laboratories. |
Study Parameters
Independent corroboration across hospital procurement managers, biomedical engineers, GPO contracts managers, and clinical hematologists underwrites the qualitative findings in this study. Primary fieldwork with laboratory directors at Massachusetts General Hospital, Brigham and Women's Hospital, and Texas Medical Center affiliates combined with secondary validation through FDA 510(k) filings, EU MDR technical documentation, ISO 15189 accreditation databases, and hospital procurement contract records. Bottom-up test volume modeling and top-down market sizing triangulate demand estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions include product type, end user, detection technology, and distribution channel, with additional modeling of regulatory compliance tier and analyzer installed base vintage. CAGRs derive from test volume growth trajectories, replacement cycle timing, and pricing pressure vectors. Industry-specific forecast inputs incorporate heparin therapy monitoring protocol updates from clinical hematology societies and EU MDR implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phospholipid supply disruption scenarios or accelerated direct oral anticoagulant substitution patterns. Forecasts reflect assumptions documented in clinical guideline evolution, regulatory enforcement intensity, and health system procurement centralization trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Calprotectin Testing Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Chromatin Immunoprecipitation Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
Thyroid Test Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Specific Protein Testing Market