
 Global Ambulatory EHR Market | 2026-2036
Global Ambulatory EHR Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambulatory EHR Market Foresight
Subscription-based interoperability layers is hardening as the core revenue mechanism in ambulatory EHR sales. Epic Systems Corporation leverages its deep integration with academic medical centers to extend into affiliated outpatient networks. Oracle Cerner anchors enterprise-scale deployments across multi-site physician practices. eClinicalWorks competes aggressively on price for independent primary care groups while sustaining R&D investment in voice-enabled documentation tools.
Ambulatory electronic health records are digital systems designed for outpatient care settings, typically featuring HL7 FHIR-compliant APIs, cloud-native architectures with sub-100-millisecond query response times, and modular clinical decision support engines. These platforms enable real-time patient data capture, billing automation, and care coordination across disconnected outpatient sites. Cloud-based deployment dominates new procurement cycles as health systems abandon capital-intensive on-premise data centers, while specialty clinics represent the fastest-expanding application segment due to procedure-specific template requirements and value-based contract reporting needs. Physician practices remain the largest end-user pool, though ambulatory surgery centers are gaining share as same-day procedure volumes rise.
The US Office of the National Coordinator for Health IT enforces interoperability standards through the Cures Act Final Rule, penalizing information blocking and mandating patient-access APIs. Germany's BfArM oversees the gematik infrastructure for electronic patient records, creating compliance-driven replacement cycles for legacy outpatient systems. Japan's METI promotes healthcare data utilization guidelines that pressure smaller clinics toward certified SaaS platforms. Stakeholders must monitor how API standardization reshapes vendor switching costs and data monetization boundaries.
Market Dynamics
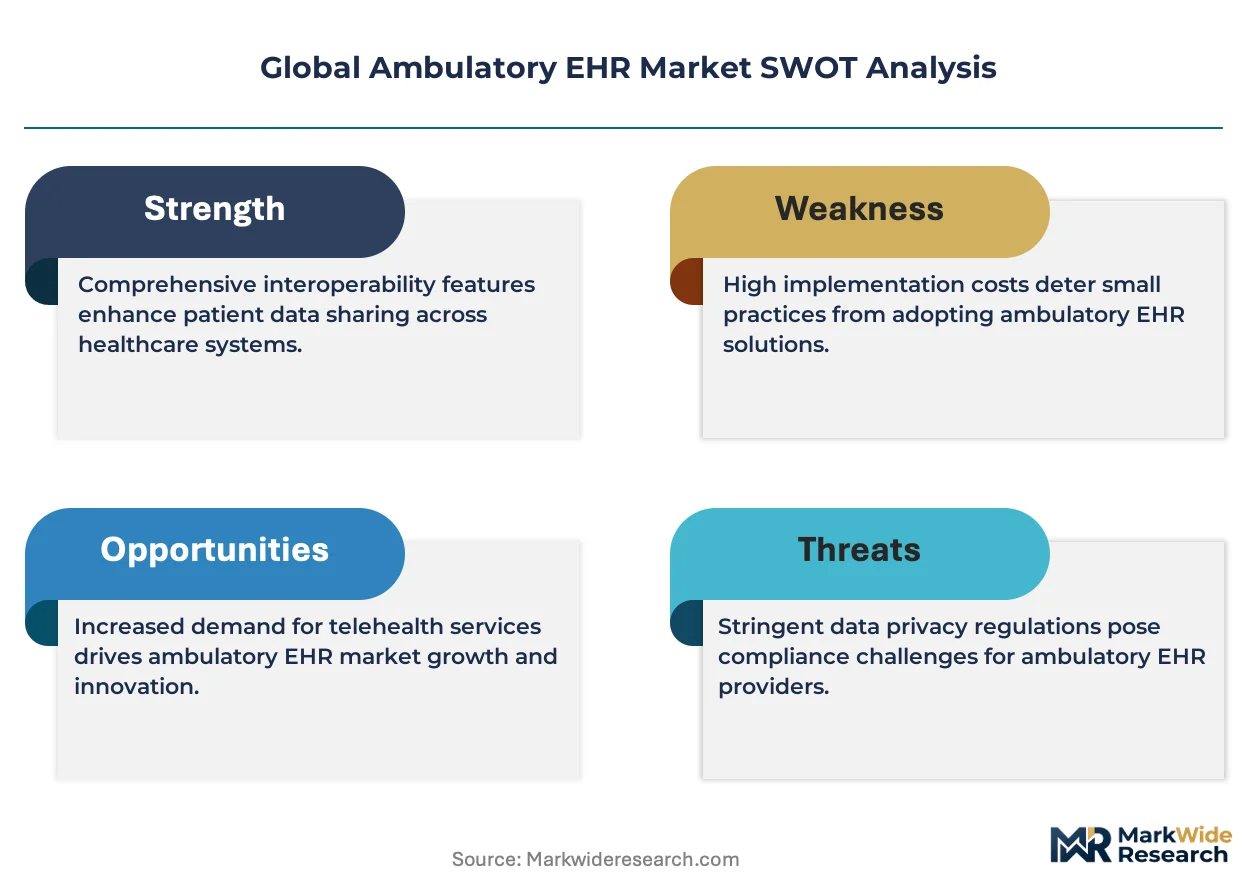
The US ONC Cures Act Final Rule is compressing vendor switching costs by mandating standardized patient-access APIs, forcing ambulatory EHR vendors to compete on interoperability depth rather than data lock-in.
Growth Catalysts
- API standardization mandates:The Cures Act Final Rule penalizes information blocking and requires FHIR-based data exchange, compelling outpatient clinics to upgrade from legacy siloed systems.
- Cloud migration tailwinds:Health systems are abandoning capital-intensive on-premise data centers in favor of subscription-based SaaS platforms with sub-100-millisecond query response times.
- Value-based contract proliferation:Specialty clinics require procedure-specific templates and automated quality reporting to meet Medicare accountable care organization metrics.
Market Restraints
- High switching costs:Data migration from legacy on-premise systems to cloud-native architectures demands 12-18 month implementation timelines and specialized HL7 integration expertise.
- Vendor concentration risk:The US ambulatory EHR market exhibits supply-side concentration among a handful of enterprise vendors, limiting price negotiation leverage for independent physician practices.
- Interoperability friction:Incomplete FHIR implementation across competing platforms creates data fragmentation that undermines care coordination goals.
Strategic Opportunities
- Ambulatory surgery center expansion:Same-day procedure volume growth in Germany and Japan is driving demand for perioperative documentation modules tailored to outpatient surgical workflows.
- Voice-enabled documentation:Natural language processing integration with ambient clinical intelligence is converging with EHR workflows to reduce physician administrative burden.
- Germany's gematik infrastructure:BfArM oversight of electronic patient record mandates creates compliance-driven replacement cycles for legacy outpatient systems in Europe's largest healthcare market.
Industry Challenges
- Clinical informatics talent scarcity:Health systems face acute shortages of professionals who can bridge clinical workflow design with FHIR API configuration and cloud security architecture.
- Legacy system integration complexity:Hybrid environments combining modern SaaS platforms with decades-old practice management software create data synchronization failures and audit trail gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambulatory EHR Market |
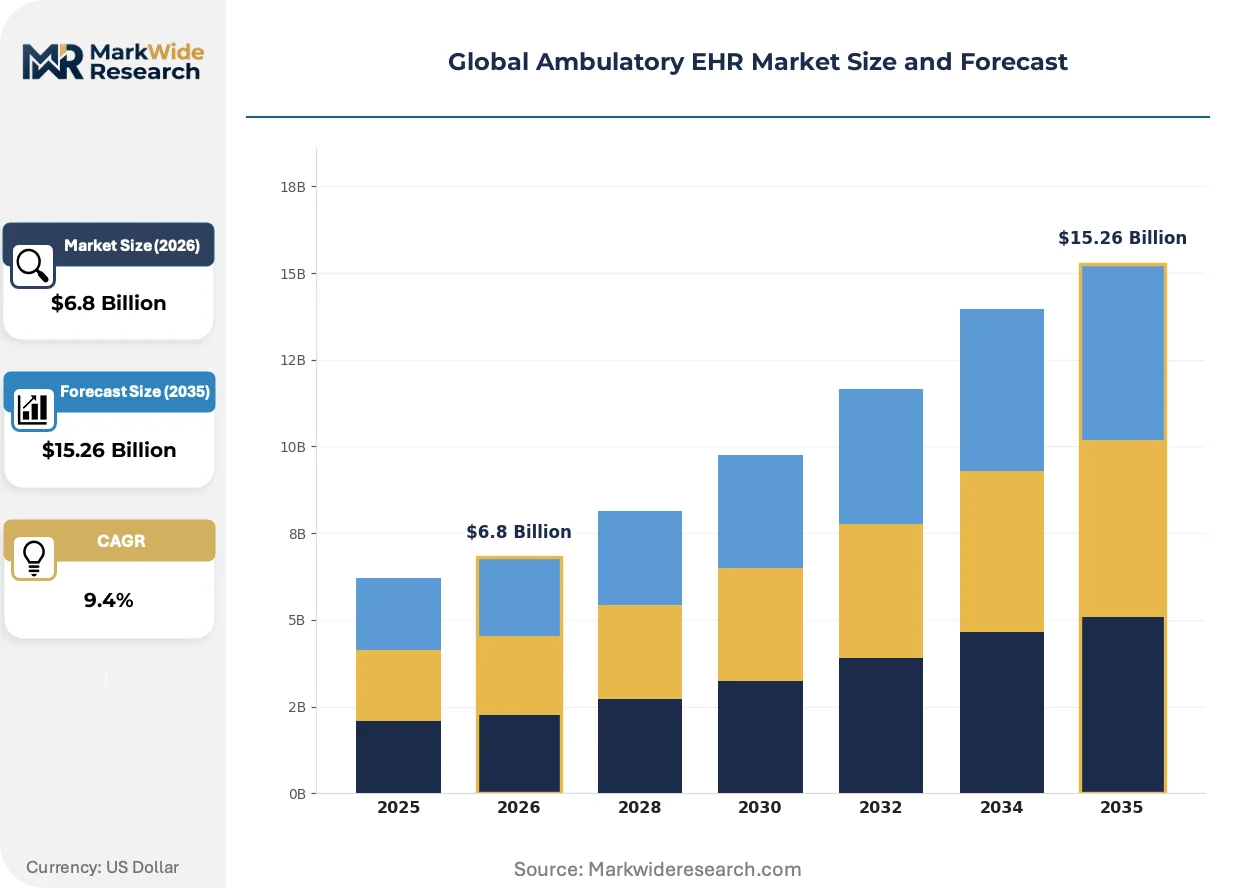
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Web-Based, Hybrid Application: Primary Care, Specialty Clinics, Urgent Care, Diagnostic Centers End User: Physician Practices, Ambulatory Surgery Centers, Community Health Centers, Outpatient Clinics Deployment Mode: Hosted, Self-Managed, Managed Service, SaaS |
| Companies Covered | Epic Systems Corporation, Oracle Cerner, eClinicalWorks, athenahealth, MEDITECH, Veradigm Inc, NextGen Healthcare, TruBridge, Greenway Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambulatory EHR Market Shifts & Advancements
Artificial intelligence and ambient clinical documentation are compressing the time between patient encounter and structured data capture, reshaping how outpatient practices justify EHR procurement decisions.
Natural language processing engines are converging with voice recognition platforms to generate structured clinical notes without keyboard interaction. Primary care groups and high-volume specialty clinics are piloting these tools to reduce documentation burden. This convergence is compressing the competitive advantage of traditional transcription services and forcing EHR vendors to bundle ambient intelligence as a core module.
Japan's METI healthcare data utilization guidelines are pressuring smaller clinics toward certified SaaS platforms with standardized data formats. The policy creates compliance-driven procurement cycles that favor vendors with pre-certified interoperability stacks. Rural and suburban clinics with limited IT staff are accelerating adoption of vendor-managed cloud deployments to satisfy METI audit requirements.
Subscription pricing models are displacing perpetual license structures across independent physician practices and multi-site groups. Vendors now unbundle implementation, training, and ongoing optimization as separate recurring revenue streams. This shift is most visible in the United States, where private equity-backed practice aggregators negotiate enterprise-wide EHR contracts with standardized monthly per-provider fees.
Global Ambulatory EHR Market Segmentation
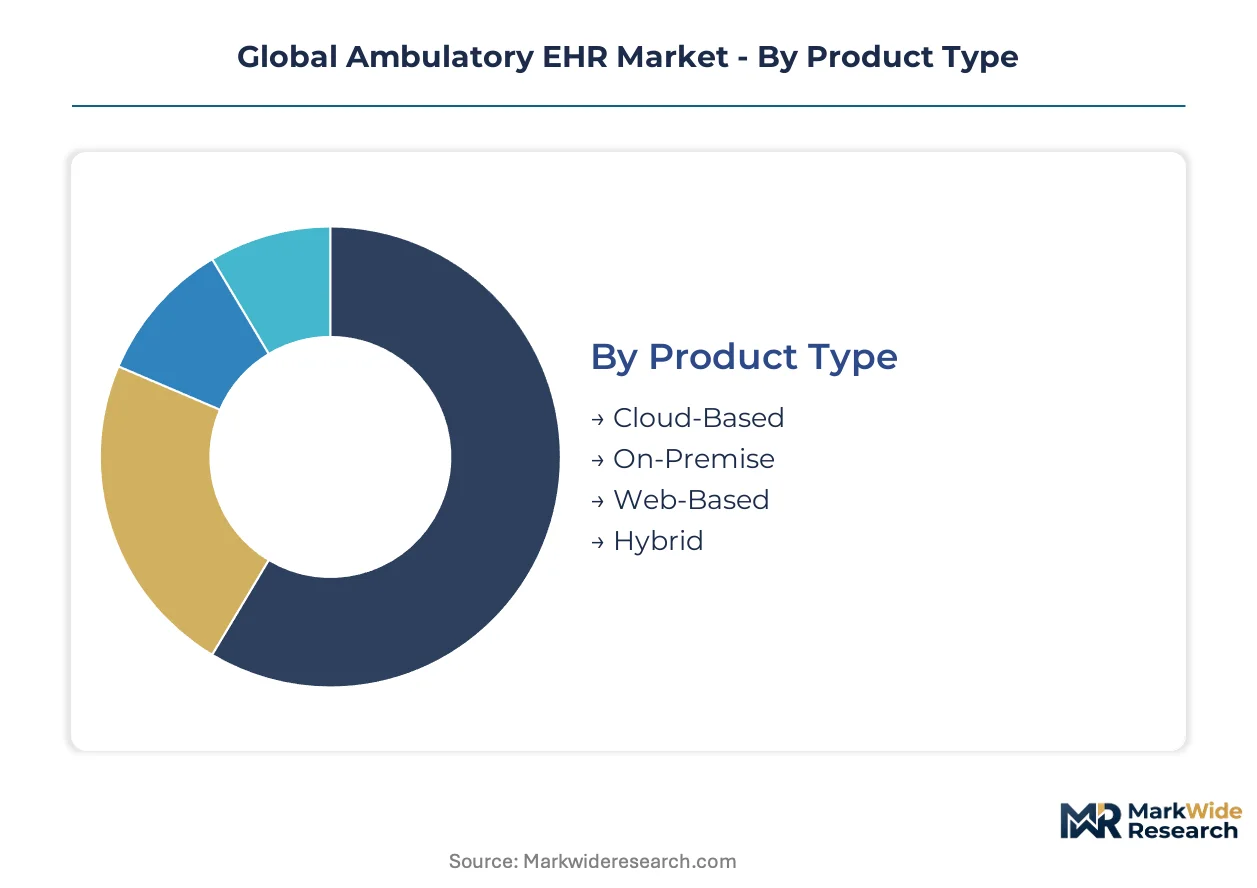
Ambulatory EHR procurement decisions pivot on interoperability mandates, cloud migration timelines, and specialty workflow requirements. Segment boundaries are hardening as vendors unbundle implementation services from core platform subscriptions.
Product Type:
Deployment architecture drives total cost of ownership calculations for outpatient clinics weighing capital expenditure against operational flexibility.
- Cloud-Based:Multi-tenant SaaS architectures with automatic FHIR API updates eliminate on-site server maintenance. US specialty clinics favor this model to satisfy ONC Cures Act compliance deadlines without capital outlay.
- On-Premise:Legacy client-server installations persist in German outpatient networks with stringent BfArM data residency requirements. Migration friction and 12-18 month implementation timelines constrain replacement velocity.
- Web-Based:Browser-accessible platforms with lighter infrastructure footprints serve Japan's rural clinics under METI certification pressure.
- Hybrid:Split configurations anchor core patient data on-premise while routing billing and scheduling through cloud gateways.
Volume sits with Cloud-Based systems; growth tilts toward Hybrid configurations bridging compliance and flexibility demands.
Application:
Clinical setting determines template complexity and regulatory reporting burden.
- Specialty Clinics:Procedure-specific documentation modules with embedded quality metrics support value-based contracting. Cardiology and orthopedics groups in the United States deploy these for Medicare ACO reporting.
- Primary Care:Comprehensive encounter capture with preventive care reminders anchors the largest installed base. German Hausarzt practices leverage these for gematik electronic patient record integration.
- Urgent Care:Rapid intake workflows with streamlined billing for episodic visits.
- Diagnostic Centers:Imaging and lab result integration with referring physician connectivity.
Primary Care captures the deepest installed base; Specialty Clinics are climbing the fastest on procedure-specific template demand.
End User:
Organization scale dictates vendor negotiation leverage and implementation approach.
- Physician Practices:Solo and small-group providers drive price-sensitive procurement. Japan's suburban clinics accelerate SaaS adoption to satisfy limited IT staffing.
- Ambulatory Surgery Centers:Perioperative documentation with anesthesia integration and same-day discharge protocols. German day-surgery volumes are expanding this segment.
- Community Health Centers:Federally qualified health centers require social determinants tracking and sliding-fee billing modules.
- Outpatient Clinics:Hospital-affiliated satellite facilities needing seamless inpatient-outpatient data continuity.
Physician Practices dominate transaction volume; Ambulatory Surgery Centers are gaining share fastest on same-day procedure growth.
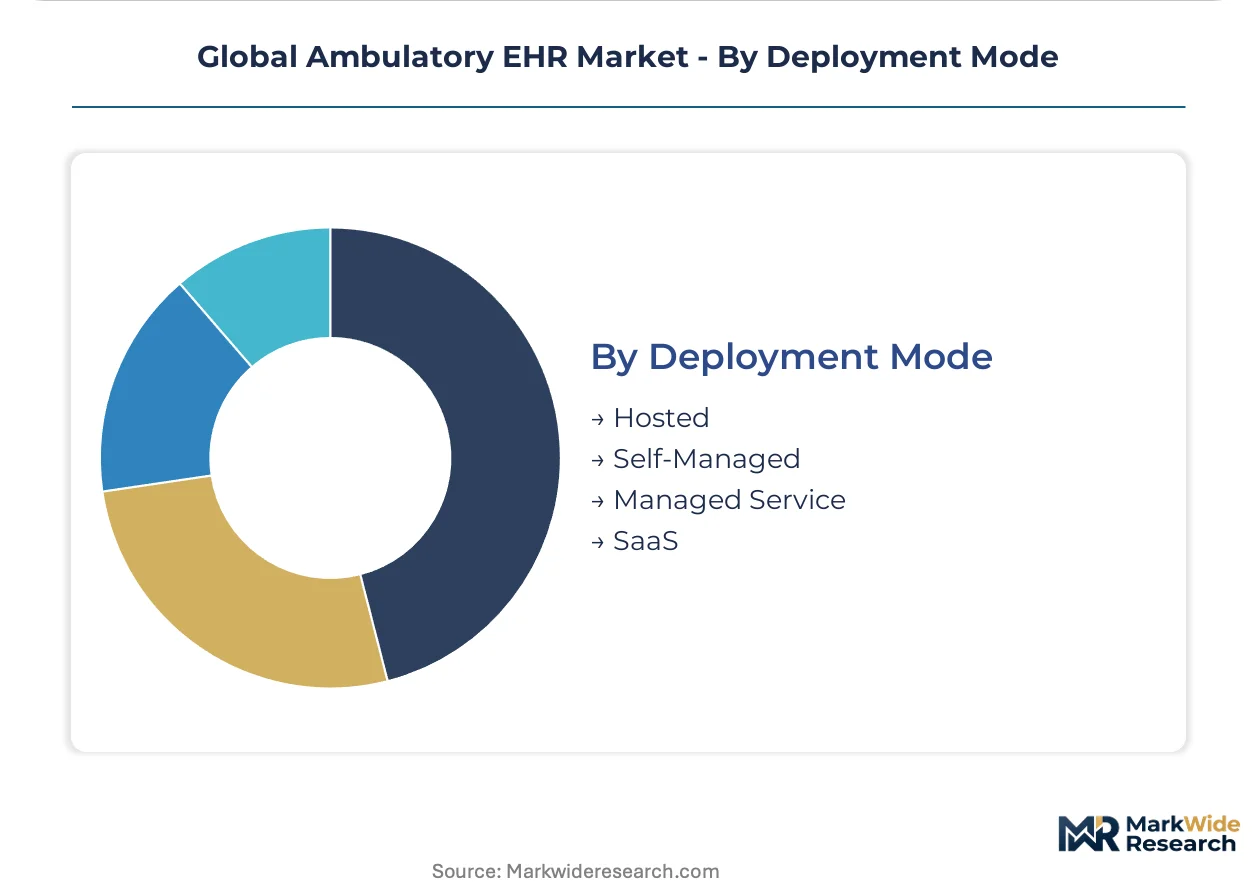
Deployment Mode:
Operational control preferences segment buyers across IT maturity spectrums.
- SaaS:Fully vendor-managed infrastructure with subscription pricing. US private equity-backed practice aggregators negotiate enterprise-wide per-provider fees.
- Managed Service:Outsourced IT operations with dedicated support tiers.
- Hosted:Single-tenant cloud with client-dedicated resources for data residency requirements.
- Self-Managed:Client-controlled infrastructure with vendor software licensing only.
SaaS claims the steepest expansion trajectory as health systems abandon capital-intensive data center ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors Epic Systems' academic medical center integration, driving affiliated outpatient network expansion across the United States. Specialty clinics in this corridor deploy cloud-native architectures to satisfy interoperability mandates.
United States
Private equity-backed practice aggregators negotiate enterprise-wide SaaS contracts with standardized per-provider fees. The ONC Cures Act Final Rule penalizes information blocking and mandates FHIR-based patient-access APIs. Texas Medical Center outpatient facilities in Houston accelerate cloud migration to meet compliance deadlines.
Germany
Hausarzt practices in Baden-Württemberg leverage procedure-specific templates for Medicare accountable care organization reporting. BfArM oversight of gematik electronic patient record infrastructure creates compliance-driven replacement cycles. Munich's outpatient networks abandon legacy client-server installations for certified cloud platforms.
Japan
Rural and suburban clinics with limited IT staff accelerate vendor-managed cloud deployments. METI healthcare data utilization guidelines pressure smaller practices toward certified SaaS platforms with standardized data formats. Osaka's specialty surgery centers pilot voice-enabled documentation tools.
United Kingdom
Hospital-affiliated satellite facilities in London's NHS trusts demand seamless inpatient-outpatient data continuity. NHS Digital interoperability standards compress vendor switching costs for legacy system replacements. Cambridge Health Partners outpatient networks integrate academic center EHR architectures.
India
Multi-site physician practice groups in Bengaluru adopt subscription-based interoperability layers for cost predictability. CDSCO guidance on digital health records pressures urban clinics toward FHIR-compliant systems. Hyderabad's health tech corridor hosts implementation specialists bridging cloud-native platforms with legacy practice management software.
Global Ambulatory EHR Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ambulatory EHR landscape, with cloud infrastructure investments separating scaled platform operators from modular specialists. The market exhibits supply-side concentration among enterprise vendors serving multi-site health systems, while independent physician practices retain price-sensitive procurement leverage. Three archetypes dominate: academic medical center-anchored integrators, enterprise-scale deployment specialists, and aggressive price competitors for small-group primary care. Consolidation through strategic acquisitions and API standardization compliance investments constitute the primary competitive vectors reshaping vendor positioning.
Within the academic medical center integration tier, Epic Systems Corporation exemplifies deep institutional embedding that extends into affiliated outpatient networks. Oracle Cerner occupies a position among enterprise-scale deployment specialists anchoring multi-site physician practice infrastructure. eClinicalWorks represents the price-competitive archetype targeting independent primary care groups while sustaining investment in voice-enabled documentation capabilities.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Cerner |
| eClinicalWorks |
| athenahealth |
| MEDITECH |
| Veradigm Inc |
| NextGen Healthcare |
| TruBridge |
| Greenway Health |
| Others |
Supply & Pricing Matrix
US private equity-backed practice aggregator procurement consolidation is compressing vendor margins and forcing cloud-native platform investments that reshape supplier economics across the ambulatory EHR landscape.
Pricing Analysis
Margin tightening in the independent physician practice tier reflects aggressive per-provider fee negotiations by consolidated buyer groups. Subscription-based SaaS pricing stratifies across enterprise, mid-market, and solo-practice tiers, with differentiation anchored in FHIR API certification depth and voice-enabled module bundling. Pricing pressure accelerates as Oracle Cerner and Epic Systems leverage academic medical center anchoring to cross-subsidize outpatient network expansion. Small-group primary care practices exhibit highest price sensitivity, while multi-site specialty surgery centers accept premium positioning for perioperative workflow specificity.
Supply Chain Analysis
Freight costs for on-premise server hardware and data center equipment factor marginally into total cost of ownership calculations as cloud migration accelerates. Software development labor concentrates in the United States, India, and Ireland, with implementation services drawing from Hyderabad's health tech corridor and Bengaluru's enterprise SaaS specialist pools. Supply chain risk rests on single-source vulnerability for specialized HL7 FHIR integration talent. Distribution runs through direct vendor sales organizations for enterprise accounts and value-added reseller networks serving independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where the ONC Cures Act Final Rule erects regulatory moats favoring vendors with pre-certified interoperability stacks and penalizing information-blocking legacy platforms.
For Market Incumbents: Hedge against API commoditization by deepening ambient clinical intelligence R&D and acquiring voice-enabled documentation specialists. Oracle Cerner and Epic Systems should reinforce data center migration service capabilities to capture 12-18 month implementation timelines that lock in switching costs. Vertical integration into cloud infrastructure ownership preserves margin control as AWS and Azure hosting fees escalate.
For New Entrants and Emerging Players: Direct-to-specialty-clinic digital sales channels bypass entrenched hospital-affiliated procurement gatekeepers. White-space concentration sits with German Hausarzt practices facing BfArM-mandated gematik compliance deadlines and Japan's rural clinics under METI certification pressure. Target ambulatory surgery center perioperative modules with procedure-specific templates as the most penetrable application segment.
For Investors and Strategic Acquirers: The window for entry favors FHIR-certified SaaS platforms with established API marketplaces over legacy on-premise install bases. Long-term viability hinges on voice-AI integration depth and value-based contract reporting automation. Monitor BfArM enforcement velocity in Germany and METI audit expansion in Japan as inflection indicators for compliance-driven replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Marketplace Launch | Epic Systems leverages academic medical center networks to establish interoperability data exchange revenue streams. |
| Voice-Enabled Documentation Acquisition | eClinicalWorks sustains R&D investment in ambient clinical intelligence to reduce physician administrative burden. |
| Cloud Infrastructure Partnership | athenahealth secures sub-100-millisecond query response times through multi-tenant SaaS architecture scaling. |
| German gematik Compliance Certification | NextGen Healthcare captures BfArM-mandated replacement cycles in Europe's largest outpatient EHR market. |
| Japan METI SaaS Pre-Certification | Veradigm positions vendor-managed cloud deployments for rural clinic audit requirement satisfaction. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this ambulatory EHR market analysis. Primary interviews with health system CIOs, ambulatory surgery center operations directors, HL7 integration specialists, and GPO contracts managers combined with bottom-up and top-down triangulation. Secondary validation drew from ONC Cures Act implementation guidance, BfArM gematik infrastructure documentation, METI healthcare data utilization guidelines, hospital procurement databases, and CMS Medicare ACO reporting specifications.
Data-stream reconciliation across deployment architecture, application setting, and end-user organization scale produced volume and value estimates throughout the projection horizon. Segmentation dimensions modeled encompassed cloud-native versus on-premise infrastructure, specialty clinic versus primary care workflows, and physician practice versus ambulatory surgery center procurement patterns. CAGRs derived from historical replacement cycle analysis, regulatory deadline clustering, and voice-AI adoption curve benchmarking against documentation burden reduction studies.
The model holds under sustained ONC, BfArM, and METI enforcement continuity; deviation in interoperability mandate delay or cloud security incident frequency would shift vendor switching cost assumptions and procurement timeline acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare BI Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Global Healthcare Integration Market
Health Informatics
North America Laboratory Information System Market
Health Informatics
Health Information Exchange (HIE) Market
Health Informatics
Global Laboratory Information Management System (LIMS) Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Healthcare Natural Language Processing Market
Health Informatics
EHR EMR Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Middle East and Africa Healthcare Archiving and Ediscovery Market