
 Anesthesia Information Management Systems Market | 2026-2036
Anesthesia Information Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Information Management Systems Market Analysis
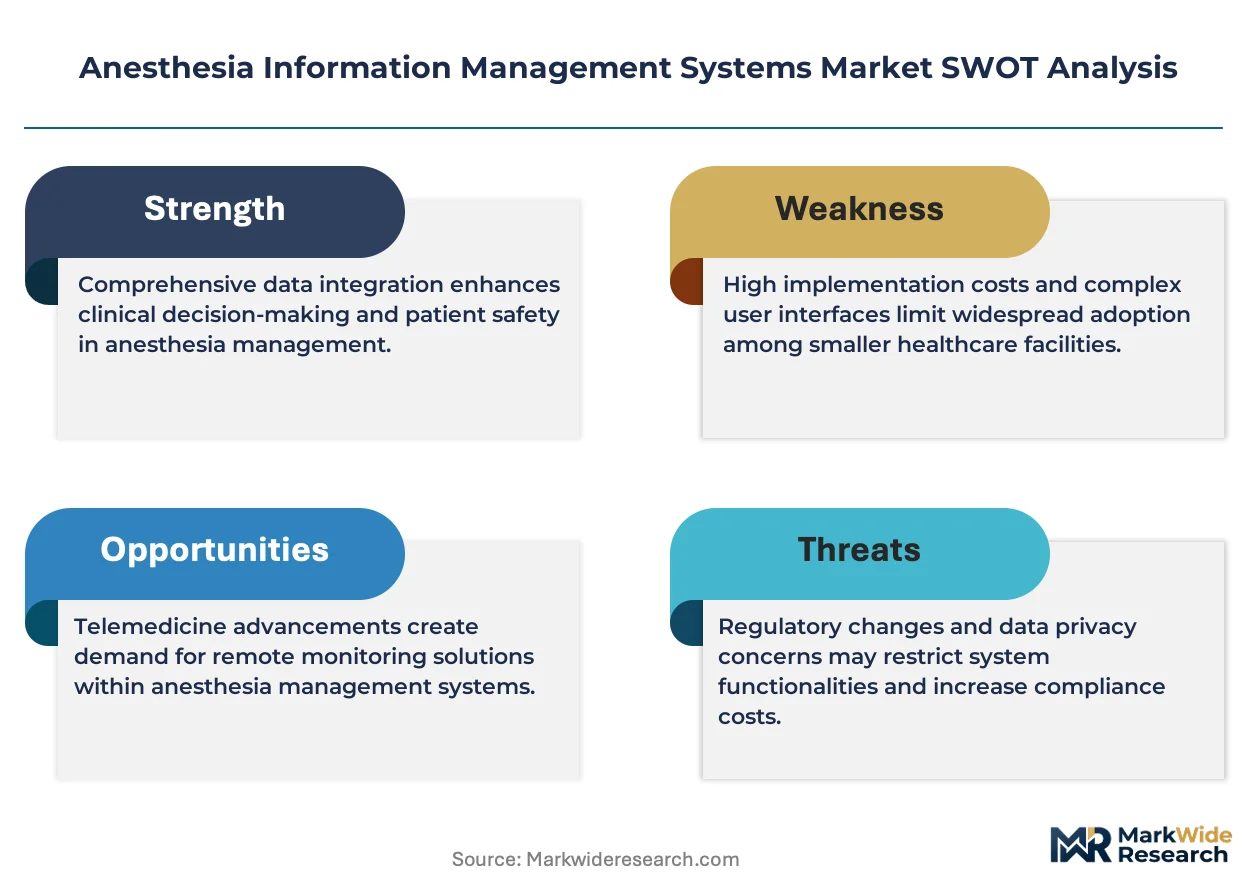
Multi-source procurement among health systems is consolidating toward preferred-vendor agreements with full-stack anesthesia platform providers. GE Healthcare leverages its embedded presence in perioperative suites to sustain hardware-software bundling advantages. Epic Systems Corporation anchors hospital IT ecosystems through native EHR integration that reduces interface complexity. Drägerwerk AG & Co. KGaA competes on device connectivity depth, linking ventilator and monitor outputs directly into anesthesia record workflows.
An anesthesia information management system (AIMS) is a specialized clinical software platform that automatically captures, documents, and archives physiological data from anesthesia delivery machines, patient monitors, and infusion pumps during surgical procedures, typically interfacing through HL7 or proprietary protocols to ensure real-time data integrity. Its primary purpose is to replace manual anesthesia record-keeping with automated documentation that improves accuracy, supports billing compliance, and generates structured data for quality improvement initiatives. Cloud-Based deployments are capturing growing share among mid-sized hospitals seeking reduced capital expenditure and faster implementation cycles, while Integrated Systems dominate enterprise accounts where anesthesia workflows must synchronize with surgical scheduling, supply chain, and billing modules across the health system. Standalone Solutions retain relevance in ambulatory surgical centers with limited IT resources, though these facilities increasingly face pressure to demonstrate outcomes data for payer contracting.
FDA oversight of software-as-a-medical-device functionality shapes product development timelines for vendors incorporating clinical decision support, while HIPAA security rule enforcement drives encryption and access-control investments. The ONC Cures Act Final Rule mandates interoperability standards that AIMS vendors must implement to maintain hospital customer eligibility for federal incentive programs. Stakeholders should monitor how CMS quality payment program measures evolve to incorporate anesthesia-specific outcomes metrics, as this will determine which documentation and analytics capabilities become table stakes for market participation.
Market Dynamics
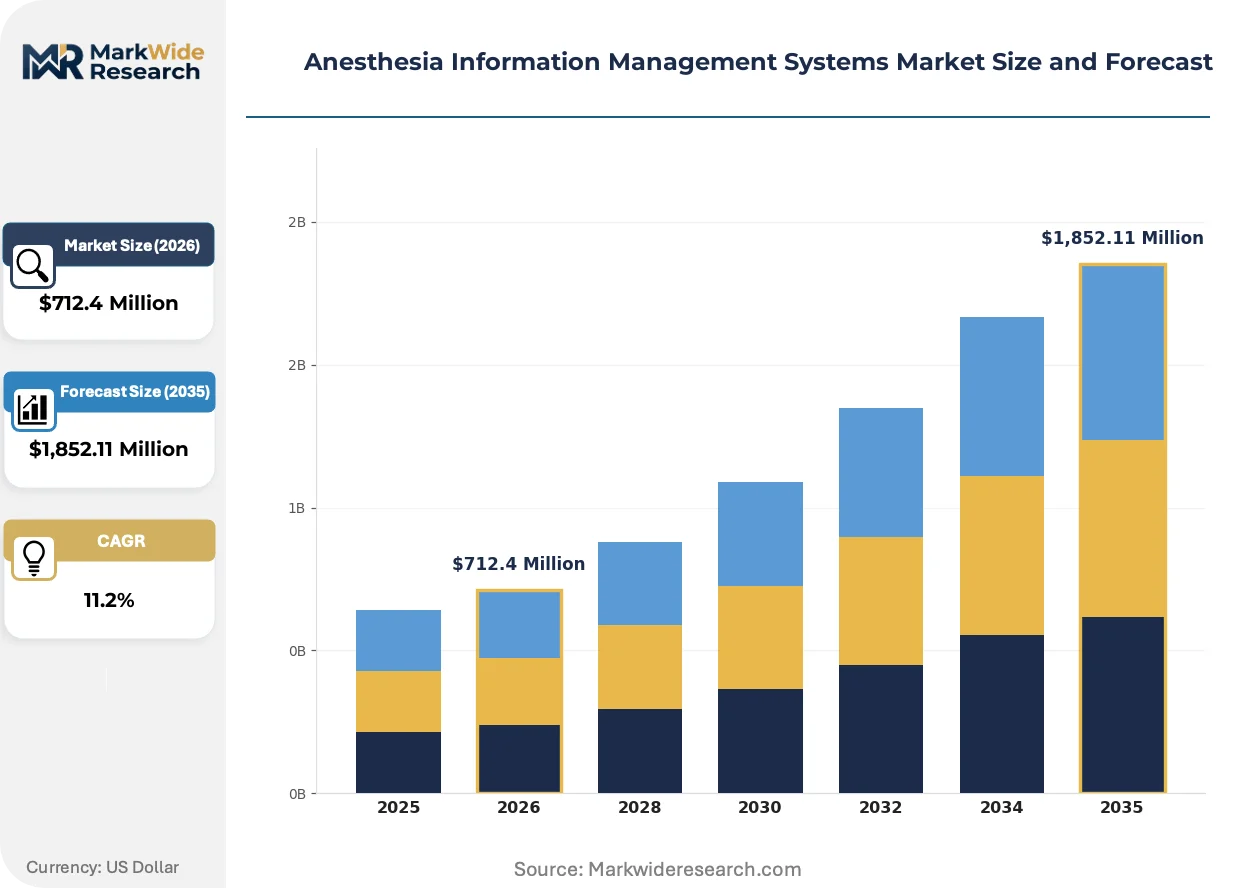
Consolidation of health system procurement is compressing vendor margins while elevating full-stack platform requirements, as hospitals abandon multi-source anesthesia IT contracts in favor of integrated perioperative suites that bundle documentation, billing, and quality analytics.
Growth Catalysts
- FDA 21 CFR Part 11 mandates:Electronic signature and audit-trail requirements for clinical software are compelling anesthesia departments to replace paper-based record systems with validated digital platforms.
- Cloud infrastructure maturation:Mid-sized hospitals are migrating AIMS deployments to hosted environments, eliminating on-premise server maintenance and accelerating implementation timelines.
- CMS quality payment programs:Anesthesia-specific outcome metrics tied to reimbursement are driving investment in automated documentation systems that capture structured data for reporting compliance.
Market Restraints
- HL7 interface complexity:Proprietary protocols from legacy patient monitors and ventilators require expensive custom integration engineering, inflating total cost of ownership for multi-vendor environments.
- Cybersecurity compliance burden:HIPAA security rule enforcement demands continuous encryption upgrades and access-control investments that strain IT budgets at smaller surgical facilities.
- Specialized clinical informaticist scarcity:Health systems face recruitment gaps for personnel capable of configuring anesthesia workflow rules, delaying system optimization and user adoption.
Strategic Opportunities
- Ambulatory surgical center penetration:Freestanding ASCs with limited IT infrastructure represent an underpenetrated segment for cloud-native AIMS offerings with subscription pricing.
- AI-enabled clinical decision support:Machine learning algorithms for anesthesia dosing recommendations are converging with automated documentation platforms, creating differentiated premium tiers.
- ONC Cures Act interoperability:Federal mandates for patient data exchange are opening integration revenue streams for vendors that certify Fast Healthcare Interoperability Resources connectivity.
Industry Challenges
- EHR synchronization complexity:Bidirectional data flows between anesthesia record systems and enterprise electronic health records require continuous mapping maintenance as EHR vendors release updates.
- FDA SaMD classification uncertainty:Clinical decision support modules risk reclassification as software-as-a-medical-device, triggering extended validation timelines and submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Information Management Systems Market |
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,852.11 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Software-as-a-Service End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Functionality: Patient Monitoring, Data Management, Workflow Optimization, Analytics Deployment: Standalone Solutions, Integrated Systems, Mobile Applications, Custom Solutions |
| Companies Covered | Drägerwerk AG & Co. KGaA, GE Healthcare, Koninklijke Philips N.V., Surgical Information Systems, Cerner Corporation, Epic Systems Corporation, Talis Clinical, Provation Software, iMDsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Information Management Systems Market Emerging Trajectories
Automation of physiological data capture is eliminating manual transcription errors while generating real-time analytics streams that feed perioperative quality improvement initiatives across integrated delivery networks.
Natural language processing for anesthesia documentation is absorbing unstructured clinician notes into codified data fields, enabling automated billing code generation and quality metric extraction. Academic medical centers with complex case mixes are piloting these tools to reduce documentation burden during high-acuity procedures. The technology is absorbing transcription service budgets and redirecting anesthesia provider time toward patient care.
The EU Medical Device Regulation is extending conformity assessment requirements to clinical software with diagnostic or therapeutic functions, forcing AIMS vendors with European hospital customers to engage notified bodies for CE marking. Implementation timelines have stretched by twelve to eighteen months for modules incorporating patient risk stratification algorithms. Vendors are responding by segregating European product builds from US deployments to isolate regulatory scope.
Health system purchasing committees are consolidating anesthesia IT decisions under chief information officer oversight, displacing department-level autonomy that previously favored best-of-breed standalone solutions. Enterprise EHR-native modules are capturing preference in these centralized evaluations due to reduced interface risk and unified support structures. This concentration is most visible in United States multi-hospital systems pursuing digital transformation standardization.
Anesthesia Information Management Systems Market Segmentation
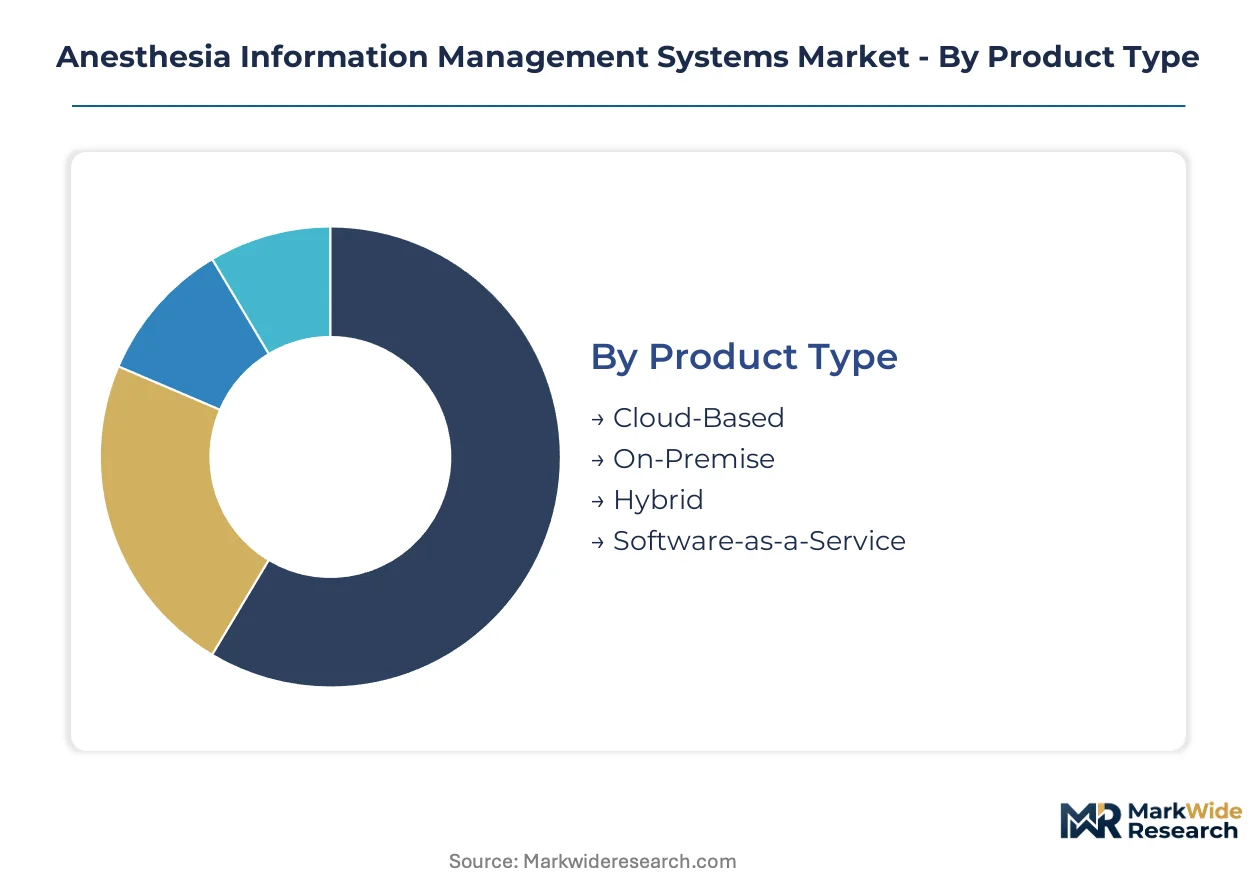
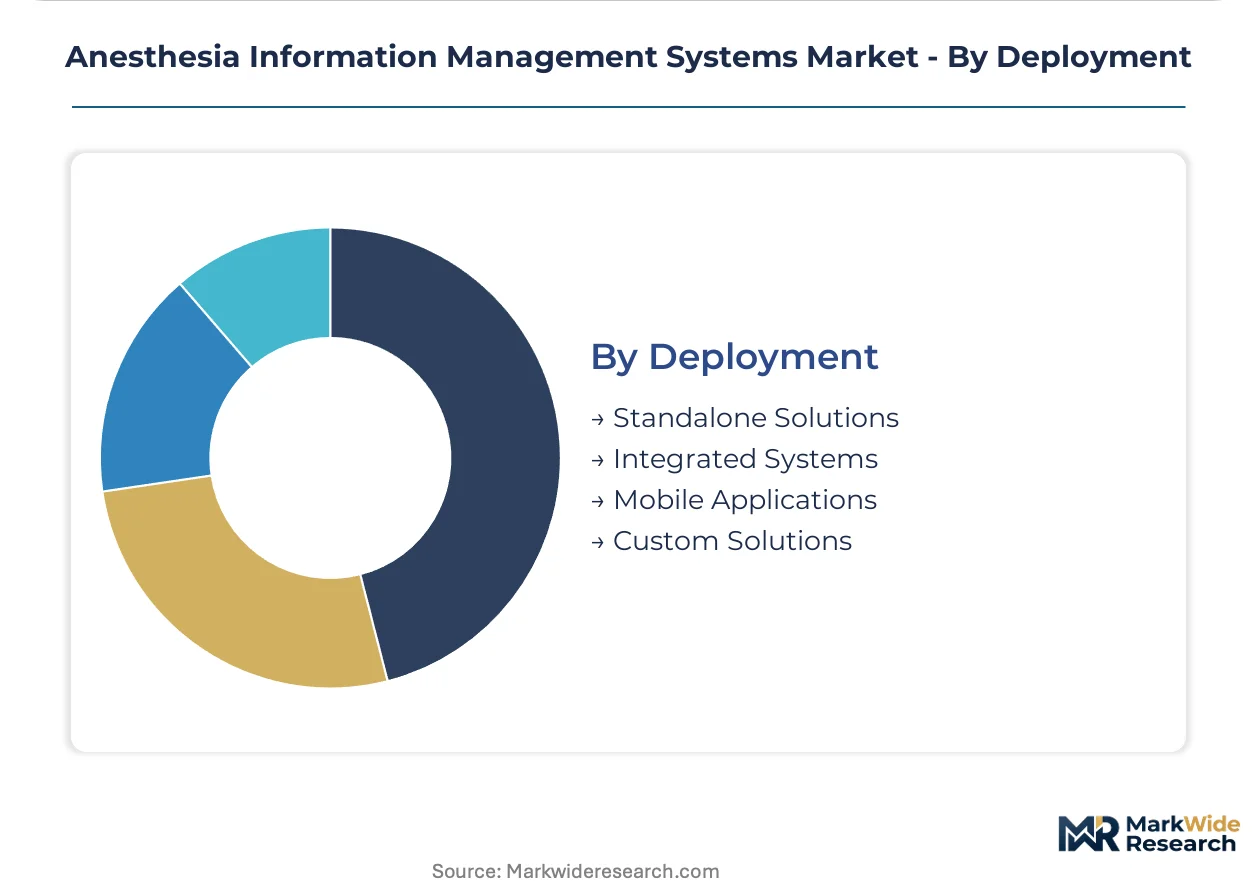
Anesthesia Information Management Systems segment across deployment architecture, clinical setting, functional capability, and implementation model. Each dimension reflects distinct capital expenditure profiles, regulatory compliance burdens, and integration complexity that shape vendor go-to-market strategies.
Product Type:
Standardization dominates cloud-native offerings while hybrid architectures demand extensive customization to bridge legacy infrastructure with modern platforms.
- Cloud-Based:Hosted environments eliminate on-premise server maintenance and accelerate implementation cycles. Mid-sized hospitals in the United States favor this model for reduced capital expenditure and automatic security patching under HIPAA requirements.
- On-Premise:Local server installations retain preference among academic medical centers with dedicated IT infrastructure and complex workflow rule configurations. These deployments satisfy institutional data sovereignty policies but require continuous hardware refresh cycles.
- Hybrid:Mixed architectures balance sensitive patient data on local servers with analytics workloads in hosted environments.
- Software-as-a-Service:Subscription pricing models lower entry barriers for ambulatory surgical centers with constrained IT budgets.
Leading the category by volume: On-Premise. Expanding most quickly: Cloud-Based.
End User:
Procurement authority concentrates at different organizational levels across these settings, from centralized hospital IT committees to clinic-level decision makers.
- Hospitals:Enterprise health systems drive the majority of revenue through perioperative suite standardization initiatives. FDA 21 CFR Part 11 compliance mandates and CMS quality payment program requirements compel these institutions toward validated digital documentation platforms.
- Ambulatory Surgical Centers:Freestanding facilities with limited technical staff increasingly adopt cloud-native solutions with subscription economics. Payer contracting pressures for outcomes demonstration are accelerating AIMS penetration in this historically underpenetrated segment.
- Clinics:Smaller outpatient settings prioritize cost containment over advanced functionality.
- Research Institutions:Academic centers leverage anesthesia data for clinical trial recruitment and perioperative outcomes studies.
Dominant by procurement volume: Hospitals. Steepest expansion trajectory: Ambulatory Surgical Centers.
Functionality:
Margin profiles diverge sharply between commodity data capture modules and premium analytics tiers with predictive capabilities.
- Patient Monitoring:Real-time physiological data ingestion from anesthesia machines and patient monitors forms the core platform capability. HL7 interface engineering and proprietary protocol conversion dominate implementation complexity in multi-vendor environments.
- Data Management:Structured archiving with audit-trail integrity supports billing compliance and medicolegal documentation requirements. HIPAA security rule enforcement drives continuous encryption and access-control investment.
- Workflow Optimization:Automated scheduling and resource allocation modules reduce anesthesia provider idle time.
- Analytics:Quality improvement dashboards and outcome benchmarking command premium pricing.
Highest revenue concentration: Patient Monitoring. Gaining share fastest: Analytics.
Deployment:
Integration depth determines total cost of ownership, with standalone solutions minimizing interface engineering but limiting data utility.
- Standalone Solutions:Self-contained documentation platforms serve ambulatory surgical centers and small clinics with limited IT resources. These deployments avoid EHR synchronization complexity but require manual data transfer for enterprise reporting.
- Integrated Systems:Native connectivity with enterprise electronic health records dominates hospital procurement preferences. ONC Cures Act interoperability mandates and unified support structures drive consolidation toward these configurations.
- Mobile Applications:Tablet-based documentation interfaces enable anesthesia provider mobility within surgical suites.
- Custom Solutions:Bespoke workflow configurations address unique institutional requirements.
Leading by enterprise adoption: Integrated Systems. Climbing the fastest: Mobile Applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley software engineering talent anchors United States dominance in anesthesia information management systems, while European medical device manufacturing clusters and Asian healthcare digitization programs shape complementary demand centers.
United States
Epic Systems Corporation and Cerner Corporation anchor hospital IT ecosystems through native EHR integration, reducing interface complexity for anesthesia workflows. FDA 21 CFR Part 11 mandates compel health systems toward validated digital documentation platforms with electronic signature capabilities. The Greater Boston medical technology corridor hosts concentrated perioperative informatics research, accelerating AI-enabled clinical decision support pilots.
Germany
Drägerwerk AG & Co. KGaA leverages embedded device manufacturing heritage to link ventilator and monitor outputs directly into anesthesia record workflows. EU Medical Device Regulation extends conformity assessment requirements to clinical software with diagnostic functions, stretching implementation timelines for risk stratification modules. The Baden-Württemberg industrial cluster sustains precision engineering capabilities for anesthesia delivery machine integration.
China
NMPA regulatory pathways for software-as-a-medical-device are converging with hospital digital transformation budgets under the Healthy China 2030 initiative. National Health Commission interoperability standards mandate HL7 FHIR connectivity for tertiary hospital anesthesia departments. The Yangtze River Delta healthcare technology corridor concentrates domestic AIMS development and pilot deployments.
Japan
METI funding for healthcare AI integration supports anesthesia documentation automation in university hospitals. PMDA software medical device classification guidance shapes vendor product development timelines for clinical decision support modules. The Kansai region's medical device manufacturing base sustains perioperative equipment integration engineering.
United Kingdom
NHS England digital transformation programs prioritize perioperative workflow standardization across integrated care systems. MHRA guidance on software medical devices influences procurement specifications for anesthesia information systems. The London-Southeast health technology cluster concentrates health informatics vendor development and hospital pilot partnerships.
Anesthesia Information Management Systems Market Vendor Landscape
Strategic partnerships dominate the current landscape as health system procurement consolidation compresses vendor margins and elevates full-stack platform requirements. The vendor base clusters around three archetypes: embedded medical device manufacturers with hardware-software bundling advantages, enterprise EHR-native platforms with reduced interface complexity, and specialized clinical documentation vendors with anesthesia-specific workflow depth. M&A activity and technology licensing agreements represent the primary competitive moves, with smaller vendors seeking EHR connectivity certification and larger platforms acquiring niche workflow capabilities.
Within the embedded device manufacturer tier, Drägerwerk AG & Co. KGaA exemplifies hardware-software integration depth, while GE Healthcare occupies a position spanning imaging and perioperative suites. Epic Systems Corporation anchors the EHR-native archetype, representing unified support structures that health system CIOs favor in centralized procurement evaluations. These three entities collectively illustrate how competitive positioning stratifies across bundling advantages, ecosystem integration, and specialized workflow expertise.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Surgical Information Systems |
| Cerner Corporation |
| Epic Systems Corporation |
| Talis Clinical |
| Provation Software |
| iMDsoft |
| Others |
Supply Flow & Price Mechanics
Health system CIO consolidation of anesthesia IT procurement authority has shifted vendor pricing power toward enterprise-wide platform licensing with multi-year service bundling. Subscription SaaS tiers now dominate mid-sized hospital contracts, while academic medical centers negotiate perpetual licenses with customization premiums.
Pricing Analysis
Warranty and implementation service bundling separates premium vendor tiers from unbundled economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR Part 11 validation depth and HL7 interface engineering complexity. Cost compression in the economy tier intensifies because cloud-native entrants undercut legacy on-premise maintenance contracts. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Reverse logistics for anesthesia monitor refurbishment and ventilator remanufacturing flows through certified third-party service depots in the United States, Germany, and Japan. Software development draws from Indian engineering centers, Taiwanese semiconductor fabrication for embedded devices, and German precision manufacturing for sensor components. Single-source vulnerability concentrates in proprietary HL7 interface chipsets from select Asian foundries. Distribution runs through direct hospital contracting for enterprise accounts and regional medical equipment distributors for ASC penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anesthesia information management systems occupy a technology-transition phase where cloud-native platforms displace legacy on-premise documentation infrastructure. Machine learning-enabled clinical decision support modules are supplanting rule-based alerting systems in premium tier deployments.
For Market Incumbents: Cement ecosystem lock-in through deeper EHR-native integration and exclusive device connectivity partnerships with ventilator manufacturers. Cloud-native entrants with subscription pricing threaten hardware-software bundling margins. Backward integration into HL7 interface chipset design reduces third-party dependency risks.
For New Entrants and Emerging Players: Freestanding ambulatory surgical centers represent the most penetrable buyer archetype with unmet demand for lightweight, subscription-priced documentation platforms. Cloud-native deployment with automatic HIPAA security patching addresses IT resource scarcity. Direct digital marketing to ASC administrator associations bypasses entrenched hospital GPO channels.
For Investors and Strategic Acquirers: The window for entry favors specialized clinical workflow vendors with anesthesia-specific informatics expertise over generalist EHR platforms. Long-term viability centers on AI-enabled outcome prediction capabilities that justify premium pricing. Monitor FDA SaMD classification guidance revisions for clinical decision support modules as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native EHR connectivity reduces HL7 interface engineering costs for Epic and Cerner hospital ecosystems. |
| Acquisition of Specialist Firm | Anesthesia-specific workflow vendors bring proprietary clinical rule libraries that accelerate AI training data accumulation. |
| FDA Submission | Software-as-a-medical-device clearance for dosing recommendation modules unlocks premium tier pricing in US hospitals. |
| Hospital System Partnership | Preferred-vendor agreements with integrated delivery networks secure multi-year recurring revenue visibility. |
| CE Marking Pathway | EU MDR conformity assessment for risk stratification algorithms enables European academic medical center expansion. |
Methodological Framework
Multi-period observation of anesthesia documentation automation rates and cloud deployment adoption anchored the trend analysis, supplemented by interviews with perioperative informaticists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, CMS quality payment program measure specifications, hospital procurement database extracts, and ONC Cures Act interoperability certification records. Bottom-up facility-level deployment estimates triangulated against top-down vendor revenue segmentation.
Segment-weighting across deployment architecture, clinical setting, functional capability, and implementation model shaped the analytical framework. CAGRs derived from logistic diffusion curves fitted to cloud migration patterns and EHR integration penetration rates across the modeling period. Forecast inputs incorporated health system consolidation timelines, FDA SaMD classification uncertainty resolution scenarios, and ASC payer contracting pressure intensification.
Revisions become necessary when FDA software medical device reclassification guidance materializes or when CMS anesthesia-specific quality measures expand reporting requirements. Forecasts reflect assumptions about interoperability mandate compliance deadlines and cloud infrastructure reliability improvements. Practitioners should monitor ONC certification timeline shifts and health system bankruptcy filings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Global Cardiovascular Information System Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Master Patient Index Software Market