
 Canned Pork Market | 2026-2036
Canned Pork Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Pork Market Insights
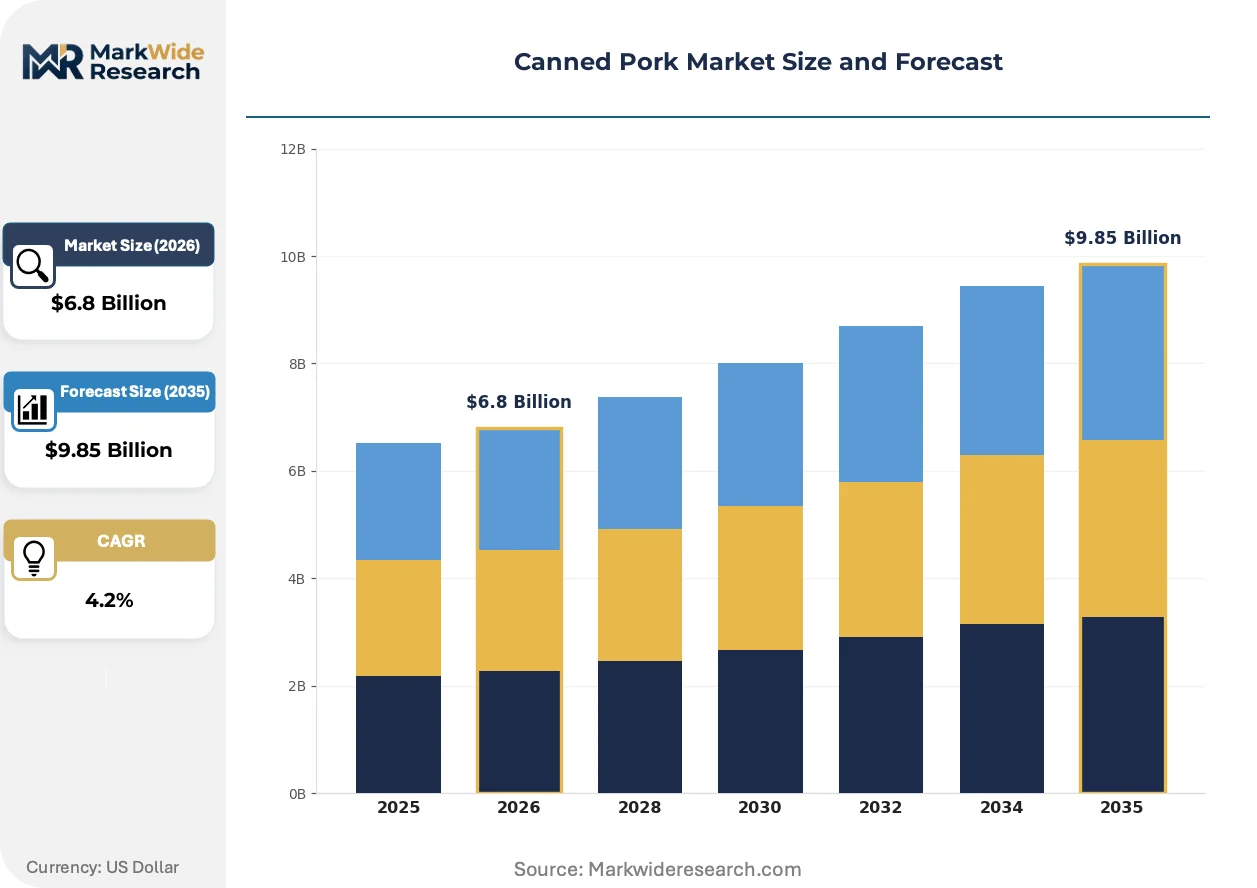
USDA-FSIS Safe Food for Canadians Regulations (SFCR) alignment and HACCP certification is bifurcating supplier eligibility across North American retail channels. Hormel Foods Corporation leverages vertical integration from farm to canning to sustain margin control in premium chunked segments. Tyson Foods anchors its position through R&D intensity in reduced-sodium curing formulations. Smithfield Foods competes on geographic dominance in Midwest processing corridors, while JBS differentiates via Brazilian captive supply of raw material.
Canned pork comprises thermally stabilized swine meat preserved in hermetically sealed containers through retort processing at 121°C, achieving commercial sterility and shelf stability exceeding 24 months without refrigeration. The primary commercial purpose centers on providing protein-dense, ambient-storage meal components for retail households, institutional foodservice, and emergency relief operations. Chunked formats dominate volume through food manufacturing of ready meals and soups, while pouch packaging represents the fastest-expanding structural category driven by reduced shipping weight and microwave-convenience positioning. Supermarket channels remain the mature margin pool, though online distribution is capturing incremental growth in urban household replenishment patterns.
USDA-FSIS inspection mandates and FDA Food Safety Modernization Act (FSMA) preventive controls govern domestic production access, while EU Regulation (EC) No 853/2004 on food of animal origin shapes export eligibility into European retail. Brazil's MAPA (Ministério da Agricultura, Pecuária e Abastecimento) export certification requirements and China's GB 2726 national food safety standard for cooked meat products further fragment compliance architectures. Stakeholders must monitor evolving front-of-pack labeling mandates and carbon accounting disclosures across their priority destination markets.
Market Dynamics
Retort pouch packaging technology is compressing traditional can formats across Southeast Asian retail corridors, forcing processors to reconfigure filling lines and shelf-stable protein economics.
Growth Catalysts
- Urban household replenishment:Dense metropolitan clusters in Vietnam and the Philippines are driving ambient-protein stocking cycles through convenience store networks and quick-commerce platforms.
- EU cold chain reduction mandates:Regulatory pressure to minimize refrigerated transport is expanding shelf-stable meat procurement by European institutional foodservice operators and emergency logistics providers.
- Reduced-sodium curing R&D:Advances in potassium chloride substitution and natural flavor masking are opening premium positioning in health-conscious North American retail segments.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings in Brazilian and US grain belts compress processor margins during contract-renewal windows with institutional buyers.
- Single-source retort equipment dependency:Concentrated supply of high-pressure sterilization machinery from German and Italian OEMs creates capex bottlenecks for mid-scale processors.
- Plant-based protein substitution:Textured vegetable protein and mycelium-based alternatives are capturing trial among Southeast Asian urban millennials in casual dining channels.
Strategic Opportunities
- Indonesian archipelago distribution:Underdeveloped cold chain infrastructure across 17,000 islands creates captive demand for ambient-storage protein in provincial retail and disaster relief stockpiles.
- Front-of-pack carbon labeling:Early compliance with emerging EU and UK carbon accounting disclosure rules can secure preferential placement in sustainability-curated retail banners.
- Microwaveable pouch + e-commerce bundling:Direct-to-household subscription models pairing retort pouches with complementary shelf-stable sides are testing in São Paulo and Mexico City metro zones.
Industry Challenges
- Retort operator certification timelines:USDA-FSIS and MAPA-mandated thermal processing validation protocols extend facility commissioning by 8-14 months, delaying revenue recognition.
- Legacy ERP integration with traceability systems:Batch-level blockchain and GS1 serialization requirements are forcing costly middleware deployments at Midwest and São Paulo processing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Pork Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chunky, Shredded, Sliced, Whole Packaging Type: Can, Pouch, Cup, Tray End User: Household, Restaurants, Catering Services, Food Processing Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Hormel Foods Corporation, Conagra Brands, Tyson Foods, JBS, Smithfield Foods, BRF, Marfrig Global Foods, Nestlé, Vion Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Pork Market Trends and Innovations
Active and intelligent packaging systems are rewriting shelf-life communication protocols, while regulatory pressure on sodium and carbon transparency is compressing formulation and labeling cycles simultaneously.
High-barrier multilayer retort pouches with oxygen-scavenging films are bifurcating the conventional metal can market. Premium chunked pork processors in Thailand and Spain are adopting these structures for microwave-ready positioning. The technology is bifurcating channel economics: supermarkets absorb higher unit costs for convenience premiums, while traditional wholesale channels resist format migration.
EU Regulation (EC) No 1169/2011 front-of-pack nutritional labeling requirements are tightening sodium disclosure thresholds for processed meat products. Manufacturers serving German and French retail banners must reformulate or accept traffic-light labeling penalties. Smaller Portuguese and Polish processors are exiting branded retail rather than absorb R&D and packaging redesign costs.
Quick-commerce replenishment is displacing weekly supermarket stocking for ambient proteins in São Paulo, Jakarta, and Manila metro corridors. Dark store networks and 15-minute delivery platforms are compressing case sizes and favoring single-serve pouch formats. This behavioral shift is most visible among dual-income households without cold storage redundancy in dense urban towers.
Canned Pork Market Segmentation
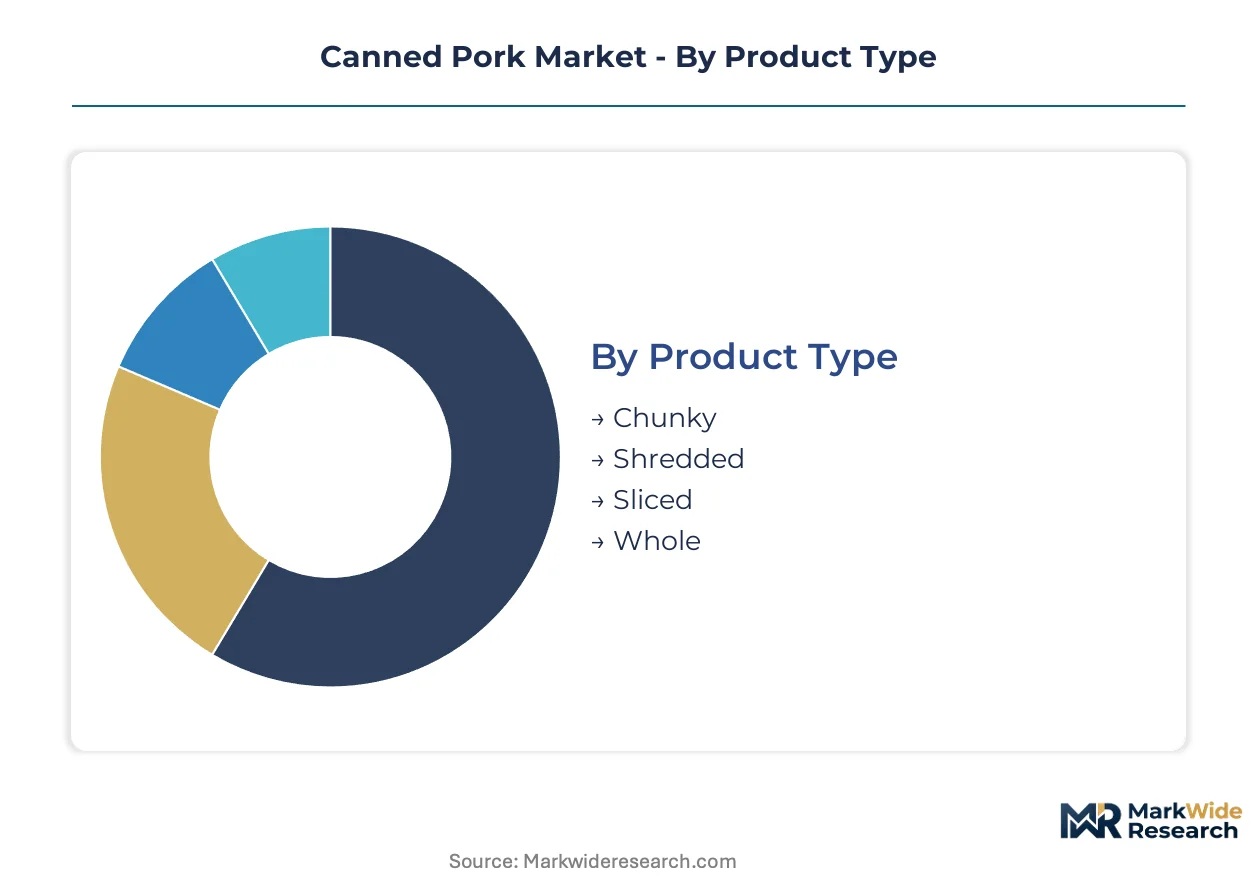
Retort processing configurations and channel economics fragment the canned pork landscape across four intersecting dimensions. Margin capture varies sharply by format convenience, thermal stability requirements, and route-to-market infrastructure investments.
Product Type:
Margin pools concentrate in formats supporting industrial food manufacturing and premium retail positioning.
- Chunky:Irregular bite-sized pieces retain muscle fiber integrity through 121°C retort cycles, commanding premium placement in Thai and Vietnamese ready-meal manufacturing. Industrial buyers in Bangkok and Ho Chi Minh City procurement corridors prioritize this format for soup and stew applications where texture differentiation supports branded positioning.
- Shredded:Pulled pork textures processed through controlled mechanical separation dominate North American sandwich and taco filling channels. QSR chains in Texas and California specify moisture retention standards above 65% for holding-cabinet performance, locking in supplier qualification requirements.
- Sliced:Uniform thickness cuts serve European deli counter and institutional catering segments with presentation requirements.
- Whole:Intact shoulder or ham portions target ceremonial and gift-box retail in East Asian markets.
Chunky holds installed capacity across Southeast Asian processing corridors. Shredded is rotating up the share rankings through QSR specification wins.
Packaging Type:
Cost tier stratification separates capital-intensive metal formats from flexible alternatives gaining traction in quick-commerce channels.
- Can:Three-piece tinplate or aluminum cylinders with double-seamed ends remain the default for 24+ month shelf stability in emergency stockpiles and military logistics. Midwest US and São Paulo canneries maintain dedicated filling lines for institutional contracts requiring drop-shock durability.
- Pouch:High-barrier multilayer laminates with aluminum oxide or ethylene vinyl alcohol cores are climbing fastest in São Paulo and Jakarta metro e-commerce bundles. Microwave venting features and 40% shipping weight reduction support dark-store replenishment economics.
- Cup:Single-serve polypropylene containers with peelable lidding target convenience store hot-bar integration in Japan and South Korea.
- Tray:Thermoformed barrier trays with modified atmosphere capabilities serve European retail deli segments requiring reclosability.
Can formats retain dominant installed base. Pouch structures are expanding most quickly through urban quick-commerce penetration.
End User:
Application-driven volume concentration splits between ambient-protein replenishment cycles and ingredient manufacturing specifications.
- Household:Pantry-stocking consumers in Manila and Jakarta dense urban towers drive single-serve and small-case formats through 15-minute delivery platforms. Cold storage redundancy gaps in rental apartment configurations favor shelf-stable protein security.
- Restaurants:Independent and chain foodservice operators in Mexico City and São Paulo specify reduced-sodium cured inputs for menu labeling compliance.
- Catering Services:Institutional banquet and event contractors in German and French metropolitan zones procure large-format cans for holding-line efficiency.
- Food Processing:Ready-meal manufacturers in Thailand and Spain integrate chunked inputs as protein components in retorted curry and stew applications.
Food Processing commands dedicated production lines. Household is climbing fastest through quick-commerce platform onboarding.
Distribution Channel:
Customer type and geography dictate margin capture, with platform economics compressing traditional wholesale structures.
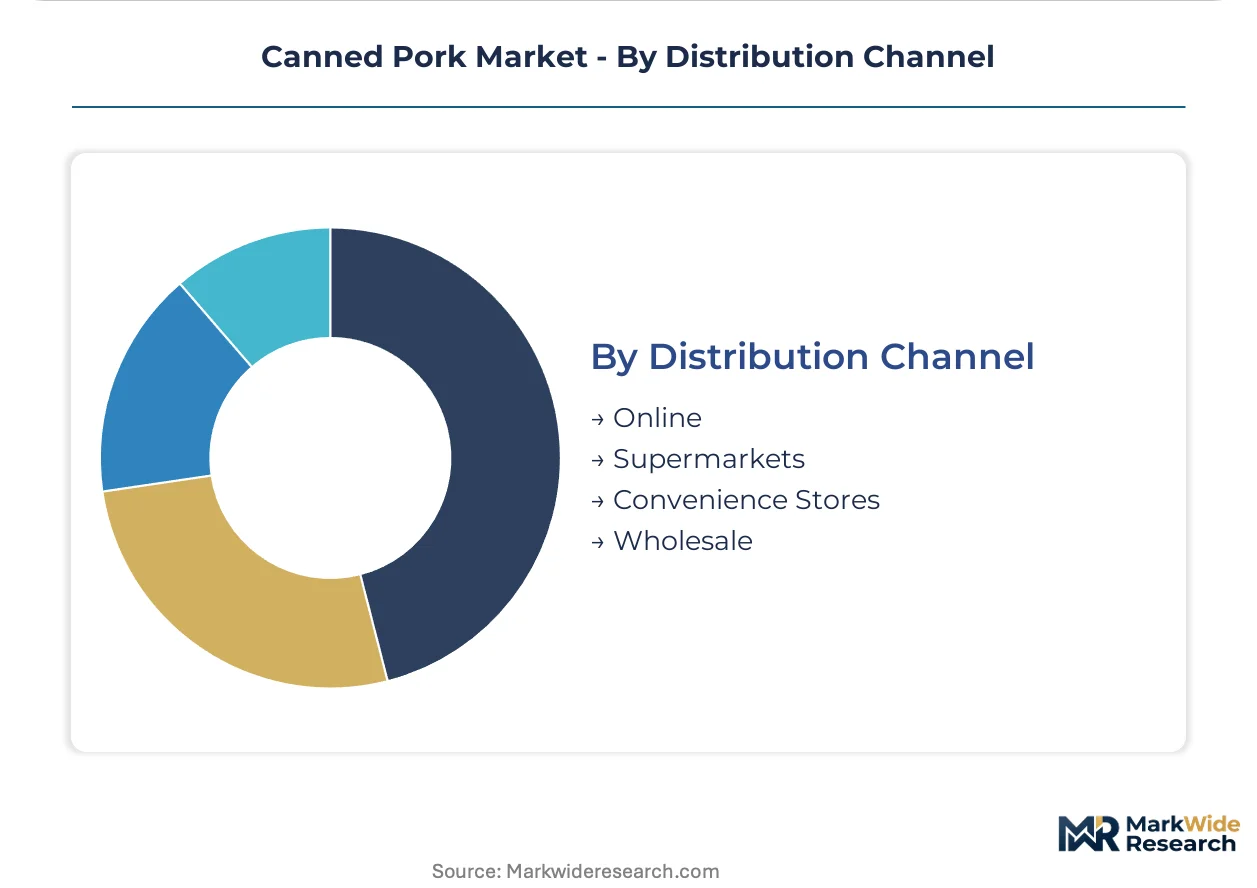
- Online:Direct-to-household subscription models and quick-commerce dark stores in São Paulo, Jakarta, and Manila are displacing weekly supermarket stocking. Fifteen-minute delivery platforms compress case sizes and favor pouch format bundling with complementary shelf-stable sides.
- Supermarkets:Traditional retail banners in US Midwest and German suburban corridors remain the mature margin pool for branded chunked and sliced formats.
- Convenience Stores:Urban corner store networks in Vietnam and the Philippines drive ambient-protein replenishment through high-frequency, small-basket transactions.
- Wholesale:Cash-and-carry and institutional distributors in Latin American corridors serve restaurants and catering operators with large-format can configurations.
Supermarkets retain dominant shelf space allocation. Online is gaining share fastest through metro dark-store density expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional buyers and quick-commerce platforms concentrate procurement in five national markets where regulatory frameworks and distribution infrastructure shape competitive access. Each geography presents distinct compliance thresholds and channel economics for shelf-stable protein suppliers.
United States
Midwest processing corridors anchor domestic supply, with USDA-FSIS inspection mandates governing facility access. The FDA Food Safety Modernization Act preventive controls framework shapes export eligibility protocols. Chicago and Omaha metropolitan zones host concentration of canning operations serving military logistics and emergency relief stockpiles.
Brazil
Captive supply integration from grain belt to processing plant sustains raw material cost advantages. MAPA export certification requirements fragment compliance architectures for European and Asian destinations. São Paulo state maintains dominant installed capacity, with JBS and BRF operations concentrated in the southeastern industrial corridor.
Germany
EU cold chain reduction mandates expand institutional procurement of ambient-storage proteins. EU Regulation (EC) No 853/2004 on food of animal origin governs import eligibility and domestic processing standards. The Ruhr industrial zone and Bavarian processing clusters serve as distribution hubs for Central European retail banners.
Vietnam
Urban household replenishment through convenience store networks drives ambient-protein stocking cycles. The country's national food safety authority enforces cooked meat product standards aligned with regional import requirements. Ho Chi Minh City and Hanoi metro corridors concentrate quick-commerce platform density and dark-store infrastructure.
Indonesia
Underdeveloped cold chain infrastructure across the archipelago creates captive demand for shelf-stable protein. National food safety regulators enforce halal certification requirements that shape supplier qualification. Java island processing zones and provincial retail networks in Sumatra and Sulawesi serve disaster relief stockpiles and remote community access.
Canned Pork Market Competitive Landscape
Player mix skews toward vertically integrated protein conglomerates with captive raw material supply and mid-scale regional processors competing on geographic proximity to institutional buyers. Strategic archetypes bifurcate between farm-to-can integrators controlling margin pools through backward supply chain ownership and formulation specialists commanding premium positioning through reduced-sodium and clean-label credentials. Dominant competitive moves center on retort pouch capacity expansion for quick-commerce channel access and R&D partnerships targeting potassium chloride substitution technologies.
Within the integrated conglomerate tier, Hormel Foods Corporation and Tyson Foods exemplify divergent approaches to margin defense. Hormel occupies a position anchored in premium chunked segment control through upstream farm ownership. Tyson sits within the formulation-driven vector, with its corporate structure supporting R&D intensity in curing innovation. JBS represents the emerging-market integrated model, with its Brazilian corporate origin signaling captive supply advantages in global raw material sourcing.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| Conagra Brands |
| Tyson Foods |
| JBS |
| Smithfield Foods |
| BRF |
| Marfrig Global Foods |
| Nestlé |
| Vion Group |
| Others |
Pricing and Supply Chain Analysis
USDA-FSIS Safe Food for Canadians Regulations alignment gates supplier eligibility and simultaneously stratifies price tiers across North American retail channels, forcing processors to absorb certification costs or surrender shelf space to compliant rivals.
Pricing Analysis
Cost-plus contracts indexed to Chicago Board of Trade corn and soybean meal futures dominate procurement between Brazilian processors and Latin American institutional buyers. Price differentiation separates HACCP-certified facilities from standard-tier operators, with the former commanding placement premiums in German and French retail banners. Pricing pressure stems from feed cost volatility in US and Brazilian grain belts, compressing margins during contract-renewal windows. Quick-commerce households in São Paulo and Jakarta metro zones exhibit lowest price sensitivity, while Latin American wholesale distributors remain most responsive to unit cost fluctuations.
Supply Chain Analysis
Inbound logistics costs through Santos and Ho Chi Minh City ports fluctuate with container availability on Asia-Latin America trade lanes, forcing processors to buffer inventory or absorb freight volatility. Raw material supply concentrates in Brazil, the United States, and China, with captive hog farming in São Paulo state and Iowa corridors anchoring cost structures. German and Italian OEMs control high-pressure retort equipment supply, creating single-source vulnerability for mid-scale processors expanding pouch capacity. Distribution runs through supermarket wholesale networks in mature markets and quick-commerce dark stores in Southeast Asian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort pouch technology is disrupting shelf-stable protein economics, with EU cold chain reduction mandates accelerating format substitution across institutional procurement channels.
For Market Incumbents: Fortify backward integration into captive hog supply in Brazilian and US Midwest corridors to insulate margins from feed cost volatility. Expand HACCP-certified pouch capacity in Thailand and Spain to preempt quick-commerce specification wins by regional processors. Plant-based protein substitution in Southeast Asian casual dining channels threatens trial conversion among urban millennials. For New Entrants and Emerging Players: MAPA export certification fast-tracks unlock European retail access for Brazilian mid-scale processors with compliant thermal processing validation. Target Indonesian provincial retail networks across Sumatra and Sulawesi where underdeveloped cold chain infrastructure creates captive demand for ambient-storage protein. Bundle microwaveable retort pouches with complementary shelf-stable sides in direct-to-household subscription models testing in São Paulo and Mexico City. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across retort pouch manufacturing lines as German and Italian OEM equipment backlogs extend facility commissioning timelines. Acquisition candidates include Southeast Asian processors with installed chunked-format capacity and dormant MAPA or EU 853/2004 certification pathways. Monitor potassium chloride substitution R&D partnerships as signal of premium positioning viability in reduced-sodium North American retail segments.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Capacity Expansion | Captures quick-commerce channel growth in São Paulo and Jakarta metro corridors. |
| Backward Integration into Hog Farming | Insulates Brazilian processors from Chicago Board of Trade feed cost volatility. |
| EU 853/2004 Certification Investment | Unlocks institutional procurement contracts under cold chain reduction mandates. |
| Potassium Chloride Substitution R&D | Opens premium positioning in health-conscious German and French retail banners. |
| Dark Store Distribution Partnership | Compresses replenishment cycles for 15-minute delivery platforms in Manila and Ho Chi Minh City. |
Research Methodology
Cross-validation between primary interviews with retort processing engineers, USDA-FSIS compliance officers, and Southeast Asian quick-commerce category managers anchors the qualitative findings against secondary validation from MAPA export certification databases, EU Regulation (EC) No 853/2004 implementation guidance, and Chicago Board of Trade agricultural futures data. Bottom-up facility capacity assessments triangulate with top-down retail channel audits across supermarket, convenience store, and online distribution networks.
Sensitivity analysis around feed cost indexation, retort equipment lead times, and regulatory compliance timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, end-user application, and distribution channel, with regional regulatory clusters further disaggregating geographic outputs. CAGRs derive from installed capacity utilization rates, channel migration patterns, and formulation R&D intensity indices specific to shelf-stable meat processing.
Decision-makers should treat outputs as directional under assumptions of sustained EU cold chain reduction policy and stable Brazilian hog supply; material deviation in either would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Middle East Red Meat Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Meat Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Beef Jerky Market
Meat Products
United States Frozen Meat Market
Meat Products
Meat Paste Market
Meat Products
Grass Fed Beef Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Global Edible Meat Market
Meat Products
Grassfed Jerky Market
Meat Products
Blended Meat Market
Meat Products
Pepperoni Foods Market
Meat Products
United States Red Meat Market
Meat Products
Brisket Market
Meat Products
Europe Canned Meat Market