
 Kitchen Countertop Market | 2026-2036
Kitchen Countertop Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Countertop Market Analysis
Fabrication labor margins is narrowing as templating software and CNC cutting equipment shift value toward material suppliers and brand owners. Cosentino SA anchors European premium quartz through its Silestone and Dekton lines, leveraging proprietary sintering technology. MSI dominates North American import distribution, controlling slab logistics from factory gate to fabricator yard. Cambria competes as the only American-made quartz producer, sustaining its position through captive resin formulation and domestic manufacturing scale.
Kitchen countertops are horizontal work surfaces installed in food preparation areas, typically fabricated from stone, mineral composite, or synthetic materials with thicknesses ranging from 1 cm to 4 cm and engineered to withstand thermal shock, abrasion, and moisture exposure. Their primary purpose is to provide sanitary, durable workspace for residential cooking and commercial foodservice operations. Granite remains the mature volume leader among material types, though engineered quartz captures accelerating share as fabricators prefer its consistent slab dimensions and reduced installation waste. The residential end user segment occupies the dominant demand position, while hospitality applications generate premium pricing through custom thickness and integrated sink specifications.
The EPA oversees VOC emissions from laminate adhesive systems under Clean Air Act standards, while OSHA workplace silica rules constrain dry-cutting practices for natural stone and drive investment in water-fed fabrication equipment. NSF International certifies food-contact surfaces for commercial kitchen compliance, creating a gatekeeping standard that engineered materials increasingly target. Stakeholders must monitor how state-level building code amendments and evolving silica exposure thresholds reshape fabrication economics and material substitution patterns.
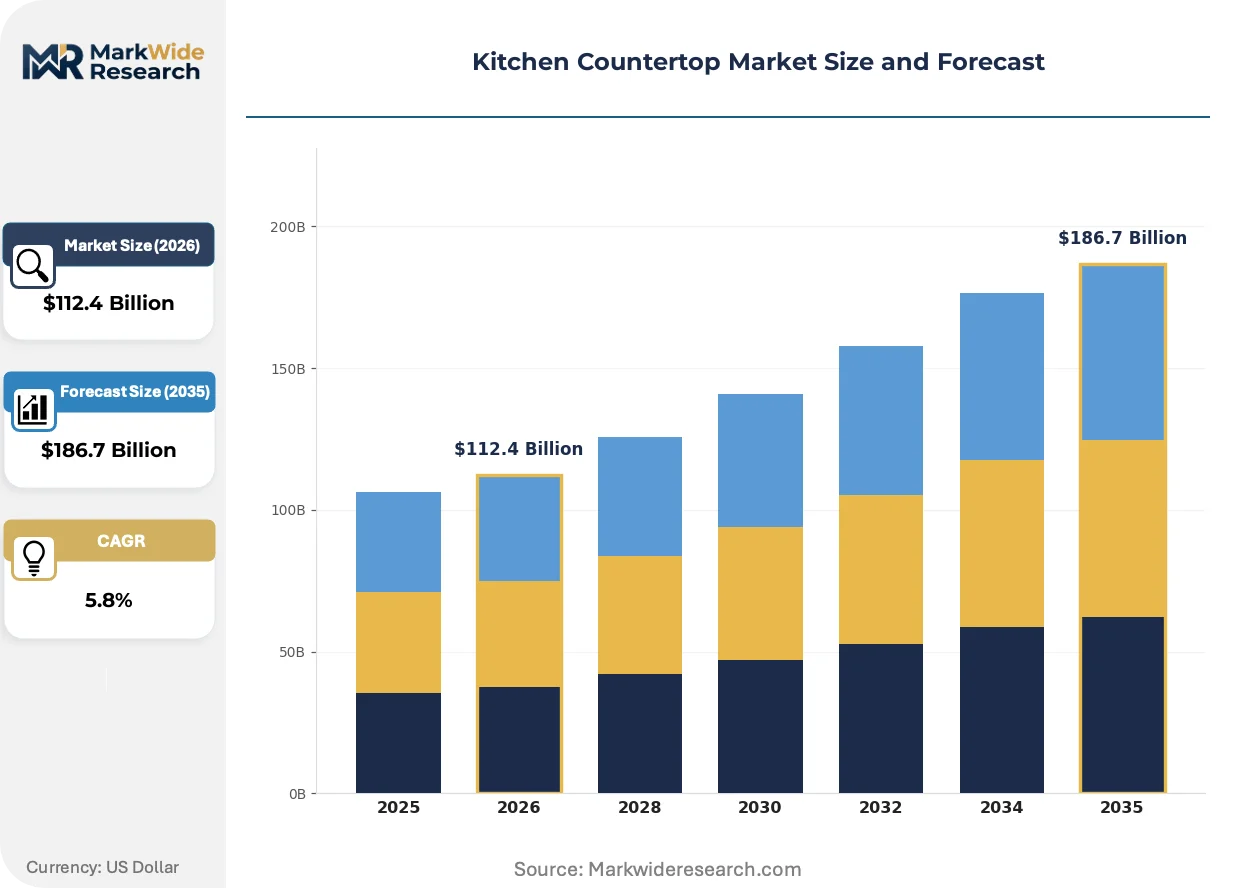
Market Dynamics
Fabrication automation is compressing margins for independent installers while concentrating value with resin formulators and slab distributors who control specification data. This structural shift favors capital-intensive players with captive supply chains over fragmented local fabricators.
Growth Catalysts
- NSF/ANSI 51 Certification:Commercial foodservice operators in the United States increasingly specify engineered quartz meeting this food-contact standard, displacing natural stone in high-traffic kitchen environments where sanitation audits are mandatory.
- Suburban Renovation Cycles:Residential replacement demand across North American metro peripheries is accelerating as homeowners who purchased during low-rate periods invest in kitchen upgrades rather than relocation.
- Metropolitan India Construction:Apartment development along the Mumbai-Bangalore corridor is generating concentrated slab demand as developers standardize on quartz surfaces for mid-market unit specifications.
Market Restraints
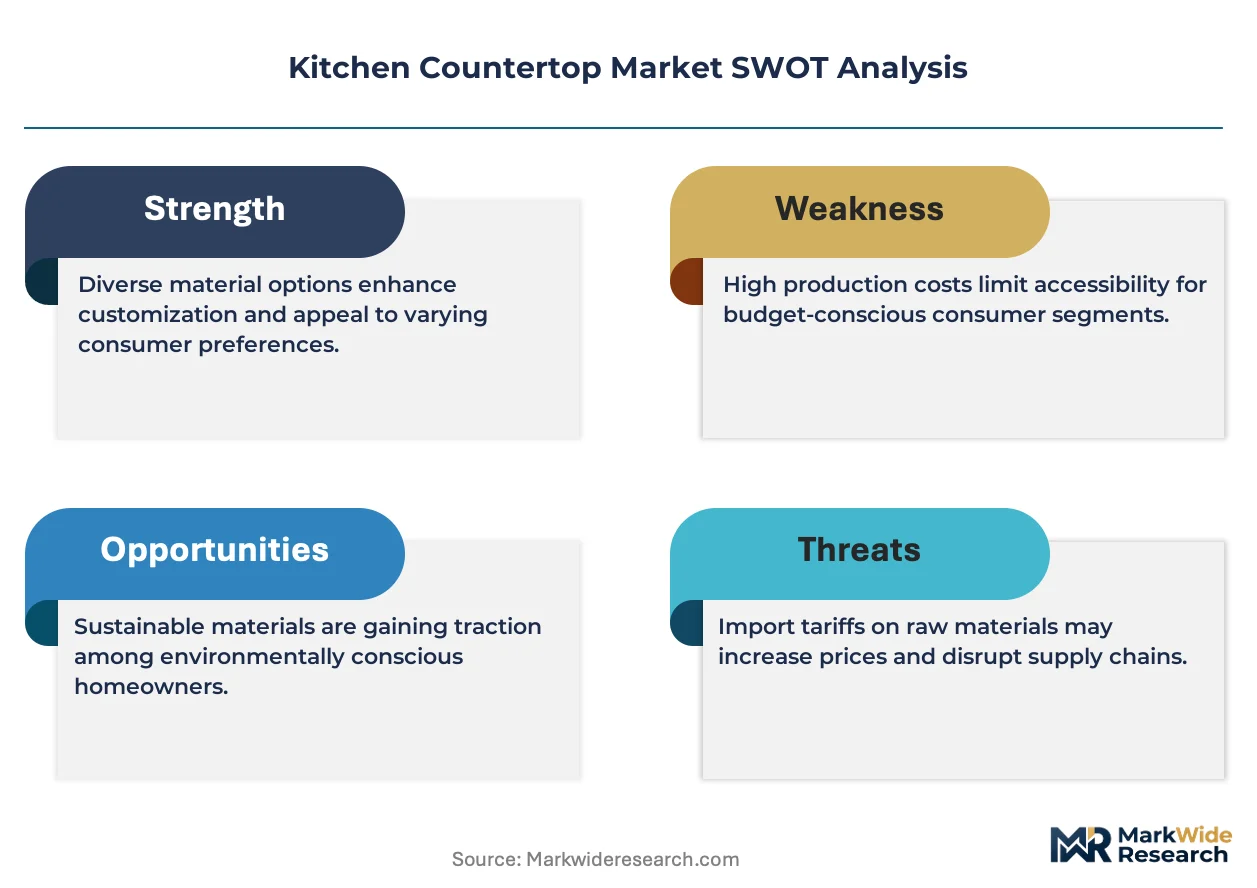
- Petrochemical Resin Volatility:Engineered quartz production depends on petroleum-derived polyester and epoxy resins, exposing manufacturers to crude oil price swings that compress margin predictability.
- Silica Exposure Regulation:OSHA's respirable crystalline silica permissible exposure limit constrains dry-cutting operations, forcing fabricators toward water-fed CNC equipment with higher capital requirements.
- Sintered Stone Substitution:Ultra-compact surfaces manufactured through high-pressure sintering threaten premium quartz positioning in architectural specifications where thermal shock resistance is prioritized.
Strategic Opportunities
- Secondary City Penetration:India's tier-2 urban centers including Pune and Hyderabad show underdeveloped distribution infrastructure for branded engineered surfaces, creating first-mover positioning for organized suppliers.
- Integrated Sink Systems:Specification of seamless basin integration in hospitality and healthcare end-uses commands premium pricing and reduces competitive pressure from commodity slab distributors.
- Water-Fed Fabrication Equipment:Regulatory pressure on silica dust is accelerating replacement cycles for fabrication equipment, creating aftermarket service and financing opportunities for equipment OEMs.
Industry Challenges
- CAD Templating Expertise:Digital measurement and CNC programming skills remain scarce among legacy fabricators, creating bottlenecks as project specifications demand tighter dimensional tolerances.
- Multi-Jurisdictional Certification:Commercial foodservice installations require navigating overlapping EPA VOC standards, NSF food-contact protocols, and state-level building codes, extending sales cycles and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Countertop Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Granite, Quartz, Marble, Laminate Production Method: Natural, Engineered, Recycled, Solid Surface End User: Residential, Commercial, Education, Hospitality Thickness: 1 cm, 2 cm, 3 cm, 4 cm |
| Companies Covered | Formica, MSI, Cosentino SA, Hanwha, Arborite, Caesarstone, Wilsonart, Arpa Industriale, Cambria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Countertop Market Emerging Trajectories
Digital templating and automated cutting systems are redistributing power across the value chain, compressing fabrication into a logistics function while elevating material science and brand equity as primary differentiation vectors.
Water-jet cutting integrated with 3D surface scanning is collapsing the traditional templating-to-installation timeline from weeks to days. High-volume residential developers in the United States are specifying this workflow to accelerate project closeouts. The technology is collapsing the competitive advantage of artisan fabricators who previously relied on manual measurement expertise.
REACH restrictions on crystalline silica content in manufactured articles are tightening compliance requirements for European quartz producers. ECHA classification of respirable silica as a carcinogen is forcing reformulation toward lower-silica engineered surfaces. German and Italian manufacturers are responding with accelerated R&D into alternative mineral fillers including recycled glass and porcelain.
Builder-direct procurement models are bypassing traditional distributor-showroom channels in North American suburban construction. National homebuilders are consolidating specification authority at corporate headquarters, displacing local fabricator influence over material selection. This concentration is most visible in Texas and Florida metro markets where production home construction dominates new housing supply.
Kitchen Countertop Market Segmentation
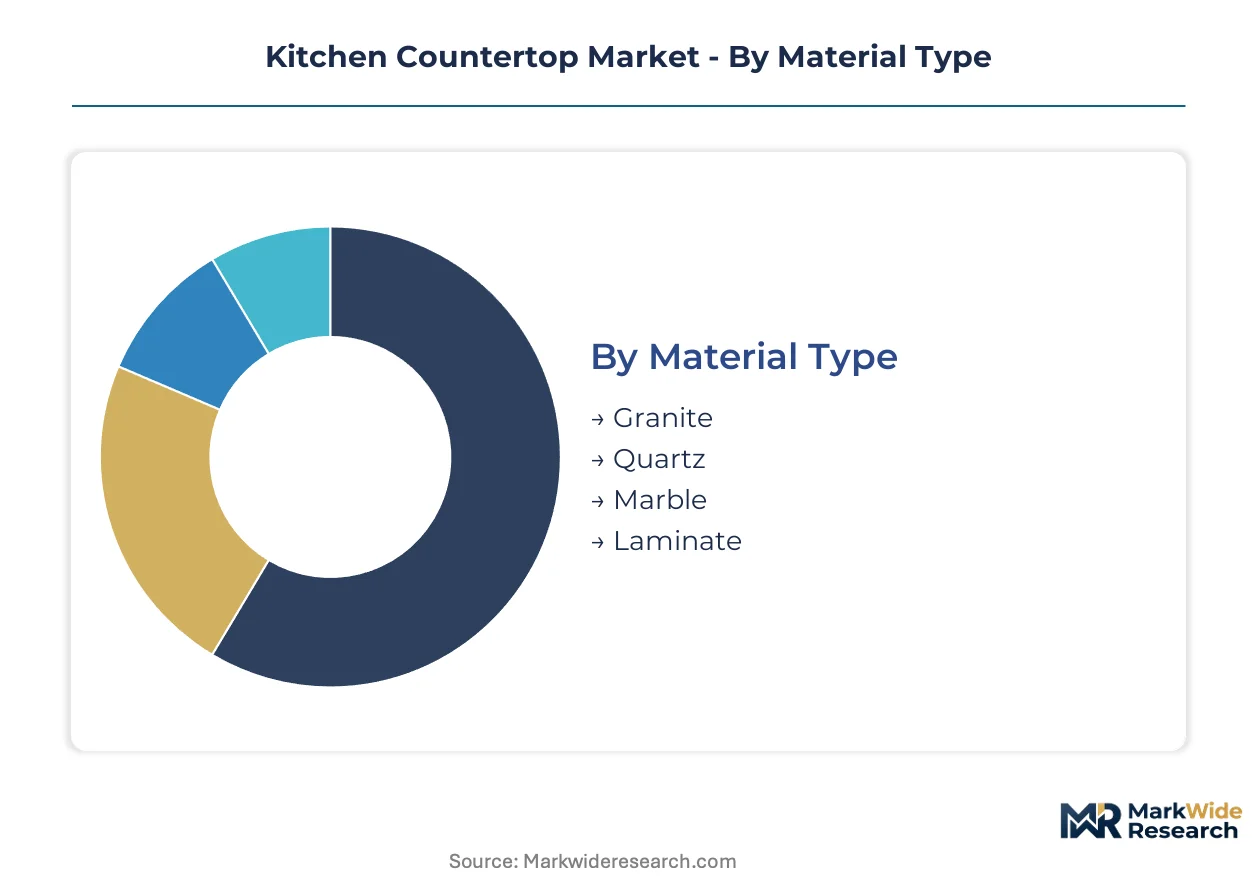
Material composition and fabrication method determine performance specifications, installation economics, and regulatory compliance pathways across countertop applications. Thickness and end-use segmentation directly influence pricing structures and distribution channel selection.
Material Type:
Mature natural stone categories coexist with engineered alternatives that command specification authority through dimensional consistency and compliance certification.
- Granite:Igneous rock slabs quarried from Brazil, India, and Italy retain dominant volume share through established distribution networks and consumer familiarity with natural pattern variation. Demand concentrates in North American suburban renovation projects where homeowners prioritize perceived durability and resale value recognition.
- Quartz:Engineered stone combining ground mineral aggregate with polymer resin binders achieves superior stain resistance and NSF/ANSI 51 food-contact certification that natural stone cannot match. Fabricators prefer quartz for reduced templating waste and consistent slab dimensions that accelerate CNC cutting throughput.
- Marble:Metamorphic calcium carbonate stone prized for veining aesthetics carries porosity limitations that restrict use to low-traffic residential vanity and baking applications.
- Laminate:Paper-resin composite bonded to particleboard substrate occupies economy renovation segments where budget constraints override performance specifications.
Granite retains volume leadership; quartz holds the steepest expansion curve.
Production Method:
Cost tier stratification separates premium positioning from commodity substitution threats.
- Natural:Quarried stone blocks processed through gang saws and polishing lines carry extraction and shipping cost structures that limit margin compression flexibility.
- Engineered:Breton vibrocompression technology enables manufacturers to control slab dimensions, color consistency, and performance characteristics through resin formulation adjustments.
- Recycled:Post-consumer glass and porcelain aggregate formulations respond to ECHA REACH sustainability pressures and green building specification trends in European commercial projects.
- Solid Surface:Acrylic or polyester resin systems allow thermoformed seamless integration and repairability that commands premium pricing in healthcare and laboratory environments.
Natural methods dominate current volume; engineered production climbs the fastest.
End User:
Application type dictates compliance burden, specification complexity, and pricing power.
- Residential:Single-family and multifamily housing accounts for the majority of slab consumption, with renovation cycles driving replacement demand in suburban North American markets.
- Commercial:Corporate foodservice, retail, and institutional kitchens require NSF certification and EPA VOC compliance that filter supplier eligibility and extend sales cycles.
- Education:K-12 and university foodservice operations prioritize durability and sanitation audit performance over aesthetic differentiation.
- Hospitality:Hotels and restaurants specify custom thicknesses, integrated sinks, and branded surface designs that generate premium pricing and direct manufacturer relationships.
Residential commands absolute volume; hospitality delivers the steepest margin expansion.
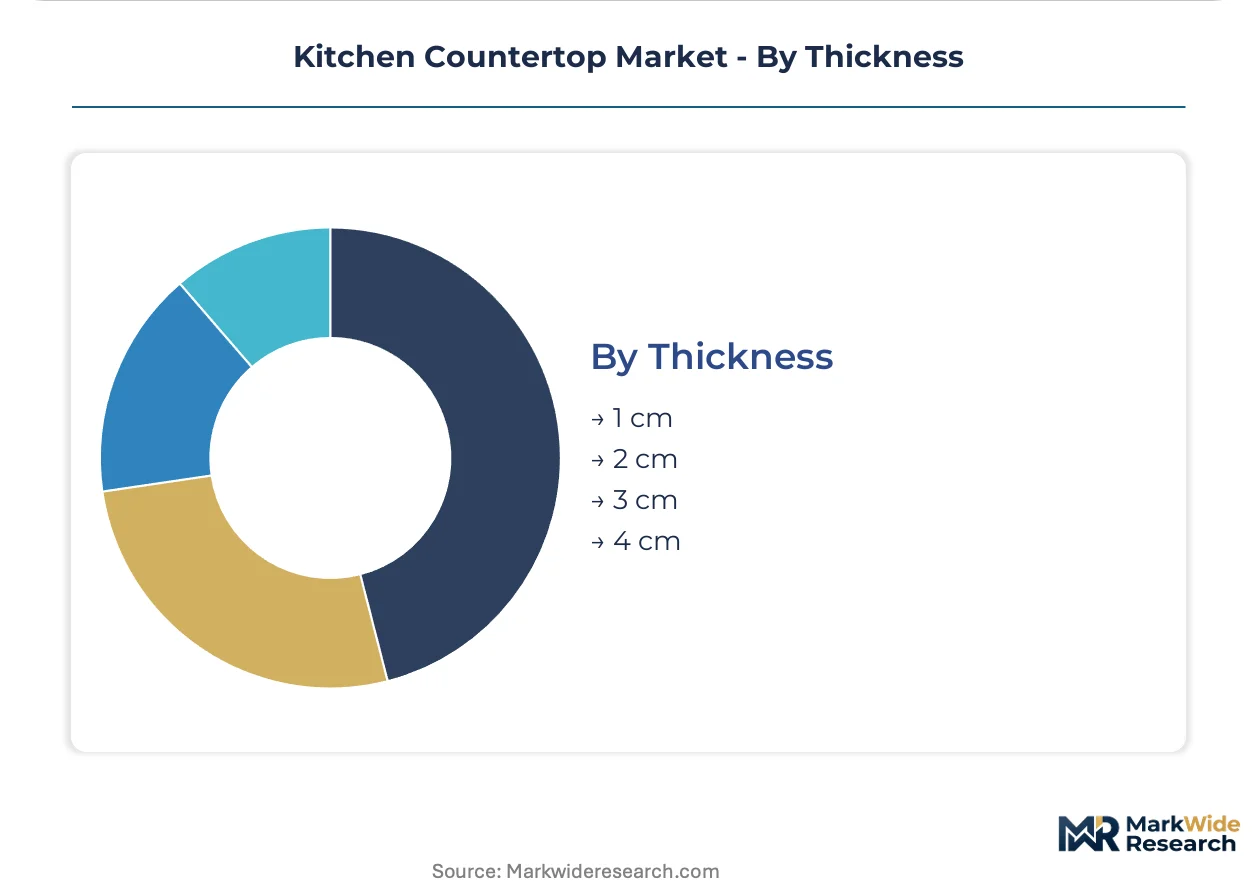
Thickness:
Customer type and installation context determine dimensional specification patterns.
- 1 cm:Ultra-thin profiles serve vertical cladding and furniture applications where weight reduction matters more than impact resistance.
- 2 cm:Standard residential kitchen specifications balance material cost with sufficient structural integrity for typical loading conditions.
- 3 cm:Premium residential and commercial installations specify this thickness for edge profile options and perceived substantiality.
- 4 cm:Heavy-duty commercial foodservice and custom architectural applications demand maximum thermal mass and impact resistance.
2 cm retains installation frequency leadership; 3 cm gains specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Renovation-driven suburban markets in the United States tolerate premium material costs, while India's apartment developers enforce strict budget discipline on slab specifications.
United States
Suburban renovation cycles in Texas and Florida metro areas sustain replacement demand as homeowners invest in kitchen upgrades. OSHA silica exposure regulations constrain dry-cutting practices, forcing fabricators toward water-fed CNC equipment. The Southeast corridor from Atlanta through Charlotte concentrates production homebuilder activity where builder-direct procurement models bypass traditional distributor channels.
India
Apartment construction along the Mumbai-Bangalore corridor generates concentrated quartz slab demand from mid-market developers standardizing on engineered surfaces. BIS certification requirements for building materials extend compliance timelines for imported products. Pune and Hyderabad present underdeveloped distribution infrastructure for branded engineered surfaces, creating positioning opportunities for organized suppliers.
Germany
Commercial foodservice operators specify NSF-compliant engineered quartz for sanitation audit performance in high-traffic kitchen environments. ECHA REACH restrictions on crystalline silica content force reformulation toward alternative mineral fillers. The North Rhine-Westphalia industrial cluster anchors fabrication equipment manufacturing and resin formulation R&D activity.
China
Production scale advantages concentrate in coastal provinces serving both domestic apartment construction and export markets. GB standards for building materials and food-contact surfaces create multi-layer compliance requirements. The Yangtze River Delta manufacturing belt hosts vibrocompression technology deployment and slab logistics consolidation.
Brazil
Natural granite extraction from Minas Gerais quarries retains cost competitiveness in residential renovation segments. ANVISA food-contact surface regulations filter supplier eligibility for commercial kitchen installations. São Paulo's metropolitan construction activity drives specification authority toward engineered alternatives in premium residential towers.
Kitchen Countertop Market Vendor Landscape
Capability concentration sits with resin formulators and sintering technology holders; scale advantage sits with slab distributors controlling logistics from factory gate to fabricator yard. The market structures around three tiers: multinational material science firms with proprietary formulation IP, regional distributors managing import logistics and templating software integration, and fragmented local fabricators facing margin compression from automation. Dominant competitive moves include backward integration into captive resin production and strategic partnerships with high-volume residential developers.
Within the multinational material tier, Cosentino SA anchors European premium positioning through its Silestone and Dekton lines, while MSI dominates North American import distribution networks. Cambria occupies a distinct position as the only American-made quartz producer, sustaining differentiation through domestic manufacturing scale and captive supply chain control.
| Leading Market Players |
|---|
| Formica |
| MSI |
| Cosentino SA |
| Hanwha |
| Arborite |
| Caesarstone |
| Wilsonart |
| Arpa Industriale |
| Cambria |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing belt anchors global engineered quartz capacity, and its resin formulation scale directly shapes downstream pricing power for slab distributors across export markets. Petrochemical input volatility and logistics consolidation in this cluster create asymmetric margin pressure that favors capital-intensive players with captive supply chains over fragmented fabricators.
Pricing Analysis
Long-term offtake contracts between Breton technology licensees and petrochemical resin suppliers dominate pricing structures, insulating volume buyers from spot market polyester volatility. Price differentiation rests on NSF/ANSI 51 certification tier and slab thickness specification, with hospitality-grade 3 cm surfaces commanding substantial premiums over standard 2 cm residential stock. Pricing pressure stems from sintered stone substitution in architectural specifications, compressing margins at the premium tier. Multi-family developers exhibit highest price sensitivity, while hospitality operators prioritize performance certification over unit cost.
Supply Chain Analysis
Extended payment terms from MSI and Cosentino to regional distributors have become standard working capital instruments, compressing cash conversion cycles for independent fabricators. Raw material supply concentrates in China, India, and Spain, with vibrocompression equipment and polymer resin formulations drawing from German and Italian engineering inputs. Single-source vulnerability sits with petroleum-derived resin supply, exposing manufacturers to crude price swings. Distribution runs through importer-distributor networks controlling slab logistics from factory gate to fabricator yard, with builder-direct procurement bypassing traditional showroom channels in North American suburban construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sintered stone substitution threatens premium quartz positioning, forcing incumbents to defend specification authority through certification investment and fabrication automation.
For Market Incumbents: Insulate market position by deepening captive resin formulation capabilities and securing NSF/ANSI 51 certification lock-in for commercial foodservice specifications. Backward integration into sintering technology R&D counters thermal shock performance advantages from ultra-compact surface competitors. Channel control through templating software deployment maintains fabricator dependency and specification influence. For New Entrants and Emerging Players: Pursue distribution infrastructure gaps in India's tier-2 urban centers including Pune and Hyderabad, where organized branded surface penetration remains underdeveloped. Water-fed fabrication equipment aftermarket service presents white-space opportunity given OSHA silica compliance mandates. Go-to-market positioning through equipment financing partnerships with regional fabricators accelerates customer acquisition without direct slab distribution investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates with underperforming countertop divisions lacking scale or certification depth. Long-term viability across the analysis window favors resin formulators and sintering IP holders over commodity slab distributors facing automation-driven margin compression. The signal to watch is builder-direct procurement concentration in Texas and Florida production home markets, which indicates channel power shift toward national specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| NSF/ANSI 51 Certification Investment | Unlocks commercial foodservice specification authority where sanitation audits are mandatory compliance events. |
| Water-Fed Fabrication Equipment Deployment | Addresses OSHA silica exposure limits while creating recurring aftermarket service revenue streams. |
| Backward Integration into Resin Formulation | Reduces petrochemical price volatility exposure and protects margin predictability for engineered quartz production. |
| Builder-Direct Procurement Partnership | Bypasses distributor-showroom channels where national homebuilders consolidate specification authority at corporate headquarters. |
| Sintering Technology R&D Acceleration | Counters thermal shock performance advantages threatening premium quartz positioning in architectural specifications. |
Methodological Framework
Desk research of trade customs data, building permit filings, and commercial foodservice equipment standards preceded structured interviews with resin formulation chemists, CNC fabrication equipment OEMs, distributor procurement directors, and hospitality FF&E specification consultants. Primary fieldwork captured installation economics, templating automation adoption curves, and regulatory compliance cost structures across residential renovation and commercial new construction segments. Secondary validation drew from EPA VOC emission databases, OSHA enforcement records, and NSF certification registries. Bottom-up volume modeling triangulated against top-down construction spending allocation estimates.
The analytical framework held residential renovation cycle intensity and petrochemical resin price bands as fixed boundary conditions while varying apartment construction velocity, silica exposure threshold stringency, and sintered stone penetration rates across the projection horizon. Segmentation dimensions modeled include material composition, production method, end-use application, thickness specification, and regional regulatory cluster. CAGRs derived from installed base replacement dynamics and new construction absorption patterns, with fabrication automation adoption curves and certification compliance timelines as industry-specific forecast inputs.
Sensitivities concentrate around OSHA silica permissible exposure limit revisions, ECHA REACH crystalline silica content restrictions, and crude oil price volatility affecting resin input costs. Forecasts reflect documented assumptions regarding suburban renovation cycle duration and metropolitan India construction velocity. Macroeconomic contraction, accelerated regulatory restriction, or breakthrough sintered stone cost reduction would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Oman Kitchen Hood Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Interactive Tables Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Modular Kitchen Market