
 Italy Cookware Market | 2026-2036
Italy Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Cookware Market Foresight
The EU Green Deal is rebalancing material sourcing across Italian cookware supply chains as Brussels tightens restrictions on per- and polyfluoroalkyl substances in food-contact articles. Bialetti leverages its heritage moka pot expertise to anchor premium positioning in aluminum stovetop segments. Lagostina sustains manufacturing scale through its long-standing base in Omegna, controlling distribution into both domestic retail and European export channels. Risoli specializes in die-cast aluminum production, competing on thermal efficiency for professional kitchen applications.
Italy cookware encompasses vessels and containers designed for stovetop, oven, and open-flame food preparation, typically fabricated from aluminum alloys, ferrous metals, or copper with thicknesses ranging from 2.5mm to 5mm for heat distribution control. Its primary commercial purpose spans residential meal preparation and professional foodservice operations requiring precise temperature management. Stainless steel stock pots and Dutch ovens occupy the highest margin tier within material categories, while non-stick frying pans represent the fastest-growing product type as home cooks prioritize convenience and reduced-oil cooking methods. Cast iron retains niche dominance among professional chefs seeking superior heat retention for slow-cooking applications.
Italy's cookware sector operates under EFSA food-contact material guidelines, REACH chemical safety protocols, and CE marking conformity requirements that dictate surface coating composition and heavy metal migration limits. BIS voluntary standards for imported kitchen goods create additional compliance layers for Asian suppliers entering Italian distribution channels. Stakeholders must monitor evolving EU packaging waste directives and national extended producer responsibility schemes that will reshape material recovery obligations across the value chain.
Market Dynamics
EU Green Deal mandates on per- and polyfluoroalkyl substances are forcing Italian cookware manufacturers to reconfigure coating chemistries and aluminum sourcing across their supply chains. The regulatory pressure is compressing legacy non-stick product lines while accelerating investment in ceramic and mineral-based alternatives.
Growth Catalysts
- EFSA food-contact material guidelines:Stricter migration limits for heavy metals are driving replacement cycles in professional kitchens across Lombardy and Emilia-Romagna.
- Professional foodservice expansion:Milan and Rome restaurant operators are upgrading to PFOA-free equipment to comply with Brussels-mandated chemical safety protocols.
- Recycled aluminum adoption:Northern Italy's industrial cookware belt around Turin is capturing investment in closed-loop material recovery systems.
Market Restraints
- Primary aluminum price volatility:Energy-intensive smelting costs in European smelters are compressing margin structures for die-cast cookware producers.
- REACH compliance complexity:Substance authorization timelines for novel coating chemistries are extending product development cycles by 18-24 months.
- Asian import competition:BIS-certified cookware from Indian and Chinese suppliers is pressuring mid-tier pricing in domestic retail channels.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily retail networks lack premium cookware distribution density relative to northern regions.
- EU packaging waste directives:Extended producer responsibility schemes are creating first-mover advantages for manufacturers with established material recovery infrastructure.
- Induction compatibility convergence:Ferromagnetic base technology is opening replacement demand in households transitioning from gas to electric cooktops.
Industry Challenges
- Coating formulation expertise gap:Ceramic alternative development requires polymer chemistry capabilities scarce in traditional Italian metalworking regions.
- CE marking timeline compression:Conformity assessment body capacity constraints are delaying market access for redesigned product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Cookware Market |
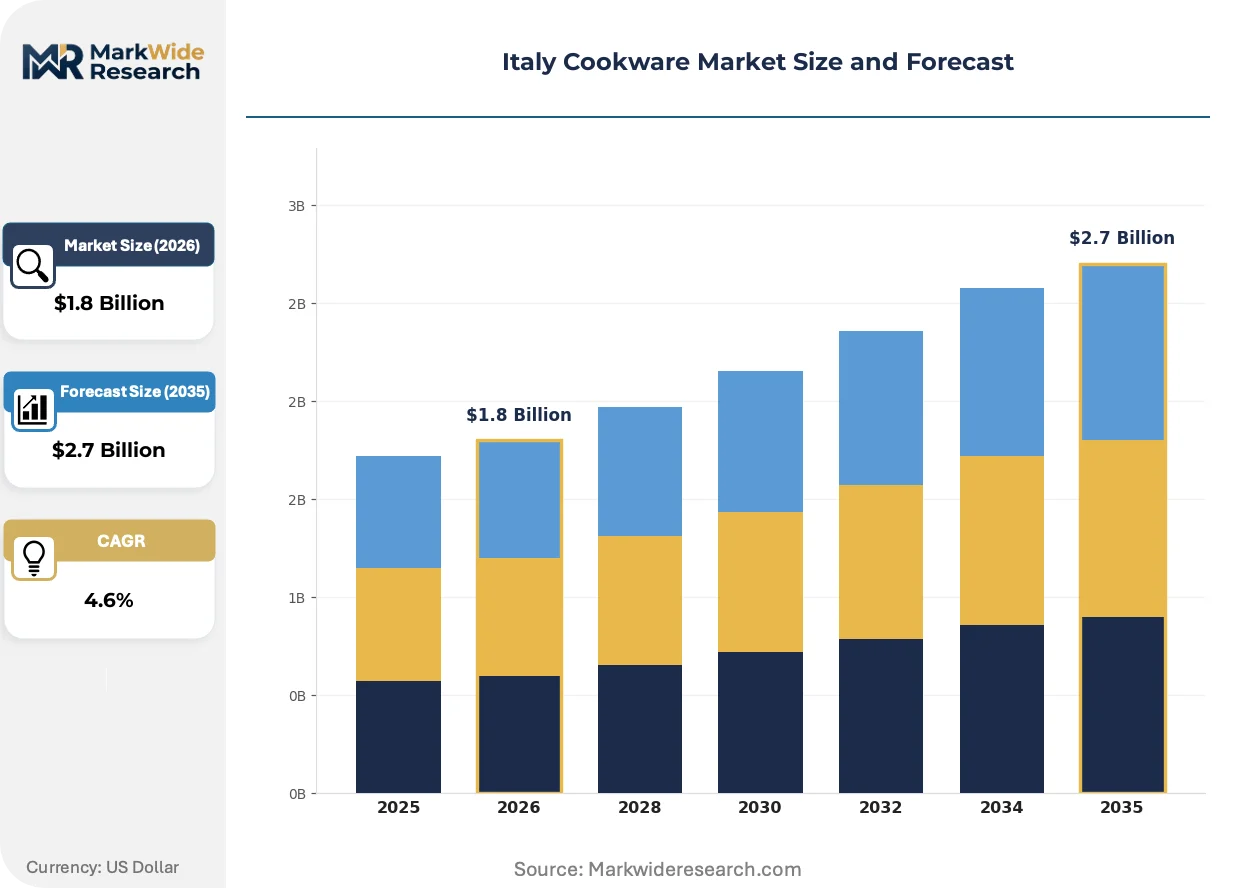
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frying Pans, Saucepans, Stock Pots, Dutch Ovens Material: Stainless Steel, Cast Iron, Non-stick, Copper End User: Home Cooks, Professional Chefs, Restaurants, Catering Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores |
| Companies Covered | Ruffoni, Risoli, Ballarini, Barazzoni, Guzzini, Lagostina, Bialetti, Mepra, Hestan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Cookware Market Shifts & Advancements
Material substitution and regulatory compliance are converging to reshape product architectures across Italian cookware manufacturing. Innovation investment is concentrating on coating durability and thermal efficiency rather than aesthetic differentiation.
Ceramic-reinforced sol-gel coatings are overtaking traditional polytetrafluoroethylene formulations in non-stick applications. Professional kitchen operators in Milan's hospitality sector are adopting these surfaces at accelerating rates due to temperature stability above 450°C. The technology is overtaking legacy chemistries in premium frying pan segments while compressing warranty claim rates for manufacturers.
EU Green Deal implementation through ECHA substance restriction proposals is mandating elimination of perfluorooctanoic acid derivatives from food-contact articles. Italian manufacturers must reformulate surface treatments or face market withdrawal deadlines. The regulation most affects aluminum cookware producers in Piedmont, who are accelerating partnerships with German chemical suppliers for compliant alternatives.
Direct-to-restaurant procurement is consolidating purchasing authority previously fragmented across regional distributors. Large hospitality groups in Rome and Florence are negotiating volume contracts directly with Omegna-based manufacturers, bypassing traditional wholesale channels. This pattern is most visible in northern Italy's industrial catering sector, where procurement centralization is compressing distributor margins.
Italy Cookware Market Segmentation
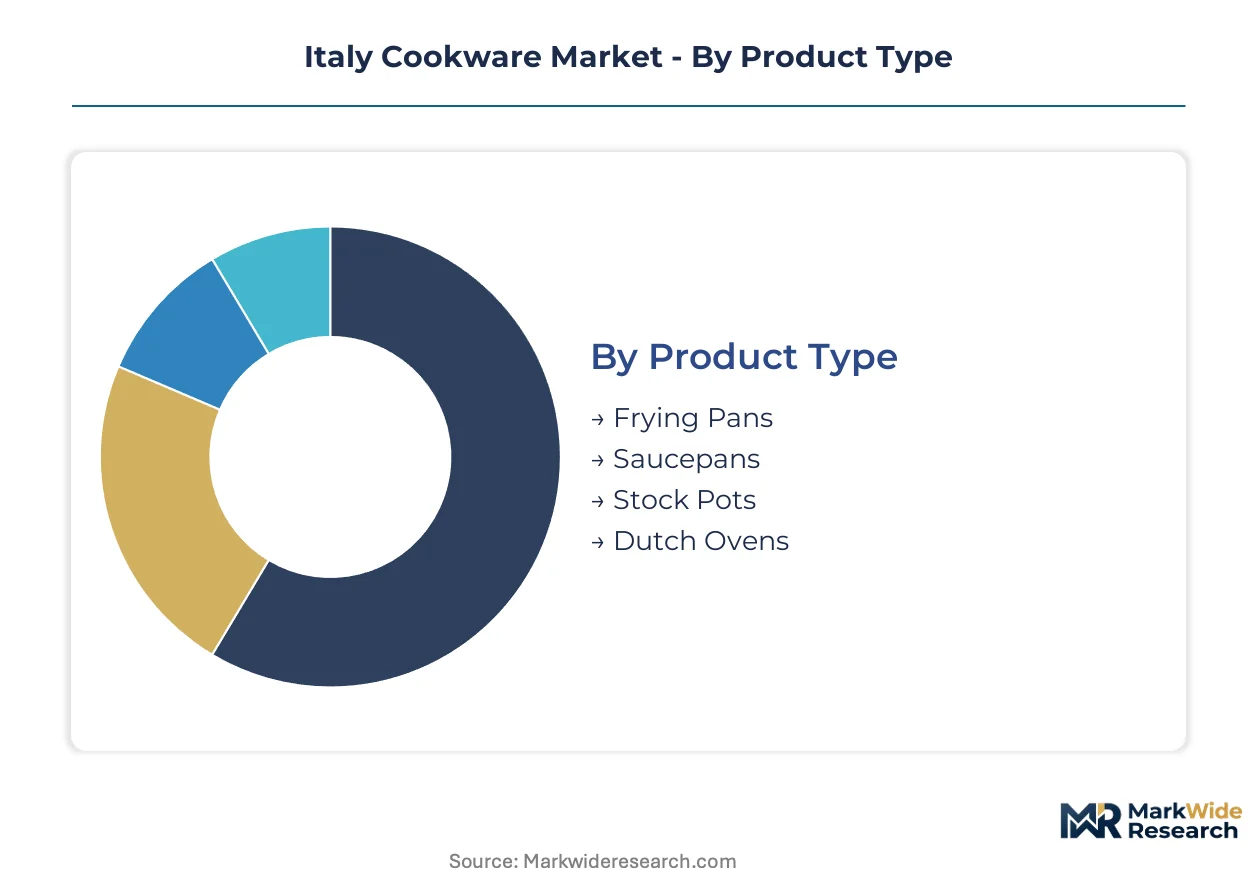
Italian cookware purchasing patterns diverge sharply across professional and residential contexts, with regulatory pressure on coating chemistries and induction compatibility driving material selection. Segment boundaries are blurring as restaurant procurement centralizes and home cooks adopt professional-grade specifications.
Product Type:
Functional design specifications determine heat distribution performance and end-use suitability across stovetop applications.
- Frying Pans:Shallow vessels with sloped sides engineered for rapid heat response and tossing motion. Milan restaurant operators are replacing legacy PTFE-coated units with ceramic-reinforced sol-gel surfaces to meet EFSA migration limits.
- Saucepans:Medium-depth constructions with straight walls optimized for liquid reduction and sauce emulsification. Northern Italy's industrial cookware belt around Turin concentrates die-cast aluminum production for this segment.
- Stock Pots:High-capacity vessels with 5mm+ base thickness for slow-simmering applications. Professional kitchens in Emilia-Romagna favor these for broth preparation.
- Dutch Ovens:Enamel-coated cast iron constructions with tight-fitting lids for braising. Campania retail networks show distribution gaps for this premium category.
Mature deployment sits with Stock Pots in traditional restaurant supply. Newer deployment is concentrated in Frying Pans as coating reformulation accelerates.
Material:
Cost tier positioning separates commodity aluminum from premium metal formulations commanding margin premiums.
- Stainless Steel:Chromium-nickel alloys with 18/10 composition ratios delivering corrosion resistance and neutral flavor profiles. Highest margin tier within material categories due to durability claims and professional kitchen adoption.
- Cast Iron:Ferrous metal with 3-4mm wall thickness providing superior thermal mass for slow-cooking applications. Professional chefs in Rome maintain niche demand for uncoated surfaces requiring seasoning maintenance.
- Non-stick:Aluminum substrates with PTFE or ceramic-reinforced sol-gel surface treatments. EU Green Deal mandates on perfluorinated substances are compressing legacy product lines while ceramic alternatives gain share fastest.
- Copper:2.5mm hammered constructions with tin or stainless steel linings for precise temperature control. Limited to premium residential segments due to maintenance requirements and price positioning.
Volume concentration favors Non-stick in mass retail. Margin capture concentrates in Stainless Steel for professional channels.
End User:
Application intensity dictates durability requirements and procurement authority structures across consumption contexts.
- Home Cooks:Residential consumers prioritizing convenience features and aesthetic coordination with kitchen environments. Induction compatibility is driving replacement cycles in households transitioning from gas cooktops.
- Professional Chefs:Individual practitioners selecting personal equipment for technique-specific applications. Thermal efficiency specifications dominate purchasing criteria in this segment.
- Restaurants:Licensed foodservice establishments subject to EFSA food-contact material compliance. Direct-to-manufacturer procurement is consolidating previously fragmented distributor relationships.
- Catering Services:High-volume mobile food operations requiring lightweight, stackable constructions for transport logistics. Northern Italy's industrial catering sector shows strongest demand concentration.
Procurement standardization sits with Restaurants. Equipment personalization concentrates in Professional Chefs.
Distribution Channel:
Customer type and purchase urgency determine channel selection and service level expectations.
- Online Retail:Digital platforms capturing convenience-oriented residential purchases with specification comparison tools. Induction compatibility filtering is accelerating search-driven selection.
- Specialty Stores:Assortment-focused retailers in Milan and Rome offering hands-on evaluation and staff consultation. Premium material categories maintain highest sell-through here.
- Supermarkets:Mass-market channels distributing commoditized non-stick and basic stainless steel constructions. Price compression from Asian BIS-certified imports is most visible in this channel.
- Department Stores:Full-line retailers with cookware as a home goods category anchor. Southern Italy underpenetration is most acute in this channel relative to northern density.
Established volume sits with Supermarkets. Channel expansion is concentrating in Online Retail as specification transparency improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors Italy's cookware manufacturing density through its position at the southern edge of the Alpine industrial corridor connecting Turin and Bergamo. The metropolitan area hosts procurement headquarters for major hospitality groups and specialty retail flagships. This concentration shapes national distribution patterns and regulatory compliance timelines.
Lombardy
Milan restaurant operators are replacing legacy PTFE-coated equipment with ceramic-reinforced surfaces to meet EFSA migration limits. The EU Green Deal's perfluorinated substance restrictions are accelerating coating reformulation investments across the region. Bergamo's metalworking cluster is retooling die-cast aluminum lines for induction-compatible base constructions.
Piedmont
Turin's industrial cookware belt is capturing closed-loop recycled aluminum investment as energy-intensive primary smelting costs compress margins. REACH substance authorization timelines are extending product development cycles for coating chemistries. Omegna's manufacturing base sustains scale through direct-to-restaurant procurement contracts with Rome and Florence hospitality groups.
Emilia-Romagna
Bologna's professional kitchen supply chains are driving stock pot replacement cycles under stricter heavy metal migration limits. ECHA substance restriction proposals are mandating PFOA derivative elimination from food-contact articles. Parma's foodservice equipment distributors are consolidating purchasing authority previously fragmented across regional wholesalers.
Lazio
Rome's hospitality sector is negotiating volume contracts directly with northern manufacturers, bypassing traditional wholesale channels. CE marking conformity requirements are dictating surface coating composition for imported Asian cookware. The metropolitan area shows underpenetration in premium Dutch oven distribution relative to northern retail density.
Campania
Naples retail networks lack premium cookware distribution density compared to northern regions, creating whitespace for specialty store expansion. BIS voluntary standards for imported kitchen goods are adding compliance layers for Asian suppliers entering southern distribution channels. Extended producer responsibility schemes under EU packaging waste directives are reshaping material recovery obligations for regional distributors.
Italy Cookware Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material-grade and coating-technology dimensions in Italy's cookware sector. The vendor base organizes into heritage aluminum specialists, stainless steel premium fabricators, and die-cast thermal efficiency producers. Three archetypes dominate: multigenerational family manufacturers with regional brand equity, industrial-scale exporters with European distribution control, and coating-technology innovators pivoting from PTFE to ceramic alternatives. Competitive moves concentrate on direct-to-restaurant procurement consolidation and backward integration into recycled aluminum sourcing.
Among heritage Italian manufacturers, Bialetti, Lagostina, and Risoli exemplify distinct strategic positioning archetypes. Bialetti occupies a position representing premium aluminum stovetop heritage anchored in moka pot expertise. Lagostina sits within the scale-driven tier with manufacturing base concentration in Omegna controlling domestic retail and European export channels. Risoli exemplifies the die-cast aluminum specialist archetype competing on thermal efficiency specifications for professional kitchen applications. These three represent the competitive core around which coating reformulation investments and induction compatibility convergence are reorganizing market structure.
| Leading Market Players |
|---|
| Ruffoni |
| Risoli |
| Ballarini |
| Barazzoni |
| Guzzini |
| Lagostina |
| Bialetti |
| Mepra |
| Hestan |
| Others |
Supply & Pricing Matrix
Primary aluminum smelting costs flow from European energy markets through die-cast cookware producers in Turin and Bergamo, compressing margin structures for mid-tier non-stick product lines while premium stainless steel fabricators capture pricing power through thermal efficiency certifications.
Pricing Analysis
Value-based pricing anchored in thermal conductivity performance and EFSA compliance certification separates premium stainless steel stock pots from commodity aluminum frying pans. Three-tier pricing structure across premium, standard, and economy levels reflects material grade differentiation and induction compatibility bundling. Cost compression in die-cast aluminum segments is intensifying because energy-intensive smelting expenses are squeezing producers without captive recycled material streams. Supermarket channels show highest buyer price sensitivity to Asian BIS-certified import competition, while professional kitchen procurement prioritizes coating durability over unit cost.
Supply Chain Analysis
Logistics costs from German chemical suppliers to Piedmont coating facilities are rising as REACH substance authorization timelines extend product development cycles. Geographic supply concentration rests on Italian primary aluminum from European smelters, Chinese ceramic coating precursors, and German polymer chemistry inputs. Raw material dependencies center on aluminum ingot, sol-gel ceramic formulations, and ferromagnetic base alloys for induction compatibility. Single-source vulnerability sits with German chemical suppliers for PFOA-free coating alternatives. Distribution runs through consolidated direct-to-restaurant procurement channels bypassing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
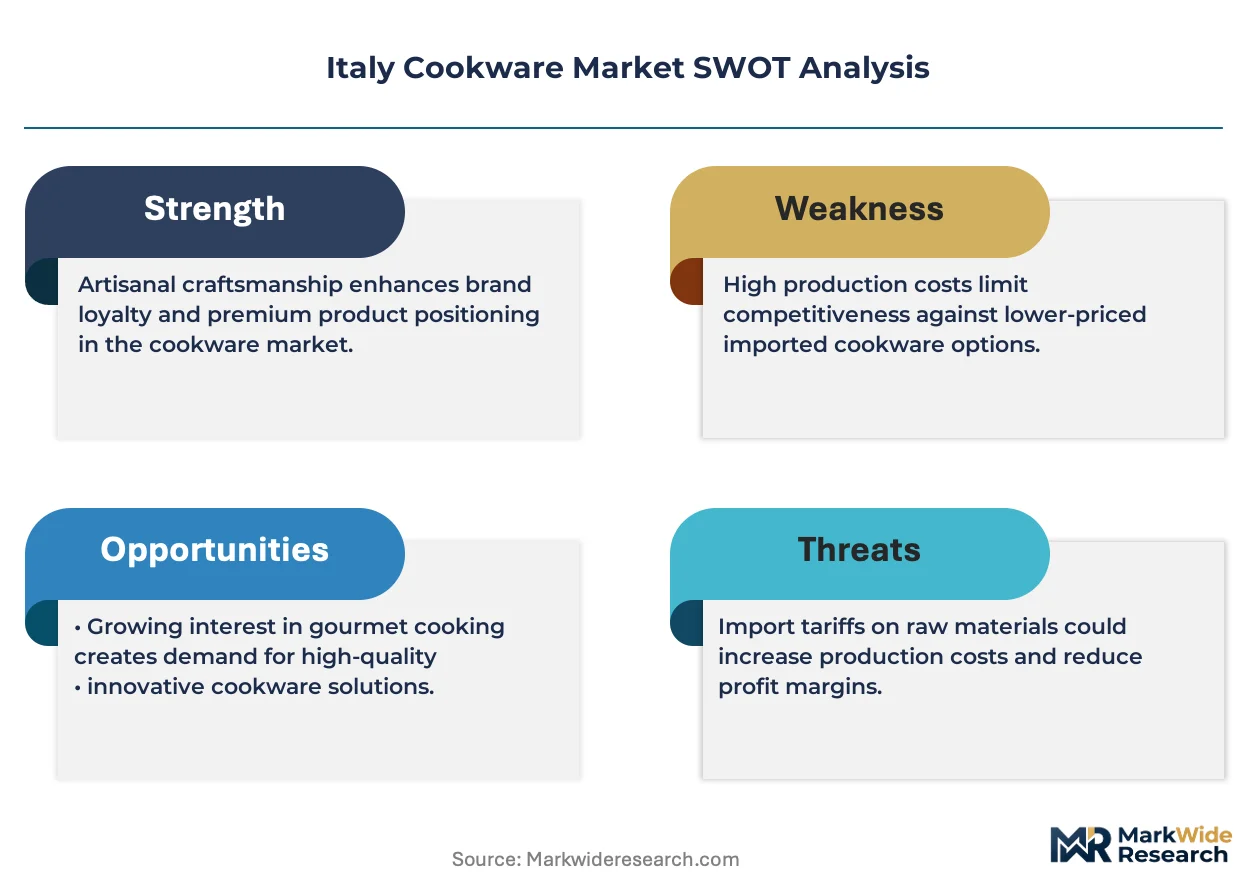
The Italy cookware market reads as a cost-of-compliance story where EU Green Deal mandates on perfluorinated substances erect barrier-to-entry moats favoring manufacturers with established coating reformulation partnerships and EFSA certification infrastructure.
For Market Incumbents: Extend backward integration into closed-loop recycled aluminum sourcing in Turin's industrial belt to defend margin position against primary smelting cost volatility. Deepen partnerships with German chemical suppliers for ceramic-reinforced sol-gel coating alternatives before REACH authorization timelines harden competitive gaps. Channel control through direct-to-restaurant procurement consolidation in Milan and Rome hospitality groups protects pricing power from distributor margin compression. For New Entrants and Emerging Players: Specialty store partnerships in Campania and Sicily offer whitespace penetration where premium Dutch oven and copper cookware distribution density lags northern Italy. Target underpenetrated southern retail networks with induction-compatible product lines as households transition from gas cooktops. A go-to-market angle emphasizing EFSA compliance certification and extended producer responsibility readiness addresses regulatory pressure points incumbent distributors have neglected. For Investors and Strategic Acquirers: Accelerated direct-to-restaurant procurement volume growth from Rome and Florence hospitality groups is the leading indicator that coating-technology innovators with ceramic alternative pipelines will command acquisition premiums. Long-term viability over a multi-year horizon favors die-cast aluminum specialists with Omegna manufacturing footprints and established European export channel control. Acquisition target archetype: mid-scale producers with REACH-compliant coating chemistries and captive recycled aluminum supply agreements. The signal to monitor is CE marking conformity assessment body capacity constraints delaying competitor market access.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation | EU Green Deal PFOA restrictions in Brussels mandate ceramic alternative development by Piedmont manufacturers. |
| Recycled Aluminum Integration | Turin industrial belt investments in closed-loop material recovery reduce exposure to energy-intensive primary smelting. |
| Direct-to-Restaurant Procurement | Milan and Rome hospitality groups consolidate purchasing authority, compressing traditional distributor margins. |
| Induction Compatibility Convergence | Ferromagnetic base technology captures replacement demand from Italian households exiting gas cooktops. |
| Southern Distribution Expansion | Campania and Sicily retail networks lack premium cookware density relative to northern specialty store concentration. |
Research Methodology
Document review covered EFSA food-contact material guidelines, REACH substance restriction proposals, EU Green Deal implementation texts, and Italian national extended producer responsibility schemes, complemented by interviews with plant managers at Omegna and Turin manufacturing facilities, procurement leads from Milan hospitality groups, ceramic coating R&D directors, and distribution channel partners in Lombardy and Campania. Secondary validation drew from customs trade data, SEC filings of listed cookware manufacturers, and CE marking conformity assessment body records. Bottom-up segmentation modeling triangulated against top-down market sizing from aluminum alloy consumption patterns.
Historical shipment data cross-referenced against panel input from procurement executives across northern Italy's industrial cookware belt anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled included product type, material grade tier, end-user application intensity, and distribution channel structure. CAGRs were derived from aluminum price trajectory assumptions and regulatory compliance cost pass-through elasticity. Industry-specific forecast inputs incorporated ECHA substance restriction proposal timelines and induction cooktop adoption rates from Italian household energy transition surveys.
Caveats apply where ECHA substance authorization delays, primary aluminum price spikes, or Asian import tariff adjustments could materially shift the outlook for coating reformulation investments and margin structures. Stakeholders should weight assumptions against their own operating context and regulatory compliance readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
UAE Kitchen Hoods Market