
 Dispersing Agents Market | 2026-2036
Dispersing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Dispersing Agents Market Analysis
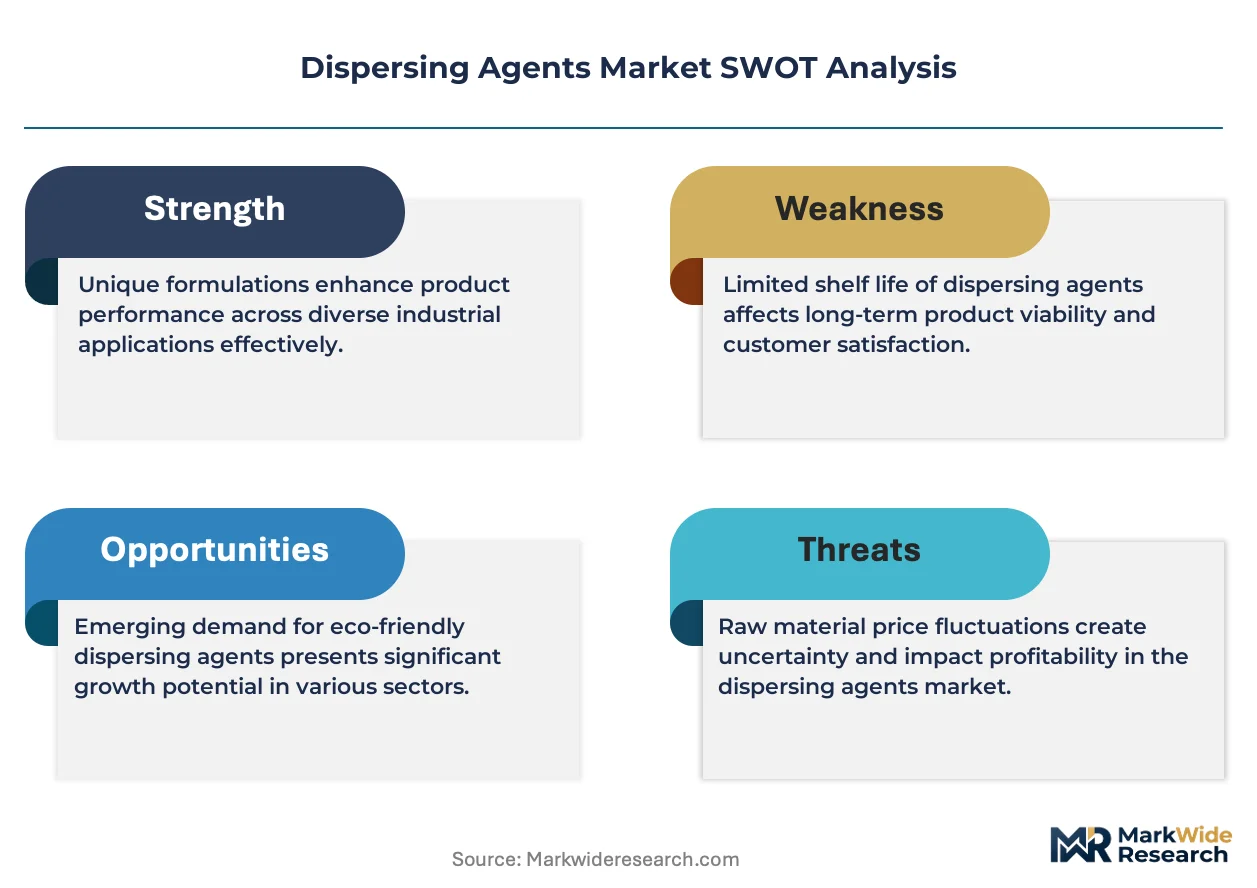
Multi-source procurement of specialty surfactant intermediates is repositioning how coatings formulators manage supply security. BASF SE leverages backward integration into acrylic acid derivatives to sustain margin control across European supply corridors. Dow Inc. anchors North American demand through ethylene oxide chain dominance, while Arkema SA competes on fluorinated dispersant technology for high-performance inks.
Dispersing agents are surface-active compounds, typically 500–50,000 Da molecular weight, that adsorb onto particle interfaces to reduce interfacial tension and prevent agglomeration in liquid media. Polymeric dispersants now command the largest value share within product type segmentation due to their steric stabilization efficacy in high-solid waterborne systems; surfactants retain volume leadership in agriculture and construction applications where cost sensitivity limits premium chemistry adoption. Paints and coatings end users generate the deepest margin pools, though pharmaceutical applications require the most intensive regulatory documentation and quality certification.
EPA registration requirements under FIFRA govern agricultural dispersant formulations in the United States, while REACH and the EU Green Deal constrain petrochemical-derived feedstock use across European manufacturing. China's MEE enforces wastewater discharge standards that elevate demand for biodegradable dispersant alternatives in Yangtze River basin production zones. Formulators must decide whether to absorb compliance costs or pass them downstream before the next regulatory enforcement cycle tightens further.
Market Dynamics
Waterborne coatings mandates across automotive and industrial applications are compressing solvent-based dispersant demand while elevating polymeric alternatives. This regulatory-driven formulation pivot is restructuring supplier relationships and raw material procurement patterns.
Growth Catalysts
- REACH solvent restrictions:European coatings formulators must replace high-VOC surfactants with compliant polymeric dispersants, creating immediate substitution demand across industrial paint lines.
- China's infrastructure pipeline:State-directed construction spending sustains massive offtake for cement and concrete dispersing agents, particularly polycarboxylate ether-based superplasticizers.
- Automotive refinishing waterborne transition:Collision repair shops and OEM refinish operations adopt low-VOC systems, requiring high-performance dispersants compatible with metallic and pearl effect pigments.
Market Restraints
- Ethylene oxide supply concentration:North American and European producers face input cost volatility tied to Gulf Coast petrochemical complex outages and natural gas price swings.
- Fluorinated chemistry regulatory friction:F-Gas Regulation and EPA SNAP program restrictions constrain perfluorinated dispersant use in high-performance ink applications.
- Biobased feedstock technical limitation:Plant-derived hydrophobic anchors lack the molecular weight precision of petroleum-based acrylics, limiting performance in high-solid industrial coatings.
Strategic Opportunities
- India's construction chemical penetration:Underdeveloped admixture usage in residential and commercial concrete creates expansion space for polycarboxylate dispersant suppliers.
- EU Green Deal biobased mandates:Renewable content thresholds in public procurement favor dispersant producers with verified bio-circular feedstock pathways.
- Pharmaceutical nanosuspension growth:Poorly soluble API formulations require specialized polymeric stabilizers, opening high-margin specialty chemical demand.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required for waterborne system stabilization—surfactant-polymer synergy, pigment wetting kinetics—outpaces technical training pipeline output.
- Multi-jurisdictional registration timelines:Agricultural dispersant suppliers face 18-36 month EPA FIFRA and state-level review cycles that delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispersing Agents Market |
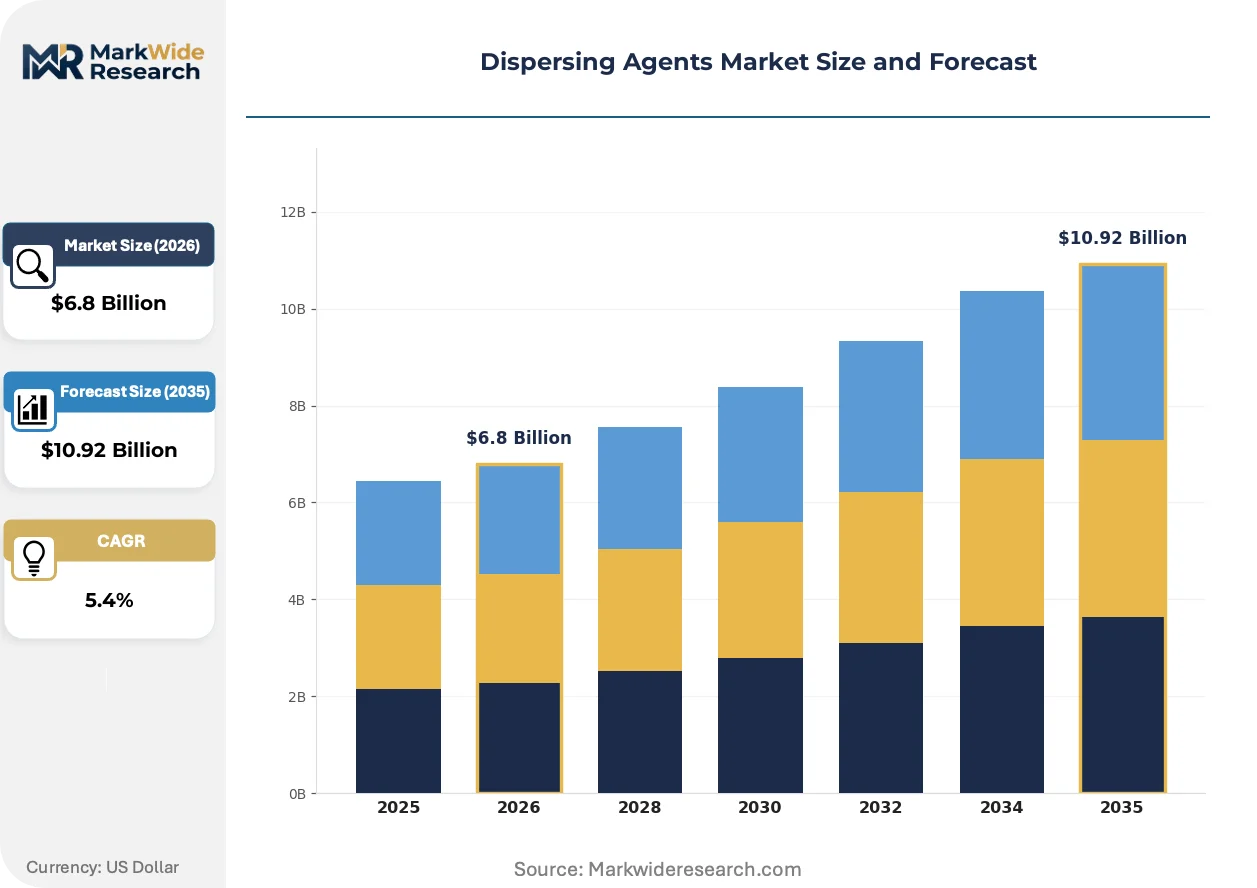
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Dispersants, Surfactants, Suspensions, Emulsions End User: Paints, Coatings, Plastics, Inks Application: Agriculture, Construction, Automotive, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | BASF SE, Dow Inc., Arkema SA, Clariant AG, Evonik Industries AG, Solvay SA, ALTANA AG, LANXESS AG, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispersing Agents Market Emerging Trajectories
Polymeric architecture engineering is displacing conventional surfactant chemistry across premium coating segments. This molecular-design shift is compressing commodity margins while rewarding proprietary dispersant platforms with steric stabilization performance.
Hybrid comb-brush copolymer technology is electrifying high-solid waterborne industrial coatings. These structures combine anchoring segments with extended solvated chains to prevent pigment flocculation at reduced solvent levels. Automotive OEM clearcoat and basecoat formulators in Germany and Japan are accelerating adoption. The technology is electrifying competitive positioning by enabling VOC compliance without sacrificing optical properties or application latitude.
China's MEE wastewater discharge standards are tightening surfactant manufacturing permits in the Yangtze River basin. Facilities must demonstrate biodegradability or advanced treatment capability to maintain operating licenses. Construction-grade dispersant production clusters in Jiangsu and Zhejiang provinces face the steepest compliance investments. Domestic suppliers are responding with glycoside-based and modified natural polymer alternatives that meet COD and toxicity thresholds.
Coatings buyers are consolidating supplier relationships around full-formulation service capabilities rather than discrete chemical procurement. Large industrial paint manufacturers in the United States now demand dispersant suppliers provide integrated colorant compatibility testing and production troubleshooting. This service bundling is compressing spot-market transactions and favoring technical-service-intensive distributors. The pattern is most visible in automotive refinish and protective coatings segments where color matching complexity drives dependency on supplier expertise.
Dispersing Agents Market Segmentation
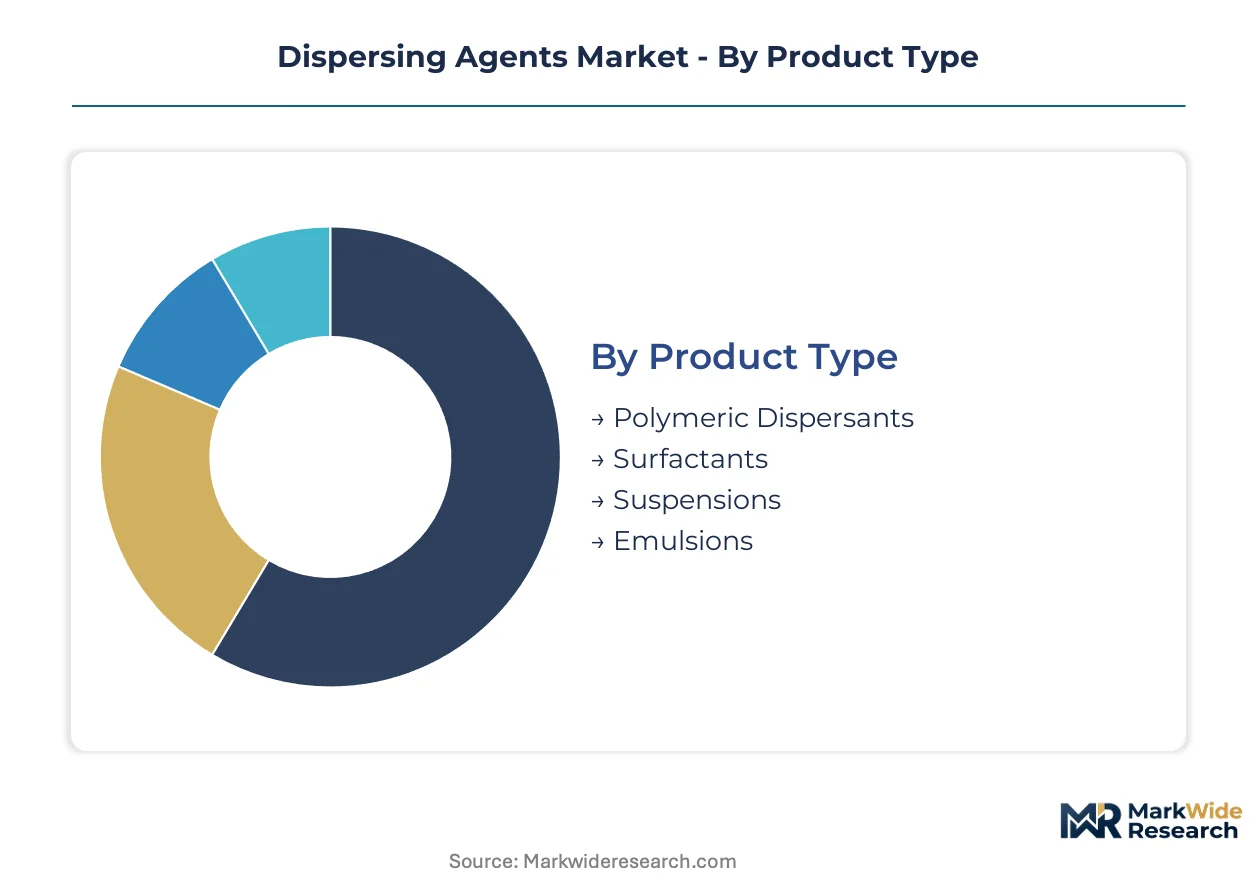
Dispersing agent procurement varies sharply by performance tier and regulatory exposure. Formulators select chemistry based on pigment load requirements, VOC constraints, and end-use certification demands rather than commodity pricing alone.
Product Type:
Standardization dominates commodity surfactants while polymeric architectures demand bespoke molecular engineering for each coating system.
- Polymeric Dispersants:Comb-brush and block copolymer structures deliver steric stabilization in high-solid waterborne coatings. German automotive OEM clearcoat formulators specify these for metallic pigment dispersion under EU solvent restrictions.
- Surfactants:Anionic and nonionic small-molecule compounds remain cost-effective for agricultural and construction applications where performance thresholds permit simpler chemistry.
- Suspensions:Pre-dispersed pigment concentrates reduce manufacturing complexity for mid-size coatings producers lacking in-house dispersion equipment.
- Emulsions:Oil-in-water systems serve specialized ink and adhesive applications requiring controlled particle size distribution.
Most installed capacity flows through Surfactants. Expansion is steepest in Polymeric Dispersants.
End User:
Margin profiles diverge between specification-driven OEM supply and price-sensitive maintenance coatings.
- Paints:Architectural and industrial formulations consume the largest surfactant volumes, with waterborne transitions in China and India driving polymeric dispersant substitution.
- Coatings:Automotive refinishing commands premium pricing for dispersants compatible with pearl and effect pigments; collision repair shops in the United States consolidate supplier relationships around technical service bundles.
- Plastics:Masterbatch producers require heat-stable dispersants for engineering resin compounding, particularly in polycarbonate and polyamide systems.
- Inks:High-performance gravure and flexographic applications face fluorinated chemistry constraints under EPA SNAP and EU F-Gas Regulation.
Coatings generate the deepest margin pools. Plastics applications are gaining share fastest in Asia-Pacific manufacturing clusters.
Application:
Regulatory intensity scales from construction commodity supply to pharmaceutical documentation requirements.
- Agriculture:Pesticide and fertilizer formulations require EPA FIFRA registration, imposing 18-36 month commercialization timelines on dispersant suppliers.
- Construction:Polycarboxylate ether superplasticizers dominate concrete admixture demand, with Chinese state infrastructure spending sustaining massive offtake.
- Automotive:OEM waterborne mandates and collision repair VOC regulations in Germany, Japan, and the United States elevate polymeric dispersant specification.
- Pharmaceuticals:Nanosuspension formulations for poorly soluble APIs demand specialized polymeric stabilizers with intensive quality certification and regulatory documentation.
Construction absorbs the highest volume. Pharmaceuticals present the steepest expansion trajectory.
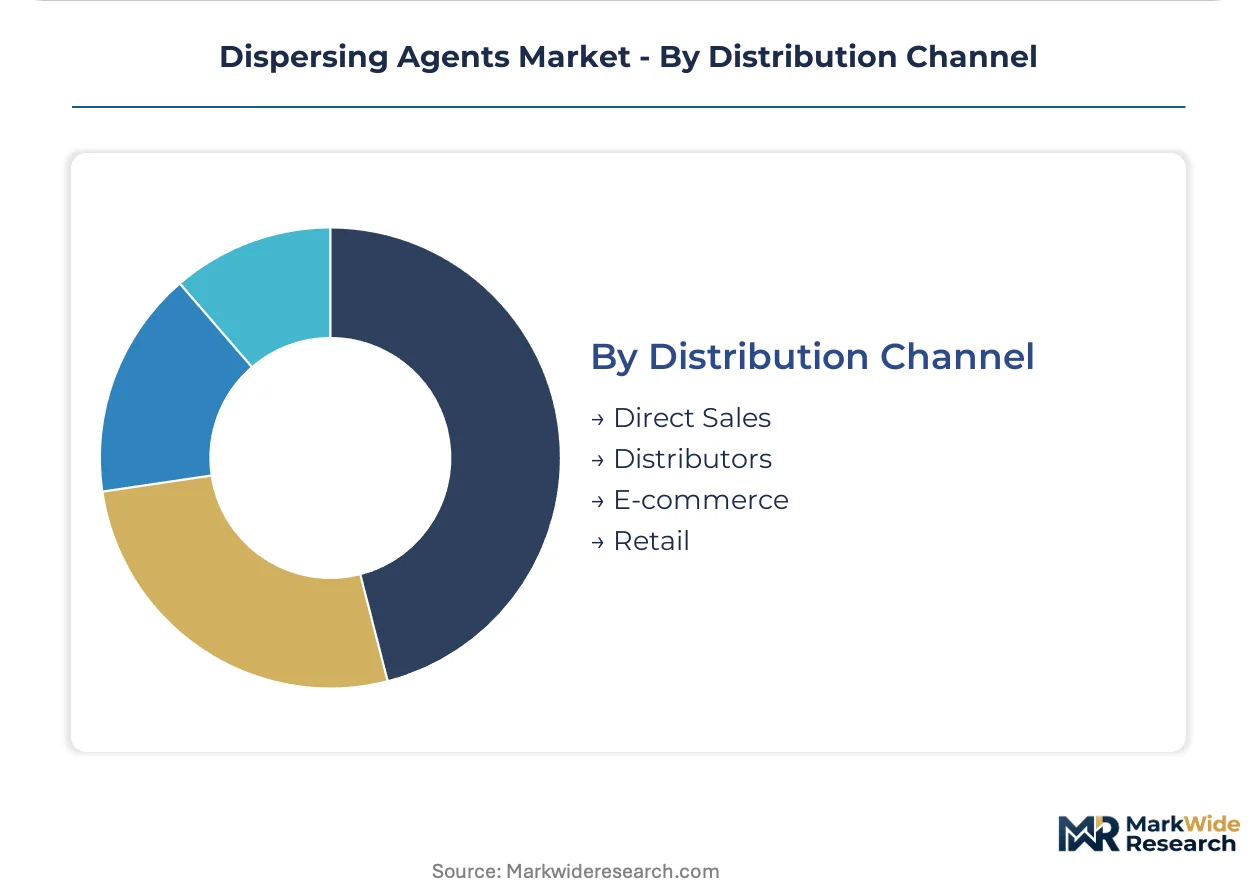
Distribution Channel:
Relationship depth separates technical-service channels from transactional procurement.
- Direct Sales:Large coatings manufacturers negotiate framework agreements with dispersant producers for integrated colorant compatibility testing and production troubleshooting.
- Distributors:Regional chemical distributors serve mid-size formulators with inventory pooling and technical support, particularly in fragmented European markets.
- E-commerce:Spot purchasing of commodity surfactants is expanding for small coatings producers and maintenance operations with predictable formulation requirements.
- Retail:Limited to consumer-grade paint additives and DIY construction chemical segments with minimal technical specification.
Direct Sales capture the largest contract value. E-commerce is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor dispersing agent manufacturing capacity, though procurement patterns diverge sharply across national markets based on regulatory stringency and end-use concentration.
China
State-directed infrastructure spending sustains massive offtake for polycarboxylate ether superplasticizers in concrete admixtures. MEE wastewater discharge standards tighten manufacturing permits in the Yangtze River basin, forcing biodegradability demonstrations. Production clusters in Jiangsu and Zhejiang provinces face steepest compliance investments for COD and toxicity thresholds.
United States
Automotive refinishing operations accelerate waterborne system adoption for collision repair VOC compliance. EPA FIFRA registration requirements govern agricultural dispersant formulations with 18-36 month review cycles. Gulf Coast petrochemical complex concentration creates ethylene oxide supply vulnerability for North American producers.
Germany
Automotive OEM clearcoat formulators specify comb-brush polymeric dispersants for metallic pigment dispersion under EU solvent restrictions. REACH compliance and the EU Green Deal constrain petrochemical-derived feedstock use across manufacturing. Industrial paint production concentrates in North Rhine-Westphalia and Bavaria, with technical service bundling reshaping supplier relationships.
India
Underdeveloped admixture penetration in residential and commercial concrete creates expansion space for polycarboxylate dispersant suppliers. BIS standards and evolving environmental norms gradually tighten formulation requirements. Construction chemical demand concentrates in Maharashtra and Gujarat, with infrastructure outlays sustaining national offtake growth.
Japan
Automotive OEM waterborne mandates in clearcoat and basecoat applications elevate high-performance dispersant specification. METI industrial standards and voluntary environmental agreements shape formulation chemistry selection. Manufacturing clusters in Kanto and Kansai regions drive precision dispersant demand for effect pigment systems.
Dispersing Agents Market Vendor Landscape
Global majors compete with regional champions across technology tiers and service integration depth. The supplier base organizes around three structural layers: integrated petrochemical conglomerates with captive feedstock positions, specialty chemical houses with proprietary polymer architectures, and regional distributors with formulation troubleshooting capabilities. Capacity expansion in Asia-Pacific manufacturing zones and backward integration into acrylic acid derivatives represent dominant competitive moves.
Within the integrated petrochemical tier, BASF SE and Dow Inc. exemplify divergent geographic anchoring strategies, with the former representing European supply corridor control and the latter occupying North American ethylene oxide chain dominance. Arkema SA sits within the specialty performance tier, with its corporate structure suggesting fluorinated chemistry positioning for high-performance applications. These three entities collectively illustrate how supplier archetypes map to distinct regulatory and end-use exposure profiles across automotive, construction, and agricultural demand verticals.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Arkema SA |
| Clariant AG |
| Evonik Industries AG |
| Solvay SA |
| ALTANA AG |
| LANXESS AG |
| Croda International Plc |
| Others |
Supply Flow & Price Mechanics
Backward integration into acrylic acid derivatives anchors margin control for European dispersant producers while compressing pricing power for non-integrated formulators dependent on spot-market ethylene oxide. This structural divide separates suppliers who capture value from captive feedstock positions versus those absorbing Gulf Coast petrochemical volatility.
Pricing Analysis
Ethylene oxide pass-through volatility compresses margins for North American surfactant producers when Gulf Coast outages spike input costs. Three-tier pricing structure across premium polymeric dispersants, standard surfactants, and economy-grade construction admixtures reflects certification grade and volume scale differentiation. Pricing pressure stems from REACH compliance costs forcing reformulation investments. Agricultural applications show highest price sensitivity due to commodity crop economics, while pharmaceutical nanosuspension stabilizers command lowest sensitivity given regulatory documentation barriers.
Supply Chain Analysis
China's evolving domestic-content preferences in Yangtze River basin procurement reshape sourcing patterns for construction-grade dispersants. Manufacturing gravity centers on China, Germany, and the United States, with Jiangsu and Zhejiang provinces hosting concentrated polycarboxylate ether capacity. Feedstock dependencies rest on ethylene oxide, acrylic acid derivatives, and fluorinated intermediates. Single-source vulnerability concentrates around Gulf Coast ethylene oxide complexes. Distribution runs through direct sales frameworks for large coatings manufacturers and regional distributors for mid-size formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dispersing agents market functions as a stable compounder, with waterborne coatings mandates across automotive and industrial applications delivering steady substitution-driven expansion.
For Market Incumbents: Acquire proprietary comb-brush copolymer technology platforms to defend against specialty chemical houses encroaching on automotive OEM clearcoat specifications. Deepen backward integration into acrylic acid derivatives to secure margin control against ethylene oxide volatility. Expand technical service bundling capabilities to lock in collision repair shop relationships before distributor consolidation accelerates. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian construction admixtures offers white-space entry for polycarboxylate ether suppliers with cost-optimized manufacturing. Target underdeveloped residential concrete penetration in Maharashtra and Gujarat with localized production partnerships. Pursue glycoside-based biodegradable dispersant positioning to exploit MEE wastewater compliance requirements in Yangtze River basin zones. For Investors and Strategic Acquirers: Consolidation pressure builds where technical service capabilities separate profitable direct-sales relationships from commoditized distributor channels. Five-to-ten year viability favors specialty chemical houses with verified bio-circular feedstock pathways under EU Green Deal procurement rules. Monitor EPA FIFRA registration timeline compression as inflection signal for agricultural dispersant competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid Derivatives | BASF's captive supply position insulates European margins from ethylene oxide volatility. |
| Hybrid Comb-Brush Copolymer Capacity Expansion | German automotive OEM clearcoat formulators specify these structures for metallic pigment dispersion. |
| Biodegradable Dispersant Platform Development | MEE wastewater standards in Jiangsu and Zhejiang provinces mandate COD and toxicity compliance. |
| Technical Service Bundling Investment | US collision repair shops consolidate supplier relationships around colorant compatibility expertise. |
| India Manufacturing Joint Venture | Maharashtra and Gujarat infrastructure outlays sustain polycarboxylate superplasticizer demand growth. |
Methodological Framework
Bottom-up coatings formulator demand modeling reconciled against top-down ethylene oxide chain capacity tracking forms the analytical core of this study. Primary interviews with plant managers at polycarboxylate ether production facilities, procurement leads at automotive OEM paint operations, distribution channel partners in European admixture markets, and technical R&D directors at specialty chemical houses combined with secondary validation. Sources include customs and trade data from Jiangsu and Zhejiang export zones, Cefic chemical industry reports, SEC 10-K filings from integrated petrochemical conglomerates, and EPA FIFRA registration databases.
Historical trendline analysis across polymeric dispersant substitution patterns, surfactant volume trajectories, and construction chemical penetration rates established baseline growth parameters. Segmentation dimensions modeled include product type tier, end-use industry concentration, application regulatory intensity, and regional production hub clustering. CAGRs were derived from demand elasticity coefficients applied to waterborne coatings mandate timelines and infrastructure spending projections. Forecast inputs incorporated REACH solvent restriction phase-in schedules and China's MEE wastewater discharge standard enforcement calendars.
Caveats apply where ethylene oxide supply disruptions, fluorinated chemistry regulatory bans, or biobased feedstock technical limitations could materially shift the outlook. Forecasts reflect assumptions around automotive waterborne transition adherence and state-directed Chinese infrastructure commitment levels. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
United Kingdom Feed Additives Market
Additives
Citrate Ester Market
Additives
Gasoline Additives Market
Additives
Global Matting Agents Market
Additives
Crystal Growth Modifier Market
Additives
North America Citric Acid Market
Additives
Battery Additives Market
Additives
Europe Anti-Caking Market
Additives
Refinery Process Additives Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Micronized Powder Market
Additives
Global Packaging Additives Market
Additives
Global Synthetic Tackifier Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Low VOC Coating Additives Market