
 Global IP Phone Market | 2026-2036
Global IP Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Global IP Phone Market Foresight
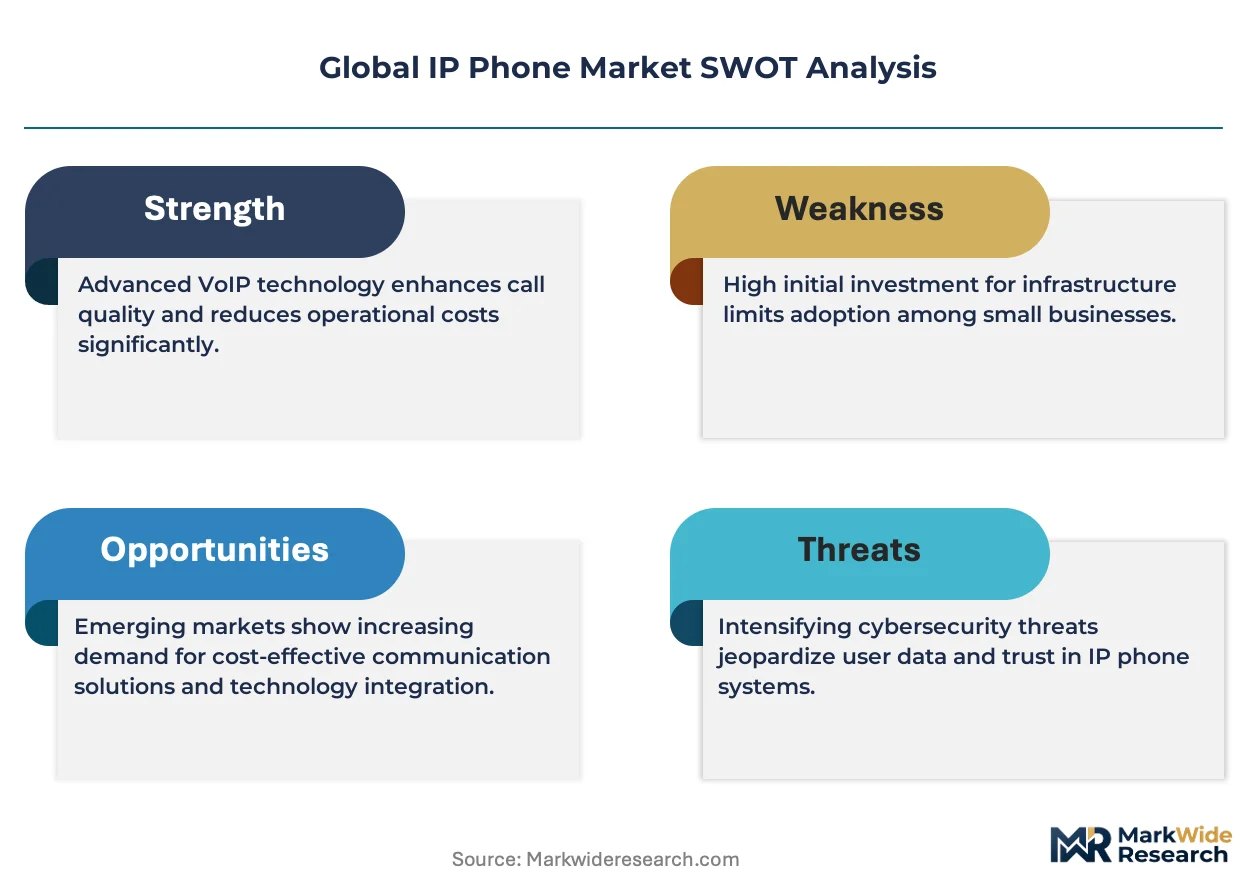
The IP phone market is rebalancing between premium enterprise-grade hardware and commoditized entry-level devices. Cisco Systems dominates high-availability deployments through its Webex-integrated portfolio. Yealink leverages cost engineering to sustain volume leadership in small and medium enterprise channels. Grandstream Networks specializes in open-standard SIP endpoints that navigate interoperability demands across mixed-vendor environments.
An IP phone is a hardware endpoint that digitizes voice into packetized data for transmission over Internet Protocol networks, typically supporting G.711 and G.729 codecs with Power over Ethernet for single-cable deployment. Its primary purpose is to replace analog telephone sets with network-addressable devices that integrate into unified communications platforms. Desk phones remain the largest product category though softphones represent the fastest-expanding segment as remote work communications normalize. Session Initiation Protocol endpoints capture the dominant technology share while secure communications specifications command the widest margin pools due to encryption certification overhead.
The FCC enforces E911 location accuracy standards that shape hardware GPS and network-based positioning requirements for IP phones sold in the United States. Europe's CE marking and GDPR frameworks constrain data processing capabilities and mandate explicit consent architectures for call recording applications. Stakeholders must monitor how NIST cybersecurity guidelines and emerging post-quantum encryption standards will redefine device certification timelines and R&D allocation priorities.
Market Dynamics
Enterprise migration from legacy PBX infrastructure to cloud-native unified communications platforms is compressing hardware refresh cycles and redefining endpoint certification requirements. The FCC's E911 location accuracy mandates impose GPS and network-based positioning hardware specifications that reshape product development roadmaps for vendors serving the United States market.
Growth Catalysts
- FCC E911 Mandates:Location accuracy requirements in the United States force hardware GPS integration, creating replacement demand as organizations retire non-compliant endpoints. Healthcare and education verticals face accelerated compliance deadlines.
- Cloud-UC Platform Expansion:Microsoft Teams and Zoom Phone deployments in Germany and Japan drive SIP endpoint procurement as enterprises standardize on software-defined communications stacks.
- Power over Ethernet Advancement:IEEE 802.3bt high-power delivery enables color touchscreen displays and advanced audio processing without separate power infrastructure, reducing installation costs in facility-wide rollouts.
Market Restraints
- Semiconductor Supply Concentration:Voice processing DSP and gigabit Ethernet PHY chip fabrication concentrates in Taiwan and South Korea, exposing lead times to geopolitical friction and foundry allocation decisions.
- Softphone Substitution:PC and mobile-based softphone applications displace desk phone volumes in remote-first organizations, compressing addressable hardware markets in technology and professional services sectors.
- GDPR Compliance Architecture:European call recording and data retention requirements impose explicit consent mechanisms that increase firmware complexity and certification costs for devices deployed in France and Germany.
Strategic Opportunities
- India Enterprise Modernization:TRAI's push for IP-based interconnection and the country's PLI scheme for telecom equipment create localized manufacturing incentives and public sector procurement preferences.
- Secure Communications Certification:NIST post-quantum cryptography guidelines and Common Criteria evaluations command 40-60% hardware margin premiums in defense, finance, and critical infrastructure deployments.
- Healthcare Integration Convergence:Nurse call system and electronic health record interoperability requirements in Japan and the United States create specialized endpoint categories with embedded HL7 and DECT integration.
Industry Challenges
- Firmware Security Talent Scarcity:Embedded systems security engineering and secure boot architecture expertise concentrates at a handful of vendors, constraining in-house development timelines for mid-tier manufacturers.
- Multi-Vendor Interoperability Certification:Session border controller, PBX, and cloud platform compatibility testing creates fragmented qualification matrices that delay product launches and inflate quality assurance overhead.
- Legacy Analog Integration Complexity:Hybrid deployments requiring simultaneous support for PSTN trunking, ISDN PRI, and pure SIP environments demand expanded SKU portfolios and extended technical support commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IP Phone Market |
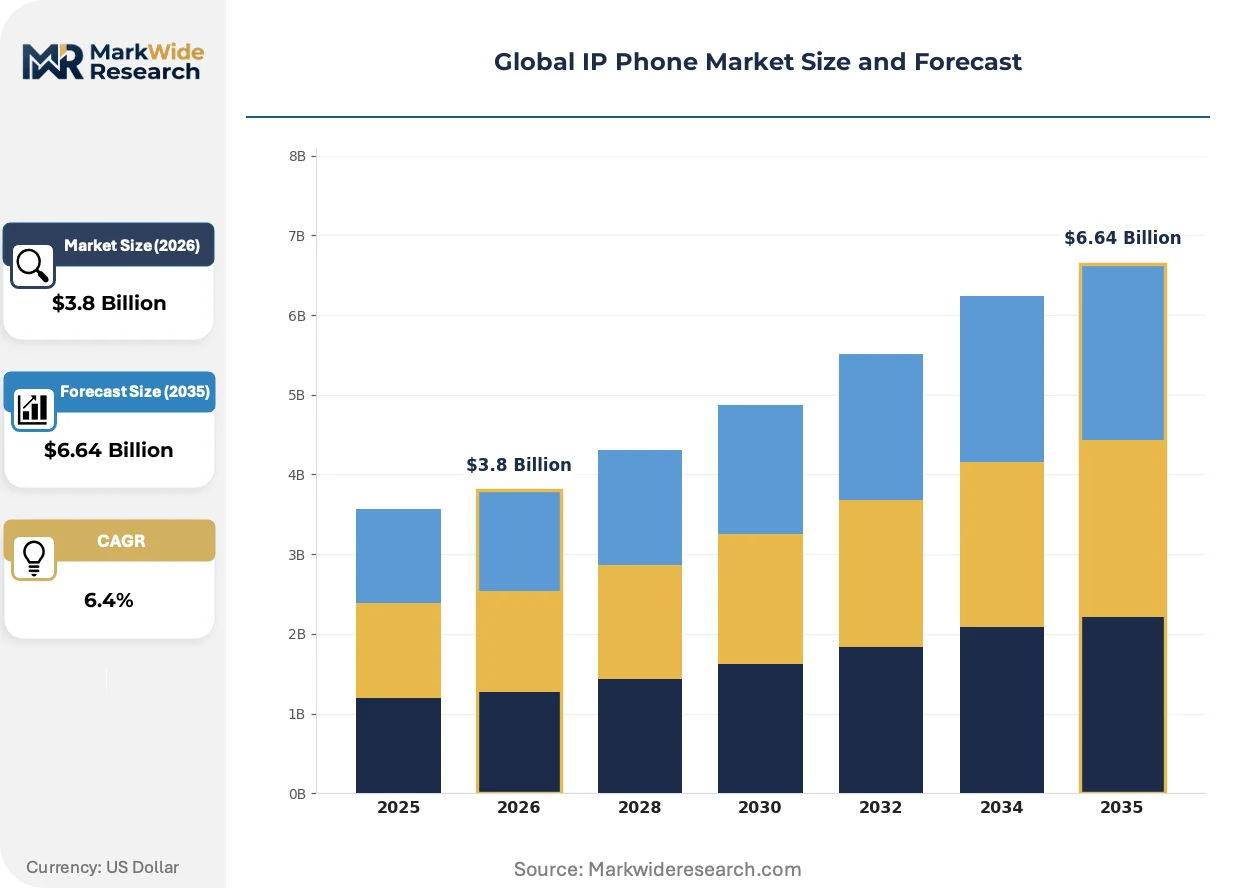
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desk Phones, Conference Phones, Wireless IP Phones, Video IP Phones, Softphones Technology: Voice over Internet Protocol, Session Initiation Protocol, Power over Ethernet, HD Voice, Secure Communications Application: Enterprise Communication, Customer Contact Centers, Remote Work Communications, Unified Communications, Call Recording End User: Small and Medium Enterprises, Large Corporations, Government Agencies, Educational Institutions, Call Service Providers |
| Companies Covered | Alcatel-Lucent Enterprise, Yealink, Cisco Systems, NEC, Grandstream Networks, Avaya, Huawei Technologies, Polycom, Mitel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IP Phone Market Shifts & Advancements
Hardware endpoint architecture is fragmenting between purpose-built desk phones, software-defined softphones, and converged video collaboration bars. Vendors are repositioning around specific integration depths rather than universal compatibility claims.
Android-based IP phone operating systems is modularizing hardware from application layers, enabling third-party UC clients to run natively on commodity silicon. Mid-market enterprises in Germany and Japan are adopting these open-platform devices to avoid vendor lock-in. This modularity is compressing R&D duplication across OEMs while accelerating feature parity.
The EU's Cyber Resilience Act imposes mandatory security update commitments and vulnerability disclosure timelines for connected devices sold in member states. Hardware vendors must maintain firmware support for 5-10 year lifecycles or face market withdrawal. Premium enterprise-grade manufacturers with established security operations centers are absorbing compliance costs more readily than cost-optimized competitors.
Enterprise buyers are consolidating endpoint procurement through managed service providers rather than direct hardware purchasing. Channel partners in the United States and United Kingdom are bundling devices with per-seat SaaS subscriptions, shifting capital expenditure to operational models. This transformation favors vendors with flexible financing programs and white-label support infrastructure.
Global IP Phone Market Segmentation
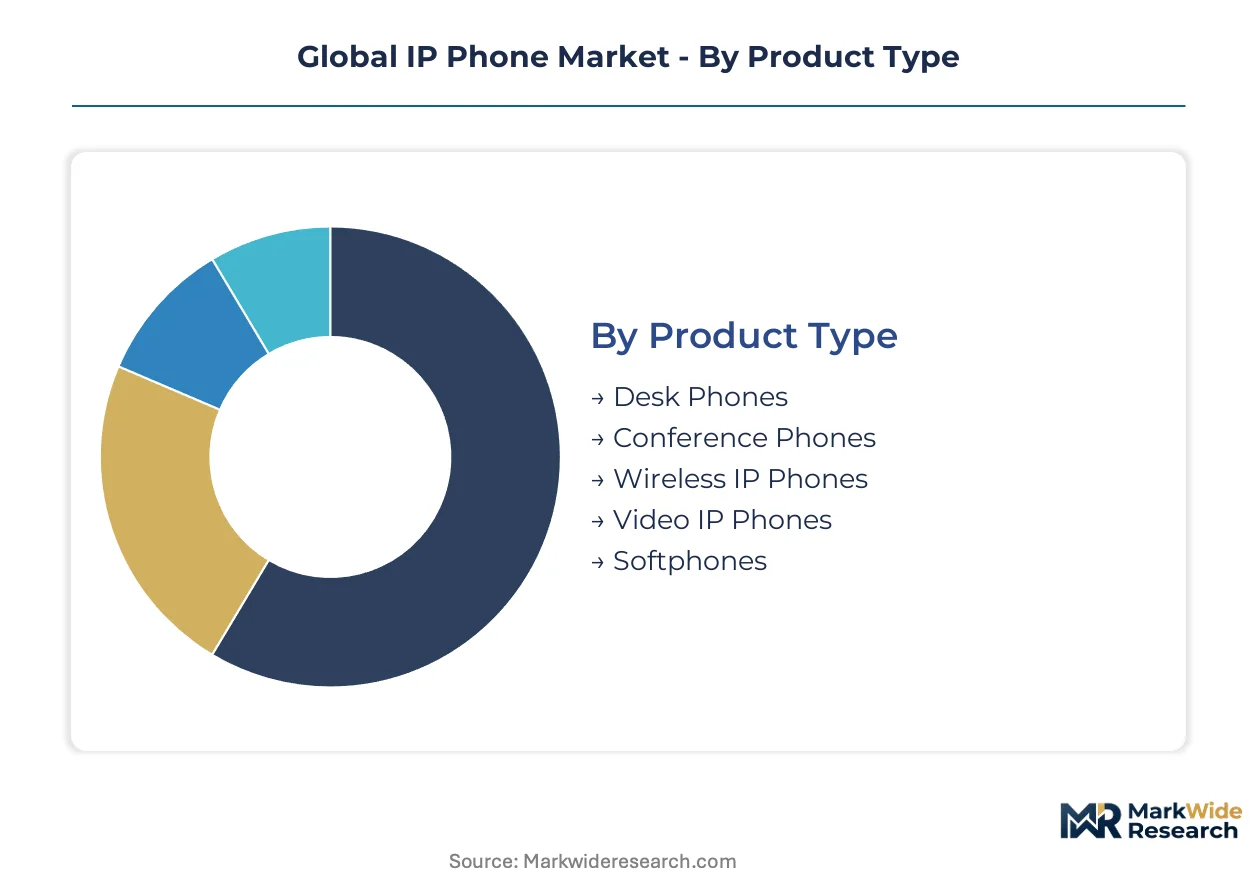
IP phone segmentation reveals how hardware refresh cycles and compliance mandates concentrate demand across distinct product tiers. Vendors calibrate R&D allocation and certification investments based on which segments command replacement urgency versus incremental expansion.
Product Type:
Enterprise upgrade trajectories diverge sharply between facility-wide hardware refreshes and software-first communications strategies.
- Desk Phones:Fixed-line endpoints with G.711/G.729 codec support and Power over Ethernet integration remain the default infrastructure choice. Large corporations in Germany and Japan drive volume as they retire decade-old analog PBX installations for cloud-UC platforms.
- Conference Phones:Multi-microphone array devices with acoustic echo cancellation and 360-degree pickup patterns serve meeting room deployments. Healthcare and education verticals in the United States face accelerated FCC E911 compliance deadlines that force hardware replacement regardless of functional age.
- Wireless IP Phones:DECT or Wi-Fi handsets enable mobility within enterprise campuses and warehouses.
- Video IP Phones:Integrated camera displays support point-to-point video calling without separate collaboration hardware.
- Softphones:Software-based endpoints running on PCs, tablets, and smartphones displace physical hardware in remote-first organizations.
Volume placements concentrate in Desk Phones; the faster expansion belongs to Softphones.
Technology:
Cost-to-performance ratios and certification overhead determine which protocol layers absorb capital expenditure versus operating budget.
- Session Initiation Protocol:Open-standard signaling protocol enabling interoperability across multi-vendor PBX and cloud-UC environments. Small and medium enterprises in mixed infrastructure settings prioritize SIP endpoints to avoid platform lock-in.
- Secure Communications:Encryption-certified hardware meeting NIST guidelines and Common Criteria evaluations for defense and financial services. These specifications command substantial margin premiums due to firmware security engineering scarcity and extended validation timelines.
- Voice over Internet Protocol:Packetized voice transmission foundation underlying all IP phone architectures.
- Power over Ethernet:Single-cable power and data delivery standard reducing installation complexity.
- HD Voice:Wideband audio codecs expanding frequency range for improved intelligibility.
Volume placements concentrate in Session Initiation Protocol; the steepest margin expansion belongs to Secure Communications.
Application:
Compliance architecture and integration depth separate commodity procurement from specialized deployment categories.
- Enterprise Communication:Core voice services integrated with email, calendar, and messaging platforms across corporate headquarters and branch offices. Large corporations in the United States and Germany standardize on Microsoft Teams and Zoom Phone stacks that mandate certified endpoint hardware.
- Customer Contact Centers:Agent workstations requiring CRM integration, call queuing, and real-time analytics. GDPR consent mechanisms in France and Germany impose firmware complexity for call recording functionality.
- Remote Work Communications:Distributed employee connectivity spanning home offices and co-working locations.
- Unified Communications:Consolidated voice, video, and messaging on single platforms.
- Call Recording:Regulatory compliance and quality assurance capture requirements.
Volume placements concentrate in Enterprise Communication; the fastest technology shift belongs to Remote Work Communications.
End User:
Procurement authority and budget cycles fragment the addressable market across distinct buying centers with divergent technical requirements.
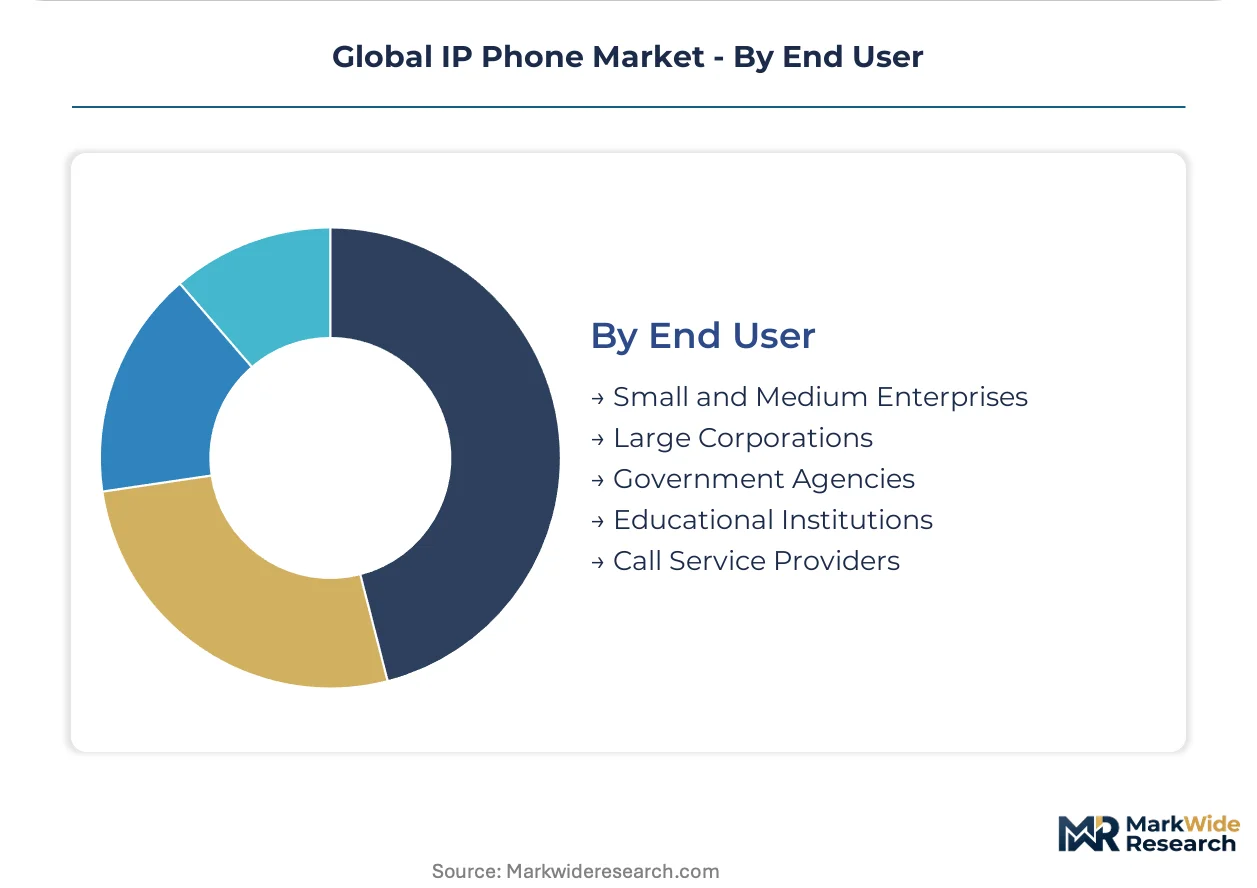
- Large Corporations:Centralized IT procurement with dedicated telephony teams managing thousand-plus endpoint deployments. These buyers negotiate enterprise licensing and demand five-year firmware support commitments under EU Cyber Resilience Act timelines.
- Government Agencies:Public sector procurement with security clearance and domestic content requirements. India's PLI scheme for telecom equipment creates localized manufacturing preferences for TRAI-mandated IP interconnection upgrades.
- Small and Medium Enterprises:Owner-operated purchasing decisions prioritizing upfront cost over lifecycle management.
- Educational Institutions:Campus-wide deployments with E911 location accuracy mandates and emergency notification integration.
- Call Service Providers:Wholesale endpoint provisioning for hosted PBX and SIP trunking resale.
Volume placements concentrate in Large Corporations; the procurement momentum is shifting fastest toward Call Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Jose anchors North American IP phone engineering density, while Shenzhen manufacturing corridors supply component ecosystems for global assembly networks. Enterprise cloud-UC procurement concentrates in three metropolitan corridors.
United States
FCC E911 mandates drive hardware replacement cycles across healthcare and education verticals with accelerated compliance deadlines. HIPAA frameworks constrain data processing architectures for call recording applications in medical settings. San Jose engineering clusters develop GPS-integrated positioning chipsets for location accuracy certification.
Germany
GDPR consent mechanisms increase firmware complexity for enterprise call recording deployments in Frankfurt financial centers. CE marking requirements and EU Cyber Resilience Act timelines mandate five-year firmware support commitments from hardware vendors. Bavarian manufacturing hubs assemble SIP endpoints for Microsoft Teams and Zoom Phone standardization projects.
Japan
METI industrial standards and healthcare integration requirements create specialized endpoint categories with HL7 and DECT convergence. Kanto region enterprises lead cloud-UC deployment cycles with centralized IT procurement managing thousand-plus endpoint rollouts. Tokyo metropolitan hospitals demand nurse call system interoperability with electronic health record platforms.
India
TRAI-mandated IP-based interconnection upgrades and PLI scheme incentives for telecom equipment create localized manufacturing preferences. Bangalore IT corridors drive enterprise modernization as public sector procurement shifts toward domestic content requirements. Maharashtra industrial zones host assembly operations for cost-optimized SIP endpoint production.
South Korea
Semiconductor fabrication concentration in Hsinchu-linked supply chains exposes voice processing DSP lead times to foundry allocation decisions. Seoul Capital Area enterprises adopt Android-based open-platform devices to avoid vendor lock-in in unified communications stacks. Busan-Ulsan logistics hubs manage component distribution for Asia-Pacific assembly networks.
Global IP Phone Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification overhead and security engineering depth. The vendor base organizes into three tiers: enterprise-grade manufacturers with established security operations centers, cost-optimized volume producers leveraging contract manufacturing, and open-standard specialists navigating multi-vendor interoperability demands. Strategic consolidation centers on M&A activity for security certification capabilities and geographic expansion through channel partner acquisition.
Within the premium-tier vector, Cisco Systems and Alcatel-Lucent Enterprise exemplify enterprise-grade positioning through Webex-integrated portfolios and established security operations infrastructure. Yealink occupies a position within the cost-optimized volume tier, leveraging Shenzhen-based manufacturing scale for small and medium enterprise channel penetration. Grandstream Networks represents the open-standard specialist archetype, focusing on SIP interoperability across mixed-vendor deployment environments.
| Leading Market Players |
|---|
| Alcatel-Lucent Enterprise |
| Yealink |
| Cisco Systems |
| NEC |
| Grandstream Networks |
| Avaya |
| Huawei Technologies |
| Polycom |
| Mitel |
| Others |
Supply & Pricing Matrix
Large corporation procurement teams with centralized IT budgets dominate volume purchasing and enforce subscription-based pricing models that bundle hardware with per-seat SaaS commitments. This buyer concentration compresses upfront hardware margins while extending vendor revenue recognition across multi-year service contracts. FCC E911 compliance certification creates tiered cost structures that separate premium-positioned manufacturers from cost-optimized competitors serving price-sensitive small and medium enterprise channels.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and security certification tiers separates premium enterprise-grade hardware from commoditized entry-level devices. Three-tier pricing structure across premium, standard, and economy levels reflects NIST cybersecurity validation overhead and EU Cyber Resilience Act firmware support commitments. Cost compression in the mid-market tier intensifies because Android-based open-platform devices eliminate proprietary R&D duplication. Small and medium enterprises exhibit highest price sensitivity, while government agencies and defense contractors accept substantial premiums for Common Criteria-certified endpoints.
Supply Chain Analysis
Trans-Pacific freight cost volatility and semiconductor logistics complexity shape inventory positioning strategies for voice processing DSP and gigabit Ethernet PHY components. Component fabrication concentrates in Taiwan, South Korea, and China, with final assembly drawing from Shenzhen manufacturing corridors and Bavarian industrial hubs. Single-source vulnerability in foundry allocation for specialized voice processors exposes lead times to geopolitical friction. Distribution runs through managed service providers and channel partners rather than direct enterprise sales, shifting working capital requirements downstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global IP Phone Market operates as a cost-of-compliance story where FCC E911 mandates and EU Cyber Resilience Act timelines erect barrier-to-entry moats favoring established security operations centers over cost-optimized entrants.
For Market Incumbents: Cement certification leadership by accelerating NIST post-quantum cryptography integration ahead of guideline finalization, while acquiring channel partners in India and Germany to capture PLI scheme benefits and GDPR-compliant service bundling. Softphone substitution in remote-first technology sectors threatens desk phone volumes, demanding defensive portfolio expansion into Android-based open-platform devices. For New Entrants and Emerging Players: Managed service providers represent the most penetrable channel archetype for white-label endpoint provisioning without direct Cisco or Yealink competition. Target India's public sector modernization under TRAI-mandated IP interconnection upgrades, where domestic content requirements disadvantage established multinational vendors. A hardware-as-a-service financing model bypasses capital expenditure constraints that freeze small and medium enterprise procurement decisions. For Investors and Strategic Acquirers: The window for entry favors security certification specialists with established Common Criteria evaluation pipelines and embedded firmware engineering depth. Long-term viability hinges on five-to-ten year firmware maintenance capabilities under EU regulatory timelines. Watch for NIST post-quantum cryptography guideline publication as the inflection signal triggering accelerated replacement cycles in defense and financial services verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Certification | NIST guideline alignment commands 40-60% margin premiums in defense deployments. |
| Android Open-Platform Development | Modular architecture avoids vendor lock-in for Germany and Japan enterprises. |
| India PLI Localization | Domestic assembly qualifies for TRAI-mandated public sector procurement preferences. |
| Managed Service Provider Channel Acquisition | Per-seat SaaS bundling shifts capital expenditure to operational models in United States. |
| Healthcare Integration Convergence | HL7 and DECT interoperability creates specialized endpoint categories in Japan and United States. |
Research Methodology
SEC filings, FCC equipment authorization databases, and EU CE marking registries formed the secondary backbone for vendor positioning and certification timeline analysis. Primary interviews with unified communications platform engineers, enterprise IT procurement directors, and channel partner sales executives validated hardware refresh cycle assumptions and pricing model evolution. Bottom-up endpoint shipment estimates triangulated against top-down cloud-UC platform deployment disclosures from Microsoft and Zoom.
Historical trendline analysis of PBX migration patterns and cloud-UC adoption curves informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, technology protocol, application vertical, and end-user procurement authority dimensions. CAGR derivation rested on SIP endpoint penetration rates, softphone displacement velocity, and regulatory compliance deadline clustering in healthcare and education verticals.
Caveats apply where semiconductor foundry allocation disruptions or accelerated NIST post-quantum cryptography standard publication could materially shift the outlook. Forecasts reflect assumptions about enterprise cloud migration velocity and regulatory enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Tetra Terminals Market
Telecommunications
5G Connections Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
Chile Telecom Market
Telecommunications
Smart SIM Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Telecom API Platform Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Belgium ICT Market
Telecommunications
Mobile Fronthaul and Backhaul Market
Telecommunications
Norway Telecom Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
Cambodia ICT Market