
 IOT in Aviation Market | 2026-2036
IOT in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
IOT in Aviation Market Analysis
The performance gap between premium sensor-embedded avionics and commodity tracking hardware is hardening as airlines prioritize predictive maintenance over basic location monitoring. Honeywell International Inc. leverages its integrated flight deck ecosystem to dominate high-margin connected aircraft retrofits. Cisco Systems, Inc. competes through ruggedized networking infrastructure that sustains uptime across harsh tarmac environments. Thales Group anchors European demand with cybersecurity-hardened communication systems that meet stringent airworthiness protocols.
IoT in aviation encompasses networked sensor arrays, edge computing nodes, and cloud analytics platforms that transmit real-time operational data from aircraft systems, ground equipment, and cargo containers to centralized decision engines. These systems typically operate across 1090 MHz Extended Squitter and satellite L-band frequencies, processing telemetry streams at sub-second latency to enable automated fault detection and route optimization. Predictive maintenance applications within the application dimension are capturing disproportionate investment as carriers seek to minimize aircraft-on-ground incidents and extend engine shop visit intervals. Sensor networks within the technology dimension are maturing fastest, with RFID and GPS transitioning toward standardized commodity components while cloud computing architectures absorb the bulk of new software spending.
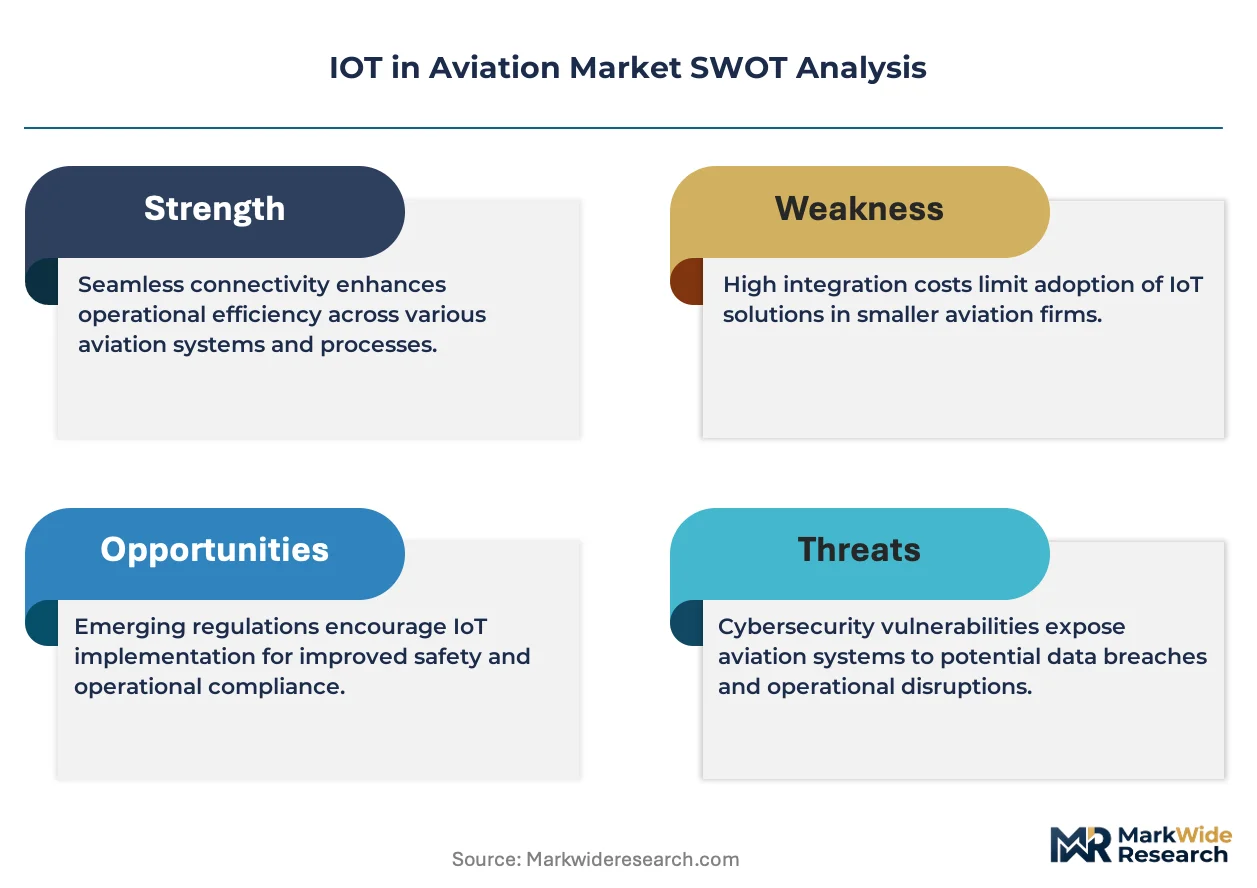
The FAA's airworthiness directives on continuous engine health monitoring and EASA's certification requirements for connected avionics under CS-25 are reshaping supplier qualification pathways and procurement timelines. ICAO's Global Aeronautical Distress and Safety System standards further compel fleet-wide connectivity upgrades for transoceanic operators. Stakeholders must weigh the capital intensity of full-stack platform deployment against modular point solutions that preserve interoperability across mixed-vendor environments.
Market Dynamics
Airlines face mounting pressure to retrofit aging narrow-body fleets with sensor networks before FAA airworthiness directives mandate real-time engine health monitoring across all Part 121 operations. This retrofit imperative is compressing procurement timelines and forcing carriers into accelerated vendor qualification cycles.
Growth Catalysts
- FAA Continuous Engine Health Monitoring Mandate:The directive compels Part 121 carriers to install real-time telemetry systems on turbofan engines above 33,000 pounds thrust, creating immediate retrofit demand across the installed base of Boeing 737NG and Airbus A320ceo aircraft.
- Extended Squitter (1090ES) Infrastructure:Ground station densification across the continental United States enables sub-second latency for automated fault detection, reducing aircraft-on-ground incidents by enabling predictive dispatch decisions.
- Engine Shop Visit Interval Extension:Carriers including Delta and United prioritize sensor-embedded retrofits that stretch time-between-overhauls, directly lowering unit maintenance costs per flight hour.
Market Restraints
- Avionics-Grade Sensor Cost Volatility:MEMS pressure transducers and fiber-optic strain gauges face supply concentration in Japanese and German component foundries, exposing procurement budgets to yen-euro exchange rate swings.
- Certification Timeline Friction:FAA Supplemental Type Certificate approval for connected retrofits averages 18-24 months, freezing fleet-wide deployment schedules and deferring revenue recognition for system integrators.
- Legacy ARINC 429 Bus Architecture:Pre-2010 aircraft lack sufficient data bandwidth to support full-stack predictive maintenance platforms, forcing expensive wiring harness replacements or performance-limited edge node workarounds.
Strategic Opportunities
- EASA CS-25 Connected Avionics Certification Pathway:The framework creates a streamlined equivalence route for FAA-approved systems, opening transatlantic retrofit opportunities for US-originated sensor platforms without redundant testing.
- Cargo Container Telemetry White Space:Temperature-controlled ULDs (unit load devices) remain underpenetrated by real-time tracking, with pharmaceutical and perishables lanes driving demand for cold-chain-validated IoT endpoints.
- Edge-to-Cloud Architecture Convergence:Pairing NVIDIA Jetson-class onboard inference with AWS Ground Station downlinks enables fault prediction without continuous satellite connectivity, reducing recurring data costs for regional carriers.
Industry Challenges
- Airworthiness Directive Synchronization Lag:FAA and EASA issue divergent compliance timelines for equivalent safety-critical systems, forcing dual-certification strategies that strain engineering resources and delay fleet-wide harmonization.
- Legacy FMS Integration Complexity:Flight management computers from the 1990s lack native APIs for sensor data ingestion, requiring middleware development that extends retrofit downtime and raises non-recurring engineering costs per aircraft.
- Cybersecurity Skill Scarcity:Airlines struggle to hire avionics security engineers familiar with DO-326A airworthiness security process specifications, slowing connected fleet deployments despite available hardware budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IOT in Aviation Market |
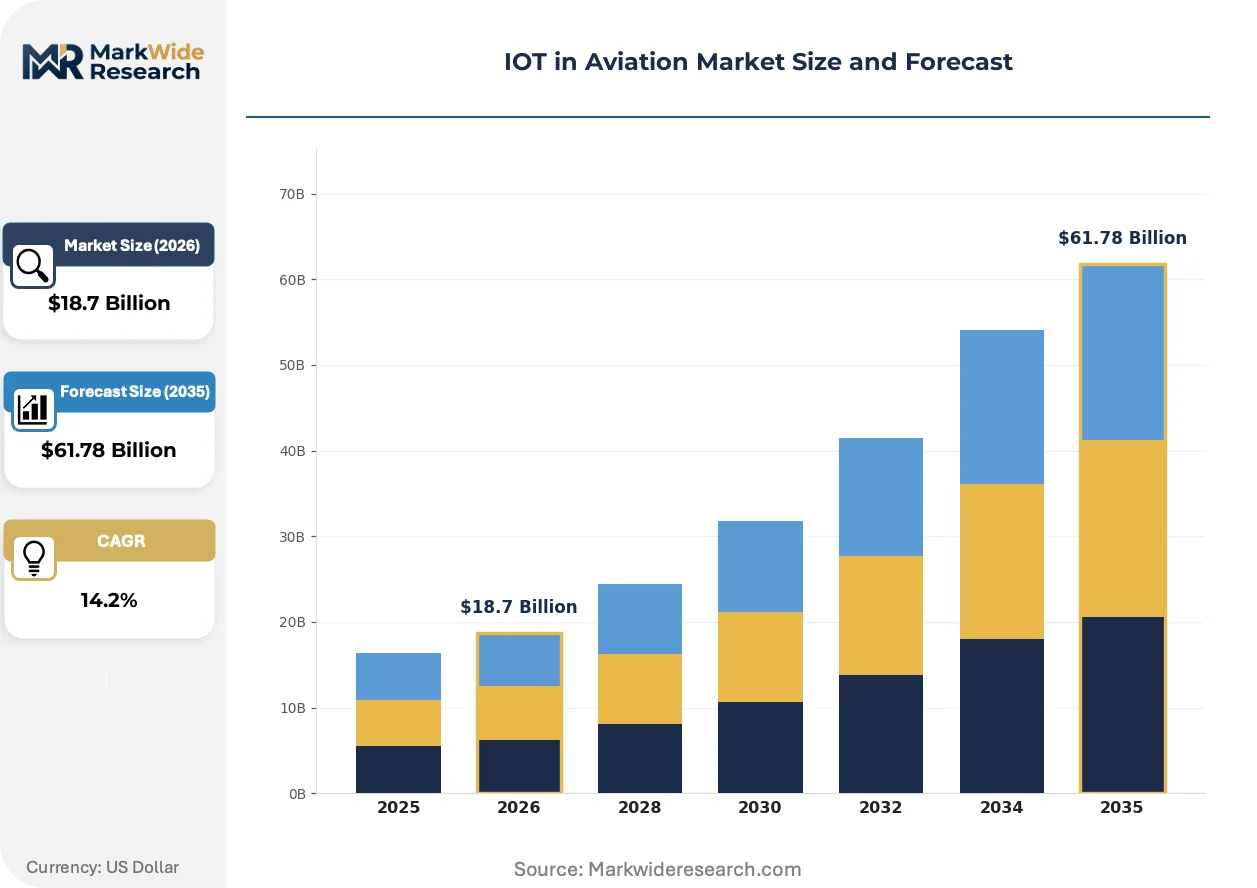
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, GPS, Sensor Networks, Cloud Computing Application: Flight Tracking, Predictive Maintenance, Cargo Management, Surveillance End User: Airlines, Airports, Maintenance Providers, Cargo Operators Solution: Data Analytics, Communication Systems, Security Solutions, Navigation Tools |
| Companies Covered | Honeywell International Inc., Cisco Systems, Inc., IBM Corporation, Thales Group, Collins Aerospace, GE Aerospace, SITAONAIR, Huawei Technologies Co., Ltd., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IOT in Aviation Market Emerging Trajectories
Edge computing architectures are displacing centralized cloud processing for latency-critical fault detection, while regulatory mandates force standardization of data formats across previously proprietary avionics ecosystems. These shifts are compressing supplier margins and rewarding full-stack platform vendors.
Digital twin technology is decentralizing maintenance planning from centralized MRO facilities to line stations. Airlines including United deploy physics-based engine models that simulate component degradation using live sensor feeds, enabling turn-time maintenance decisions without removing powerplants. This capability is compressing the competitive advantage of traditional engine OEM service networks.
EASA's CS-25 Certification Memorandum on connected avionics mandates end-to-end encryption for all safety-critical data links. European carriers must retrofit previously certified systems with AES-256 modules, accelerating hardware refresh cycles. Thales and Honeywell dominate this compliance-driven replacement market with pre-certified integrated solutions.
After-sales service unbundling is fragmenting long-term MRO contracts. Carriers now procure sensor hardware, analytics software, and predictive algorithms from separate vendors, forcing incumbents to defend attachment rates through API interoperability rather than bundled pricing. This pattern is most visible among US ultra-low-cost carriers retrofitting used aircraft acquisitions.
IOT in Aviation Market Segmentation
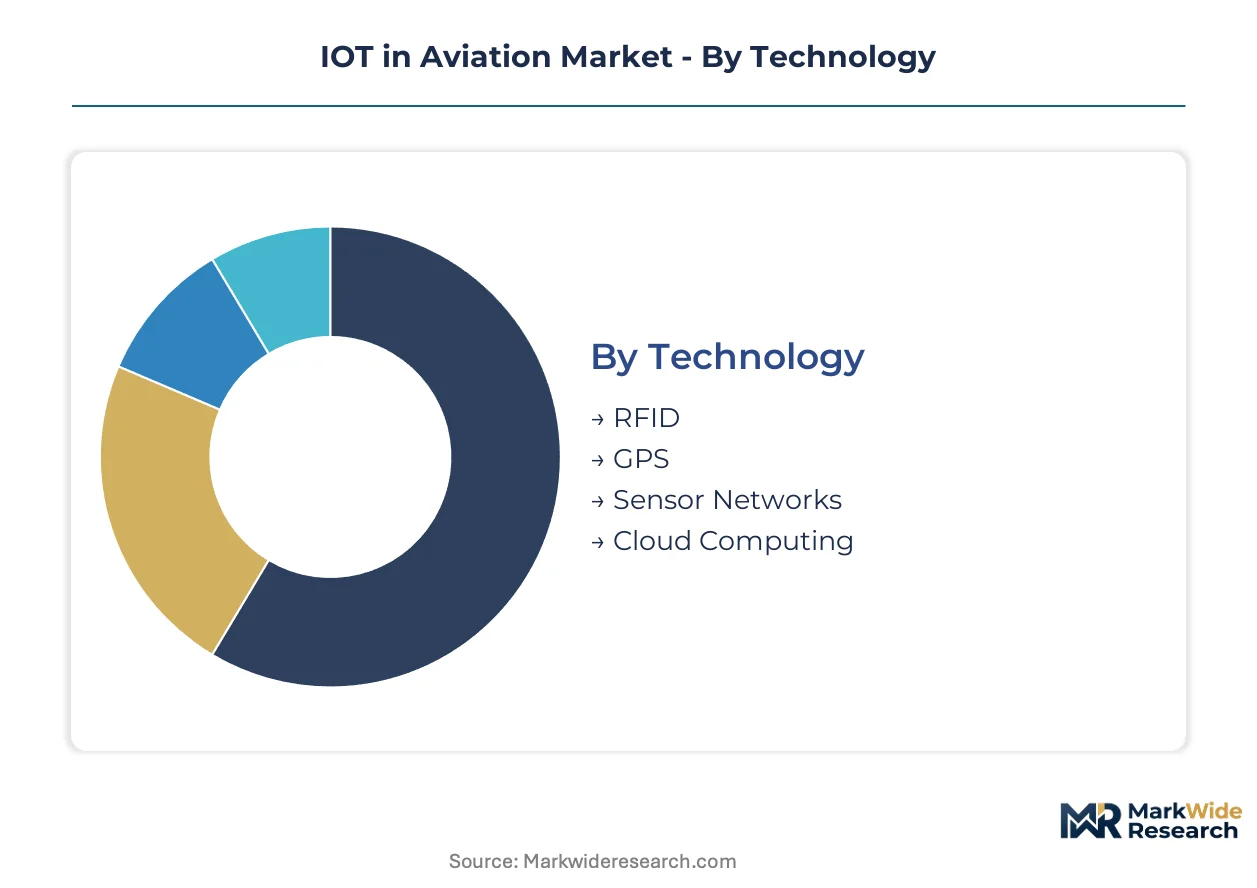
IoT deployment strategies diverge sharply across aviation subsectors, with sensor density, connectivity architecture, and regulatory exposure varying by operational context. Procurement patterns reflect these differences: carriers prioritize engine telemetry, airports invest in tarmac automation, and cargo operators chase cold-chain validation.
Technology:
Cost tier separates adopters in this category, with premium avionics-grade components commanding multiples over commodity hardware.
- Sensor Networks:Fiber-optic strain gauges and MEMS pressure transducers form the sensing layer for engine health monitoring and structural fatigue detection. Demand concentrates among US Part 121 carriers retrofitting narrow-body fleets to meet FAA continuous monitoring mandates, with supply concentration in Japanese and German component foundries creating currency exposure.
- Cloud Computing:Distributed data lakes and inference engines process terabyte-scale telemetry streams from connected aircraft. United and Delta anchor North American demand for hybrid architectures that balance edge latency against centralized model training, driven by predictive maintenance ROI targets.
- RFID:Passive and active tags track ground equipment, life-limited components, and unit load devices through 860-960 MHz UHF bands.
- GPS:Multi-constellation receivers provide position, navigation, and timing data fused with inertial reference systems.
Volume sits with Sensor Networks; growth tilts toward Cloud Computing.
Application:
Margin profiles differentiate this category, with predictive maintenance capturing disproportionate software attach rates against commoditized tracking functions.
- Predictive Maintenance:Physics-based digital twins and machine learning models forecast component failures from vibration, temperature, and oil debris signatures. Engine shop visit interval extension drives carrier investment, with Delta deploying live sensor feeds to compress turn-time maintenance decisions without powerplant removal.
- Flight Tracking:1090 MHz Extended Squitter and satellite L-band transponders transmit position and intent data for air traffic management and distress alerting. ICAO Global Aeronautical Distress and Safety System standards compel transoceanic fleet upgrades, with ground station densification across the continental United States enabling sub-second latency.
- Cargo Management:Temperature, humidity, and shock sensors monitor pharmaceutical and perishables lanes through cold-chain-validated endpoints.
- Surveillance:Integrated sensor suites support ground proximity warning, traffic collision avoidance, and unauthorized access detection.
Revenue concentrates in Predictive Maintenance; expansion accelerates fastest in Cargo Management.
End User:
Maturity stage separates buyers, with airlines leading connected fleet deployment while cargo operators lag in sensor penetration.
- Airlines:Network carriers and ultra-low-cost operators retrofit installed bases with engine telemetry, flight deck connectivity, and cabin management systems. FAA airworthiness directives on continuous health monitoring compress procurement timelines for Boeing 737NG and Airbus A320ceo fleets.
- Airports:Terminal operators and ground handlers deploy tarmac sensor networks for equipment tracking, gate allocation optimization, and foreign object debris detection.
- Maintenance Providers:MRO facilities integrate incoming telemetry streams with hangar execution systems to pre-position parts and labor.
- Cargo Operators:Freight carriers and express integrators instrument unit load devices and container fleets for real-time condition monitoring.
Deployment depth favors Airlines; investment momentum builds in Airports.
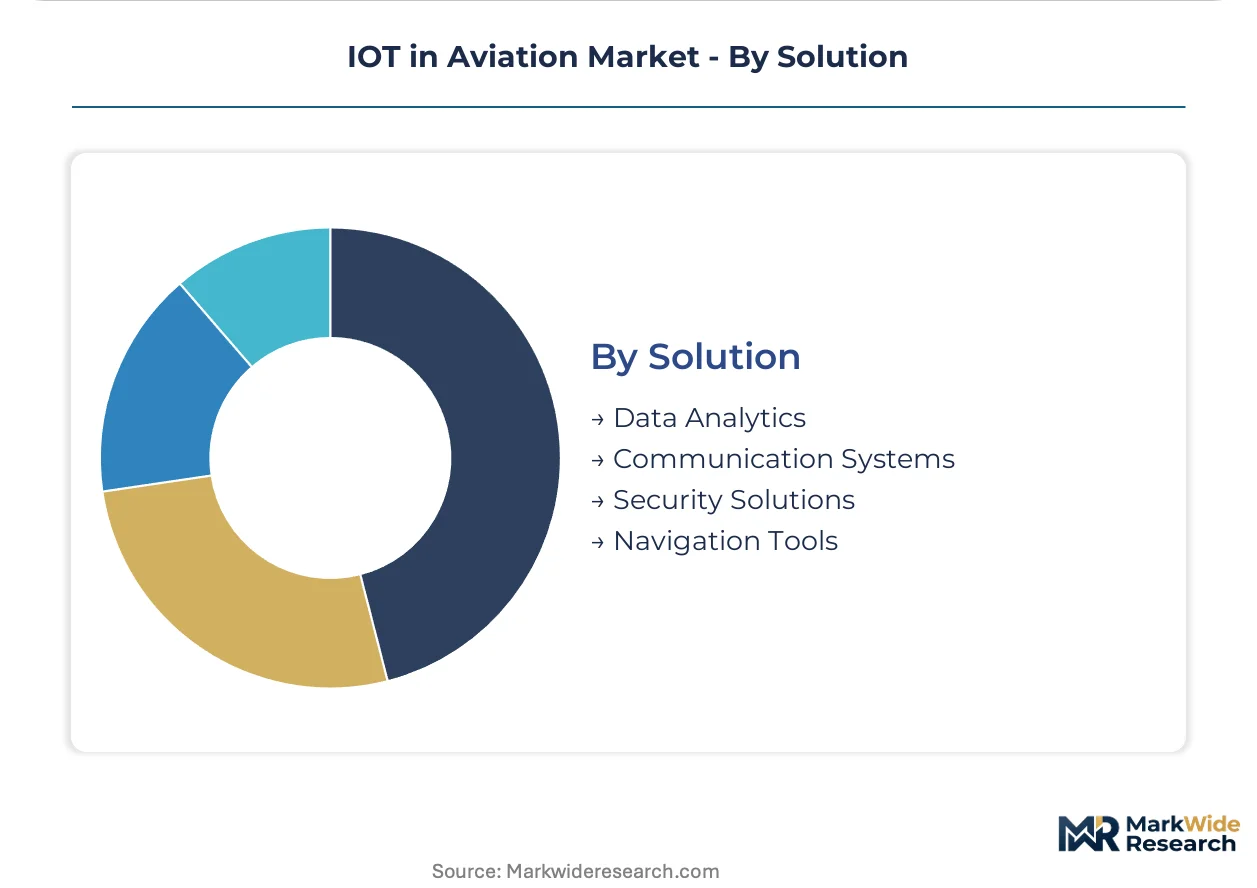
Solution:
Supply concentration shapes competitive dynamics, with integrated platform vendors defending position against modular point-solution challengers.
- Data Analytics:Predictive algorithms, visualization dashboards, and automated alerting engines translate raw telemetry into maintenance decisions and operational optimizations. After-sales unbundling fragments procurement, with carriers sourcing hardware, software, and algorithms from separate vendors.
- Communication Systems:Ruggedized networking infrastructure sustains connectivity across harsh tarmac environments and pressurized cabin conditions. EASA CS-25 mandates for end-to-end encryption accelerate hardware refresh cycles among European carriers.
- Security Solutions:Cryptographic modules, intrusion detection, and access control systems protect safety-critical data links under DO-326A airworthiness security specifications.
- Navigation Tools:Augmented positioning and route optimization applications fuse multi-source sensor data for fuel efficiency and schedule recovery.
Attachment rates favor Data Analytics; compliance spending elevates Security Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors North American IoT aviation deployment through Boeing's engineering corridor and Alaska Airlines' connected fleet operations. The metropolitan cluster concentrates sensor integration labs, cloud analytics development, and FAA certification facilities that shape procurement patterns across the continent.
United States
Delta and United drive narrow-body retrofit demand as Part 121 carriers race to meet FAA continuous engine health monitoring mandates. The FAA's airworthiness directives on real-time turbofan telemetry compress vendor qualification timelines to 18-month cycles. Dallas-Fort Worth hosts the densest concentration of MRO facilities integrating predictive maintenance platforms with legacy Boeing 737NG fleets.
Germany
Lufthansa Group's sensor-embedded A320neo operations establish the European benchmark for predictive maintenance ROI. EASA CS-25 certification requirements for connected avionics under end-to-end encryption protocols accelerate hardware refresh cycles. Hamburg's aviation manufacturing corridor concentrates Thales and Airbus engineering resources for cybersecurity-hardened communication systems.
China
COMAC's C919 production ramp drives indigenous sensor network development for domestic fleet connectivity. MIIT standards for civil aviation IoT data security impose localization requirements on cloud analytics architectures. Shanghai's Pudong aerospace zone hosts joint ventures between Chinese carriers and foreign system integrators adapting platforms for GB-compliant certification pathways.
United Arab Emirates
Emirates and Etihad prioritize cargo container telemetry for pharmaceutical cold-chain lanes through Dubai's transhipment hub. The General Civil Aviation Authority mandates ADS-B Out compliance for all registered aircraft operating above FL290. Dubai South's logistics corridor attracts IoT endpoint manufacturers targeting perishables tracking across African and South Asian trade routes.
Japan
ANA and JAL deploy fiber-optic strain gauges for structural health monitoring on domestic narrow-body routes. METI's aviation digitalization subsidies offset retrofit costs for regional carriers operating aging Bombardier and Embraer fleets. Nagoya's Chubu aerospace cluster concentrates MEMS pressure transducer foundries supplying sensor networks to Asian MRO facilities.
IOT in Aviation Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification grade and integration depth, with full-stack platform vendors capturing software attach rates that modular hardware suppliers cannot match. The market structures around three tiers: integrated avionics OEMs with captive airworthiness certification, networking infrastructure specialists with ruggedized tarmac solutions, and point-solution sensor vendors facing commoditization pressure. Strategic moves concentrate on M&A for cybersecurity capabilities and API interoperability partnerships that preserve mixed-vendor fleet architectures.
Within the integrated avionics tier, Honeywell International Inc. and Thales Group exemplify platform vendors defending position through pre-certified connected flight deck ecosystems. Cisco Systems, Inc. anchors the networking infrastructure segment with enterprise-grade hardware adapted for aviation environmental standards. IBM Corporation occupies a position bridging legacy system integration with cloud-native analytics architectures. These three company structures—US conglomerate, French multinational, and US technology corporation—represent the dominant competitive archetypes shaping procurement negotiations with global carriers.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Cisco Systems, Inc. |
| IBM Corporation |
| Thales Group |
| Collins Aerospace |
| GE Aerospace |
| SITAONAIR |
| Huawei Technologies Co., Ltd. |
| Microsoft Corporation |
| Others |
Supply Flow & Price Mechanics
Avionics-grade certification tiers bifurcate procurement economics, with FAA Supplemental Type Certificate holders commanding premium positioning against commodity sensor vendors locked in price-based competition. This divergence manifests in supply chain configurations where Japanese MEMS foundries and German fiber-optic component houses anchor high-reliability tiers, while Taiwanese contract manufacturers feed cost-optimized tracking hardware segments.
Pricing Analysis
Value-based pricing anchors on aircraft-on-ground avoidance and engine shop visit interval extension outcomes, with carriers paying subscription tiers tied to predictive accuracy rather than hardware unit costs. Price differentiation hinges on DO-178C software certification grade and ARINC 664 network integration depth. Cost compression in commodity RFID and GPS modules intensifies as standardized 1090ES receivers flood the aftermarket. Ultra-low-cost carriers exhibit highest price sensitivity, while network carriers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
FAA and EASA airworthiness qualification gates concentrate component supply among pre-certified Japanese MEMS pressure transducer foundries, German fiber-optic strain gauge manufacturers, and US-based DO-178C software houses. Raw material dependencies include rare-earth elements for avionics-grade magnetometers, high-purity silicon for MEMS substrates, and specialized optical fibers for engine monitoring. Single-source vulnerability in Japanese MEMS supply exposes procurement budgets to yen volatility and geopolitical disruption. Distribution runs through tier-one system integrators holding STC approvals, with direct OEM relationships dominating fleet-wide retrofit contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where sensor hardware, edge computing, and cloud analytics capabilities are being consolidated under single-vendor platforms to capture software attach rates and compress certification timelines.
For Market Incumbents: Deploy API interoperability investments to defend installed base position against modular challengers fragmenting procurement. Lock in FAA STC pipeline advantages through accelerated certification programs for mixed-vendor fleet architectures. Counter cybersecurity-native entrants by acquiring DO-326A specialist engineering teams before talent scarcity hardens. For New Entrants and Emerging Players: Regional MRO partnerships offer the fastest channel to fleet penetration without STC development burdens. Target cargo container telemetry white space in pharmaceutical cold-chain lanes where validation requirements remain unsettled. Pursue edge-to-cloud architecture convergence plays pairing NVIDIA-class inference with satellite downlink alternatives to undercut incumbent data cost structures. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation toward full-stack avionics vendors with captive certification capabilities. Long-term viability favors suppliers integrating sensor hardware with predictive algorithm development rather than pure-play component manufacturers facing commoditization. Watch FAA-EASA airworthiness directive synchronization as the critical inflection signal—harmonized compliance timelines would accelerate fleet-wide deployment velocity and revalue certification backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combines sensor hardware, edge computing, and cloud analytics under unified STC approvals. |
| Cybersecurity Capability Acquisition | Addresses DO-326A engineering scarcity slowing connected fleet deployments at major carriers. |
| Cargo Telemetry Specialization | Captures underpenetrated pharmaceutical cold-chain validation requirements in express networks. |
| Regional MRO Partnership | Accelerates fleet penetration without 18-24 month FAA certification timeline exposure. |
| API Interoperability Investment | Preserves mixed-vendor architecture positioning against bundled platform consolidation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across avionics procurement directors, FAA certification engineers, airline fleet management executives, and MRO integration specialists. FAA airworthiness directive databases, EASA certification memoranda, ICAO GADSS implementation reports, and carrier 10-K fleet disclosure filings supplied quantitative foundations. Bottom-up sensor deployment estimates triangulated against top-down connected aircraft penetration forecasts.
Granularity-level modeling disaggregated the market across technology tiers, application maturity stages, end-user operational contexts, and solution integration depths throughout the projection horizon. CAGRs derived from fitted growth curves applied to retrofit cycle timing, regulatory mandate compliance windows, and fleet replacement patterns. Forecast inputs incorporated turbofan engine shop visit interval elasticity, 1090ES ground station densification trajectories, and cloud analytics architecture migration rates.
Caveats apply where FAA-EASA directive synchronization delays, MEMS component supply disruptions, or cybersecurity talent scarcity could materially shift the outlook. Forecasts reflect assumptions around regulatory timeline adherence and carrier capital allocation priorities. A model refresh is warranted upon material change in STC approval velocity or harmonized transatlantic certification pathway implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Internet of Things in Energy Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
Internet of Everything Market