
 Vehicle-To-Grid (V2G) Market | 2026-2036
Vehicle-To-Grid (V2G) Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle-To-Grid (V2G) Market Analytics
The direct-to-fleet sales channel is fragmenting as energy service providers bypass traditional automotive retail networks to contract with commercial operators. Enel X leverages its utility-scale platform to aggregate distributed EV batteries into virtual power plants across European markets. Nuvve Corporation specializes in proprietary aggregation software that enables school bus and delivery fleets to participate in wholesale electricity markets. Nissan Motor Corporation anchors the passenger vehicle segment through its long-standing CHAdeMO bidirectional standard integrated into the Leaf platform.
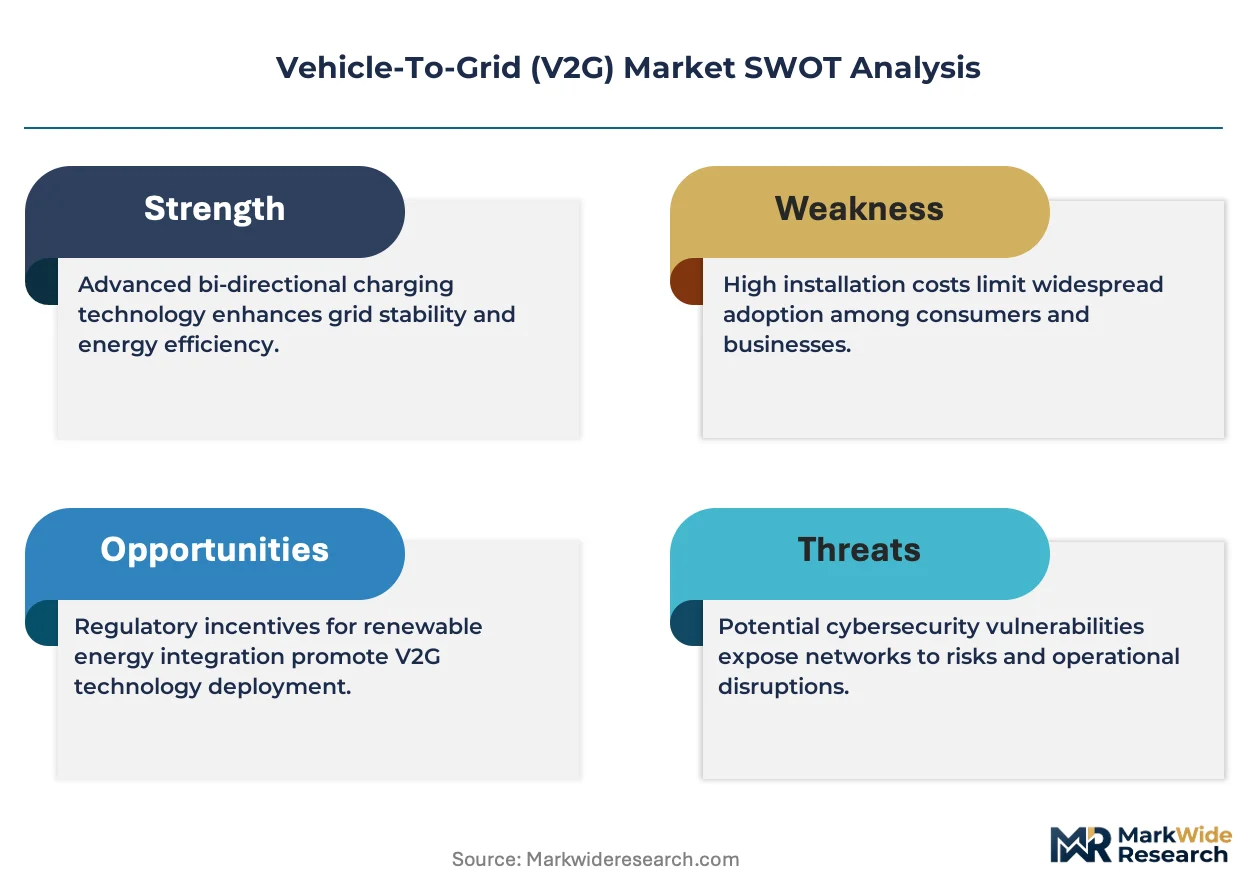
Vehicle-to-grid technology enables bidirectional energy flow between battery electric vehicles and the power grid, typically operating through AC or DC converters rated between 7 kW and 150 kW depending on installation class. The primary purpose is to treat aggregated EV batteries as decentralized storage assets that provide grid stabilization services, reduce peak demand charges, and absorb surplus renewable generation. Bidirectional charging hardware currently commands the largest share of equipment value, while energy management systems are capturing expanding margin pools as software-defined optimization becomes central to fleet economics. Frequency regulation applications lead in contracted revenue per vehicle, though renewable integration is growing fastest as solar and wind penetration rises in deregulated power markets.
The Federal Energy Regulatory Commission in the United States has issued Order 2222 to enable distributed energy resources including EVs to participate in wholesale markets, while the EU Green Deal and CE marking frameworks mandate interoperable smart charging infrastructure across member states. These regulations reshape demand by creating revenue streams for V2G participants and establishing technical standards that determine product market access. Stakeholders must monitor how national implementations of these frameworks define metering, cybersecurity, and liability requirements for bidirectional power flows.
Market Dynamics
Utility-scale aggregation platforms are compressing margins for standalone hardware vendors by bundling energy management software with bidirectional charging infrastructure, forcing equipment suppliers to defend position through vertical integration into virtual power plant orchestration.
Growth Catalysts
- FERC Order 2222:The Federal Energy Regulatory Commission's mandate enables distributed electric vehicle batteries to participate in US wholesale electricity markets, creating new revenue streams for fleet operators and accelerating V2G deployment across commercial vehicle segments.
- Frequency regulation services:Grid operators in deregulated power markets are contracting aggregated EV fleets for ancillary services, with contracted revenue per vehicle exceeding other applications due to rapid response capabilities and dispatch precision.
- German automotive clusters:OEMs and energy providers in Stuttgart and Munich are co-developing standardized V2G protocols, establishing interoperability frameworks that reduce integration friction for mass-market electric vehicle platforms.
Market Restraints
- Bidirectional converter costs:Silicon carbide power electronics and thermal management systems required for 150 kW DC V2G installations command premium pricing, compressing project returns for residential and small commercial deployments.
- CHAdeMO concentration:Nissan's proprietary bidirectional standard dominates passenger vehicle compatibility, creating dependency risk for aggregation software vendors and fleet operators standardizing on competing CCS-based hardware.
- Battery degradation uncertainty:Warranty exclusions for grid-cycling stress and limited long-term cycling data create liability gaps that deter risk-averse fleet managers from high-utilization V2G programs.
Strategic Opportunities
- School bus electrification:Predictable daytime parking patterns and large battery capacities position yellow bus fleets as ideal V2G assets, with Nuvve Corporation's aggregation software already enabling wholesale market participation across North American districts.
- EU Green Deal acceleration:The European Commission's mandate for interoperable smart charging infrastructure creates standardization tailwinds for hardware vendors and software platforms seeking cross-border scalability.
- Solar-plus-storage convergence:Integration of rooftop photovoltaic systems with bidirectional EV charging enables residential prosumers to maximize self-consumption and arbitrage time-of-use rates without standalone stationary batteries.
Industry Challenges
- Cybersecurity certification timelines:National implementations of EU CE marking and US NERC CIP frameworks are defining divergent technical requirements for bidirectional power flow authentication, delaying product launches and fragmenting engineering resources.
- Legacy fleet management integration:Telematics platforms and route optimization software used by commercial operators lack native APIs for V2G dispatch signals, requiring costly middleware development and operational workflow redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle-To-Grid (V2G) Market |
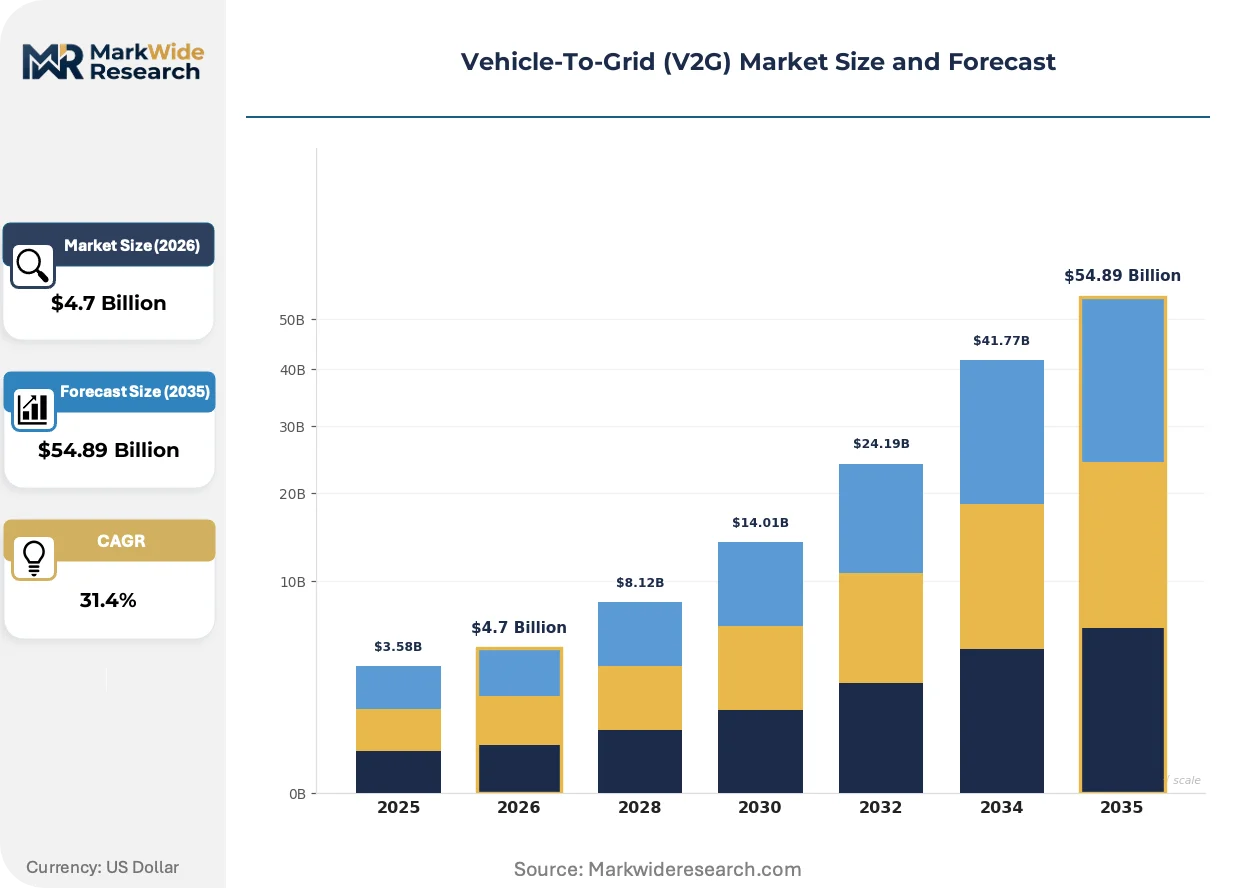
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $54.89 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bidirectional Charging, Smart Meters, Energy Management Systems, Communication Protocols End User: Residential Users, Commercial Fleets, Utility Companies, Electric Vehicle Owners Application: Frequency Regulation, Peak Load Shaving, Energy Arbitrage, Renewable Integration Installation: Onsite Charging Stations, Grid-Connected Systems, Microgrid Solutions, In-House Integrations |
| Companies Covered | Nissan Motor Corporation, Enel X, Nuvve Corporation, Groupe Renault, Mitsubishi Motors Corporation, ABB, ChargePoint, Wallbox, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle-To-Grid (V2G) Market Evolving Landscape
Software-defined optimization is displacing hardware-centric competitive differentiation, with energy management algorithms and predictive analytics capturing expanding margin pools while commoditizing power electronics.
Solid-state bidirectional converters utilizing silicon carbide semiconductors are achieving higher switching frequencies and reduced thermal losses compared to conventional IGBT architectures. Fleet operators in California and Texas are piloting 150 kW DC systems for heavy-duty electric trucks. This power density advancement is rendering obsolete the 7-22 kW AC bidirectional chargers that dominated early V2G installations.
The EU F-Gas Regulation is accelerating refrigerant transitions in thermal management systems for high-power charging hardware, compressing supplier qualification timelines for European market access. Equipment vendors are redesigning cooling loops to accommodate CO2 and hydrofluoroolefin alternatives. Bidirectional DC fast-charging stations face the most acute compliance pressure due to intensive thermal loads.
Energy service providers are disintermediating automotive retail networks by contracting directly with commercial fleet operators for turnkey V2G programs. Enel X and comparable platforms aggregate distributed assets into virtual power plants, bypassing traditional dealer service channels. This channel shift concentrates most visibly in Germany and the Netherlands where utility deregulation enables third-party energy retail.
Vehicle-To-Grid (V2G) Market Segmentation
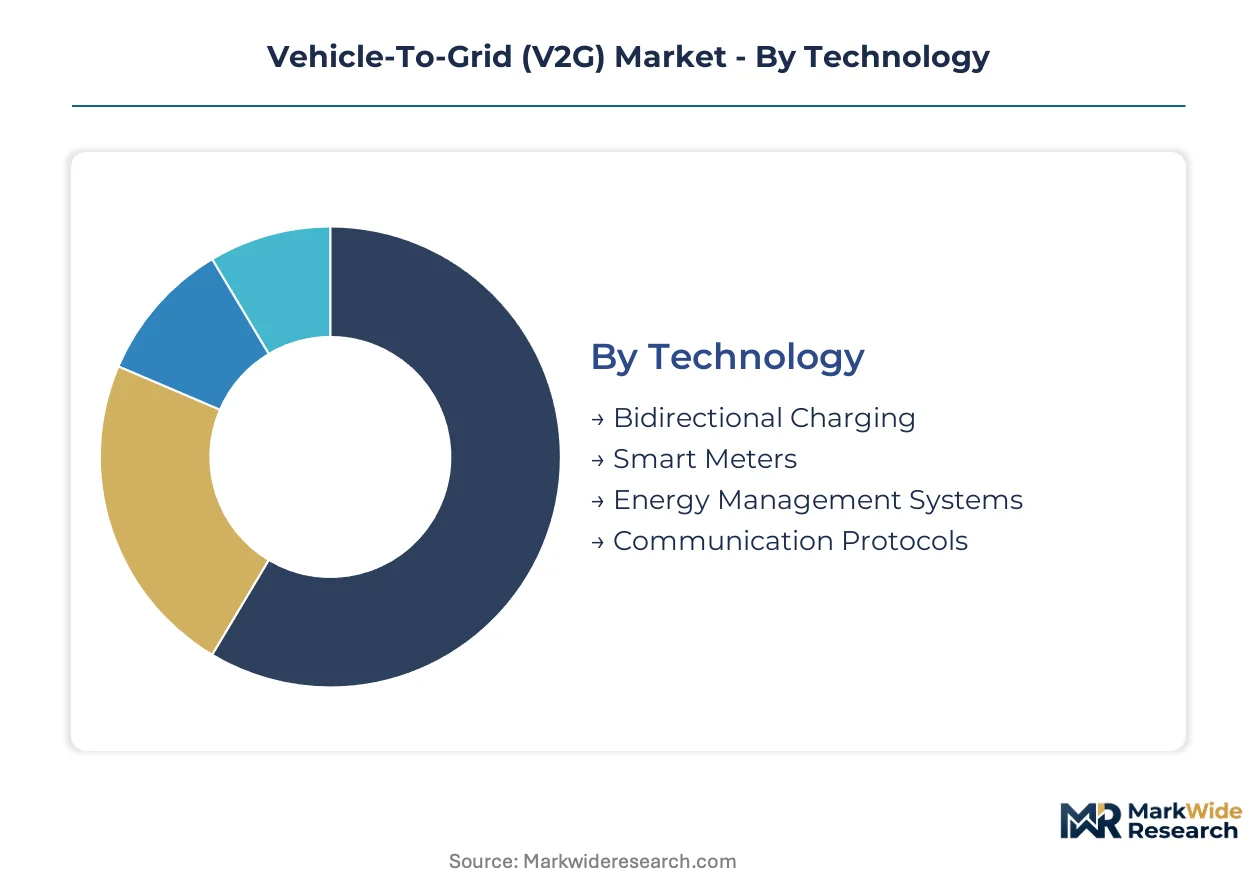
V2G market segmentation reveals how hardware, software, and service layers stack into distinct value pools with diverging margin profiles and competitive dynamics. Each category maps to specific stakeholder workflows and procurement decision-makers.
Technology:
After-sales service intensity varies sharply across technology tiers, with bidirectional charging hardware requiring field maintenance contracts and energy management systems demanding continuous software updates.
- Bidirectional Charging:Silicon carbide power electronics enable AC and DC conversion between 7 kW and 150 kW. Demand concentrates in California and Texas heavy-duty truck depots where 150 kW DC installations displace legacy AC infrastructure.
- Energy Management Systems:Predictive algorithms optimize dispatch timing and battery state-of-health monitoring. German automotive clusters in Stuttgart and Munich drive standardization requirements for OEM-integrated platforms.
- Smart Meters:Revenue-grade metering hardware with cybersecurity certification for bidirectional flow authentication. Deployment accelerates under EU CE marking mandates for interoperable infrastructure.
- Communication Protocols:ISO 15118 and CHAdeMO standards govern vehicle-grid handshaking. Compatibility gaps between Nissan's proprietary implementation and CCS-based systems create integration friction.
By volume, bidirectional charging leads. By growth pace, energy management systems are expanding most quickly.
End User:
Customer procurement sophistication spans from residential price sensitivity to utility-scale technical specification rigor.
- Commercial Fleets:School bus and delivery operators contract aggregation services for wholesale market participation. Predictable parking patterns and large battery capacities maximize grid service revenue per vehicle.
- Utility Companies:Grid operators procure virtual power plant orchestration to stabilize frequency during peak demand periods. FERC Order 2222 enables distributed EV participation in US wholesale markets.
- Residential Users:Homeowners with rooftop solar seek self-consumption optimization and time-of-use arbitrage. Bidirectional converter costs compress project returns at small scale.
- Electric Vehicle Owners:Individual drivers prioritize battery warranty preservation over grid service income. Degradation uncertainty deters high-utilization V2G enrollment.
Commercial fleets generate highest revenue per connection. Residential users show steepest expansion trajectory as equipment costs decline.
Application:
Margin capture correlates with response speed requirements and dispatch precision.
- Frequency Regulation:Sub-second response to grid operator signals commands premium contracted rates. Aggregated EV fleets in deregulated Texas and California markets capture ancillary service revenue.
- Renewable Integration:Absorption of solar and wind generation surges addresses curtailment risk. EU Green Deal acceleration in Germany and the Netherlands prioritizes this use case.
- Peak Load Shaving:Demand charge reduction for commercial facilities with high electricity tariffs. Battery degradation concerns limit utilization intensity.
- Energy Arbitrage:Time-of-use rate exploitation requires predictive price forecasting. Software-defined optimization displaces hardware-centric differentiation.
Frequency regulation dominates contracted revenue. Renewable integration is climbing the fastest as clean penetration rises.
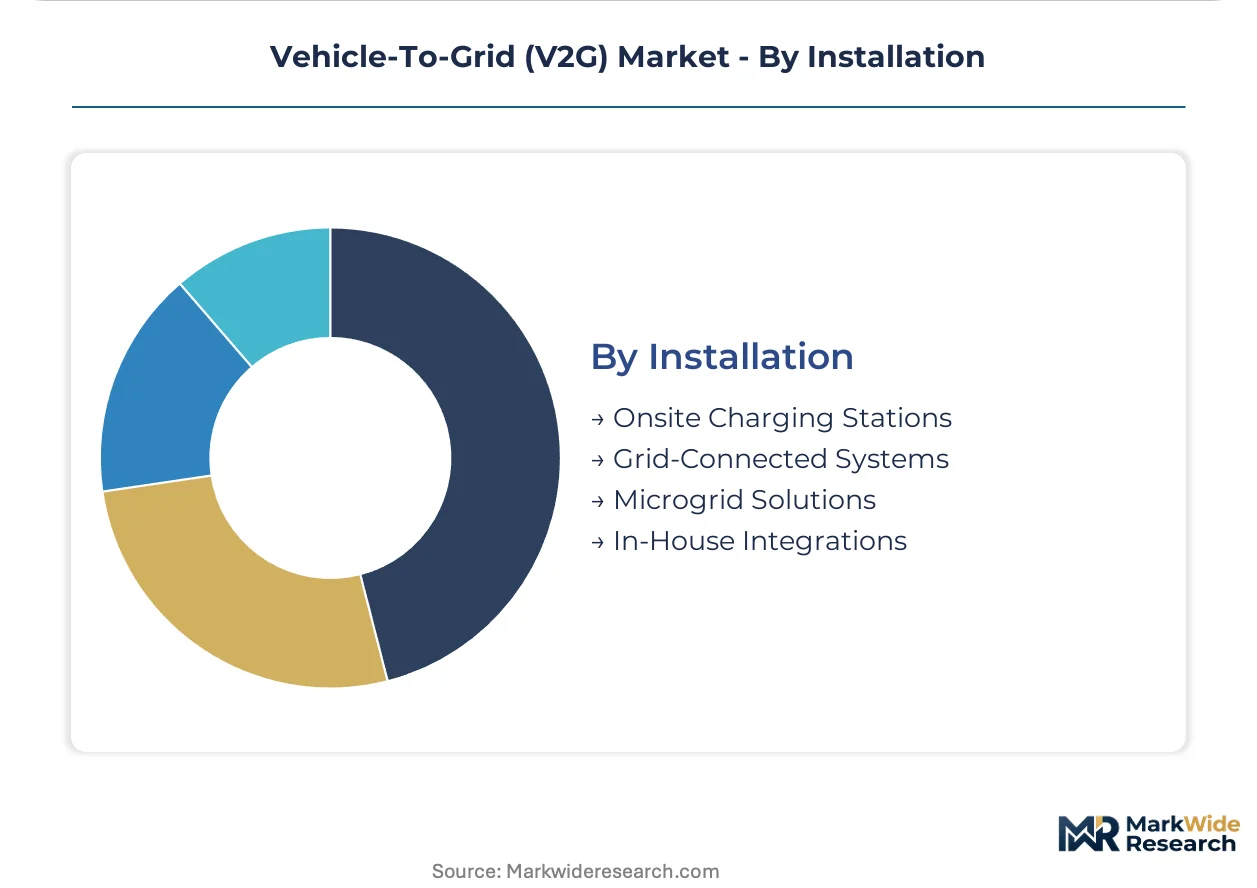
Installation:
Site preparation and interconnection complexity scale with power rating and grid integration depth.
- Onsite Charging Stations:Depot-based infrastructure for fleet operators with dedicated parking and high-voltage service. Thermal management redesigns address EU F-Gas Regulation refrigerant transitions.
- Grid-Connected Systems:Direct utility interconnection for wholesale market participation. Cybersecurity certification timelines under NERC CIP and CE marking frameworks delay deployment.
- Microgrid Solutions:Island-capable installations for resilience and backup power. Integration with stationary storage and solar arrays creates hybrid asset configurations.
- In-House Integrations:Residential garage installations with load panel upgrades and utility approval workflows. Permitting fragmentation across US municipalities extends project timelines.
Onsite charging stations lead by deployment count. Microgrid solutions are gaining share fastest in resilience-focused segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic grid interconnect capacity and North Sea offshore wind transmission corridors underwrite Europe's centrality in bidirectional charging infrastructure deployment. Utility-scale virtual power plant aggregation platforms cluster near high-voltage substations in Germany and the Netherlands. California's transmission upgrades and Texas ERCOT deregulation anchor North American frequency regulation markets.
Germany
Automotive OEMs and energy providers in Stuttgart and Munich are co-developing standardized V2G protocols for mass-market electric vehicles. The EU Green Deal and F-Gas Regulation mandate interoperable smart charging infrastructure and refrigerant transitions in thermal management systems. Stuttgart's automotive cluster anchors OEM-integrated platform development, while Munich hosts utility-scale aggregation software engineering centers.
United States
FERC Order 2222 enables distributed EV batteries to participate in wholesale electricity markets, creating revenue streams for fleet operators in Texas and California. The Federal Energy Regulatory Commission's mandate reshapes metering and cybersecurity requirements for bidirectional power flows. California's heavy-duty truck depots pilot 150 kW DC installations, while Texas ERCOT markets capture ancillary service revenue from aggregated school bus fleets.
Netherlands
Utility deregulation enables third-party energy retail and direct contracting between service providers and commercial fleet operators. CE marking frameworks under the EU Green Deal accelerate interoperable infrastructure deployment across Dutch distribution networks. Eindhoven's high-tech systems cluster hosts bidirectional converter engineering and thermal management redesigns for CO2 refrigerant compliance.
Japan
Nissan's CHAdeMO bidirectional standard dominates passenger vehicle compatibility through long-standing Leaf platform integration. METI guidelines shape vehicle-grid handshaking protocols and aggregation software certification requirements. Tokyo's metropolitan grid hosts pilot programs for residential prosumers with rooftop solar and time-of-use arbitrage optimization.
United Kingdom
Ofgem's regulatory sandbox programs test virtual power plant orchestration and frequency response contracting mechanisms for aggregated EV fleets. The country's net-zero commitments accelerate smart meter deployment with revenue-grade bidirectional flow authentication. London's fintech and energy trading clusters develop predictive analytics for wholesale market participation by distributed storage assets.
Vehicle-To-Grid (V2G) Market Competitive Landscape
On the supply side, the industry is consolidating around utility-scale aggregation platforms that bundle energy management software with bidirectional charging hardware. Tiered competitive positioning separates integrated virtual power plant orchestrators from standalone equipment vendors and specialized software developers. Dominant competitive moves include strategic partnerships between automotive OEMs and energy service providers, plus backward integration by hardware suppliers into captive energy management system development.
Within the integrated platform tier, Enel X and Nuvve Corporation exemplify utility-scale virtual power plant orchestrators that aggregate distributed EV batteries into wholesale market participation. Nissan Motor Corporation anchors the passenger vehicle segment through its proprietary CHAdeMO standard, representing the OEM-integrated archetype that reduces third-party aggregation friction. These three companies occupy positions spanning the value chain from vehicle hardware through grid services, illustrating how competitive positioning increasingly depends on software-defined optimization capabilities rather than power electronics differentiation alone.
| Leading Market Players |
|---|
| Nissan Motor Corporation |
| Enel X |
| Nuvve Corporation |
| Groupe Renault |
| Mitsubishi Motors Corporation |
| ABB |
| ChargePoint |
| Wallbox |
| Siemens |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp freight corridor's container rates directly compress margins for silicon carbide power electronics shipped from European foundries, concentrating pricing power among German and Dutch hardware vendors while forcing tiered equipment offerings across residential and commercial installation classes.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with fleet operators securing 30-40% unit cost reductions on 150 kW DC installations above 50-unit orders. Price differentiation hinges on CE marking certification grade and after-sales service bundling, where field maintenance contracts capture recurring revenue streams. Pricing pressure stems from utility-scale aggregation platforms bundling energy management software with hardware, eroding standalone equipment margins. Residential users exhibit highest price sensitivity due to compressed project returns at small scale, while utility companies prioritize technical specification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing for bidirectional converters concentrates at Foxconn and Jabil facilities in Mexico and Poland, with final assembly gravitating toward Eindhoven and Stuttgart industrial clusters. Silicon carbide wafers draw from Japanese and US substrate suppliers, while thermal management components rest on German refrigerant system specialists. Single-source vulnerability in ISO 15118 communication chipsets creates procurement risk. Distribution runs through energy service providers disintermediating traditional automotive retail networks, with direct-to-fleet contracting accelerating in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The V2G market is approaching a platform-economics inflection as ISO 15118-20 standardization dissolves vehicle-grid interoperability barriers, enabling software-defined aggregation to capture margin pools previously anchored in proprietary hardware.
For Market Incumbents: Harden defensive positions through backward integration into captive energy management system development and exclusive fleet operator contracting in California and Texas markets. The threat of utility-scale platforms bundling software with third-party hardware demands channel control investments. Prioritize CE marking and NERC CIP certification to maintain grid interconnection access as cybersecurity requirements tighten. For New Entrants and Emerging Players: Pursue white-space opportunities in school bus fleet electrification across North American districts, where predictable parking patterns and Nuvve Corporation's established aggregation protocols reduce market entry friction. The residential solar-plus-storage segment offers penetrable entry points as equipment costs decline. Lead with turnkey V2G program offerings that bypass dealer service channels entirely. For Investors and Strategic Acquirers: FERC Order 2222 implementation reshapes the acquisition landscape by validating revenue-grade metering and wholesale market participation as investable capabilities. Long-term viability centers on software-defined optimization platforms with demonstrated virtual power plant orchestration. The signal to watch is national implementations of EU cybersecurity frameworks defining product market access thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | ISO 15118-20 adoption enables cross-OEM interoperability, reducing integration friction for aggregation software vendors. |
| Battery Supply Agreement | Long-term cell offtake contracts with Korean and Chinese manufacturers secure capacity for 150 kW DC bidirectional systems. |
| Software-Defined Vehicle Investment | OEM-integrated energy management platforms capture recurring revenue from grid services rather than one-time hardware sales. |
| Geographic Manufacturing Footprint | Mexico and Poland assembly locations optimize duty exposure and logistics costs for North American and European demand. |
| Charging Infrastructure Partnership | Utility-scale virtual power plant alliances with Enel X and comparable platforms secure wholesale market participation channels. |
Research Methodology
Operator-level perspectives from utility planning officers, fleet procurement managers, OEM platform engineers, and aggregation software developers anchored the qualitative base. Primary interviews combined with secondary validation against FERC filings, EIA project databases, EU Green Deal implementation documents, and IEA technology roadmaps. Bottom-up equipment shipment analysis triangulated against top-down grid interconnection forecasts.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation modeling spanning technology tier, end-user category, application type, and installation class. CAGRs derived from unit economics analysis of fleet operator revenue per vehicle and hardware cost trajectories. Forecast inputs incorporated silicon carbide semiconductor pricing dynamics and refrigerant transition timelines under EU F-Gas Regulation.
Sensitivities concentrate around national cybersecurity certification timelines, battery degradation warranty exclusions, and wholesale market participation rules under FERC Order 2222 state implementations. Forecasts reflect documented assumptions subject to revision from regulatory fragmentation or technology substitution. Quarterly review of grid interconnection queue data and CE marking approval cadences is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Electric Two Wheelers MRO Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
Europe Electric Car Market